
 Transplantation Market | 2026-2036
Transplantation Market Size, Share, and Industry Trends Forecast 2026-2036
Transplantation Market Analysis
Transplant center demand is hardening as living-donor kidney programs expand across integrated health networks. Novartis AG leverages its immunosuppressive therapy portfolio to anchor positions in maintenance regimens post-transplant. Astellas Pharma competes through specialized calcineurin inhibitor formulations that dominate maintenance protocols. TransMedics differentiates via portable organ perfusion technology that extends viable preservation windows for heart and lung grafts.
Transplantation encompasses the surgical transfer of viable organs, tissues, or cells from donor to recipient, requiring histocompatibility matching through HLA tissue typing and sustained immunosuppression to prevent graft rejection. The procedure demands cold ischemia time under six hours for optimal cardiac graft function, with machine perfusion systems now extending viability thresholds. Kidney transplants from deceased donors represent the mature volume base, while bioprinting applications for organ scaffolds command the fastest-growing R&D investment pool. Immunosuppressive therapy segments concentrate margin pools where branded tacrolimus and belatacept formulations sustain pricing power against generic erosion.
FDA, EMA, and WHO enforce stringent graft tracking and immunosuppressive efficacy standards that shape product approval pathways and post-market surveillance obligations. The EU Green Deal and MDR frameworks are tightening requirements for single-use perfusion circuit disposal and biologic material traceability across European transplant networks. Stakeholders must monitor evolving reimbursement thresholds for machine perfusion against static cold storage benchmarks as health technology assessment bodies recalibrate value definitions.
Market Dynamics
Machine perfusion systems are displacing static cold storage as the dominant preservation modality, forcing transplant centers to reconfigure procurement workflows and capital allocation around portable organ care platforms.
Growth Catalysts
- EU MDR traceability mandates:The EU Medical Device Regulation imposes biologic material tracking requirements that accelerate investment in digital chain-of-custody systems across European transplant networks.
- Living-donor program expansion:Integrated health systems in the United States are scaling paired-exchange networks and non-directed donation protocols, tightening organ availability timelines.
- Normothermic perfusion technology:Portable heart and lung preservation devices extend viable ischemia windows from four hours toward twelve hours, expanding donor pool eligibility criteria.
Market Restraints
- Immunosuppressive generic erosion:Patent expirations on tacrolimus formulations compress branded maintenance therapy margins, constraining R&D reinvestment capacity.
- Single-use perfusion circuit costs:Disposable cartridge economics for machine perfusion systems impose per-procedure cost premiums that strain procurement budgets at mid-tier transplant centers.
- HLA matching complexity:Sensitized recipient pools with elevated panel-reactive antibody levels face prolonged wait times, capping effective demand conversion.
Strategic Opportunities
- Xenotransplantation clinical pathways:FDA breakthrough therapy designations for genetically modified porcine organ trials open alternative graft sourcing channels for heart and kidney failure populations.
- Bioprinted scaffold R&D:Convergence of 3D bioprinting with decellularized matrix technologies creates development pipelines for vascularized organ constructs targeting liver and kidney applications.
- Telemedicine-enabled donor coordination:Remote assessment protocols for expanded-criteria donors reduce geographic disparities in organ utilization rates across rural procurement zones.
Industry Challenges
- Transplant surgeon workforce constraints:Fellowship training pipeline limitations and geographic maldistribution create bottlenecks at high-volume centers.
- Cross-border organ transport logistics:Regulatory fragmentation between national procurement organizations complicates international sharing agreements for rare blood type matches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transplantation Market |
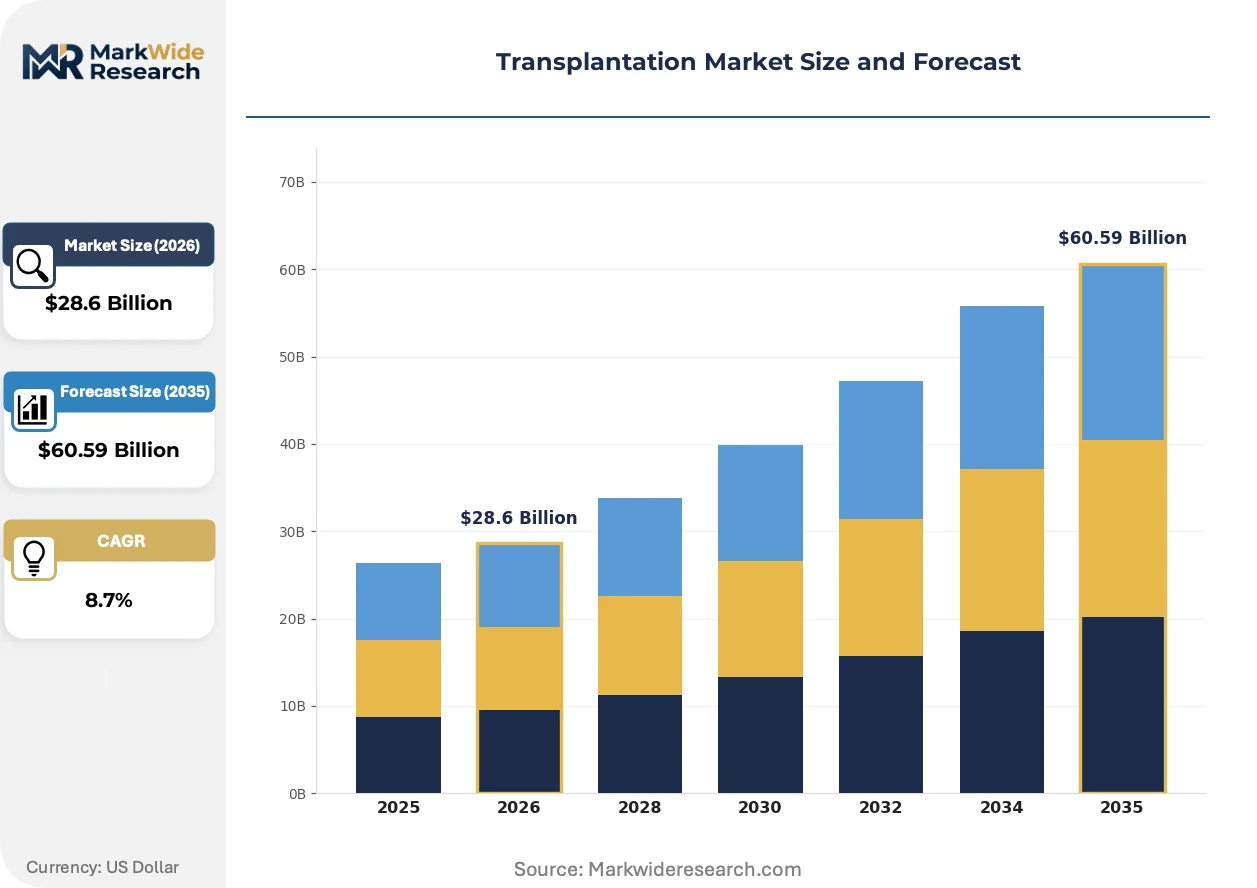
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Organ Type: Kidney, Liver, Heart, Lung Donor Type: Living Donors, Deceased Donors, Altruistic Donors, Directed Donors Technology: Immunosuppressive Therapy, Tissue Typing, Organ Preservation, Bioprinting End User: Hospitals, Transplant Centers, Research Institutions, Surgical Clinics |
| Companies Covered | Zimmer Biomet, Medtronic, Stryker Corporation, Arthrex, AbbVie, Novartis AG, Astellas Pharma, TransMedics, BioLife Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transplantation Market Emerging Trajectories
Three intersecting developments are restructuring competitive positioning: portable perfusion hardware, tightened biologic traceability mandates, and shifting procurement authority toward integrated delivery networks.
Normothermic regional perfusion is decentralizing organ viability assessment from centralized transplant hubs toward procurement site locations. Organ procurement organizations in Germany and Japan are deploying transportable ex-vivo platforms to donor hospitals, enabling functional evaluation before graft acceptance. This capability is compressing cold ischemia exposure and expanding the addressable donor pool for marginal organs.
REACH and EU Green Deal frameworks are mandating sustainable disposal pathways for single-use perfusion circuits and immunosuppressive packaging waste. Manufacturers must redesign material compositions to satisfy extended producer responsibility obligations. The compliance burden falls heaviest on mid-scale perfusion device suppliers lacking captive recycling infrastructure.
Hospital procurement committees are consolidating vendor relationships for immunosuppressive portfolios under value-based contracting frameworks. Integrated health networks in the United States are bundling induction and maintenance therapies under multi-year agreements with outcome guarantees. This concentration is most visible at academic medical centers with captive pharmacy operations and internal specialty pharmacy capabilities.
Transplantation Market Segmentation
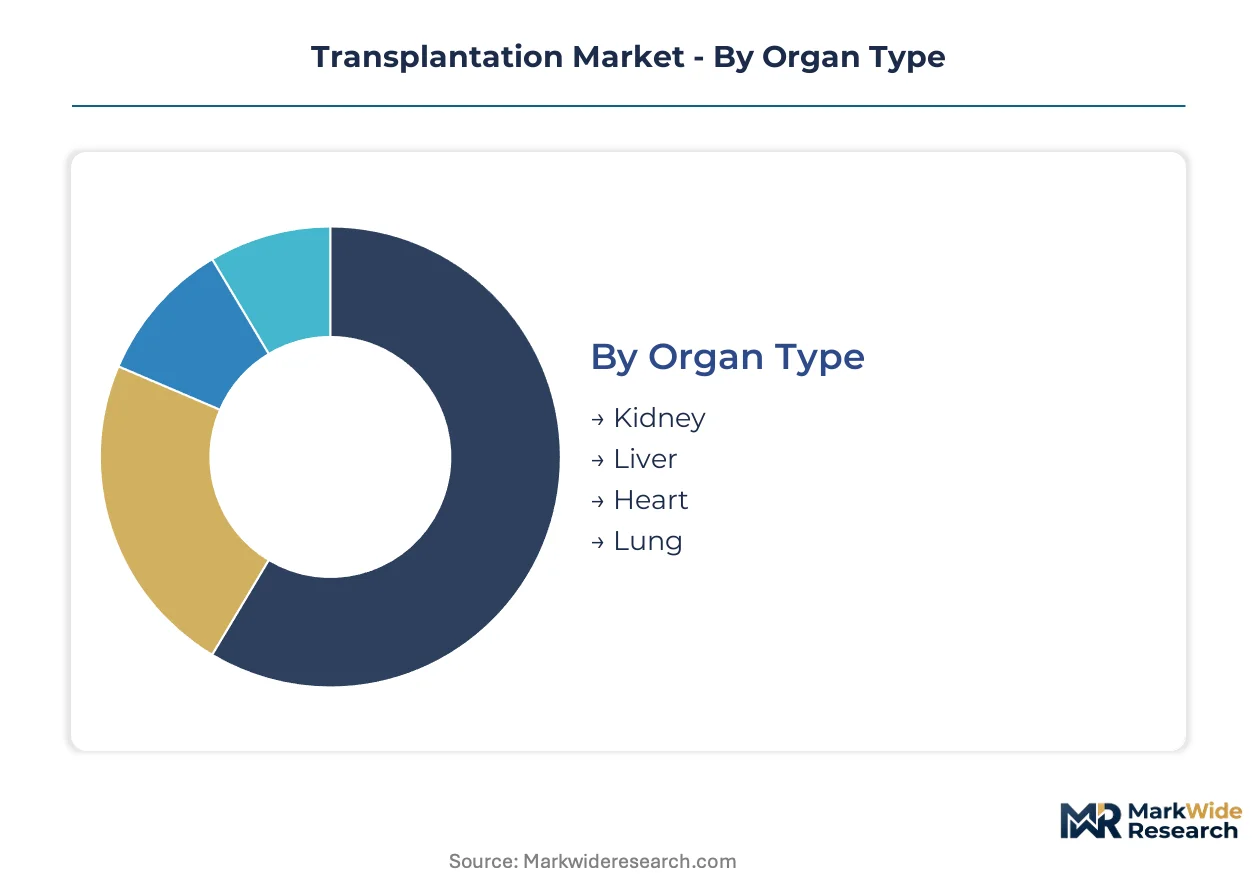
Transplantation market segmentation reveals distinct procurement patterns across organ types and preservation technologies. Each category carries specific regulatory, reimbursement, and logistics requirements that shape vendor selection and capital deployment strategies.
Organ Type:
Kidney and liver grafts operate as embedded components within integrated transplant networks, while heart and lung procedures demand standalone specialized infrastructure.
- Kidney:Deceased-donor nephrectomy constitutes the procedural volume base, with paired-exchange networks in the United States and Germany tightening living-donor availability timelines. Hospital end-users dominate procurement as transplant centers embed kidney programs within broader nephrology service lines.
- Liver:Split-liver techniques and living-donor hepatectomy expand graft supply against chronic shortage conditions. Japanese transplant centers concentrate demand for living-donor protocols given cultural preferences and deceased-donor scarcity.
- Heart:Mechanical circulatory support bridges constrain standalone program economics.
- Lung:Ex-vivo lung perfusion extends marginal donor acceptance criteria.
Volume placements concentrate in kidney transplantation; the faster expansion belongs to lung graft protocols enabled by portable perfusion advances.
Donor Type:
Cost-tier stratification separates high-complexity altruistic chains from standardized deceased-donor workflows.
- Living Donors:Laparoscopic nephrectomy and hepatectomy techniques reduce recovery timelines, expanding paired-exchange feasibility. United States integrated health networks scale non-directed donation programs, compressing waitlist intervals for sensitized recipients.
- Deceased Donors:Brain-dead and circulatory-death procurement protocols generate the foundational graft supply. German organ procurement organizations achieve highest conversion efficiency through standardized donor management algorithms.
- Altruistic Donors:Non-directed chains create complex logistics overhead.
- Directed Donors:Emotional pressure dynamics complicate informed consent.
Deceased donors anchor procurement volume; altruistic chains are expanding most quickly through paired-exchange network scaling.
Technology:
Application maturity separates established immunosuppressive maintenance from emerging bioprinting R&D pipelines.
- Immunosuppressive Therapy:Calcineurin inhibitors and antiproliferative agents constitute the revenue base, with tacrolimus formulations facing generic erosion. FDA tightening of efficacy benchmarks shapes maintenance protocol selection at United States transplant centers.
- Organ Preservation:Normothermic machine perfusion displaces static cold storage as the dominant modality for heart and lung grafts. TransMedics portable platforms extend viable ischemia windows, expanding donor pool eligibility criteria.
- Tissue Typing:Next-generation sequencing reduces HLA ambiguity.
- Bioprinting:Vascularized scaffold development commands fastest-growing R&D investment.
Immunosuppressive therapy captures current margin concentration; bioprinting applications show the steepest expansion trajectory.
End User:
Customer-type differentiation separates high-volume academic centers from distributed surgical clinic capacity.
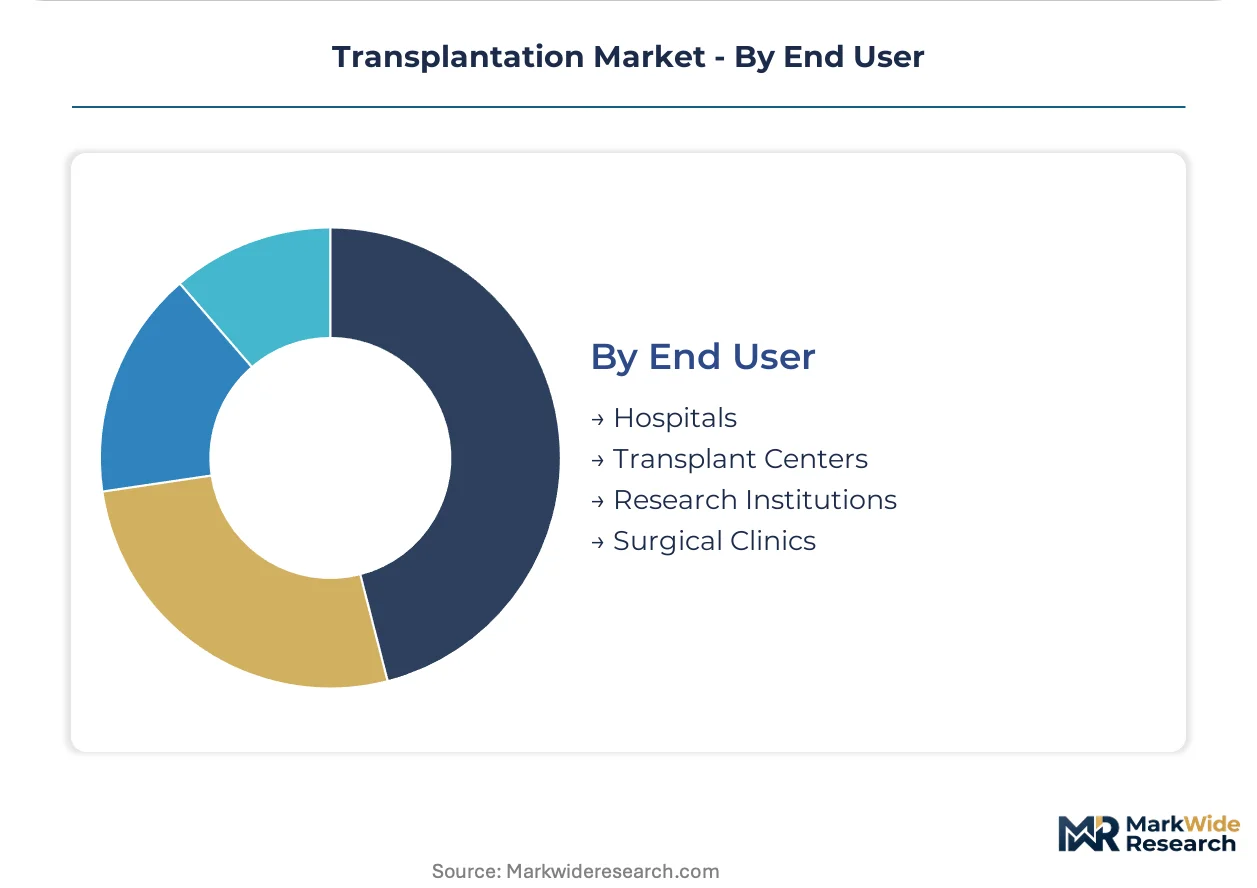
- Hospitals:General acute-care facilities with embedded transplant units handle living-donor nephrectomy and standard deceased-donor procedures. German hospital networks achieve scale through regional concentration of procurement expertise.
- Transplant Centers:Specialized facilities manage complex multi-organ and re-transplant cases. United States academic medical centers consolidate immunosuppressive purchasing under value-based contracting with outcome guarantees.
- Research Institutions:Xenotransplantation trials and bioprinting development.
- Surgical Clinics:Limited to pre-transplant evaluation and post-operative monitoring.
Hospital placements dominate graft volume; transplant centers are gaining share fastest through complex case consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organ procurement networks concentrate supply expertise in the United States, Germany, and Japan, while consumption demand spreads across transplant centers in secondary markets. Production of immunosuppressive therapies and perfusion hardware clusters in Switzerland, the United States, and Japan. Distribution networks face friction from national procurement sovereignty rules that fragment cross-border organ sharing.
United States
Integrated health networks in the United States are scaling paired-exchange programs and non-directed donation chains, compressing waitlist intervals for sensitized recipients. FDA immunosuppressive efficacy benchmarks are tightening maintenance protocol requirements at academic medical centers. Transplant volume concentrates in the Midwest and Southeast, where procurement organizations achieve highest conversion efficiency through standardized donor management algorithms.
Germany
German organ procurement organizations achieve benchmark conversion rates through centralized donor management protocols and regional concentration of transplant expertise. EU MDR traceability mandates are accelerating digital chain-of-custody investments across hospital networks. The Rhine-Ruhr and Bavarian clusters host the densest transplant center networks, with normothermic perfusion deployment expanding from centralized hubs toward procurement site locations.
Japan
Japanese transplant centers concentrate demand for living-donor hepatectomy and kidney protocols given cultural preferences and deceased-donor scarcity. PMDA regulatory pathways for xenotransplantation trials are opening alternative graft sourcing channels. The Kanto region around Tokyo anchors procurement coordination, while Kansai-based centers pioneer split-liver techniques and paired-exchange network integration.
Switzerland
Swiss pharmaceutical manufacturers anchor immunosuppressive therapy supply chains for European and Asian transplant markets. Swissmedic oversight of biologic material traceability aligns with EU MDR frameworks, creating compliance continuity across contiguous markets. The Basel-Zurich corridor concentrates formulation and packaging operations, with specialized cold-chain logistics extending distribution reach into Eastern European procurement networks.
United Kingdom
NHS Blood and Transplant is consolidating procurement authority under integrated commissioning frameworks, shifting vendor selection toward outcome-based contracting. The UK regulator enforces graft tracking standards that exceed baseline EU requirements. London and Manchester transplant centers are piloting telemedicine-enabled donor coordination protocols to reduce geographic disparities in organ utilization across rural procurement zones.
Transplantation Market Vendor Landscape
Top-tier vendors anchor immunosuppressive maintenance therapy, while specialized perfusion device manufacturers occupy the emerging technology tier. The market structure separates consolidated pharmaceutical portfolios from fragmented hardware innovators. Strategic archetypes include diversified pharma conglomerates with transplant-focused divisions, pure-play organ preservation technology developers, and diversified medical device manufacturers with orthopedic-to-transplant extension strategies. Dominant competitive moves include portfolio diversification into adjacent cell therapy applications and technology licensing partnerships between perfusion hardware developers and procurement organizations.
Within the pharmaceutical tier, Novartis AG and Astellas Pharma represent calcineurin inhibitor maintenance therapy anchors, their positions shaped by branded formulation durability against generic erosion. TransMedics exemplifies the portable perfusion technology archetype, its market presence tied to normothermic preservation hardware that extends viable ischemia windows for heart and lung grafts. Zimmer Biomet and Stryker Corporation occupy diversified device manufacturer positions, their transplant market participation representing extension from established orthopedic and surgical portfolios rather than core strategic focus.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Medtronic |
| Stryker Corporation |
| Arthrex |
| AbbVie |
| Novartis AG |
| Astellas Pharma |
| TransMedics |
| BioLife Solutions |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap immunosuppressive manufacturers in Switzerland and Japan anchor supply discipline through multi-generational ownership horizons, enabling pricing stability against volatile raw material costs while resisting quarterly margin pressure that forces asset sales among private-equity-rolled competitors.
Pricing Analysis
Margin tightening in branded maintenance therapy reflects patent cliff dynamics for tacrolimus formulations as FDA efficacy benchmarks harden protocol selection. Three-tier pricing structure across premium, standard, and economy levels separates novel biologic induction agents from generic calcineurin inhibitors and volume-contracted maintenance bundles. Cost-down pressure on perfusion disposables accelerates because single-use cartridge economics strain mid-tier transplant center procurement budgets. Academic medical centers with captive specialty pharmacy operations exhibit lowest price sensitivity; distributed surgical clinics face acute budget constraints.
Supply Chain Analysis
CE marking and FDA 510(k) clearance gates concentrate perfusion hardware supply among Swiss, United States, and Japanese device manufacturers with validated quality management systems. Active pharmaceutical ingredient production for immunosuppressants draws from Indian, Chinese, and Italian chemical synthesis clusters. Single-source vulnerability permeates porcine-derived biological material sourcing for xenotransplantation scaffold development. Distribution runs through hospital procurement committees consolidating vendor relationships under value-based contracting frameworks with outcome guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU MDR traceability mandates and REACH disposal obligations force mid-scale perfusion suppliers toward distressed exits, concentrating procurement authority among integrated health networks with compliance infrastructure.
For Market Incumbents: Lock in transplant center loyalty through multi-year immunosuppressive portfolio agreements bundling induction and maintenance therapies with outcome guarantees. Secure backward integration into porcine breeding facilities for xenotransplantation biological material supply. FDA breakthrough therapy designation pathways for genetically modified organ trials represent the critical regulatory lever to defend against emerging bioprinting substitute technologies.
For New Entrants and Emerging Players: Launch via telemedicine-enabled donor coordination platforms targeting rural procurement zones with geographic utilization disparities. White-space concentration exists in portable normothermic perfusion devices for kidney grafts, where TransMedics has not yet extended its heart-lung dominance. Partner with German organ procurement organizations for transportable ex-vivo platform pilot deployments.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap immunosuppressive manufacturers with intact formulation patents but eroding branded margins in United States and European markets. Long-term viability hinges on xenotransplantation clinical trial progression and bioprinting scaffold vascularization milestones. Watch FDA breakthrough therapy designation velocity for genetically modified porcine organs as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Academic medical centers in the United States consolidate immunosuppressive purchasing under outcome-based contracting with multi-year guarantees. |
| FDA Submission | Breakthrough therapy designation pathways for genetically modified porcine heart and kidney trials accelerate alternative graft sourcing channels. |
| Manufacturing Scale-Up | Swiss and Japanese API producers expand calcineurin inhibitor formulation capacity to offset Indian generic erosion pressure. |
| Reimbursement Strategy | Health technology assessment bodies in Germany and the United Kingdom recalibrate value definitions for machine perfusion against cold storage benchmarks. |
| Strategic Partnership | Organ procurement organizations in Germany deploy transportable ex-vivo platforms to donor hospitals, compressing cold ischemia exposure. |
Methodological Framework
Multi-period observation of transplant center procurement patterns, immunosuppressive protocol adoption curves, and perfusion device deployment timelines anchored the trend analysis, supplemented by interviews with transplant surgeons, hospital pharmacy directors, organ procurement organization executives, and regulatory affairs specialists at FDA and EMA. Secondary validation drew from FDA 510(k) filings, EMA marketing authorization applications, ClinicalTrials.gov xenotransplantation trial registries, and hospital procurement database extracts. Bottom-up graft volume modeling triangulated against top-down pharmaceutical revenue estimates.
Input-output matrices mapped donor type flows through preservation technology tiers to end-user segments across the projection horizon. Segmentation dimensions included organ type, donor category, preservation modality, immunosuppressive agent class, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for machine perfusion adoption and patent cliff erosion schedules for branded maintenance therapies. Forecast inputs incorporated paired-exchange network scaling rates and EU MDR compliance cost trajectories.
Regulatory pathway delays, xenotransplantation clinical trial setbacks, and immunosuppressive generic entry acceleration are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Menopause Treatment Market
Medical Treatment
Gallbladder Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Endovenous Laser Therapy Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Leprosy Treatment Market