
 Bromhidrosis Disease Treatment Market | 2026-2036
Bromhidrosis Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bromhidrosis Disease Treatment Market Analysis
A shortage of board-certified dermatological surgeons is redrawing competitive dynamics in specialized odor treatment centers. AbbVie Inc. leverages its immunology R&D infrastructure to sustain pipeline depth in skin-condition therapeutics. Pfizer Inc. anchors its position through manufacturing scale and established hospital formulary relationships. Galderma SA specializes in dermatology-focused portfolios that differentiate its brand from generalist pharmaceutical competitors.
Bromhidrosis disease treatment encompasses medical interventions targeting chronic body odor arising from bacterial decomposition of apocrine sweat secretions, typically involving topical antimicrobials with chlorhexidine or triclosan bases, aluminum-based antiperspirants, and procedural options such as botulinum toxin injections or sweat gland excision. The primary commercial purpose centers on restoring patient quality of life and social function through odor suppression and microbial load management. Topical antimicrobials command the largest revenue share within treatment type segments due to their non-invasive profile and repeat-purchase economics, while surgical procedures capture concentrated margin pools despite smaller volumes. The adults patient age group dominates absolute demand, though adolescent segments show faster growth trajectories tied to earlier clinical intervention norms.
The FDA regulates topical antimicrobial formulations under monograph and new drug application pathways, while the EMA's MDR framework governs surgical device classifications for botulinum toxin delivery systems in European markets. Japan's PMDA maintains distinct efficacy standards for transdermal patch technologies that shape product development timelines for multinational sponsors. Stakeholders must monitor evolving antimicrobial resistance surveillance data and regional reimbursement shifts to align portfolio priorities with access dynamics.
Market Dynamics
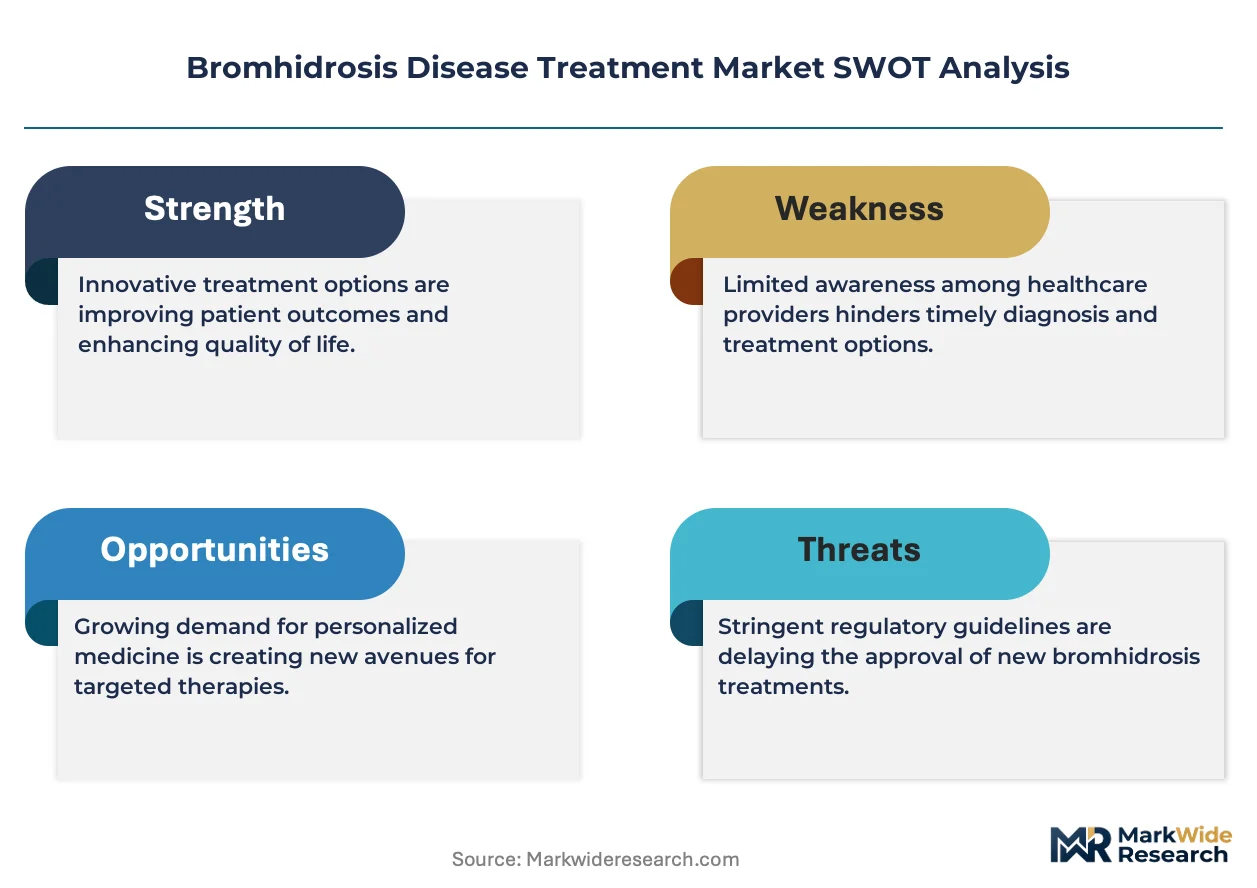
The FDA's ongoing refinement of topical antimicrobial monograph guidelines is compressing formulation timelines while forcing sponsors toward new drug application pathways, fundamentally restructuring how dermatology clinics source odor-suppression therapies.
Growth Catalysts
- Metropolitan corridor concentration:Demand clusters along the Boston-to-Washington healthcare axis, where dermatology clinics are expanding specialized odor-treatment service lines. This geographic density accelerates referral networks and procedure volume.
- REACH antimicrobial framework:The European Chemicals Agency's evolving biocide regulations are standardizing chlorhexidine and triclosan safety profiles, reducing cross-border formulation barriers for topical developers.
- Botulinum toxin delivery systems:Minimally invasive sweat gland modulation is displacing excision surgery in outpatient settings, broadening addressable patient populations beyond severe cases.
Market Restraints
- Board-certified surgeon scarcity:Specialized odor-treatment centers face constrained procedural capacity due to limited fellowship-trained dermatological surgeons, particularly in secondary metropolitan markets.
- Aluminum salt input volatility:Antiperspirant active ingredient supply chains concentrate in Chinese and Indian chemical manufacturers, exposing formulators to tariff and shipping cost fluctuations.
- Antimicrobial resistance surveillance:The CDC's expanding monitoring programs for bacterial tolerance to topical agents threaten long-term efficacy claims for legacy chlorhexidine formulations.
Strategic Opportunities
- Adolescent intervention protocols:Earlier clinical norms in Japan and South Korea for apocrine sweat management create template markets for age-segmented product development and pediatric dermatology partnerships.
- Transdermal patch platforms:Japan's PMDA maintains distinct efficacy standards for sustained-release technologies that multinational sponsors can leverage for differentiated positioning against conventional topicals.
- Telemedicine triage channels:Digital-first diagnosis and prescription routing for odor-related conditions open access pathways in rural and underserved sub-regions of the United States.
Industry Challenges
- MDR device reclassification:The EU's Medical Device Regulation is forcing botulinum toxin delivery system manufacturers through extended conformity assessment timelines, delaying market entry.
- Formulation-stability expertise:Shortages of pharmaceutical chemists specializing in antimicrobial-sweat interaction kinetics slow pipeline progression for next-generation topical candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bromhidrosis Disease Treatment Market |
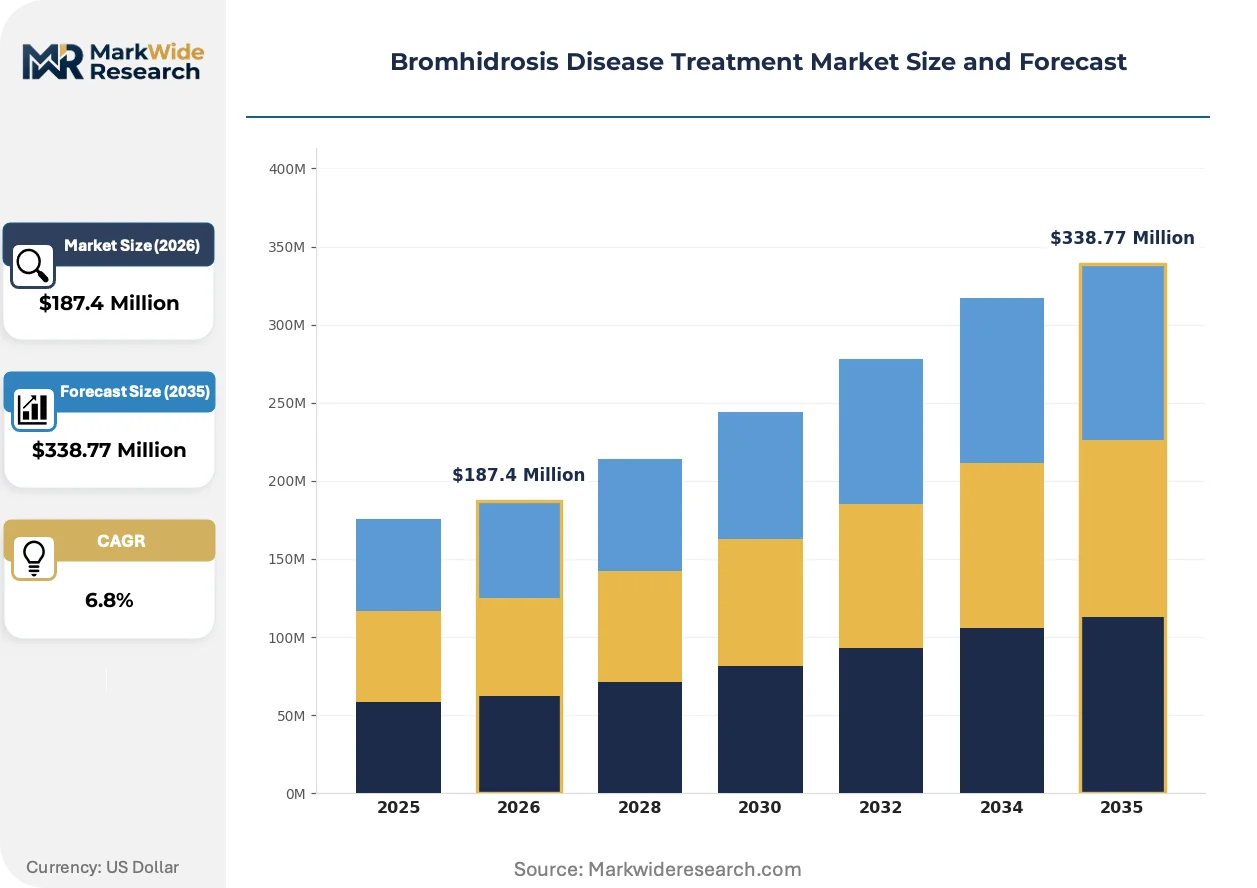
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Topical Antimicrobials, Antiperspirants, Oral Medications, Surgical Procedures Patient Age Group: Children, Adolescents, Adults, Seniors Delivery Method: Topical Application, Oral Administration, Injection, Transdermal Patches Therapy Approach: Conservative Management, Surgical Intervention, Pharmacotherapy, Lifestyle Modification |
| Companies Covered | AbbVie Inc., Pfizer Inc., Boehringer Ingelheim International GmbH, Galderma SA, Hikma Pharmaceuticals Plc, Ipsen Pharma, Johnson and Johnson Services Inc., JOURNEY MEDICAL CORP., Medytox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bromhidrosis Disease Treatment Market Emerging Trajectories
Microbiome-targeted interventions and sustained-release delivery mechanisms are displacing legacy antiperspirant architectures, while regulatory pressure on antimicrobial safety profiles accelerates investment in alternative active ingredients.
Microbiome-modulating topical formulations are fragmenting the traditional antimicrobial segment by targeting specific Corynebacterium strains rather than broad bacterial suppression. Prestige dermatology clinics in Germany and Switzerland are piloting these precision therapies for refractory bromhidrosis cases. The technology is fragmenting competitive positioning between general antiperspirant manufacturers and specialized pharmaceutical developers.
The FDA's 2023 antimicrobial monograph reclassification proposal is forcing reformulation of chlorhexidine-based products toward new drug application pathways. Sponsors face extended clinical trial requirements for efficacy endpoints previously accepted under over-the-counter standards. United States-based topical developers are responding by diversifying active ingredient portfolios toward aluminum zirconium complexes and botulinum toxin adjuncts.
Direct-to-consumer diagnostic testing for apocrine gland activity is compressing the traditional clinic-referral pathway for odor-related conditions. Subscription-based at-home sweat analysis kits, prevalent in metropolitan United States markets, are routing patients toward telemedicine consultations rather than in-person dermatology appointments. This channel shift is most visible in California and New York, where digital health infrastructure supports integrated prescription fulfillment.
Bromhidrosis Disease Treatment Market Segmentation
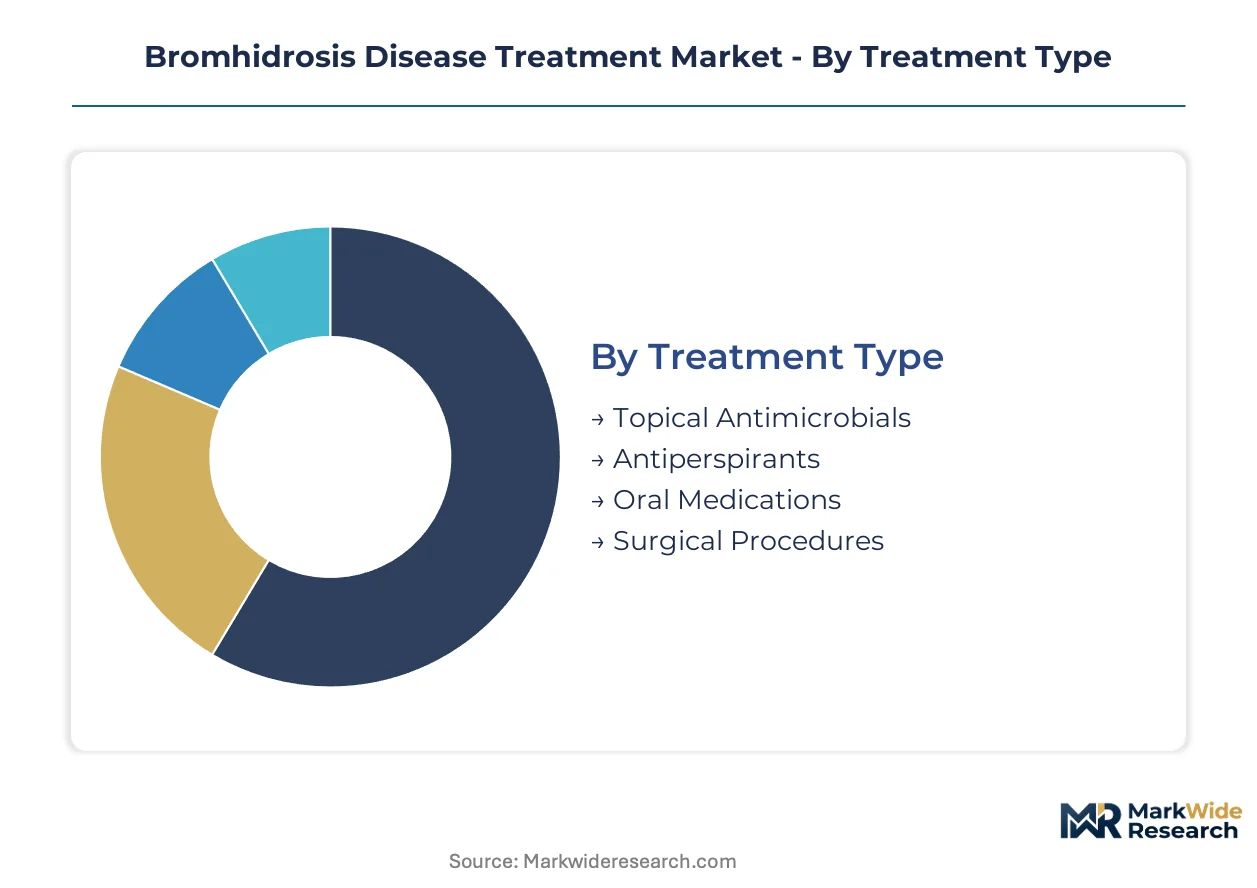
Treatment modalities for bromhidrosis fragment across invasive and non-invasive pathways, each carrying distinct reimbursement profiles and patient acquisition economics. Segmentation clarity enables sponsors to align formulation investments with procedure volume concentration and regulatory pathway requirements.
Treatment Type:
Margin pools concentrate in procedural interventions despite smaller volumes, while topical formulations generate recurring revenue through repeat-purchase dynamics.
- Topical Antimicrobials:Chlorhexidine and triclosan-based formulations dominate outpatient prescribing patterns. Demand clusters along the Boston-to-Washington corridor where dermatology clinics prioritize non-invasive first-line therapy. The FDA's monograph reclassification is compressing development timelines and forcing sponsors toward new drug application pathways.
- Antiperspirants:Aluminum salt complexes function through eccrine duct occlusion and apocrine secretion suppression. German and Swiss prestige clinics are expanding aluminum zirconium service lines for refractory cases. Aluminum salt input volatility from Chinese and Indian chemical manufacturers exposes formulators to tariff and shipping cost fluctuations.
- Oral Medications:Systemic agents targeting autonomic nervous system modulation remain niche due to side-effect profiles.
- Surgical Procedures:Sweat gland excision and botulinum toxin injections capture concentrated margin pools.
The dominant share belongs to topical antimicrobials, while surgical procedures are closing the gap fastest through outpatient volume expansion.
Patient Age Group:
Commercial focus tilts toward segments with established reimbursement pathways and higher procedure tolerance.
- Adults:The absolute demand anchor, driven by occupational and social function restoration priorities. Metropolitan United States corridors show dense procedure concentration. Board-certified dermatological surgeon scarcity constrains capacity expansion in secondary markets.
- Adolescents:Earlier clinical intervention norms in Japan and South Korea are creating template markets for age-segmented protocols. Pediatric dermatology partnerships in Seoul and Tokyo are piloting standardized apocrine management pathways.
- Children:Pre-pubertal cases remain rare, limiting dedicated product development.
- Seniors:Comorbidity profiles complicate surgical candidacy, channeling demand toward conservative modalities.
Adults command the dominant share, with adolescents expanding most quickly through earlier intervention norms.
Delivery Method:
Route selection determines regulatory pathway complexity and manufacturing investment requirements.
- Topical Application:Creams, gels, and solutions constitute the standard-of-care entry point. REACH framework standardization is reducing cross-border formulation barriers for European developers.
- Injection:Botulinum toxin delivery systems are displacing excision surgery in outpatient settings. The EU's MDR device reclassification is forcing extended conformity assessment timelines.
- Oral Administration:Systemic bioavailability challenges limit efficacy for localized apocrine targets.
- Transdermal Patches:Sustained-release platforms face distinct PMDA efficacy standards in Japan that shape multinational development timelines.
Topical application retains the dominant share, while injection modalities are gaining share fastest through minimally invasive positioning.
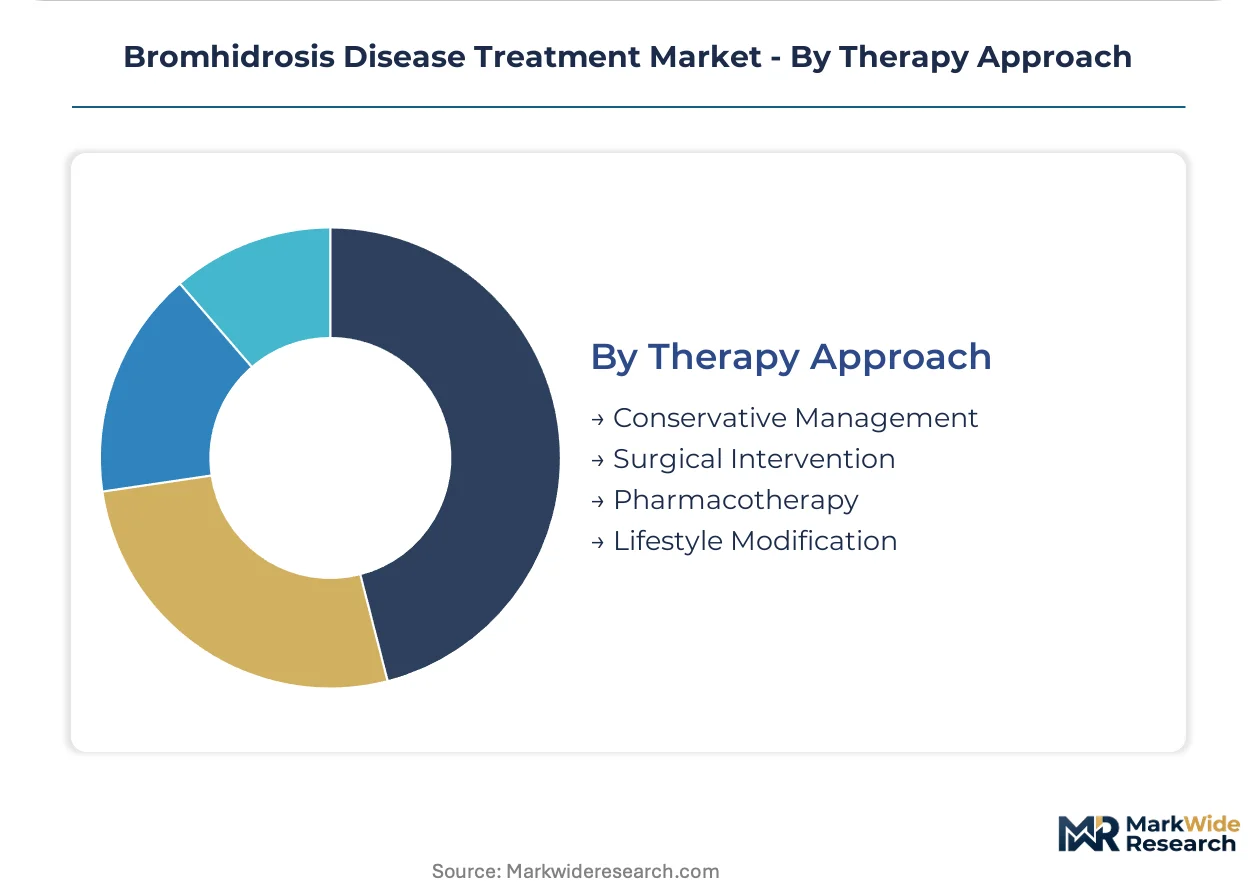
Therapy Approach:
Treatment sequencing follows severity-graded protocols with clear escalation triggers.
- Conservative Management:Topical antimicrobials combined with hygiene protocols form the first-line standard. Telemedicine triage channels in California and New York are routing patients toward digital-first diagnosis.
- Pharmacotherapy:Adjunctive systemic agents support refractory cases where topicals prove insufficient.
- Surgical Intervention:Excision and botulinum toxin modulation address severe, lifestyle-impairing presentations.
- Lifestyle Modification:Dietary and behavioral adjuncts support pharmaceutical efficacy but rarely suffice as monotherapy.
Conservative management holds the dominant share, with pharmacotherapy climbing the fastest through combination protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss prestige dermatology corridors, while volume-driven expansion accelerates across Japanese and South Korean metropolitan clusters. Metropolitan healthcare corridors in the United States capture premium procedure economics, creating asymmetric margin distribution across developed markets.
United States
Demand clusters along the Boston-to-Washington healthcare axis, where dermatology clinics expand specialized odor-treatment service lines. The FDA's refinement of topical antimicrobial monograph guidelines is compressing formulation timelines for domestic sponsors. New York and California digital health infrastructure supports telemedicine triage channels routing patients toward integrated prescription fulfillment.
Germany
Prestige dermatology clinics in Munich and Zurich pilot microbiome-modulating precision therapies for refractory bromhidrosis cases. The EMA's MDR framework governs surgical device classifications for botulinum toxin delivery systems, extending conformity assessment timelines. The REACH antimicrobial framework standardizes chlorhexidine safety profiles, reducing cross-border formulation barriers for topical developers.
Japan
Earlier clinical intervention norms for apocrine sweat management create template markets for age-segmented product development. The PMDA maintains distinct efficacy standards for transdermal patch technologies that shape multinational development timelines. Pediatric dermatology partnerships in Tokyo pilot standardized apocrine management pathways for adolescent segments.
South Korea
Seoul metropolitan clinics drive faster growth trajectories in adolescent bromhidrosis intervention through established cosmetic dermatology infrastructure. The MFDS regulates minimally invasive sweat gland modulation procedures under medical device pathways. Busan-Ulsan corridor manufacturers supply aluminum salt active ingredients to regional antiperspirant formulators.
Switzerland
Swissmedic oversees specialized pharmaceutical portfolios targeting dermatology-focused therapeutic differentiation. Basel and Geneva clusters concentrate formulation-stability expertise for next-generation antimicrobial candidates. Prestige clinic networks leverage proximity to German border markets for cross-border patient referral economics.
Bromhidrosis Disease Treatment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with immunology R&D infrastructure separating premium pharmaceutical developers from commodity antiperspirant manufacturers. The vendor base fragments across specialized dermatology-focused portfolios and generalist pharmaceutical competitors with established hospital formulary relationships. Three archetypes dominate: multinational pharmaceutical conglomerates with manufacturing scale, dedicated dermatology specialists with precision therapy pipelines, and regional toxin delivery system manufacturers with minimally invasive positioning. Competitive moves concentrate on portfolio diversification toward microbiome-targeted formulations and strategic partnerships bridging telemedicine triage with prescription fulfillment infrastructure.
Among pharmaceutical conglomerates, AbbVie Inc. and Pfizer Inc. exemplify divergent strategic positioning within dermatology therapeutics. AbbVie leverages immunology R&D infrastructure to sustain pipeline depth in skin-condition therapeutics, occupying a technology-driven archetype. Pfizer anchors market presence through manufacturing scale and established hospital formulary relationships, representing cost-leadership consolidation. Galderma SA sits within the dedicated dermatology specialist tier, differentiating through focused portfolios rather than generalist pharmaceutical breadth.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Pfizer Inc. |
| Boehringer Ingelheim International GmbH |
| Galderma SA |
| Hikma Pharmaceuticals Plc |
| Ipsen Pharma |
| Johnson and Johnson Services Inc. |
| JOURNEY MEDICAL CORP. |
| Medytox |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day formulation stability testing cycles govern inventory positioning for topical antimicrobial developers, concentrating pricing power with manufacturers possessing captive aluminum salt supply and in-house chlorhexidine synthesis capability. This lead-time band compresses margin flexibility for sponsors dependent on spot-market active ingredient procurement.
Pricing Analysis
The customization-premium spread separates configured-to-order microbiome-modulating formulations from standard chlorhexidine-based topicals by a substantial margin tier. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by FDA monograph compliance tier and brand heritage in dermatology corridors. Pricing pressure stems from aluminum salt input volatility originating in Chinese and Indian chemical manufacturers, compressing margins for non-integrated formulators. Price-sensitive buyers cluster in secondary metropolitan United States markets, while German and Swiss prestige clinics exhibit lowest sensitivity due to outcome-based reimbursement structures.
Supply Chain Analysis
Strategic stockpile preferences dominate aluminum salt procurement given tariff exposure and shipping cost volatility, contrasting with just-in-time inventory approaches for finished topical formulations in domestic distribution. Active ingredient supply concentrates in China, India, and South Korea, with aluminum zirconium complexes and chlorhexidine base materials drawing from these hubs. Single-source vulnerability in aluminum salt feedstock creates structural risk for formulators lacking backward integration. Distribution runs through hospital formulary procurement committees and dermatology clinic direct purchasing channels, with telemedicine platforms emerging as alternative routing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine triage integration with prescription fulfillment platforms signals a platform-economics inflection in bromhidrosis treatment access, with interoperability between digital diagnostic tools and dermatology clinic scheduling systems restructuring patient acquisition economics.
For Market Incumbents: Consolidate formulation-stability expertise through targeted acquisition of specialized pharmaceutical chemists and backward integration into aluminum salt precursor manufacturing. The FDA's monograph reclassification threat demands defensive certification investment in new drug application pathways. Channel control through exclusive hospital formulary agreements anchors pricing power against emerging microbiome-modulating competitors. For New Entrants and Emerging Players: Adolescent intervention protocol gaps in United States pediatric dermatology represent the most penetrable white-space target, as incumbent portfolios remain adult-centric. Direct-to-consumer diagnostic testing infrastructure in California and New York offers a go-to-market angle bypassing traditional clinic-referral bottlenecks. Subscription-based at-home sweat analysis kits enable patient capture upstream of prescription decisions. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical conglomerates with under-optimized dermatology-focused therapeutic portfolios. Long-term viability centers on precision microbiome modulation capabilities and regulatory pathway expertise across FDA, EMA, and PMDA jurisdictions. The signal to watch is botulinum toxin delivery system MDR conformity assessment timeline compression in European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome-Targeted Formulation Development | Precision therapies for refractory cases fragment competitive positioning against legacy antimicrobials in German prestige clinics. |
| Transdermal Patch Platform Investment | PMDA efficacy standard compliance creates differentiated positioning against conventional topical applications in Japanese markets. |
| Telemedicine Triage Integration | Digital-first diagnosis routing opens access pathways in rural United States sub-regions beyond metropolitan corridor concentration. |
| Backward Integration into Aluminum Salt Supply | Captive active ingredient production insulates margins from Chinese and Indian chemical manufacturer tariff volatility. |
| Adolescent Protocol Partnership Development | Pediatric dermatology collaborations in Seoul and Tokyo template age-segmented product development for earlier intervention norms. |
Methodological Framework
Desk research of FDA monograph filings, EMA MDR device classifications, and PMDA transdermal patch guidance documents preceded structured interviews with dermatology clinic medical directors, pharmaceutical regulatory affairs leads, hospital formulary procurement managers, and topical formulation R&D chemists. Secondary validation drew from ClinicalTrials.gov protocol databases, SEC 10-K pharmaceutical segment disclosures, and REACH framework biocide registration records. Bottom-up patient volume estimates across metropolitan United States corridors triangulated with top-down market sizing from sponsor pipeline disclosures.
Variance-decomposition across treatment type, patient age group, delivery method, and therapy approach segmentation dimensions structured the analytical framework. CAGRs were derived from procedure volume trajectory modeling and repeat-purchase economics for topical formulations across the projection horizon. Forecast inputs incorporated antimicrobial resistance surveillance trends from CDC monitoring programs and evolving reimbursement pathway shifts in Japanese and South Korean healthcare systems.
Underlying assumptions cover sustained FDA monograph pathway stability, aluminum salt supply chain continuity, and telemedicine regulatory permissiveness, with deviation risk concentrated in EMA MDR device reclassification timeline extensions and REACH framework chlorhexidine restriction escalations. Revision becomes warranted when antimicrobial resistance surveillance data crosses efficacy claim impairment thresholds for legacy topical formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Hypothermia Management Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Endovenous Laser Therapy Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Tissue Repair Technologies Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Hypercalcemia Treatment Market