
 Penile Cancer Treatment Market | 2026-2036
Penile Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Penile Cancer Treatment Market Analysis
Precision-molecular stratification is bifurcating the penile cancer treatment landscape into biomarker-directed and conventional protocol arms. Pfizer Inc. leverages its kinase inhibitor portfolio to compete in targeted therapy segments with documented clinical activity. Bristol-Myers Squibb Company anchors its position through checkpoint inhibitor development programs in squamous cell carcinomas. Merck & Co., Inc. dominates PD-1 pathway investigations with sustained R&D commitment to rare tumor types.
Penile cancer treatment encompasses surgical resection, radiation delivery, systemic chemotherapy, immunomodulation, and multimodal combination protocols directed at squamous cell neoplasms of the male external genitalia, with 5-fluorouracil and cisplatin remaining foundational cytotoxic agents. The primary purpose is locoregional control, organ preservation, and metastatic disease management in a malignancy with fewer than 2,000 annual cases in most developed health systems. Surgery and immunotherapy represent the most dynamic segment pair, with Mohs micrographic surgery and sentinel lymph node biopsy gaining protocol share while PD-1/PD-L1 inhibitors capture the fastest expansion in advanced disease settings. Hospitals and cancer treatment centers concentrate the largest margin pools due to bundled reimbursement for complex genitourinary surgical oncology and infusion services.
FDA orphan drug designation and EMA's priority medicines scheme shape development economics by compressing trial timelines and extending market exclusivity for penile cancer therapeutics. NMPA and PMDA parallel track reviews for squamous cell carcinoma indications are opening access corridors in East Asian markets with rising disease awareness. Stakeholders must monitor biomarker validation progress and regulatory harmonization across FDA, EMA, and Japan's Sakigake designation to anticipate which therapy modalities will secure preferential coverage and prescribing dominance.
Market Dynamics
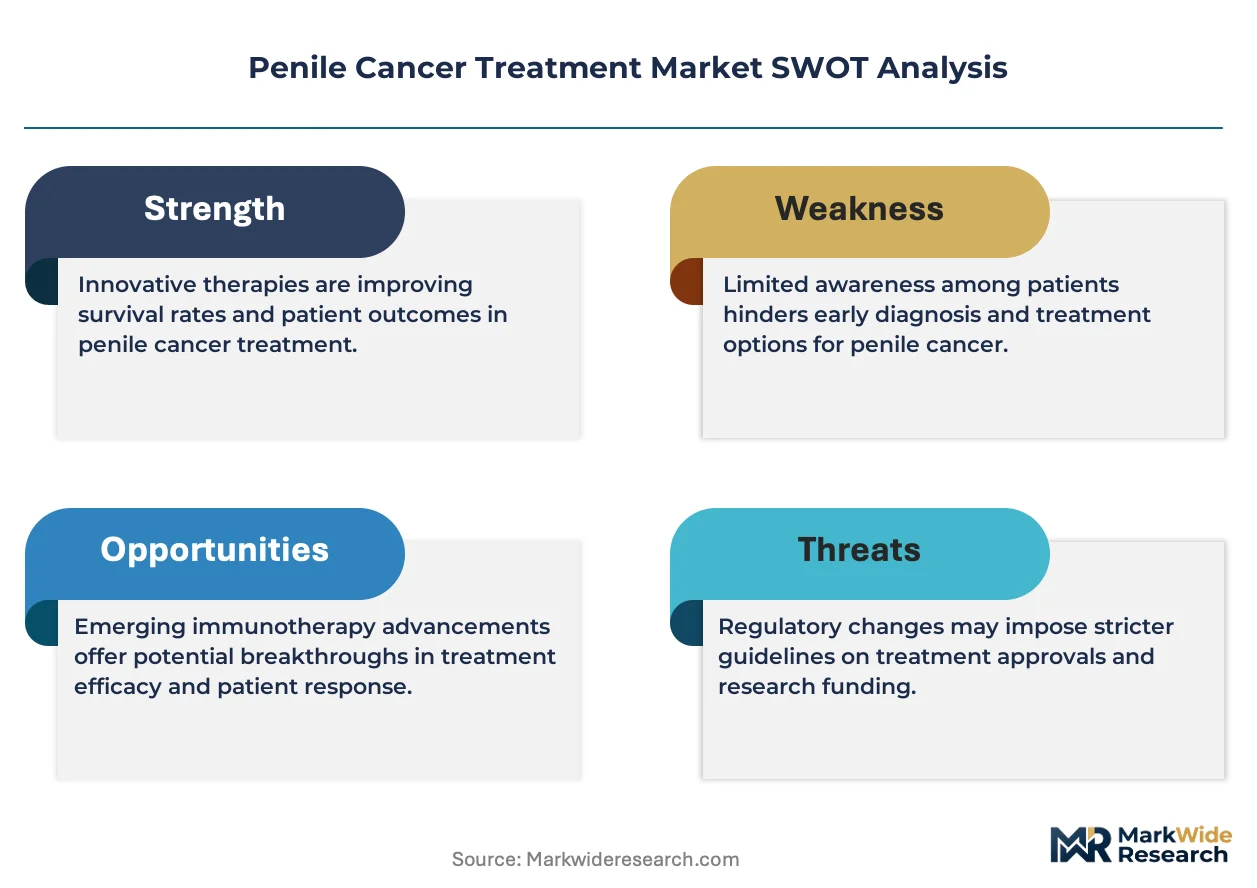
Precision-molecular stratification is compressing treatment protocols into biomarker-directed versus conventional arms, forcing reinvestment across oncology service lines. Referral networks for rare male malignancies are consolidating volume into specialized centers capable of supporting complex surgical oncology and infusion services.
Growth Catalysts
- FDA Orphan Drug Designation:Compressed trial timelines and extended market exclusivity accelerate therapeutic development economics for rare tumor indications.
- Squamous Cell Carcinoma Pipeline Expansion:PD-1/PD-L1 inhibitor investigations in advanced disease settings are capturing protocol share from cytotoxic foundations.
- Japan's Sakigake Priority Review:Parallel track mechanisms for novel oncology modalities compress regulatory lag in East Asian access corridors.
Market Restraints
- Biomarker Validation Bottlenecks:Incomplete molecular stratification infrastructure limits patient identification for targeted enrollment.
- Volume Concentration in Tertiary Centers:Disease rarity restricts procedure economics to high-throughput academic medical centers in the United States, Germany, and Japan.
- Cytotoxic Agent Supply Fragility:Cisplatin and 5-fluorouracil manufacturing concentration creates vulnerability in foundational chemotherapy access.
Strategic Opportunities
- EMA Priority Medicines Scheme:Accelerated assessment pathways for unmet medical needs compress time-to-reimbursement in European markets.
- Mohs Micrographic Surgery Protocol Expansion:Organ-preserving surgical techniques are displacing radical resection in early-stage presentations.
- Sentinel Lymph Node Biopsy Standardization:Minimally invasive staging protocols reduce morbidity burden and shorten recovery trajectories.
Industry Challenges
- Genitourinary Oncology Specialist Scarcity:Fellowship-trained surgical oncologists capable of complex penile-preserving procedures remain concentrated in major metropolitan clusters.
- Multimodal Protocol Coordination:Integration of surgical, radiation, and systemic therapy timelines requires specialized care coordination infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Penile Cancer Treatment Market |
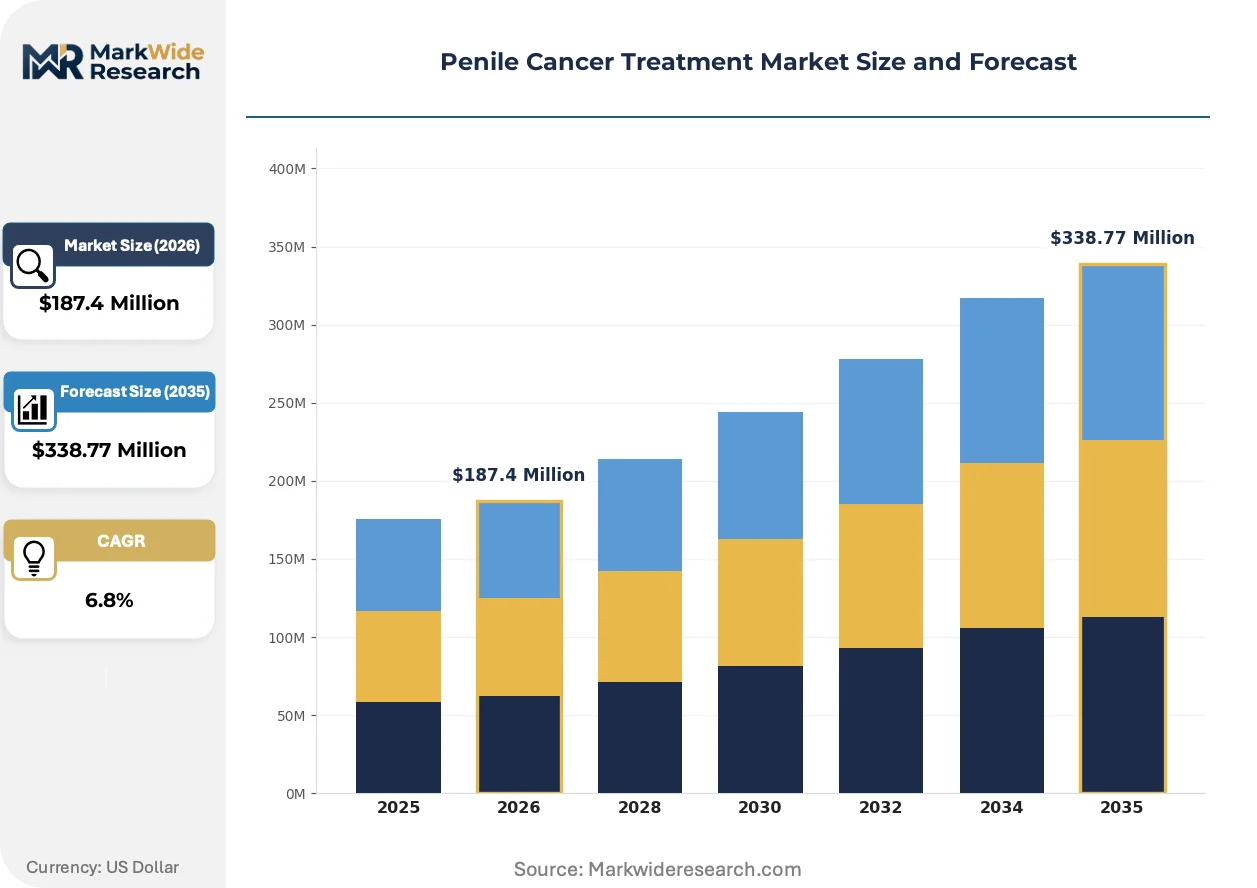
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Radiotherapy, Chemotherapy, Immunotherapy End User: Hospitals, Clinics, Cancer Treatment Centers, Home Care Therapy Area: Localized Disease, Advanced Disease, Recurrence, Palliative Care Delivery Mode: Intravenous, Oral, Topical, Combination Therapy |
| Companies Covered | Pfizer Inc., Novartis AG, Bristol-Myers Squibb Company, Merck & Co., Inc., F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc, AstraZeneca PLC, Eli Lilly and Company, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Penile Cancer Treatment Market Emerging Trajectories
Molecular diagnostic platforms are resequencing treatment decision trees before therapeutic selection occurs. Real-time tissue analysis and circulating biomarker detection are compressing the interval between diagnosis and protocol assignment.
Mohs micrographic surgery with intraoperative margin assessment is miniaturizing resection boundaries while preserving functional anatomy. Academic medical centers in the United States and Germany are adopting this technique for T1-T2 lesions previously managed with partial or total penectomy. The approach is compressing reconstructive burden and reducing psychosexual morbidity in curative-intent settings.
EMA's priority medicines scheme and FDA's orphan drug designation are creating parallel regulatory tracks that compress development timelines for rare oncology indications. These frameworks extend market exclusivity periods and reduce trial enrollment requirements. Squamous cell carcinoma programs targeting PD-1/PD-L1 pathways are capturing the majority of designations, redirecting portfolio investment away from cytotoxic combinations.
Patient navigation through specialized genitourinary oncology centers is consolidating referral patterns into high-volume institutions. Community urology practices are transferring complex cases to tertiary centers with embedded clinical trial infrastructure. This channel compression is most visible in the United States, where bundled reimbursement for surgical oncology and infusion services concentrates margin pools in integrated delivery networks.
Penile Cancer Treatment Market Segmentation
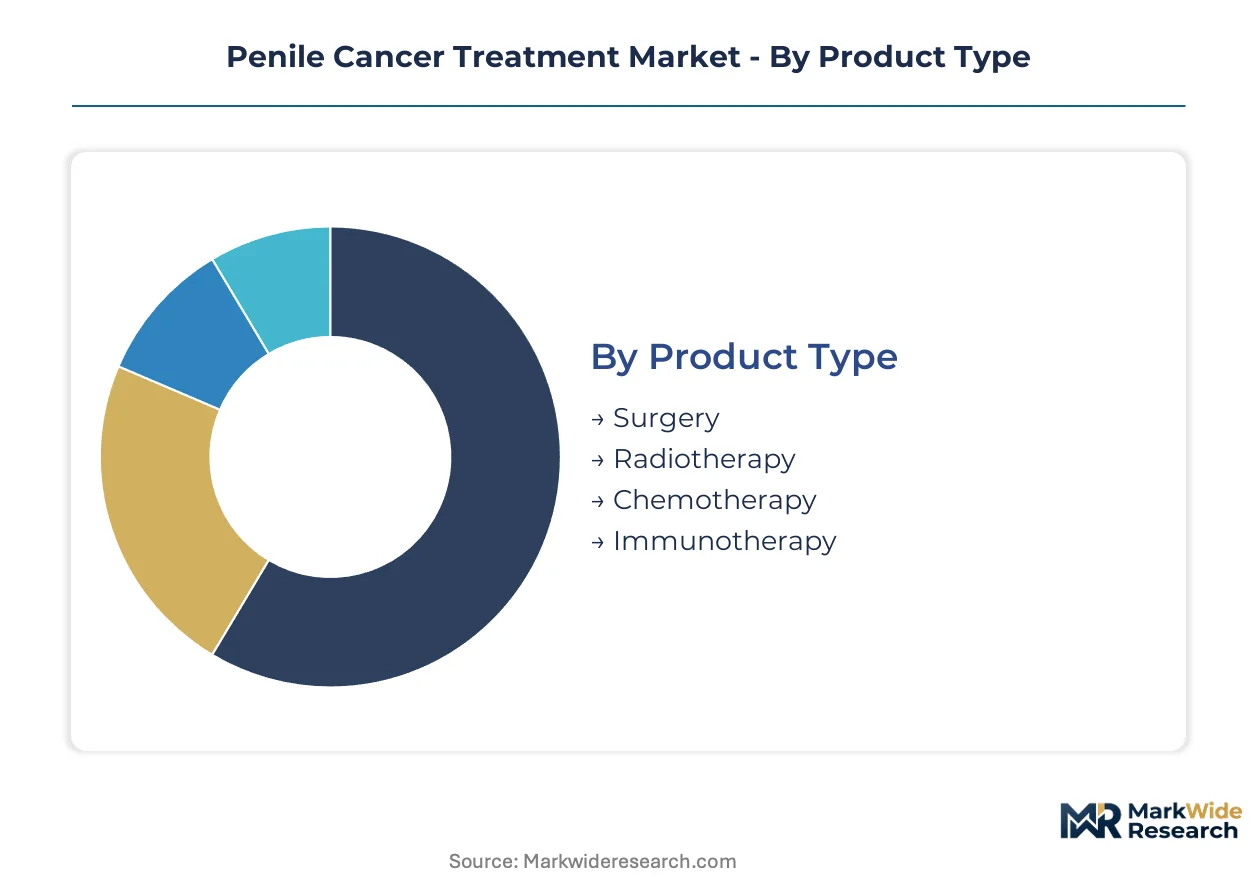
Penile cancer treatment segmentation reveals where bundled reimbursement concentrates margin pools and which modalities capture protocol share from conventional cytotoxic foundations. Understanding these divisions clarifies how referral networks direct volume toward specialized centers versus community settings.
Product Type:
Margin pools concentrate in surgical oncology and infusion services where bundled payments reward complex procedure economics and multimodal coordination.
- Surgery:Mohs micrographic surgery and sentinel lymph node biopsy miniaturize resection boundaries while preserving functional anatomy. Academic medical centers in the United States and Germany adopt these techniques for T1-T2 lesions previously managed with partial penectomy, compressing reconstructive burden and reducing psychosexual morbidity.
- Immunotherapy:PD-1/PD-L1 inhibitors capture protocol share in advanced disease settings where checkpoint blockade displaces cisplatin-based cytotoxic foundations. FDA orphan drug designation accelerates development timelines for squamous cell carcinoma programs targeting these pathways.
- Radiotherapy:External beam and brachytherapy protocols serve organ-preservation strategies in localized presentations.
- Chemotherapy:5-fluorouracil and cisplatin remain foundational despite manufacturing concentration vulnerabilities.
The dominant share belongs to Surgery, while Immunotherapy is expanding most quickly through biomarker-directed enrollment.
End User:
Volume concentration patterns reveal where fellowship-trained specialists and clinical trial infrastructure determine access to novel therapeutic modalities.
- Cancer Treatment Centers:Bundled reimbursement for complex genitourinary surgical oncology and infusion services concentrates margin pools in these institutions. Patient navigation consolidates referral patterns from community urology practices into high-volume tertiary settings with embedded trial infrastructure.
- Hospitals:Academic medical centers anchor multidisciplinary tumor boards coordinating surgical, radiation, and systemic therapy timelines. Germany's specialized oncology hospitals and Japan's designated cancer care hospitals exemplify this concentration.
- Clinics:Community urology practices transfer complex cases upstream due to specialist scarcity.
- Home Care:Oral targeted agents and supportive care protocols enable limited outpatient management.
Cancer Treatment Centers command the largest revenue concentration, with Hospitals retaining the deepest clinical trial penetration.
Therapy Area:
Protocol intensity and reimbursement tiers scale with disease stage, creating distinct economic profiles across curative and palliative intents.
- Localized Disease:Organ-preserving surgical techniques and adjuvant radiation dominate this segment. Mohs micrographic surgery standardization in the United States and Germany reduces radical resection rates for early-stage presentations.
- Advanced Disease:Systemic therapy escalation and multimodal combinations define this category. PD-1/PD-L1 inhibitor investigations capture the steepest expansion trajectory as first-line options displace cytotoxic doublets.
- Recurrence:Salvage protocols require specialized surgical oncology expertise concentrated in major metropolitan clusters.
- Palliative Care:Symptom-directed radiation and supportive systemic therapy address metastatic burden.
Localized Disease retains the highest procedure volume, though Advanced Disease shows the fastest protocol innovation uptake.
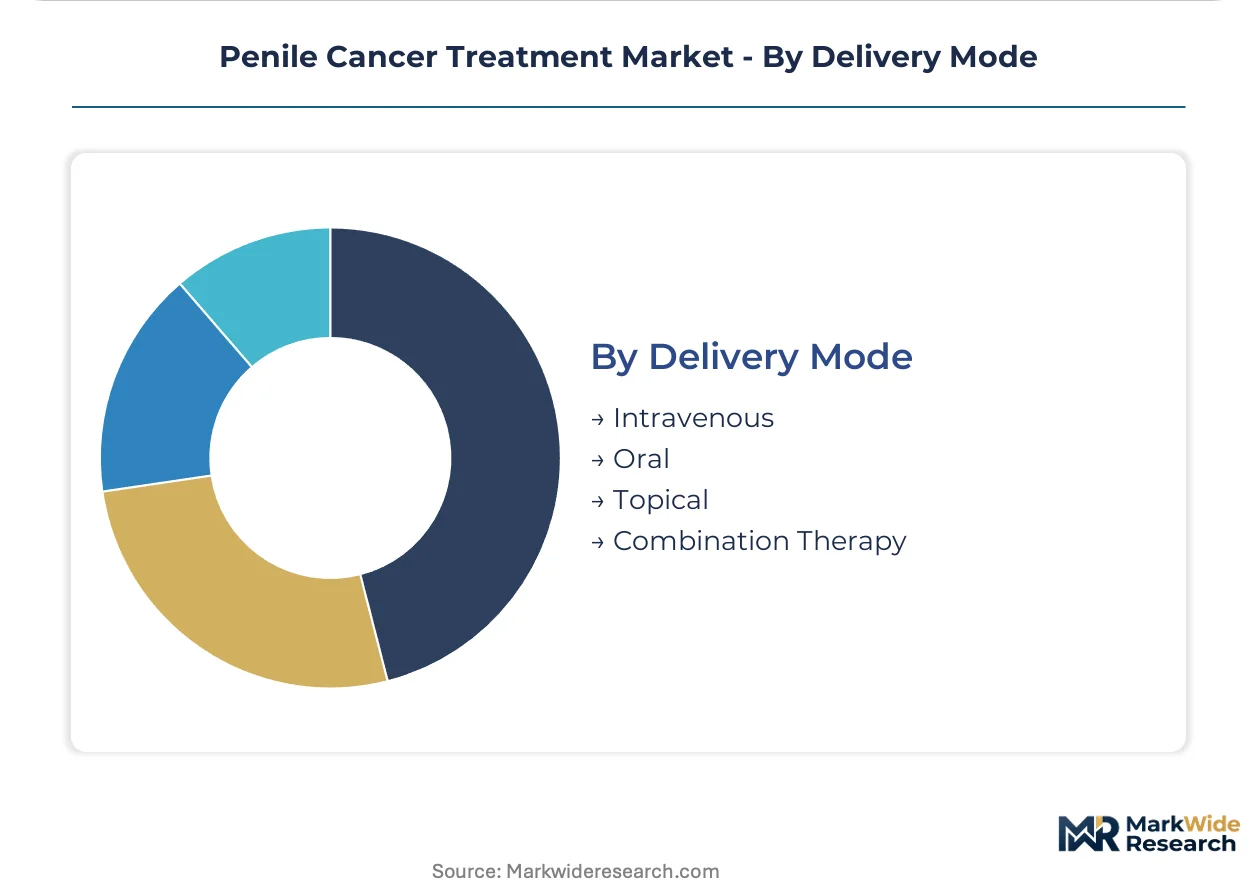
Delivery Mode:
Administration infrastructure requirements determine where therapy concentrates and which settings can support protocol compliance.
- Intravenous:Infusion services require specialized oncology nursing and adverse event management capabilities. Cancer treatment centers in the United States, Germany, and Japan concentrate this capacity due to bundled reimbursement alignment.
- Combination Therapy:Sequential or concurrent multimodal protocols demand care coordination infrastructure spanning surgical, radiation, and medical oncology services. Academic medical centers embed these capabilities through multidisciplinary tumor boards.
- Oral:Targeted agents enable outpatient administration with adherence monitoring requirements.
- Topical:5-fluorouracil and imiquimod serve select superficial lesions in limited settings.
Intravenous administration anchors the largest service volume, while Combination Therapy claims the highest reimbursement per episode.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized surgical oncology equipment and training protocols to cancer centers across Central Europe and the Middle East. Japanese pharmaceutical innovators supply PD-1 inhibitor compounds to academic medical centers in East Asia and Australia. The United States anchors clinical trial infrastructure that attracts investigator-initiated studies from Canada and Latin America.
United States
Academic medical centers in Houston, Chicago, and New York City concentrate fellowship-trained genitourinary oncologists capable of Mohs micrographic surgery. FDA orphan drug designation compresses development timelines for squamous cell carcinoma programs. The MD Anderson Cancer Center and Memorial Sloan Kettering Cancer Center anchor multidisciplinary tumor boards coordinating surgical, radiation, and systemic therapy timelines.
Germany
Specialized oncology hospitals in Munich, Heidelberg, and Berlin manage complex penile-preserving procedures with embedded clinical trial infrastructure. EMA's priority medicines scheme accelerates assessment pathways for unmet medical needs. The German Cancer Research Center in Heidelberg coordinates biomarker validation studies across the country's designated cancer care network.
Japan
Designated cancer care hospitals in Tokyo, Osaka, and Nagoya concentrate sentinel lymph node biopsy standardization for early-stage presentations. PMDA's Sakigake priority review compresses regulatory lag for novel oncology modalities. The National Cancer Center Hospital in Tokyo anchors PD-1/PD-L1 inhibitor investigations in advanced squamous cell carcinoma settings.
United Kingdom
Royal Marsden Hospital and University College London Hospitals consolidate referral patterns for rare male malignancies from community urology practices. MHRA parallel scientific advice accelerates alignment with FDA and EMA development pathways. London's integrated academic health science centers embed care coordination infrastructure for multimodal protocol delivery.
Australia
Peter MacCallum Cancer Centre in Melbourne and Royal Prince Alfred Hospital in Sydney anchor organ-preservation surgical techniques for localized disease presentations. TGA priority review pathways align with FDA breakthrough therapy designations for rare oncology indications. Australia's national cancer registries support real-world evidence generation for biomarker-directed enrollment protocols.
Penile Cancer Treatment Market Vendor Landscape
Listed leaders compete with private specialists across kinase inhibitor and checkpoint inhibitor development programs. Tier-one pharmaceutical conglomerates anchor PD-1/PD-L1 pathway investigations through sustained R&D commitment to rare tumor types. Mid-tier oncology specialists concentrate on squamous cell carcinoma biomarker validation and companion diagnostic co-development. Competitive moves center on strategic partnerships for clinical trial infrastructure and geographic licensing arrangements for East Asian access corridors.
Within the large-cap pharmaceutical tier, Pfizer Inc. and Bristol-Myers Squibb Company exemplify divergent strategic positioning. Pfizer leverages kinase inhibitor portfolio breadth to compete in targeted therapy segments. Bristol-Myers Squibb anchors its presence through checkpoint inhibitor development programs in squamous cell carcinomas. Merck & Co., Inc. occupies a distinct position through sustained dominance in PD-1 pathway investigations. These three entities collectively represent the competitive archetypes visible across the development landscape: kinase-focused, checkpoint-focused, and pathway-dominant.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline plc |
| AstraZeneca PLC |
| Eli Lilly and Company |
| Johnson & Johnson Services, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for platinum-based chemotherapy compounds concentrate pricing power with API manufacturers in India and China, while bundled reimbursement for surgical oncology services in the United States and Germany insulates hospital margins from raw material volatility. This inventory-to-pricing coupling forces cancer treatment centers to carry buffer stocks of cisplatin and 5-fluorouracil despite cold-chain requirements, embedding working capital costs into procedure economics.
Pricing Analysis
Hospital procurement consortiums anchor contract-based long-term offtake structures for cytotoxic agents, with FDA certification tier and volume scale driving price differentiation between academic medical centers and community clinics. Pricing pressure stems from EMA reference pricing harmonization across European markets, compressing reimbursement ceilings for immunotherapy infusion services. Community urology practices exhibit highest price sensitivity due to limited formulary flexibility, while integrated cancer networks leverage bundled episode payments to absorb cost compression.
Supply Chain Analysis
Port congestion at Rotterdam and Singapore disrupts inbound logistics for temperature-sensitive biologics, extending delivery windows for PD-1 inhibitor shipments to Australian and Japanese treatment centers. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, with platinum salt dependencies and monoclonal antibody cell line sourcing creating single-source vulnerability for orphan oncology indications. Distribution runs through specialized cold-chain logistics providers serving tertiary cancer centers with validated storage protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision-molecular diagnostic platforms are resequencing penile cancer treatment into a platform-economy inflection, where biomarker-directed enrollment protocols interoperate across EMA, FDA, and PMDA regulatory frameworks to compress trial timelines and expand addressable patient pools.
For Market Incumbents: Fortify clinical trial infrastructure in Heidelberg and Tokyo to defend against mid-tier oncology specialists capturing biomarker validation partnerships. Prioritize backward integration into companion diagnostic development to lock in protocol share as molecular stratification displaces conventional staging algorithms. For New Entrants and Emerging Players: Lead with sentinel lymph node biopsy standardization services in Australia's designated cancer care hospitals, where organ-preservation surgical techniques remain underpenetrated relative to the United States and Germany. Position through GPO contracts with integrated delivery networks seeking to reduce referral leakage to academic medical centers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because FDA orphan drug designation and Japan's Sakigake priority review create parallel access corridors that reward portfolio diversification across rare tumor indications. Target mid-tier firms with validated PD-1/PD-L1 squamous cell carcinoma data packages. Watch EMA priority medicines scheme acceptance rates as the signal for reimbursement velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Biomarker-directed enrollment compresses protocol timelines for squamous cell carcinoma programs. |
| Regulatory Approval Pathway | Parallel FDA and EMA orphan designations accelerate market exclusivity for rare tumor indications. |
| Licensing Agreement | East Asian access corridors open through PMDA Sakigake and NMPA priority review partnerships. |
| Manufacturing Scale-Up | Cold-chain capacity expansion secures biologic supply integrity for immunotherapy infusion services. |
| Pipeline Diversification | Kinase inhibitor portfolios complement checkpoint inhibitor development in targeted therapy segments. |
Methodological Framework
Operator-level perspectives from genitourinary oncology fellowship directors, hospital procurement managers at designated cancer care hospitals, regulatory affairs leads at EMA and PMDA, and formulary directors at major US integrated delivery networks anchored the qualitative base. Secondary validation drew from FDA orphan drug designation databases, EMA priority medicines scheme assessments, ClinicalTrials.gov squamous cell carcinoma program listings, and hospital procurement database extracts. Bottom-up procedure volume estimates and top-down reimbursement flow analysis triangulated market sizing across the analysis window.
Sensitivity analysis tested biomarker validation timeline assumptions and regulatory approval pathway probabilities across the projection horizon. Segmentation dimensions modeled included therapy modality, disease stage presentation, delivery mode infrastructure requirements, and regional regulatory cluster alignment. CAGRs derived from procedure volume trajectories and reimbursement rate evolution, with inputs from real-world evidence generation protocols and companion diagnostic adoption curves.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA orphan oncology frameworks; material policy shifts would require re-modeling. Specific risk factors include biomarker validation bottlenecks, cytotoxic agent supply disruptions, and genitourinary specialist scarcity concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Gallbladder Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Tennis Elbow Treatment Market
Medical Treatment
Onchocerciasis Treatment Market