
 Lysosomal Storage Disease Treatment Market | 2026-2036
Lysosomal Storage Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lysosomal Storage Disease Treatment Market Foresight
Buyer concentration is rebalancing as consolidated hospital systems and specialty pharmacy networks gain leverage over fragmented prescriber pools. Sanofi leverages its global rare disease infrastructure to sustain market presence across Gaucher and Fabry franchises. Takeda Pharmaceutical Company Limited anchors its position through inherited Shire lysosomal assets and deep hematology channel relationships.
Lysosomal storage disease treatment encompasses therapeutic interventions that replace deficient enzymes, reduce substrate accumulation, or stabilize mutant proteins to halt progressive cellular damage in inherited metabolic disorders. Enzyme replacement therapy dominates commercial value due to established intravenous infusion protocols and long-term safety databases, though manufacturing complexity limits margin expansion. Substrate reduction therapy competes in oral convenience segments where patient adherence and home administration drive preference, particularly in adult Gaucher type 1 populations.
FDA orphan drug exclusivity provisions and EMA conditional marketing authorization frameworks shape investment thresholds and launch sequencing for developers. Japan's PMDA sakigake designation accelerates local access reviews, creating parallel regulatory tracks that fragment global development strategies. Stakeholders must monitor how CMS and national health technology assessment bodies recalibrate value thresholds for single-dose gene therapies against chronic enzyme replacement economics.
Market Dynamics
Gene therapy pipeline maturation is compressing clinical development timelines and forcing established enzyme replacement manufacturers to defend chronic therapy franchises against single-dose curative alternatives. FDA accelerated approval pathways and EMA conditional marketing authorizations have shortened the gap between proof-of-concept and commercial launch, intensifying competitive pressure on incumbent platforms.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity provisions for rare disease indications reduce competitive entry risk and attract venture funding toward lysosomal targets with small patient populations.
- Pediatric hematology-oncology expansion:Academic medical centers in the United States, Germany, and Japan are building dedicated lysosomal disease programs to capture gene therapy referrals and infusion volume.
- Substrate reduction therapy convenience:Oral cerdelga and eliglustat formulations address patient preference for home administration in adult Gaucher type 1 populations, expanding addressable volume beyond hospital-dependent infusion centers.
Market Restraints
- Bioreactor capacity concentration:Mammalian cell culture manufacturing for recombinant enzymes concentrates at single-source facilities in Switzerland and Massachusetts, creating supply vulnerability without geographic redundancy.
- Reimbursement value threshold compression:CMS and Germany's G-BA are tightening cost-effectiveness benchmarks for chronic enzyme therapies as single-dose gene therapies enter the market with higher upfront costs but lifetime value propositions.
- Gene therapy manufacturing complexity:Viral vector production bottlenecks at contract development organizations limit batch release rates and extend patient wait times for clinical and commercial supply.
Strategic Opportunities
- Japan PMDA sakigake designation:Priority review pathways for innovative rare disease therapies enable earlier market entry and premium pricing capture before European and United States launches.
- Home infusion channel development:Specialty pharmacy networks are building nursing capacity for subcutaneous enzyme administration, displacing hospital outpatient dependence and capturing margin from site-of-care shifts.
- Next-generation substrate reduction:Blood-brain barrier penetrant small molecules for neuronopathic Gaucher and Fabry variants address unmet need in central nervous system manifestations that intravenous enzymes cannot reach.
Industry Challenges
- Gene therapy vector immunogenicity:Pre-existing neutralizing antibodies against adeno-associated virus serotypes exclude substantial patient populations from clinical trials and commercial eligibility, requiring screening infrastructure and alternative serotype development.
- Long-term follow-up infrastructure:Fifteen-year post-treatment monitoring commitments for gene therapies strain patient registries and pharmacovigilance systems originally designed for chronic therapy adverse event reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lysosomal Storage Disease Treatment Market |
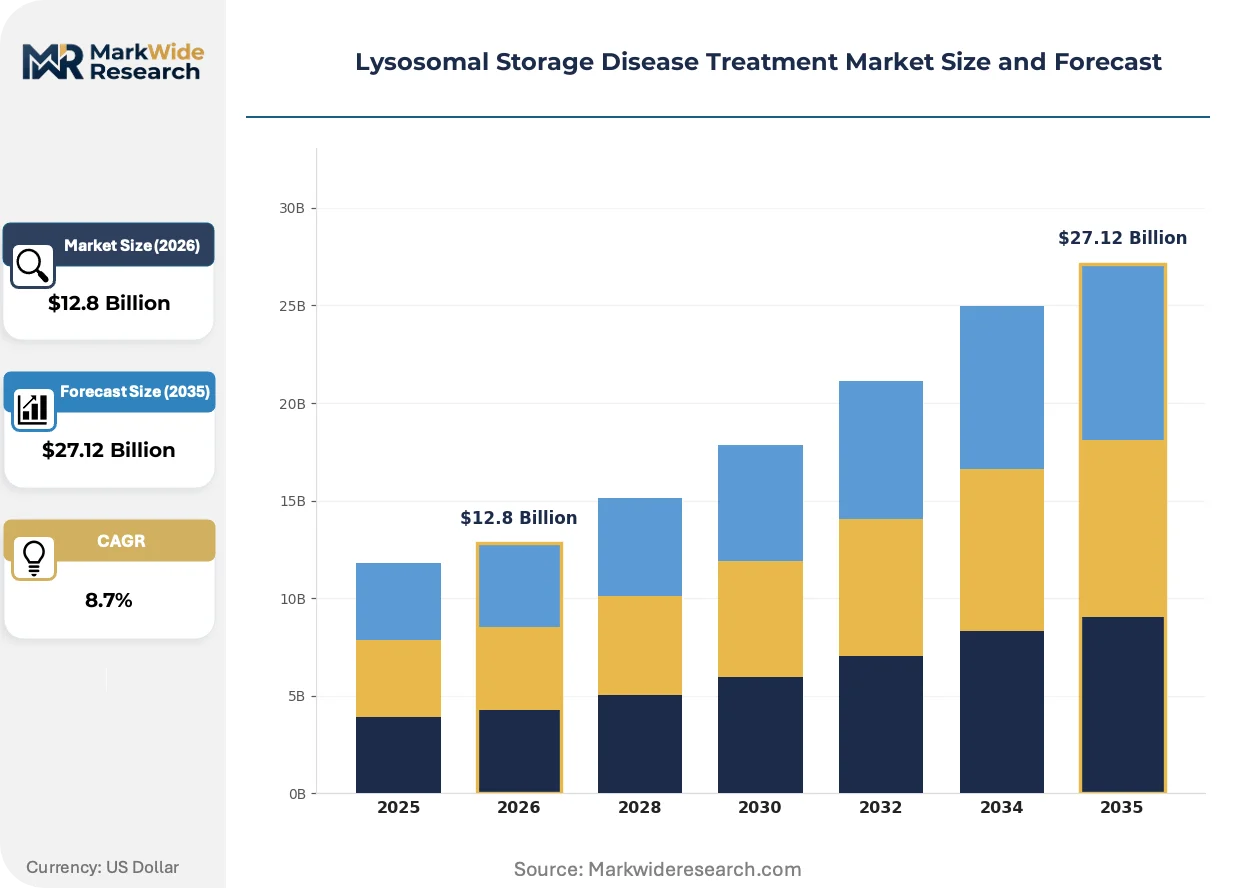
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Substrate Reduction Therapy, Chaperone Therapy, Palliative Care Indication: Gaucher Disease, Fabry Disease, Pompe Disease, Mucopolysaccharidosis End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Delivery Mode: Intravenous, Subcutaneous, Oral, Others |
| Companies Covered | Sanofi, Pfizer, Takeda Pharmaceutical Company Limited, BioMarin Pharmaceutical, Johnson & Johnson, Amicus Therapeutics, Alexion Pharmaceuticals, Orchard Therapeutics, Sigilon Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lysosomal Storage Disease Treatment Market Shifts & Advancements
Platform convergence between gene therapy and small molecule disciplines is dissolving traditional boundaries between curative and chronic treatment paradigms. Developers now pursue hybrid strategies that combine substrate reduction maintenance with one-time genetic correction.
CRISPR-based in vivo editing is converging with lipid nanoparticle delivery systems to enable direct liver targeting for hepatic lysosomal enzyme deficiencies. Academic research centers in the United States and the Netherlands are advancing IND-enabling studies for Gaucher and Fabry applications. This convergence is compressing the timeline from preclinical validation to first-in-human trials and forcing enzyme replacement manufacturers to accelerate next-generation platform investments.
EMA's updated guideline on clinical trials in small populations is streamlining adaptive trial designs for ultra-rare lysosomal indications. The framework permits single-arm studies with external controls, reducing patient recruitment burdens and enabling faster readouts on surrogate endpoints. Developers targeting neuronopathic variants are restructuring phase programs to align with these provisions, prioritizing European launch sequencing to leverage the regulatory flexibility.
Patient advocacy organizations are consolidating procurement influence through centralized registry platforms that track treatment outcomes and steer manufacturer selection. The National Gaucher Foundation in the United States and the Fabry International Network are deploying these databases to negotiate access terms and influence payer coverage decisions. This aggregation is most visible in Germany and the United States, where foundation-supported centers of excellence channel volume toward preferred therapy protocols.
Lysosomal Storage Disease Treatment Market Segmentation
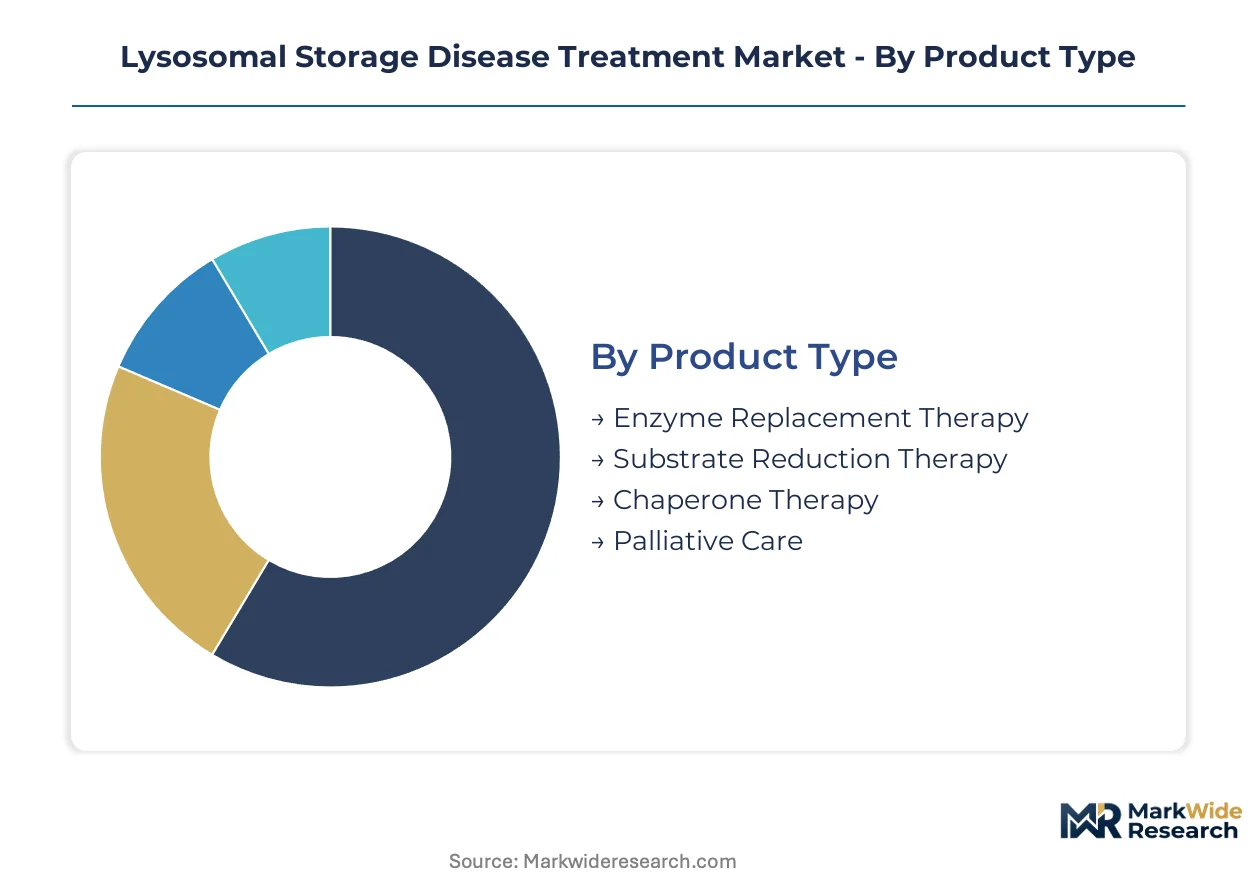
Treatment modality selection in lysosomal storage diseases hinges on disease severity, organ involvement, and patient age. Segmentation reveals how enzyme replacement dominates commercial value while gene therapy pipelines reshape future category boundaries.
Product Type:
Customization intensity spans from chronic infusion-dependent biologics to oral small molecules designed for home administration convenience.
- Enzyme Replacement Therapy:Recombinant human enzymes manufactured via mammalian cell culture address Gaucher, Fabry, and Pompe deficiencies through regular intravenous infusions. Demand concentrates at academic medical centers in the United States, Germany, and Japan where infusion infrastructure and payer frameworks for ultra-orphan biologics are most mature. Manufacturing complexity at single-source bioreactor facilities in Switzerland and Massachusetts constrains supply elasticity.
- Substrate Reduction Therapy:Oral small molecules including eliglustat and miglustat reduce glycolipid substrate accumulation in Gaucher type 1 patients with intact spleen function. Adult populations in the United States and Germany drive preference for home administration protocols that eliminate hospital outpatient dependence. Convenience advantages expand addressable volume beyond infusion-center capacity constraints.
- Chaperone Therapy:Pharmacological chaperones stabilize mutant lysosomal enzymes for Fabry disease patients with amenable genotypes.
- Palliative Care:Symptom management protocols address advanced neuronopathic variants where disease-modifying therapies remain unavailable.
Leading the category by volume: Enzyme Replacement Therapy. Growing fastest: Substrate Reduction Therapy.
Indication:
Disease prevalence and treatable population size determine investment allocation across hematologic, cardiac, and neurological manifestation patterns.
- Gaucher Disease:The most common lysosomal storage disorder with established enzyme replacement and substrate reduction options across type 1 non-neuronopathic presentations. Type 2 and 3 neuronopathic variants drive unmet need for blood-brain barrier penetrant therapies.
- Fabry Disease:X-linked glycolipid storage disorder affecting kidney, heart, and peripheral nerve function with approved enzyme replacements and chaperone alternatives. Cardiac variant presentations in adult males concentrate diagnosis and treatment initiation at cardiology referral pathways in Germany and Japan.
- Pompe Disease:Glycogen storage myopathy with infantile-onset and late-onset forms requiring lifelong enzyme replacement.
- Mucopolysaccharidosis:Heterogeneous group of disorders with variable central nervous system involvement and limited treatment options beyond hematopoietic stem cell transplantation for select subtypes.
Dominant by patient volume: Gaucher Disease. Steepest expansion trajectory: Fabry Disease.
End User:
Site-of-care economics and nursing capacity requirements segment demand across institutional and home-based administration settings.
- Hospitals:Pediatric hematology-oncology units at academic medical centers anchor infusion volume for enzyme replacement therapies requiring intravenous administration and adverse event monitoring.
- Specialty Clinics:Dedicated lysosomal disease centers concentrate multidisciplinary care coordination and clinical trial access for complex patient populations.
- Homecare Settings:Subcutaneous enzyme administration and oral substrate reduction protocols shift volume toward specialty pharmacy nursing networks.
- Research Institutions:Gene therapy trial sites capture pre-commercial patient cohorts and longitudinal outcome data.
Highest revenue concentration: Hospitals. Fastest channel shift: Homecare Settings.
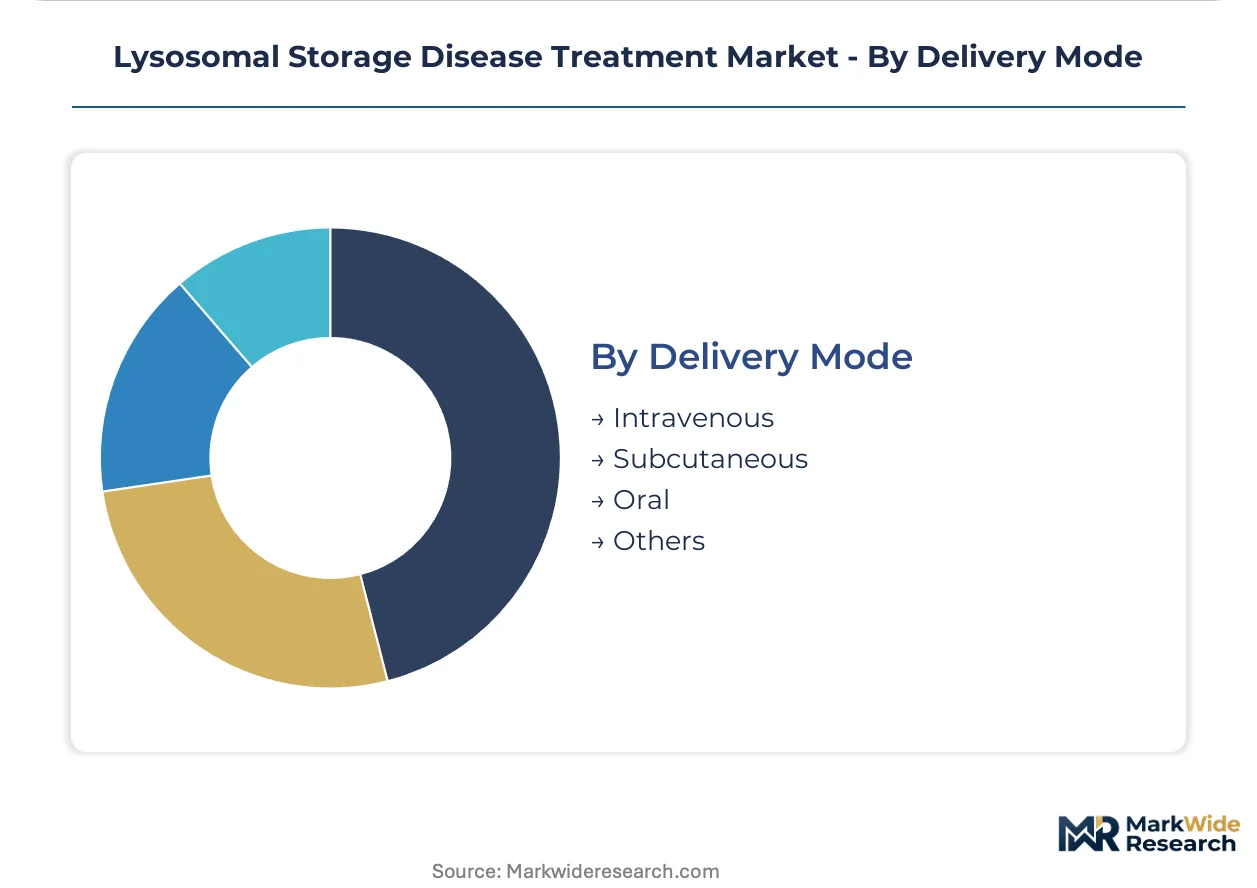
Delivery Mode:
Route selection balances bioavailability requirements against patient adherence and healthcare resource utilization patterns.
- Intravenous:Established administration route for large-molecule enzyme replacements requiring systemic circulation and tissue penetration.
- Subcutaneous:Emerging alternative for select enzyme formulations enabling home administration with reduced infusion center dependence.
- Oral:Substrate reduction therapies and chaperone molecules leverage gastrointestinal absorption for patient convenience.
- Others:Intrathecal and gene therapy delivery modalities address central nervous system manifestations inaccessible to peripheral circulation.
Current standard: Intravenous. Most rapid adoption gain: Subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where payer frameworks for ultra-orphan therapies are most established. Academic medical centers in these markets anchor infusion volume for enzyme replacement therapies. Gene therapy pipelines are accelerating local access reviews and reshaping commercial launch sequencing.
United States
Pediatric hematology-oncology units at academic medical centers drive enzyme replacement volume through established infusion infrastructure. FDA orphan drug exclusivity provisions attract venture funding toward lysosomal targets with small patient populations. The Greater Boston cluster concentrates gene therapy development activity alongside Swiss bioreactor supply relationships.
Germany
Cardiology referral pathways in university hospitals concentrate Fabry disease diagnosis and treatment initiation for adult male patients. Germany's G-BA tightens cost-effectiveness benchmarks for chronic enzyme therapies as single-dose gene alternatives enter reimbursement negotiations. The Rhine-Ruhr metropolitan region anchors hematology-oncology capacity for Gaucher and Fabry infusion networks.
Japan
PMDA sakigake designation accelerates local access reviews for innovative rare disease therapies, enabling earlier market entry. Japan's national health insurance system maintains premium pricing capture for ultra-orphan biologics before European and United States launches. The Kanto region around Tokyo concentrates specialty clinic capacity for lysosomal disease multidisciplinary care.
Switzerland
Single-source bioreactor facilities for recombinant enzyme manufacturing concentrate supply risk without geographic redundancy. Swissmedic maintains alignment with EMA conditional marketing authorization frameworks for rare disease therapies. The Basel biopharma cluster anchors mammalian cell culture production for global Gaucher and Fabry enzyme supply.
United Kingdom
NHS England's specialized commissioning framework channels lysosomal therapy volume toward designated centers of excellence. The MHRA operates post-Brexit recognition pathways for EMA orphan drug approvals, streamlining access timelines. London's academic hospital networks concentrate gene therapy trial recruitment and longitudinal outcome monitoring infrastructure.
Lysosomal Storage Disease Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue gene therapy and next-generation substrate reduction platforms. The vendor base stratifies across multinational pharmaceutical conglomerates with rare disease divisions, mid-cap biotechnology specialists, and gene therapy pure-plays. Three archetypes dominate: enzyme replacement incumbents defending chronic therapy franchises, substrate reduction oral developers capturing convenience preferences, and gene therapy innovators compressing clinical timelines. Competitive moves concentrate on M&A to secure viral vector manufacturing capacity and strategic partnerships to access blood-brain barrier penetrant small molecules.
Within the multinational tier, Sanofi and Takeda Pharmaceutical Company Limited exemplify established rare disease infrastructure players. Sanofi leverages global distribution networks across Gaucher and Fabry franchises, while Takeda anchors position through inherited lysosomal assets and deep hematology channel relationships. Among biotechnology specialists, Amicus Therapeutics occupies the pharmacological chaperone segment for genotype-amenable Fabry populations. These three entities represent distinct strategic postures: conglomerate scale defense, acquired portfolio integration, and targeted molecular mechanism specialization.
| Leading Market Players |
|---|
| Sanofi |
| Pfizer |
| Takeda Pharmaceutical Company Limited |
| BioMarin Pharmaceutical |
| Johnson & Johnson |
| Amicus Therapeutics |
| Alexion Pharmaceuticals |
| Orchard Therapeutics |
| Sigilon Therapeutics |
| Others |
Supply & Pricing Matrix
Specialized mammalian cell culture technicians in the Basel biopharma cluster command wage premiums that cascade into three-tier pricing spreads across enzyme replacement therapies, with Swiss-manufactured biologics carrying 40-60 percent cost differentials over contract-manufactured alternatives in emerging production zones.
Pricing Analysis
Volume concentrates in chronic enzyme replacement regimens while margin capture shifts toward single-dose gene therapy platforms. Pricing stratifies across premium intravenous biologics, standard oral substrate reduction therapies, and economy-tier palliative protocols. Cost compression in chronic infusion segments intensifies as CMS and Germany's G-BA tighten cost-effectiveness benchmarks against curative alternatives. Hospital systems and consolidated specialty pharmacy networks exhibit highest price sensitivity, whereas academic medical centers with dedicated lysosomal disease programs demonstrate lowest sensitivity due to restricted patient pools and orphan drug exclusivity protections.
Supply Chain Analysis
Regional distribution centers in Switzerland, Massachusetts, and Japan operate hub-and-spoke patterns for temperature-controlled biologics, with 72-hour cold chain integrity requirements dictating warehouse placement. Manufacturing draws from single-source bioreactor facilities in Basel and Boston, with viral vector production concentrated at contract development organizations in North Carolina and the Netherlands. Single-source vulnerability dominates risk profiles, as mammalian cell culture capacity lacks geographic redundancy for recombinant enzyme supply. Distribution runs through specialty pharmacy networks with nursing capacity for home infusion, displacing traditional hospital outpatient dependence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy platforms are displacing chronic enzyme replacement paradigms, with adeno-associated virus delivery systems and CRISPR-based editing technologies compressing clinical development timelines and threatening incumbent revenue streams.
For Market Incumbents: Deepen viral vector manufacturing partnerships to secure capacity for hybrid portfolio strategies combining substrate reduction maintenance with genetic correction. Accelerate next-generation blood-brain barrier penetrant small molecule investments to defend against neuronopathic indication losses. Lock in hematology channel relationships at academic medical centers before gene therapy trial sites capture referral volume.
For New Entrants and Emerging Players: Adult Gaucher type 1 patients seeking home administration convenience represent an underserved buyer archetype with highest willingness to switch from hospital-dependent infusions. Oral substrate reduction formulations and subcutaneous enzyme alternatives capture this preference shift. Prioritize specialty pharmacy nursing network partnerships over hospital system contracting to bypass incumbent channel control.
For Investors and Strategic Acquirers: Re-rating potential sits with gene therapy pure-plays given FDA accelerated approval pathway utilization and EMA conditional marketing authorization frameworks compressing commercial timelines. Long-term viability hinges on manufacturing scale-up execution and fifteen-year post-treatment monitoring infrastructure deployment. Watch PMDA sakigake designation announcements as inflection indicators for premium pricing capture before European and United States market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Viral Vector Manufacturing Scale-Up | Contract development organization capacity constraints at Lonza and Catalent sites limit batch release rates for gene therapy commercial supply. |
| Blood-Brain Barrier Penetrant R&D | |
| Specialty Pharmacy Network Expansion | Home infusion nursing capacity at BioPlus and Accredo displaces hospital outpatient dependence and captures site-of-care margin shifts. |
| Patient Registry Infrastructure | Longitudinal outcome databases at National Gaucher Foundation and Fabry International Network steer manufacturer selection and payer negotiations. |
| Regulatory Parallel Track Development | PMDA sakigake designation enables Japan market entry before FDA and EMA submissions, fragmenting global launch sequencing strategies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. FDA orphan drug designations, EMA conditional marketing authorization submissions, and ClinicalTrials.gov protocol registrations provided pipeline visibility. Bottom-up patient population estimates triangulated against top-down revenue benchmarks across treatment modalities.
Data-stream reconciliation across manufacturer reported sales, national health insurance reimbursement databases, and specialty pharmacy dispensing records calibrated volume and value outputs across the analysis window. Segmentation dimensions modeled include treatment modality, indication severity, administration route, patient age cohort, and regional regulatory cluster. CAGRs derived from epidemiological prevalence projections, therapy penetration assumptions, and pricing trajectory scenarios for chronic versus curative treatment paradigms.
Revisions become necessary when gene therapy immunogenicity exclusions expand, bioreactor capacity constraints intensify, or CMS value threshold recalibrations accelerate. Forecasts reflect documented assumptions around regulatory approval timelines, manufacturing scale-up execution, and payer negotiation outcomes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market