
 Next-Generation Neurofeedback Device Market | 2026-2036
Next-Generation Neurofeedback Device Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Neurofeedback Device Market Foresight
Graphene-enhanced dry electrode arrays is expanding its addressable footprint in next-generation neurofeedback hardware by eliminating conductive gel dependencies and cutting per-session consumable costs. Emotiv leverages proprietary polymer composites to sustain a hardware-plus-software subscription model across research and consumer tiers. Muse anchors its market position through meditation-focused wearable form factors that compete on price accessibility against clinical-grade alternatives. Neurocare Group AG specializes in integrated clinic solutions that dominate European psychiatric service channels.
Next-generation neurofeedback devices comprise real-time brain activity monitoring systems that translate electrophysiological signals—typically EEG oscillations in the 0.5-100 Hz range—into actionable feedback for cognitive or behavioral modulation, with primary commercial purpose spanning therapeutic intervention and performance optimization. Wearable devices and brain-computer interfaces together capture the steepest growth trajectories as miniaturization and edge AI processing collapse latency between signal acquisition and user-facing output. EEG technology leads installed base volume while neurostimulation modalities command premium pricing in clinical reimbursement environments where regulatory clearance complexity creates margin protection.
The FDA breakthrough device program and EU MDR classification requirements for active implantable and software-driven medical devices together shape product development timelines and market access economics for manufacturers targeting reimbursed clinical use cases. ISO 13485 quality management certification functions as a de facto gating mechanism for supply relationships with hospital procurement networks across North America and Europe. Stakeholders must monitor evolving digital therapeutics reimbursement codes and predicate device evidentiary standards as the decisive variables separating scalable clinical deployment from confined wellness-channel positioning.
Market Dynamics
The FDA breakthrough device designation pathway compresses time-to-market for EEG-based digital therapeutics, while Germany's statutory health insurance pilot programs for digital health applications expand covered indications and validate clinical reimbursement models.
Growth Catalysts
- EU MDR streamlined classification:The Medical Device Regulation's software-driven medical device framework accelerates regulatory clearance timelines for neurofeedback platforms targeting reimbursed clinical use cases across European psychiatric service channels.
- Graphene-enhanced dry electrode diffusion:Elimination of conductive gel dependencies cuts per-session consumable costs and expands addressable footprint in ambulatory settings previously excluded by hygiene protocols.
- Edge AI processing miniaturization:On-device signal processing collapses latency between EEG acquisition and user-facing output, enabling real-time feedback loops in wearable form factors for cognitive performance optimization.
Market Restraints
- ISO 13485 certification bottleneck:Quality management certification functions as de facto gating mechanism for supply relationships with hospital procurement networks, excluding uncertified manufacturers from reimbursed clinical channels.
- Precious metal electrode cost volatility:Silver and gold flake dependencies in high-fidelity sensor arrays expose hardware margins to commodity price swings in thin-margin consumer tiers.
- Neurostimulation predicate device requirements:FDA evidentiary standards for active implantable modalities demand extensive clinical trial investment, protecting incumbents but blocking rapid market entry.
Strategic Opportunities
- Underpenetrated pediatric ADHD indication:Germany's DiGA fast-track pathway for digital therapeutics creates reimbursement precedent for attention-deficit applications with limited pharmaceutical alternatives.
- Brain-computer interface convergence:Integration of neurofeedback training with motor rehabilitation protocols opens stroke recovery channels previously served by separate device categories.
- Direct-to-employer wellness channel:Corporate cognitive performance programs bypass clinical reimbursement complexity while capturing premium pricing through productivity-linked value propositions.
Industry Challenges
- Electrophysiologist talent scarcity:Interpretation of 0.5-100 Hz oscillation patterns for protocol customization requires specialized training unavailable in standard biomedical engineering curricula.
- Legacy EMR integration friction:Hospital information system connectivity demands consume 12-18 month implementation cycles, delaying revenue recognition for clinic-focused platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Neurofeedback Device Market |
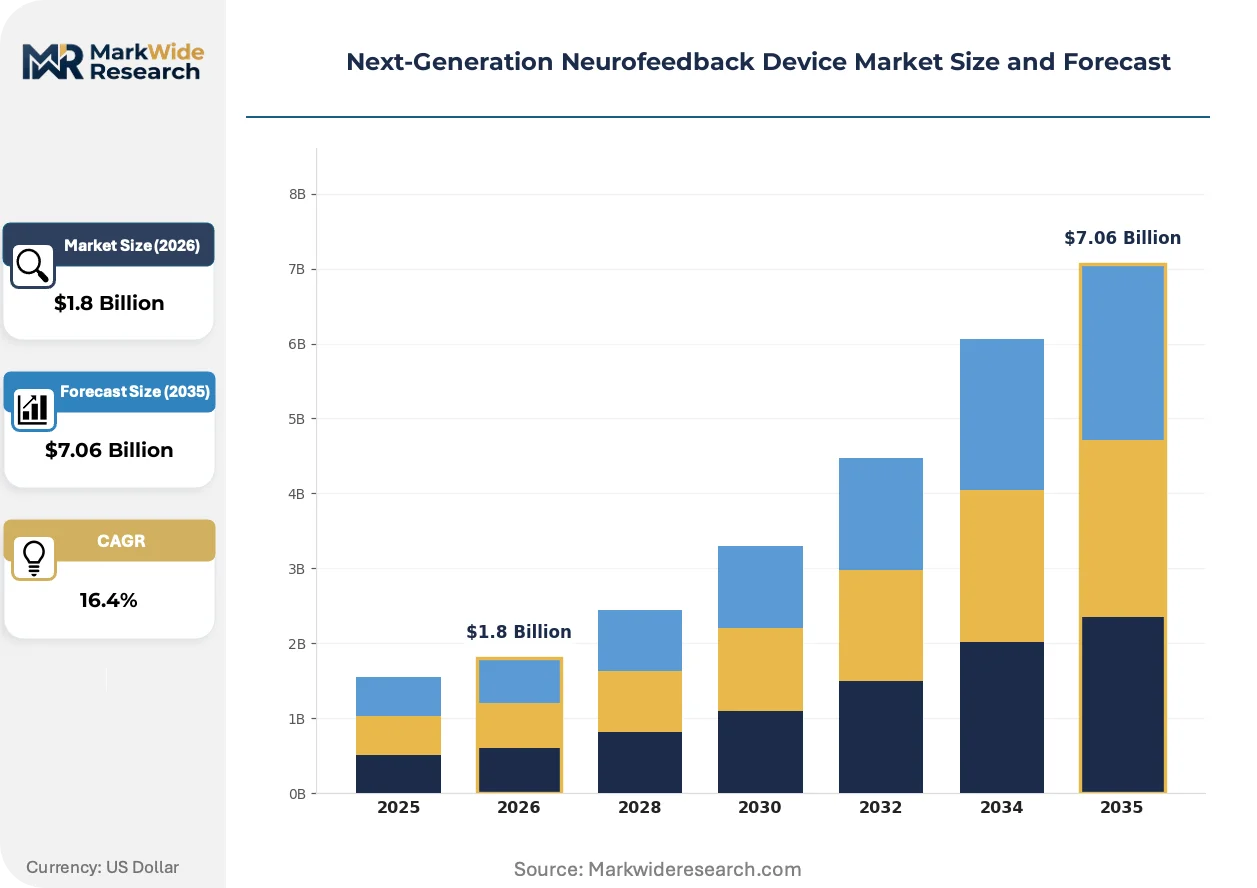
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Software Platforms, Brain-Computer Interfaces Technology: EEG, fMRI, Neurostimulation, Biofeedback Sensors End User: Clinics, Research Institutions, Fitness Centers, Home Users Application: Stress Management, Cognitive Enhancement, Sleep Improvement, Mental Health Treatments |
| Companies Covered | BrainMaster Technologies, Inc, Emotiv, Muse, NeuroSky, Neurocare Group AG, Thought Technology Ltd, Myndlift Ltd, Mitsar Co. Ltd, Narbis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Neurofeedback Device Market Shifts & Advancements
Real-time signal processing architectures and dry sensor materials are collapsing the hardware boundary between clinical-grade and consumer-accessible neurofeedback, while regulatory frameworks for digital therapeutics mature.
Graphene-enhanced polymer composites are integrating conductive pathways directly into flexible substrate layers, eliminating gel-based impedance reduction. University hospital neuropsychiatry departments are adopting these arrays for ambulatory monitoring protocols. The technology is integrating previously incompatible use cases—clinical-grade signal fidelity with consumer-grade application convenience—into single hardware platforms.
The EU MDR's software-as-medical-device classification requirements impose clinical evidence standards on algorithm-driven feedback systems. Manufacturers must demonstrate therapeutic outcome equivalence to predicate interventions. European psychiatric service providers are responding by consolidating procurement around vendors with pre-cleared quality management systems.
Subscription-based access models are displacing perpetual license structures in research and wellness segments. End-users prefer bundled hardware-software-telemetry packages with predictable annual costs. This preference shift concentrates most visibly in German statutory health insurance pilot programs, where reimbursement frameworks favor ongoing therapeutic relationship documentation over one-time device acquisition.
Next-Generation Neurofeedback Device Market Segmentation
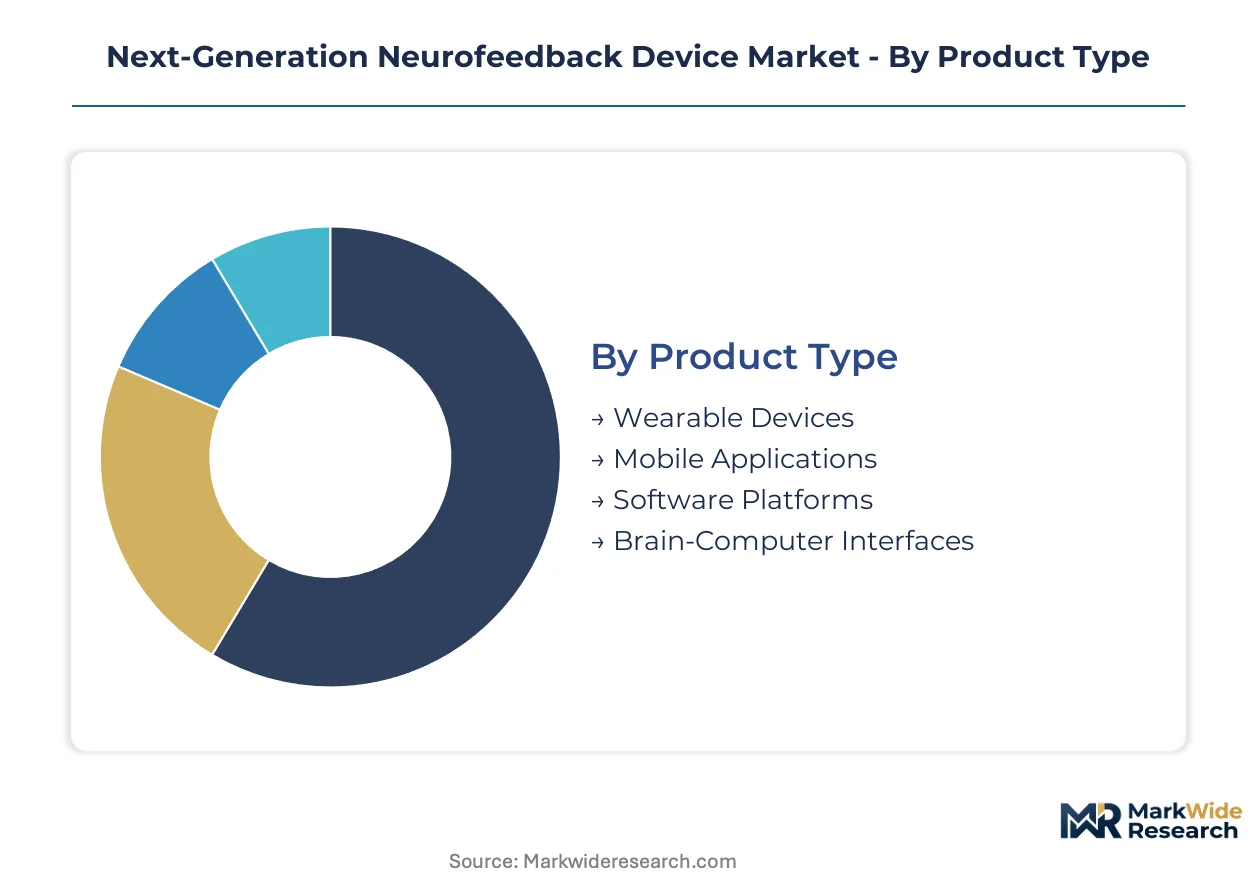
Segmentation in neurofeedback devices separates hardware-centric revenue pools from software-recurring streams, while end-use stratification determines whether vendors pursue FDA breakthrough pathways or direct-to-consumer channels. Technology choices lock manufacturers into distinct regulatory and reimbursement ecosystems that resist cross-segment mobility.
Product Type:
Wearable devices capture volume leadership through consumer accessibility, while brain-computer interfaces concentrate premium pricing in reimbursed clinical environments.
- Wearable Devices:Headband and earbud form factors integrate dry electrode arrays with edge AI processing for real-time feedback. Demand concentrates in German statutory health insurance pilot programs where DiGA reimbursement validates prescription-channel deployment for stress and sleep indications.
- Brain-Computer Interfaces:Implantable and non-invasive motor control systems translate neural signals into device commands for stroke rehabilitation protocols. Hospital neuropsychiatry departments in Munich and Berlin drive adoption where EU MDR classification enables bundled reimbursement with physical therapy services.
- Mobile Applications:Software-only delivery through smartphone platforms reduces hardware barriers to trial. Subscription monetization dominates wellness segments outside formal reimbursement frameworks.
- Software Platforms:Cloud-based telemetry and protocol management systems serve multi-site clinic networks. Procurement concentrates around ISO 13485-certified vendors with pre-cleared quality management systems for hospital information system integration.
Today's leader: Wearable Devices. Tomorrow's challenger: Brain-Computer Interfaces.
Technology:
EEG dominates installed base through decades of clinical validation, while neurostimulation commands margin protection via predicate device regulatory complexity.
- EEG:Surface electrode arrays measuring 0.5-100 Hz oscillations provide the foundational signal architecture for most commercial neurofeedback. German university hospitals anchor demand as graphene-enhanced dry electrodes eliminate gel dependencies for ambulatory monitoring expansion.
- Neurostimulation:Transcranial direct current and alternating current modulation systems apply external electrical fields to modulate cortical excitability. FDA breakthrough device designation compresses time-to-market for platforms targeting treatment-resistant depression in US academic medical centers.
- fMRI:Blood-oxygen-level-dependent imaging enables deep brain structure visualization for research protocols. Capital intensity and magnet installation requirements restrict deployment to major research institutions with dedicated imaging centers.
- Biofeedback Sensors:Peripheral physiological measures including heart rate variability and galvanic skin response complement central nervous system signals. Fitness center channels in Hamburg and Cologne adopt these for hybrid stress management programs.
EEG retains volume dominance. Neurostimulation gains share fastest through premium reimbursement capture.
End User:
Clinics concentrate purchasing power through reimbursement access, while home users expand addressable market through price-accessible hardware.
- Clinics:Psychiatric and neurological service providers procure integrated hardware-software systems for reimbursed therapeutic protocols. Neurocare Group AG's European channel dominance reflects procurement consolidation around vendors with pre-cleared EU MDR technical documentation.
- Home Users:Consumer-directed purchase of meditation and cognitive training devices bypasses clinical gatekeeping. Muse's headband positioning competes on price accessibility against clinical-grade alternatives in German direct-to-consumer channels.
- Research Institutions:University laboratories demand open API access and raw signal export for protocol customization. Emotiv's polymer composite hardware-plus-subscription model serves this segment across Berlin, Heidelberg, and Munich neuroscience departments.
- Fitness Centers:Corporate wellness and performance optimization programs adopt consumer-tier devices for member retention. Implementation concentrates in metropolitan clusters with employer-sponsored cognitive performance benefits.
Clinics anchor revenue stability. Home Users represent the steepest expansion trajectory as hardware-software bundling collapses price barriers.
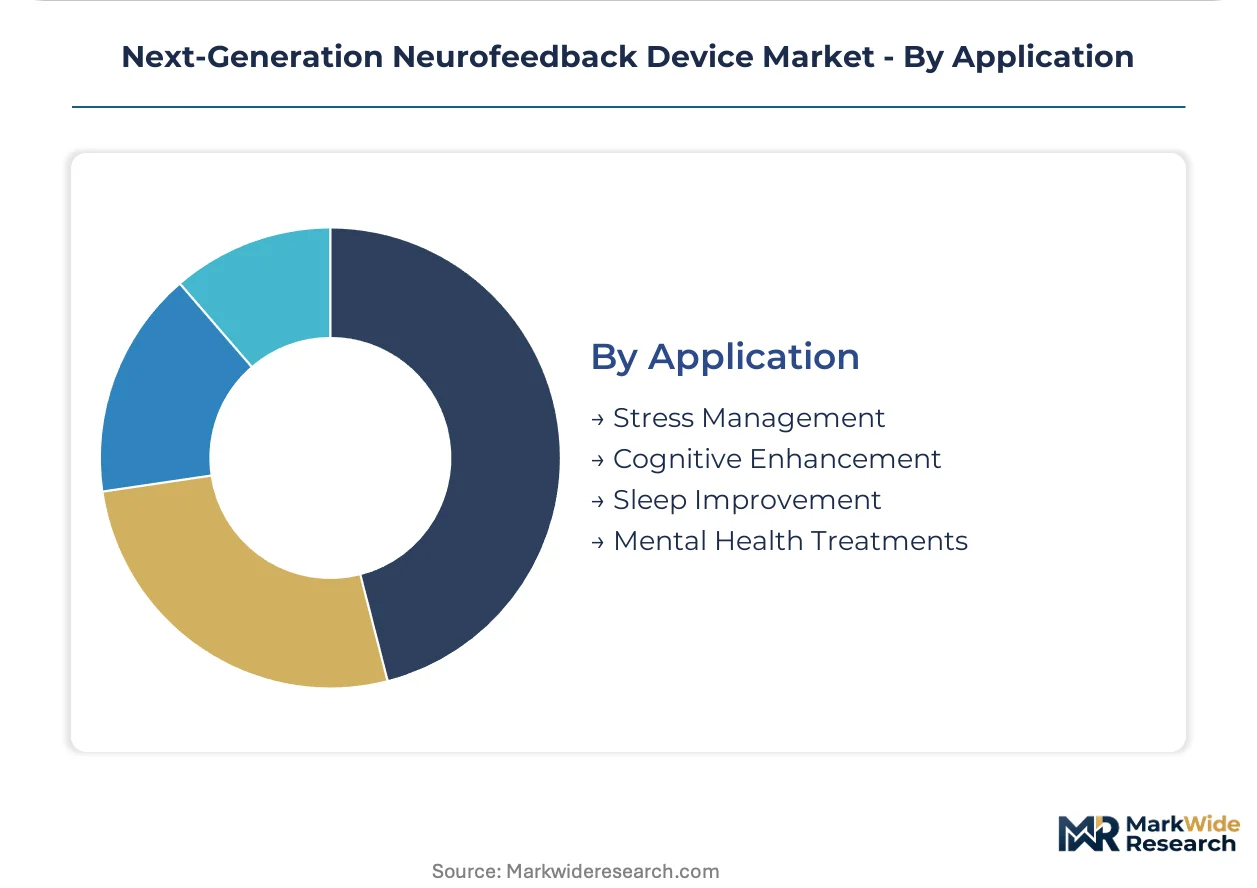
Application:
Mental health treatments concentrate regulatory investment and reimbursement validation, while cognitive enhancement occupies unregulated wellness positioning.
- Mental Health Treatments:ADHD, anxiety, and depression protocols require clinical evidence packages for FDA and EMA digital therapeutic classification. Germany's DiGA fast-track pathway creates reimbursement precedent for attention-deficit applications with limited pharmaceutical alternatives.
- Stress Management:Real-time physiological downregulation training targets corporate wellness and clinical burnout prevention. Munich and Frankfurt employer programs drive B2B channel development outside statutory insurance frameworks.
- Sleep Improvement:Slow-wave enhancement and insomnia protocols leverage consumer hardware accessibility. Meditation-focused wearables compete on price against clinical polysomnography alternatives.
- Cognitive Enhancement:Working memory and attention training for healthy populations operates in unregulated wellness territory. Research institutions in Heidelberg validate protocols that later migrate to consumer subscription models.
Mental Health Treatments command margin premiums through reimbursement. Stress Management scales fastest through employer-channel bypass of clinical complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's neuropsychiatry research cluster anchors European demand for next-generation neurofeedback hardware, with reimbursement pilots validating clinical deployment models that manufacturers replicate across North American and Asia-Pacific markets.
Germany
Statutory health insurance DiGA fast-track pathways for digital therapeutics drive prescription-channel adoption of EEG-based attention-deficit protocols. The Federal Institute for Drugs and Medical Devices oversees software-as-medical-device classification under EU MDR requirements. Berlin-Brandenburg university hospitals pilot graphene-enhanced dry electrode arrays for ambulatory psychiatric monitoring.
United States
FDA breakthrough device designation compresses regulatory timelines for neurostimulation platforms targeting treatment-resistant depression. The Center for Devices and Radiological Health maintains predicate device evidentiary standards for active implantable modalities. Academic medical centers in Boston and San Francisco anchor clinical trial recruitment for digital therapeutic validation.
China
National Health Commission pilot programs for non-pharmaceutical mental health interventions expand addressable clinical channels. The National Medical Products Administration classifies software-driven neurofeedback under revised medical device registration pathways. Shanghai and Shenzhen manufacturing clusters supply polymer composite electrode substrates to regional device assemblers.
Japan
Ministry of Health, Labour and Welfare reimbursement codes for cognitive rehabilitation devices validate BCI integration with stroke recovery protocols. The Pharmaceuticals and Medical Devices Agency imposes clinical evidence requirements on algorithm-driven feedback systems. Tokyo and Osaka neuroscience departments drive demand for open-API research platforms with raw signal export capabilities.
United Kingdom
NHS England digital therapeutics procurement frameworks create centralized purchasing channels for ISO 13485-certified vendors. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-EU withdrawal. London and Cambridge research institutions concentrate demand for cloud-based telemetry systems serving multi-site clinic networks.
Next-Generation Neurofeedback Device Market Competitive Landscape
Global majors compete with regional champions across regulatory clearance capabilities, with FDA and EU MDR certification separating reimbursed clinical vendors from wellness-channel competitors. The vendor base stratifies into three tiers: integrated clinic solution providers, consumer hardware-software bundlers, and research-platform specialists. Dominant competitive moves include strategic partnerships with university hospital networks and portfolio diversification across wearable and implantable form factors.
Within the integrated clinic solution tier, Neurocare Group AG exemplifies European channel dominance through psychiatric service network relationships. Among research-platform specialists, Emotiv occupies a position serving Berlin, Heidelberg, and Munich neuroscience departments with hardware-plus-subscription models. On the consumer-accessibility vector, Muse anchors price-competitive positioning against clinical-grade alternatives in direct-to-consumer channels.
| Leading Market Players |
|---|
| BrainMaster Technologies, Inc |
| Emotiv |
| Muse |
| NeuroSky |
| Neurocare Group AG |
| Thought Technology Ltd |
| Myndlift Ltd |
| Mitsar Co. Ltd |
| Narbis |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up clinic solution providers anchor supply consolidation across European psychiatric service channels, compressing procurement leverage into fewer vendor relationships while enforcing ISO 13485 certification as a pricing floor for reimbursed clinical tiers.
Pricing Analysis
Silver and gold flake pass-through volatility in high-fidelity sensor arrays compresses hardware margins most acutely in consumer-tier headbands, where Muse and direct-to-consumer competitors face acute price sensitivity. Pricing stratifies across FDA breakthrough-designated neurostimulation platforms, EU MDR-cleared clinic systems, and unregulated wellness wearables, with certification grade commanding the steepest premiums. Cost compression in graphene-enhanced dry electrode manufacturing is intensifying as Chinese substrate suppliers scale polymer composite production. Research institutions exhibit the least price sensitivity due to grant-funded procurement protocols.
Supply Chain Analysis
Regional distribution centers in Munich, Berlin, and Hamburg aggregate finished devices for German statutory health insurance channels, with hub-and-spoke patterns extending into Nordic and Benelux markets. Manufacturing concentrates in China for polymer composite electrodes, Germany for precision sensor assembly, and the United States for FDA-cleared neurostimulation platforms. Supply chains draw from silver and gold commodity markets, semiconductor components for edge AI processing, and medical-grade polymers for biocompatible housings. Single-source vulnerability in graphene substrate supply from Shenzhen-based producers exposes lead times to export licensing delays. Distribution runs through hospital procurement networks, direct-to-consumer e-commerce, and research equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as German DiGA reimbursement pilots shift demand toward clinically validated platforms with EU MDR technical documentation over unverified wellness alternatives.
For Market Incumbents: Anticipate margin compression from graphene-enhanced dry electrode commoditization by deepening backward integration into polymer composite substrate production. Defend clinic channel control through exclusive hospital information system integration contracts that extend implementation cycles beyond 12 months. Prioritize FDA breakthrough pathway submissions for neurostimulation modalities to maintain predicate device barriers against emerging entrants. For New Entrants and Emerging Players: Launch via direct-to-employer wellness channels in Munich and Frankfurt corporate clusters, bypassing clinical reimbursement complexity while capturing productivity-linked value propositions. Target pediatric ADHD applications through Germany's DiGA fast-track pathway, where pharmaceutical alternatives remain limited and statutory insurance coverage creates immediate addressable demand. Pursue white-label manufacturing partnerships with Shenzhen electrode substrate specialists to collapse hardware development timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among ISO 13485-certified software platform vendors with pre-cleared EU MDR quality management systems and stalled revenue recognition due to legacy EMR integration friction. Long-term viability across the analysis window hinges on reimbursement code expansion for digital therapeutics in German and US markets. Monitor FDA breakthrough device designation grants to neurostimulation platforms as the decisive inflection signal separating scalable clinical deployment from confined wellness positioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compresses regulatory timelines for EEG-based depression platforms in Boston academic medical centers. |
| EU MDR Technical Documentation | Enables bundled reimbursement with physical therapy in Berlin and Munich hospital networks. |
| Hospital System Partnership | Secures 12-18 month EMR integration contracts that delay competitor revenue recognition. |
| Software Companion Development | Supports DiGA fast-track pathway requirements for ongoing therapeutic relationship documentation. |
| Graphene Electrode Supply Agreement | Locks in polymer composite substrate access from Shenzhen manufacturing clusters. |
Research Methodology
Direct dialogue with neurofeedback device product managers, hospital procurement committee chairs, biomedical engineers at university hospitals, and GPO contracts managers grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) and breakthrough device filings, EU MDR notified body documentation, German BfArM DiGA registry entries, and CMS Medicare reimbursement code databases. Bottom-up unit economics triangulated against top-down market sizing across hardware, software, and service revenue pools.
Segment-level outputs across the analysis window reflect modeled trajectories for wearable devices, brain-computer interfaces, mobile applications, and software platforms, further disaggregated by EEG, neurostimulation, fMRI, and biofeedback sensor technologies. CAGRs emerged from regression analysis against reimbursement code expansion rates, regulatory clearance velocity, and graphene electrode cost curves. Forecast inputs incorporated statutory health insurance pilot program enrollment caps, FDA breakthrough designation approval timelines, and electrophysiologist training pipeline constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR classification delays, FDA predicate device evidentiary standard shifts, or graphene export restrictions from Chinese manufacturing clusters. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Dermal Allograft Market
Medical Devices
Cryoablation Devices Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Biliary Catheters Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Global Medical Composite Market
Medical Devices
Global Capnography Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Global Embolization Particle Market
Medical Devices
Embolic Protection Systems Market
Medical Devices
Active Implantable Devices Market