
 Barrier Materials Market | 2026-2036
Barrier Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Materials Market Intelligence
Pharmaceutical end users is collapsing into food and beverage buyers as the primary volume anchor for barrier material suppliers. Amcor plc leverages its integrated film and flexible packaging platform to capture pharmaceutical-grade barrier polymer demand across North American and European manufacturing corridors. Kuraray Co., Ltd. sustains dominance in ethylene vinyl alcohol copolymer resin supply through captive polymerization assets in Japan and Belgium. The Dow Chemical Company anchors its position via ionomer and tie-layer chemistry leadership in multilayer barrier structures for retort and aseptic applications.
Barrier materials are engineered substrates engineered to impede the transmission of gases, moisture, light, or aromas through controlled molecular density, typically achieving oxygen transmission rates below 0.1 cc/m²/day in high-performance polymer grades. Their primary industrial purpose centers on extending shelf stability, preserving active ingredient potency, and preventing sensory degradation in packaged goods, electronics encapsulation, and building envelope systems. Polymer-based barrier films command the largest value share due to tunable permeability and thermoformability, while glass and metal variants retain structural importance in pharmaceutical vial and vacuum insulation panel applications where near-zero permeability is non-negotiable. Films and laminates represent the fastest-growing form category as downgauging trends and coextrusion advances enable thinner structures without performance loss.
FDA enforces strict extractables and leachables testing protocols for pharmaceutical-contact barrier materials under container closure system guidelines, directly elevating qualification costs for new resin platforms entering drug packaging. The EU Green Deal and REACH chemical registration requirements are forcing reformulation of legacy halogenated and phthalate-based barrier additives across European converter operations. EMA's evolving standards for primary packaging integrity create persistent compliance obligations that favor established suppliers with documented regulatory dossiers. Stakeholders must monitor accelerating regulatory divergence between US and European sustainability mandates as a decisive factor in regional capacity allocation and product platform prioritization.
Market Dynamics
Coextrusion line investments by German and Japanese converters are compressing lead times for pharmaceutical-grade barrier laminates while tightening qualification windows for new resin entrants under EMA serialization mandates.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization deadlines for pharmaceutical blister packs are pulling high-barrier polymer volumes into Central European converter networks.
- Downgauging coextrusion:Advances in multilayer film architecture enable thinner oxygen barrier structures without transmission rate degradation.
- Retort pouch expansion:Food processors in Southeast Asia are adopting ethylene vinyl alcohol copolymer laminates for shelf-stable protein packaging.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Captive polymerization assets in Japan and Belgium limit second-source options for European converters.
- Extractables testing burden:FDA container closure system protocols extend qualification timelines for new pharmaceutical-contact materials.
- Halogenated additive phase-out:REACH registration requirements are forcing reformulation of legacy barrier chemistries mid-contract.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO serialization mandates are creating first-mover openings for qualified barrier film suppliers in Mumbai-Pune corridor.
- Aseptic beverage cartons:Ionomer tie-layer demand is expanding beyond dairy into plant-based protein drinks.
- US Inflation Reduction Act:Domestic content incentives for pharmaceutical manufacturing are reshoring barrier film specification authority.
Industry Challenges
- Multilayer recycling incompatibility:Post-industrial scrap from five-to-seven-layer barrier structures lacks viable mechanical reprocessing streams.
- Regulatory dossier compilation:EMA primary packaging integrity documentation requires 18-24 month lead times for new resin platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Materials Market |
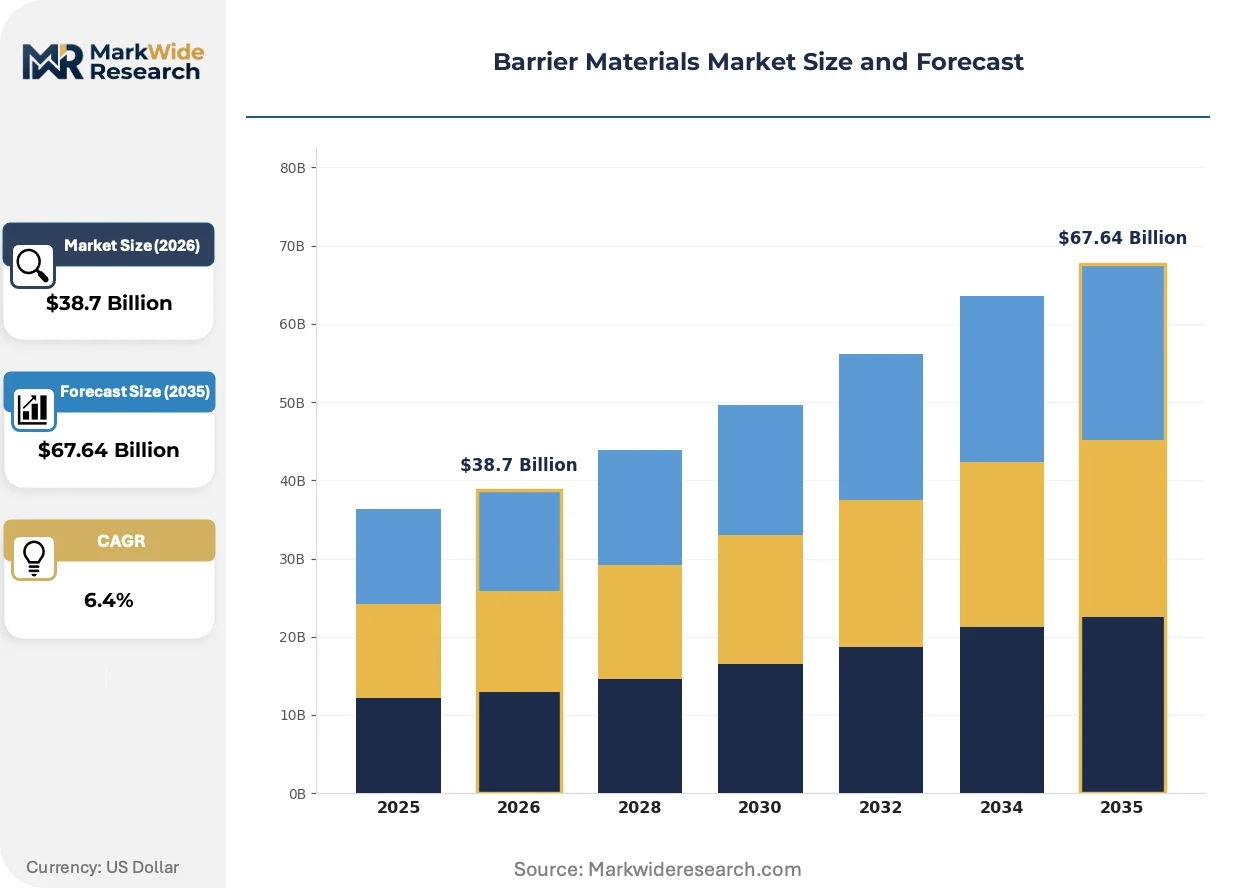
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
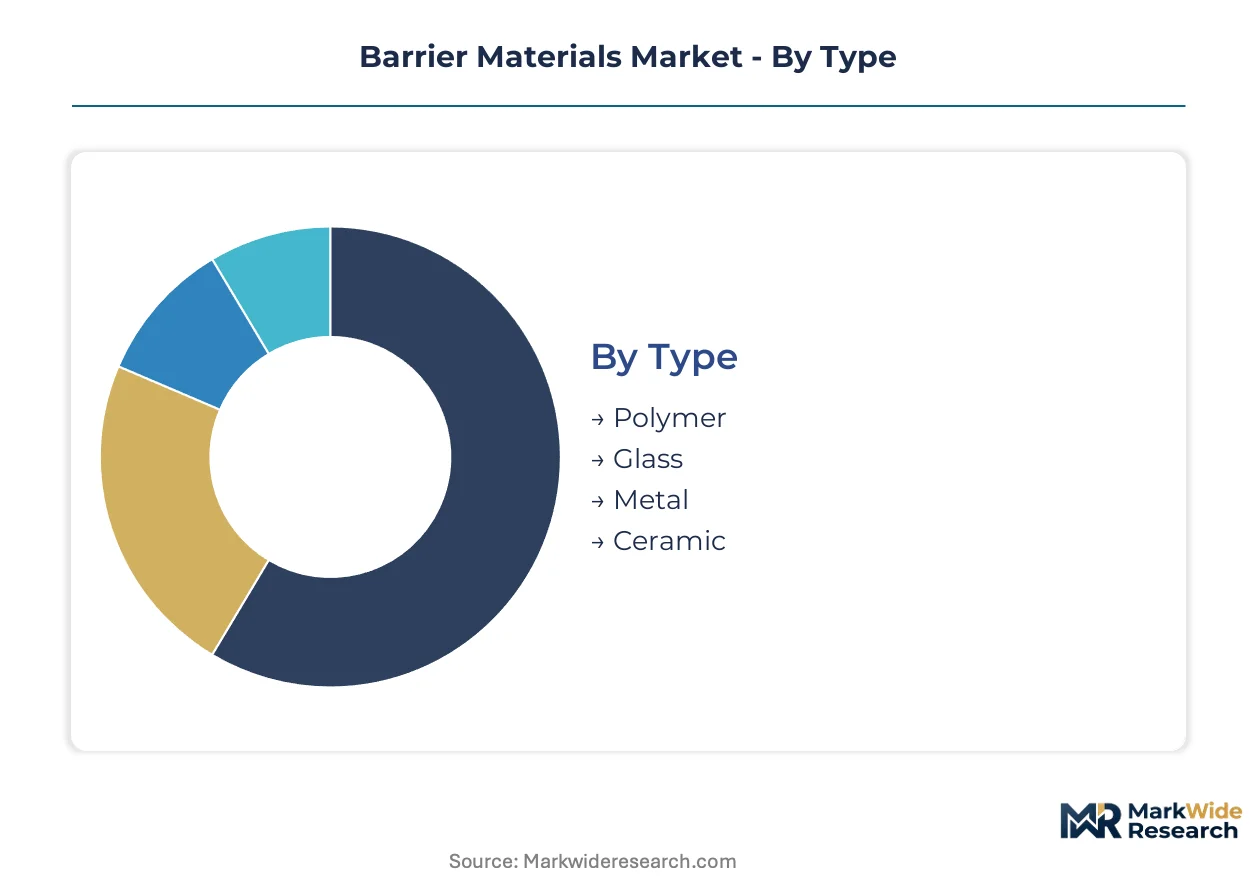
| Segmentation | Type: Polymer, Glass, Metal, Ceramic Application: Packaging, Electronics, Construction, Automotive Form: Films, Coatings, Sheets, Laminates End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Industrial |
| Companies Covered | Amcor plc, KURARAY CO., LTD., Syensqo, Mondi, Huhtamäki Oyj, Asahi Kasei Corporation, The Dow Chemical Company, Solvay SA, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Materials Market Strategic Shifts & Innovations
Barrier material development is pivoting from incremental permeability reduction toward circular-design architectures and digital supply chain integration.
Plasma-enhanced chemical vapor deposition of silicon oxide coatings onto polyethylene terephthalate substrates is supplanting metallized film layers in microwaveable retort applications. Japanese food processors are specifying these transparent barriers for premium ready-meal lines. The shift is compressing aluminum foil laminate demand while opening specification windows for regional coating equipment suppliers.
EMA's evolving primary packaging integrity standards are forcing drug manufacturers to revalidate legacy barrier structures ahead of renewal cycles. Converter operations in Germany and Switzerland are absorbing the compliance burden through dedicated regulatory affairs teams. The revalidation wave favors incumbent suppliers with decade-long extractables databases over new resin entrants.
Consolidated buying desks at North American pharmaceutical contract packagers are compressing supplier rosters from six to three qualified barrier film sources per therapeutic category. Volume commitments now bundle annual film tonnage across multiple drug SKUs. The concentration is most visible in New Jersey and Pennsylvania corridor operations serving generic oral solid dose markets.
Barrier Materials Market Segmentation
Barrier material suppliers configure product portfolios around permeability specifications and thermoforming requirements that vary sharply across pharmaceutical serialization mandates and retort packaging lines. Segmentation discipline separates commodity film converters from qualified drug-contact suppliers with extractables documentation.
Type:
Polymer-based barriers face substitution pressure from metallized films in microwaveable retort applications, while ceramic alternatives displace glass in vacuum insulation panels.
- Polymer:Ethylene vinyl alcohol copolymers and ionomer tie-layers dominate oxygen transmission specifications below 0.1 cc/m²/day. German converter networks pull high-barrier polymer volumes into Central European pharmaceutical packaging corridors under EMA serialization mandates.
- Glass:Borosilicate and soda-lime formulations deliver near-zero permeability for parenteral drug vials and ampoules. Swissmedic documentation requirements in Switzerland and adjacent markets sustain premium positioning against polymer alternatives.
- Metal:Aluminum foil laminates and metallized polyester retain structural importance in vacuum insulation panels and pharmaceutical cold-chain packaging.
- Ceramic:Silicon oxide coatings via plasma-enhanced chemical vapor deposition supplant metallized layers in Japanese premium ready-meal specifications.
Polymer retains volume leadership; ceramic holds the steepest expansion curve.
Application:
Packaging applications stratify across cost tiers from commodity food wrap to qualified pharmaceutical-contact structures with 18-24 month regulatory dossier timelines.
- Packaging:Multilayer coextrusion for retort pouches and aseptic cartons commands the largest value share. Southeast Asian food processors specify ethylene vinyl alcohol laminates for shelf-stable protein formats.
- Electronics:Moisture barrier films for OLED encapsulation and semiconductor wafer shipping require water vapor transmission rates below 0.001 g/m²/day.
- Construction:Vacuum insulation panels with glass fiber cores and metallized polymer barriers address thermal bridging in European building envelope retrofits under EU Green Deal efficiency targets.
- Automotive:Fuel vapor barrier layers in multilayer fuel tanks and battery pack encapsulation films respond to electric vehicle thermal runaway protection standards.
Packaging dominates absolute tonnage; electronics claims the highest value-per-kilogram realization.
Form:
Film and laminate formats concentrate supply in German and Japanese converter corridors, while coating technologies fragment across regional equipment suppliers.
- Films:Biaxially oriented polyethylene terephthalate and polyamide substrates serve as base layers for metallization and coextrusion. Downgauging trends enable thinner structures without oxygen barrier degradation.
- Laminates:Five-to-seven-layer coextruded structures combine polyolefin sealants with ethylene vinyl alcohol or polyvinylidene chloride barrier cores. Post-industrial scrap from these structures lacks viable mechanical reprocessing streams.
- Coatings:Silicon oxide and aluminum oxide vapor-deposited layers provide transparent microwaveable barriers.
- Sheets:Thermoformable multilayer structures for pharmaceutical blister packs and medical device trays.
Laminates absorb the majority of pharmaceutical qualification expenditure; films expand most quickly in downgauged food packaging.
End User:
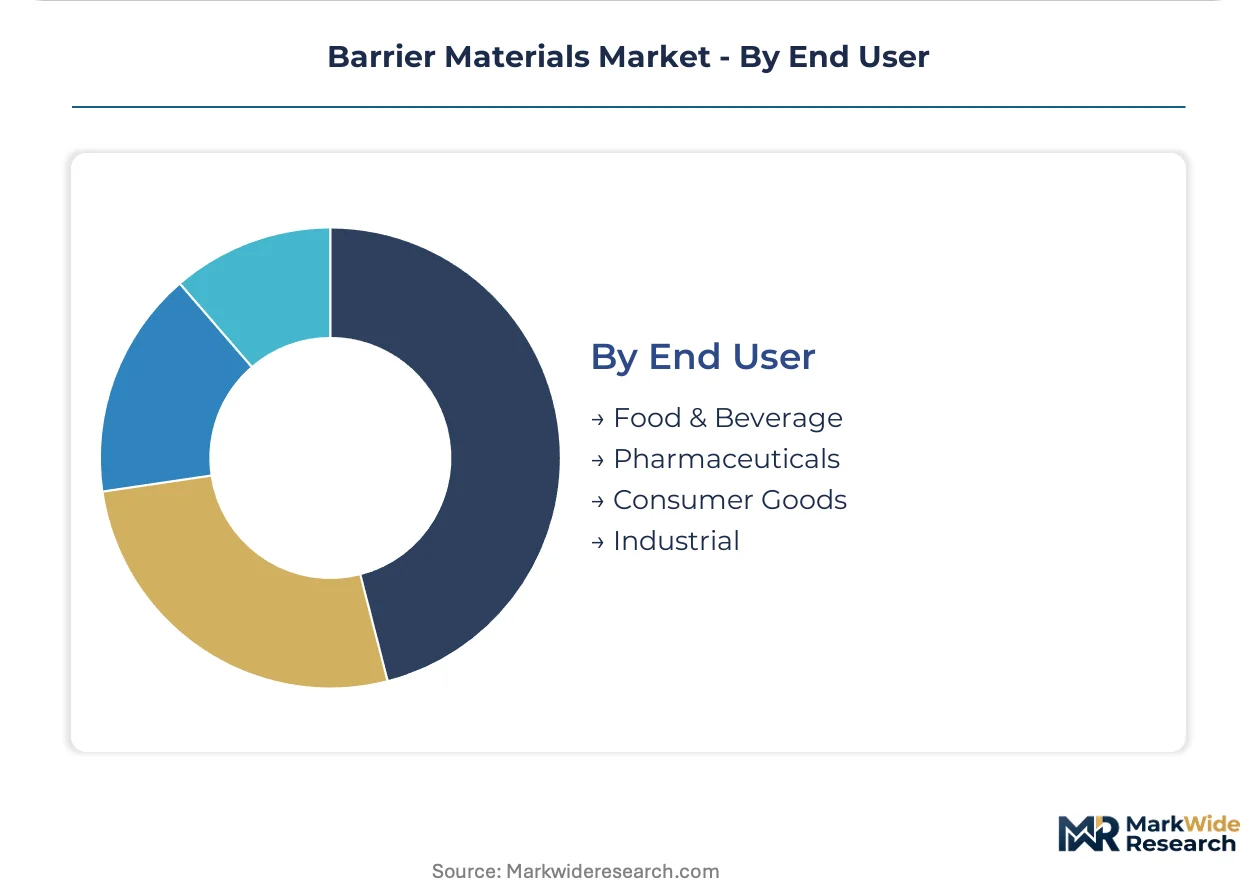
Pharmaceutical buyers impose the steepest compliance burden, while food and beverage purchasers drive volume scale across converter operations.
- Pharmaceuticals:Blister pack laminates and container closure systems require FDA extractables and leachables testing under container closure system guidelines. Consolidated buying desks at New Jersey and Pennsylvania contract packagers compress supplier rosters from six to three qualified sources per therapeutic category.
- Food & Beverage:Retort pouch and aseptic carton specifications dominate ionomer tie-layer demand. Japanese food processors specify plasma-coated transparent barriers for premium ready-meal lines.
- Consumer Goods:Aroma barrier films for coffee and personal care packaging.
- Industrial:Chemical drum liners and agricultural fumigation barriers.
Food & Beverage anchors volume throughput; Pharmaceuticals commands the tightest qualification windows and margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier film manufacturing clusters in Germany and Japan supply pharmaceutical-grade laminates to converter networks across their respective continents. Converter operations concentrate near regulatory agencies to compress qualification timelines for drug-contact materials.
United States
FDA container closure system guidelines drive extractables testing expenditure for blister pack laminates. The Inflation Reduction Act's domestic content incentives reshore specification authority for pharmaceutical barrier films. New Jersey and Pennsylvania contract packagers consolidate supplier rosters from six to three qualified sources per therapeutic category.
Germany
EMA serialization mandates under the Falsified Medicines Directive pull high-barrier polymer volumes into Central European converter corridors. REACH chemical registration requirements force reformulation of legacy halogenated barrier additives. Advanced converter networks in Baden-Württemberg and North Rhine-Westphalia supply film laminates to drug packaging operations across the continent.
Japan
METI efficiency standards accelerate plasma-enhanced chemical vapor deposition adoption for transparent microwaveable barriers. PMDA pharmaceutical packaging regulations sustain premium positioning for domestic resin suppliers. Food processors in the Kanto region specify silicon oxide-coated polyethylene terephthalate for premium ready-meal lines.
India
CDSCO serialization mandates create first-mover openings for qualified barrier film suppliers in the Mumbai-Pune corridor. The PLI scheme for pharmaceuticals incentivizes domestic packaging material qualification. Converter investments in Maharashtra target export supply to regulated European and North American drug markets.
China
NMPA evolving standards for primary packaging integrity extend dossier timelines for imported barrier structures. Dual carbon goals pressure reformulation of multilayer films with limited mechanical reprocessing streams. Yangtze River Delta coextrusion lines supply downgauged barrier films for regional food and electronics packaging.
Barrier Materials Market Key Industry Players
Concentration sits with integrated polymer producers and specialized film converters that control captive resin supply and regulatory dossier libraries. The market structure divides between multinational chemical conglomerates with polymerization assets and regional converter specialists with qualification expertise. Two archetypes dominate: resin-integrated suppliers leveraging backward integration into ethylene vinyl alcohol copolymer production, and converter specialists bundling regulatory documentation services. Competitive moves center on coextrusion line investments to compress pharmaceutical lead times and dedicated regulatory affairs teams to absorb EMA revalidation burdens.
Within the integrated chemical tier, Amcor plc and The Dow Chemical Company exemplify archetypes combining polymer chemistry leadership with flexible packaging platforms. Kuraray Co., Ltd. occupies a distinct position as a resin-specialist with captive polymerization assets in Japan and Belgium. These three anchors demonstrate how supply-side concentration in barrier polymer production creates qualification barriers for second-source entrants.
| Leading Market Players |
|---|
| Amcor plc |
| KURARAY CO., LTD. |
| Syensqo |
| Mondi |
| Huhtamäki Oyj |
| Asahi Kasei Corporation |
| The Dow Chemical Company |
| Solvay SA |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Captive ethylene vinyl alcohol polymerization assets in Japan and Belgium compress unit economics for qualified barrier resin, concentrating pricing power with integrated producers while forcing converter margins toward volume-scaled efficiency floors. This scale concentration elevates qualification costs as a competitive moat, entrenching incumbent positions across pharmaceutical-grade laminates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical-contact grades from food-grade barrier films and commodity downgauged packaging. Price differentiation hinges on extractables documentation depth and EMA regulatory dossier completeness, with contract packagers in New Jersey and Pennsylvania corridors exhibiting acute price sensitivity on generic oral solid dose volumes. Pricing pressure stems from REACH-mandated halogenated additive reformulation, forcing mid-contract cost absorption by European converters. Pharmaceutical buyers show least price sensitivity due to serialization compliance deadlines, while Southeast Asian food processors drive hard volume negotiations on retouch pouch specifications.
Supply Chain Analysis
Kurashiki Strait maritime corridors and Antwerp-Rotterdam port complexes constitute chokepoints for ethylene vinyl alcohol resin flows into Central European converter networks. Geographic supply concentration centers on Japan, Belgium, and Germany, with raw material dependencies spanning vinyl acetate monomer, ethylene feedstocks, and ionomer precursor resins. Single-source vulnerability pervades pharmaceutical-grade laminate supply, as EMA qualification windows forestall second-source substitution. Distribution runs through converter-operated slitting and metallization facilities positioned adjacent to drug packaging corridors in Baden-Württemberg and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as CDSCO serialization mandates in India and reshoring incentives under the US Inflation Reduction Act splinter specification authority away from entrenched European converter networks.
For Market Incumbents: Compound regulatory dossier depth by dedicating regional affairs teams to EMA revalidation waves, absorbing compliance burdens that strain new resin entrants. Anchor capacity expansion in Maharashtra's Mumbai-Pune corridor to intercept CDSCO-driven pharmaceutical packaging demand before qualification windows close. Prioritize captive polymerization investments over toll manufacturing arrangements to defend margin position against ionomer tie-layer substitution threats. For New Entrants and Emerging Players: Anchor in Indian pharmaceutical packaging corridors where PLI scheme incentives and nascent CDSCO enforcement create first-mover qualification opportunities ahead of European incumbent relocation. Target aseptic beverage carton specifications for plant-based protein drinks, a segment where ionomer tie-layer demand outpaces established supply relationships. Pursue coextrusion equipment partnerships with regional converters rather than greenfield resin polymerization to compress capital intensity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converter specialists with regulatory documentation libraries over resin-integrated conglomerates facing halogenated additive reformulation headwinds. Long-term viability rests on extractables database depth and EMA relationship tenure rather than polymer chemistry scale. Acquisition target archetype: mid-cap German or Swiss converters with decade-long pharmaceutical dossier histories. Watch for plasma-enhanced chemical vapor deposition equipment adoption rates in Japanese food processing as inflection indicator for metallized film displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Polymerization | Captive resin supply secures qualification priority under EMA serialization mandates. |
| Coextrusion Line Investment in Maharashtra | Proximity to CDSCO-regulated pharmaceutical corridors compresses lead times for Indian market entry. |
| Plasma Coating Technology Licensing | Silicon oxide deposition capabilities open Japanese premium ready-meal specification windows. |
| Long-term Supply Agreement with Contract Packagers | Volume commitments across multiple drug SKUs lock supplier roster positions in New Jersey corridor. |
| Regulatory Affairs Team Expansion | Dedicated EMA documentation capacity absorbs 18-24 month revalidation burdens for incumbent advantage. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with polymer plant managers, pharmaceutical procurement leads at contract packagers, converter operations directors, and EMA regulatory affairs specialists; and secondary validation against customs trade records, SEC 10-K filings, REACH registration databases, and FDA container closure system guidance documents. Bottom-up resin production estimates and top-down packaging demand aggregation were triangulated against import-export flows through Antwerp-Rotterdam and Kobe-Osaka corridors.
Across the projection horizon, the analytical framework modeled barrier material demand through segmentation dimensions spanning polymer grade tier, end-use industry, packaging form factor, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted penetration curves and substitution rate modeling for metallized versus ceramic-coated alternatives. Forecast inputs incorporated EMA serialization mandate compliance deadlines and METI efficiency standard adoption trajectories for transparent microwaveable barriers.
Underlying assumptions cover sustained REACH enforcement intensity and CDSCO regulatory alignment with European serialization standards, with deviation risk concentrated in halogenated additive phase-out timelines and multilayer recycling infrastructure development. Practitioners should keep alternative scenarios live as EU Green Deal packaging waste directives and US domestic content incentive implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
Barrier Foil Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Global High Barrier Packaging Films Market