
 Flexible Barrier Films for Electronics Market | 2026-2036
Flexible Barrier Films for Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Barrier Films for Electronics Market Foresight
OEM-direct supply chains for flexible OLED panel production is reconfiguring procurement relationships across the barrier film value chain. 3M Company leverages its multi-layer adhesive-coating portfolio to anchor high-barrier specifications for foldable display laminates. Toppan Printing Co., Ltd. sustains dominance in metallized film roll goods through precision vacuum deposition lines serving Korean display fabs. DuPont competes on polyimide-based thermal stability, occupying the premium tier where semiconductor packaging applications require sustained performance above 300°C.
Flexible barrier films for electronics are multi-layer polymer or metal-polymer laminates engineered to block oxygen and water vapor transmission below 10⁻⁶ g/m²/day, typically constructed through sequential vacuum deposition of aluminum oxide or silicon oxide onto polyethylene terephthalate or polyimide substrates. Their primary purpose is to encapsulate moisture-sensitive organic and thin-film electronic components against ambient degradation. Polyethylene terephthalate films lead volume due to mature extrusion infrastructure and cost-scaling advantages in solar cell backsheets and standard flexible printed electronics. Polyimide films represent the fastest-expanding category, as thermal and mechanical resilience requirements from automotive electronics suppliers and wearable device producers push specifications beyond polyethylene terephthalate limits. Vacuum deposition technology commands the highest value-added segment, since atomic-layer precision in barrier layer deposition directly determines device lifetime in flexible displays.
EPA regulations on per- and polyfluoroalkyl substance emissions constrain fluorinated barrier chemistries in US-based manufacturing, while REACH restrictions on organotin catalysts reshape formulation choices for European coating operations. FDA indirect food-contact standards additionally influence barrier film selection for wearable devices with skin-contact interfaces. Stakeholders must monitor divergence between Asian specification standards and Western chemical compliance regimes when situating new metallization capacity.
Market Dynamics
OLED panel manufacturers in South Korea and China are consolidating procurement around ultra-high-barrier specifications, forcing substrate suppliers to co-locate metallization capacity within 500 kilometers of display fabrication clusters.
Growth Catalysts
- Foldable Display Adoption:Korean and Chinese smartphone OEMs are scaling orders for multi-layer barrier laminates capable of withstanding 200,000+ bend cycles.
- Automotive Electronics Thermal Requirements:Polyimide-based barrier films are penetrating in-cabin flexible sensor applications where sustained operation above 150°C is mandatory.
- EPA Per- and Polyfluoroalkyl Substance Restrictions:US-based manufacturers are accelerating migration to non-fluorinated barrier chemistries, creating specification pull for silicon oxide-aluminum oxide hybrid deposition systems.
Market Restraints
- Aluminum Oxide Precursor Volatility:Trimethylaluminum supply concentrates among three global chemical suppliers, exposing barrier film coaters to input cost swings.
- East Asian Metallization Concentration:Precision vacuum deposition equipment and operational expertise cluster in South Korea, Japan, and Taiwan, limiting geographic diversification options.
- Water Vapor Transmission Rate Floor:Current atomic layer deposition processes struggle to reliably achieve below 10⁻⁶ g/m²/day at roll-to-roll production speeds.
Strategic Opportunities
- Indian Electronics Manufacturing:Production-linked incentive schemes for semiconductor and display fabrication are attracting barrier film suppliers to establish local metallization partnerships.
- Wearable Medical Patches:FDA biocompatibility pathways for skin-contact electronics are opening specification windows for ultra-thin polyimide barriers with moisture-blocking properties.
- Organic Photovoltaic Integration:Tandem cell architectures combining perovskite and silicon layers require flexible encapsulation with UV stability beyond current polyethylene terephthalate limits.
Industry Challenges
- Atomic Layer Deposition Technician Scarcity:The specialized workforce capable of calibrating plasma-enhanced deposition systems for sub-nanometer precision remains concentrated in East Asian equipment hubs.
- REACH Pre-Registration Timelines:European coating operations face 18-24 month certification cycles for novel organotin-free catalyst formulations, delaying formulation updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Barrier Films for Electronics Market |
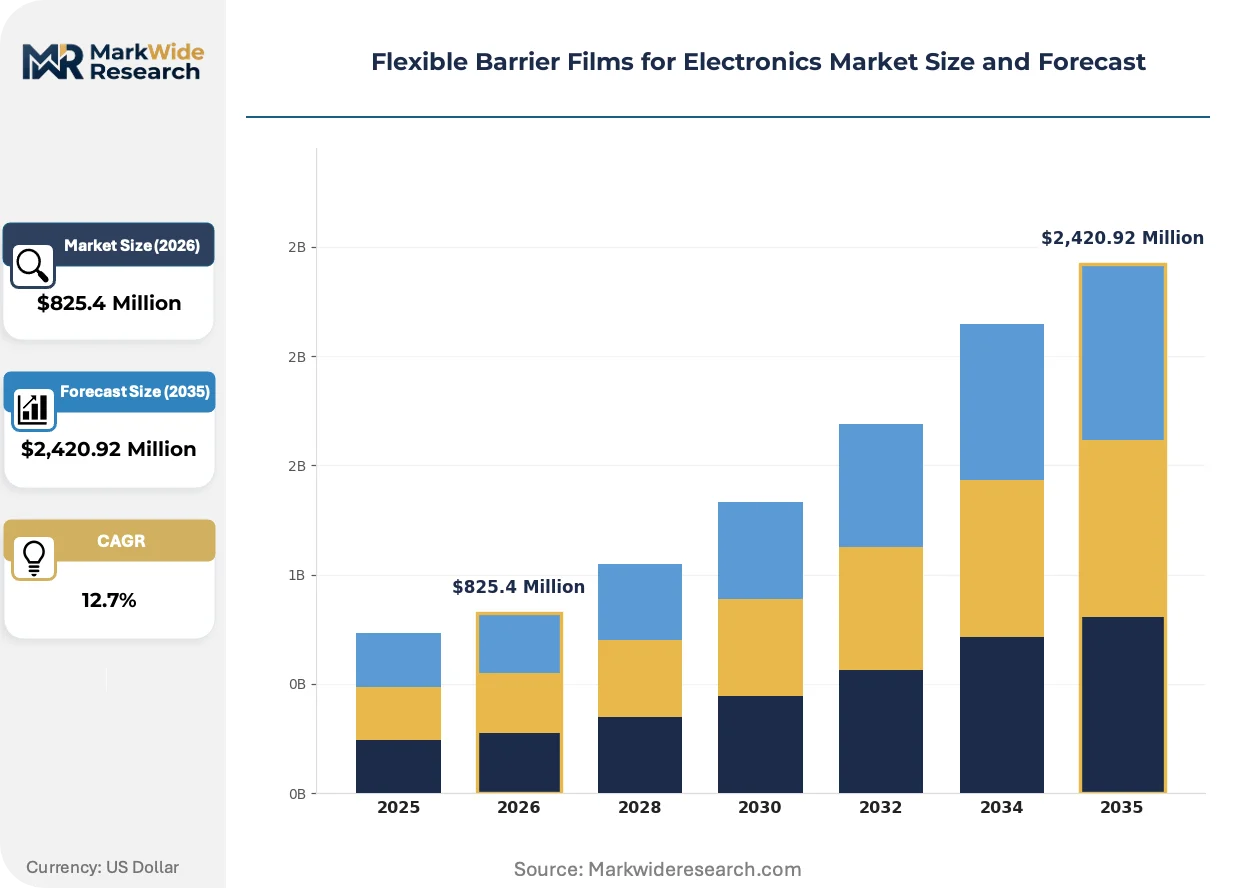
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $2,420.92 Million |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, Polyvinylidene Chloride, Aluminum Foil, Metalized Films, Polyimide Films Application: Flexible Displays, Printed Circuit Boards, Solar Cells, Sensor Protection, Flexible Printed Electronics Technology: Coating, Lamination, Extrusion, Metallization, Vacuum Deposition End User: Consumer Electronics Manufacturers, Semiconductor Fabricators, Automotive Electronics Suppliers, Wearable Device Producers |
| Companies Covered | 3M Company, Amcor Plc, Toppan Printing Co., Ltd., Honeywell International Inc., Eastman Chemical Company, Tera-Barrier Films Pte Ltd, DuPont, Materion Corporation, Beneq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Barrier Films for Electronics Market Shifts & Advancements
Barrier film technology is fragmenting along performance-versus-cost axes as end-use applications diverge between premium foldable displays and cost-sensitive solar encapsulation.
Atomic layer deposition is migrating from batch wafer processing to continuous roll-to-roll configurations. Korean display fabs are piloting 1.5-meter-wide deposition drums capable of 50 meters per minute throughput. This equipment transition is compressing capital recovery timelines for metallization suppliers while raising quality control complexity.
REACH restrictions on organotin catalysts are forcing European coating operations to reformulate polyurethane adhesive layers. Industrial consequence includes qualification delays for new laminate constructions and accelerated partnerships with Japanese catalyst suppliers. Automotive electronics suppliers in Germany face the tightest compliance windows.
Direct OEM contracting is displacing distributor-mediated procurement for high-specification barrier films. Korean OLED panel manufacturers now require substrate suppliers to embed quality engineers at fabrication facilities. This channel compression is most visible in Gyeonggi Province display clusters where three OEMs account for majority barrier film specification authority.
Flexible Barrier Films for Electronics Market Segmentation
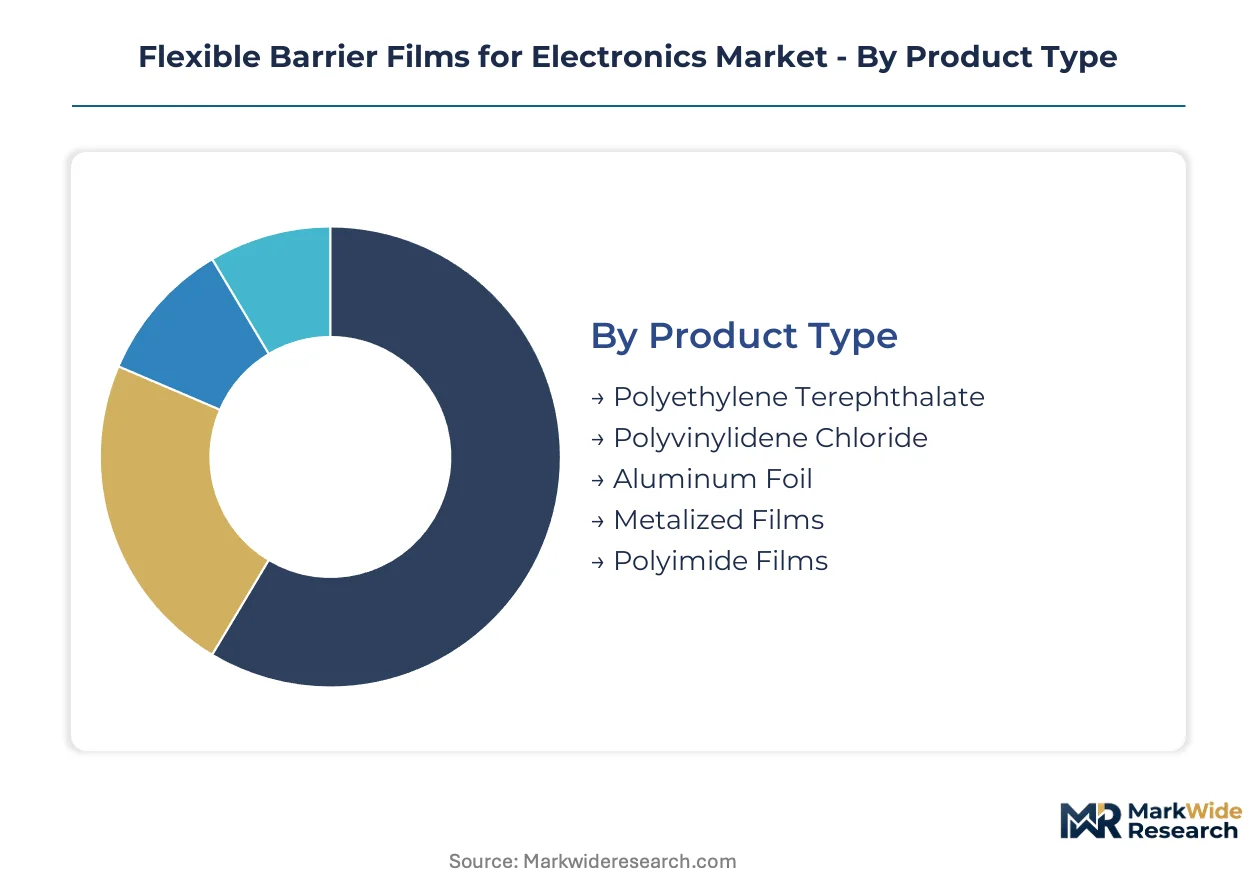
Barrier film specifications diverge sharply across electronics applications, with display encapsulation demanding atomic-layer precision while solar backsheets prioritize cost-scalable extrusion. Understanding these dimensional splits reveals where technology premiums concentrate versus where commodity substitution threatens margin.
Product Type:
Cost tier determines competitive positioning across substrate chemistries, with commodity polymers anchoring volume and high-performance polymers capturing specification premiums.
- Polyethylene Terephthalate:Extruded polyester substrates dominate solar cell backsheet and standard flexible printed electronics through mature supply chains and roll-width scalability. Korean and Chinese solar module assemblers source polyethylene terephthalate barrier laminates in kilometer-length orders, though water vapor transmission specifications plateau around 10⁻³ g/m²/day.
- Polyimide Films:Aromatic polyimide substrates sustain thermal stability above 300°C for semiconductor packaging and automotive in-cabin sensors. German automotive electronics suppliers specify polyimide barriers for flexible sensor arrays operating above 150°C, driving fastest-expanding demand within premium substrate tiers.
- Metalized Films:Aluminum-vacuum-deposited polymer webs serve mid-tier moisture barrier requirements in consumer electronics packaging.
- Aluminum Foil:Rolled aluminum webs provide opaque barrier protection for non-display electronics requiring electromagnetic shielding.
- Polyvinylidene Chloride:High-clarity chlorine-containing polymers occupy niche pharmaceutical blister pack applications with limited electronics penetration.
Polyethylene terephthalate commands the established base. The steepest expansion runs through polyimide films.
Application:
Application maturity splits between nascent foldable display volumes and established solar encapsulation scale.
- Flexible Displays:Multi-layer barrier laminates for OLED encapsulation require sub-10⁻⁶ g/m²/day water vapor transmission rates achieved through alternating silicon oxide and aluminum oxide deposition. South Korean display fabs in Gyeonggi Province specify ultra-high-barrier substrates for foldable smartphone panels rated above 200,000 bend cycles, concentrating specification authority among three OEM procurement teams.
- Solar Cells:Backsheet and frontsheet encapsulation for crystalline silicon and thin-film photovoltaic modules consumes barrier films in hectare-equivalent volumes. Chinese solar panel manufacturers in Jiangsu and Anhui provinces drive polyethylene terephthalate demand, though perovskite tandem architectures are pushing UV stability requirements beyond current substrate limits.
- Printed Circuit Boards:Flexible circuit substrates employ barrier coatings for moisture protection during surface-mount assembly.
- Sensor Protection:Automotive and industrial flexible sensors require barrier films combining thermal resilience with conformal coverage.
- Flexible Printed Electronics:Low-cost printed antenna and RFID applications tolerate higher transmission rates for cost-scaled deployment.
Solar cell encapsulation anchors volume scale. Flexible displays generate the fastest value-per-square-meter expansion.
Technology:
Process complexity stratifies value capture, with atomic-precision deposition commanding premium pricing versus commodity coating operations.
- Vacuum Deposition:Physical vapor deposition and plasma-enhanced chemical vapor deposition systems achieve angstrom-level barrier layer control. Japanese and Korean equipment suppliers dominate precision deposition tool installation, with roll-to-roll atomic layer deposition migrating from batch wafer configurations to continuous 1.5-meter-wide drum processing at 50 meters per minute.
- Metallization:Aluminum vacuum metallization onto polymer webs delivers mid-tier barrier performance for consumer electronics. Toppan Printing and similar suppliers operate precision vacuum deposition lines within 500 kilometers of Korean display fabrication clusters, co-location forced by OEM consolidation around ultra-high-barrier specifications.
- Coating:Solvent-based and water-based polymer coatings provide economical moisture protection for non-critical electronics.
- Lamination:Adhesive bonding of multi-layer webs combines barrier properties with mechanical protection.
- Extrusion:Melt-processing of barrier polymers into monolayer or coextruded sheet serves cost-minimized solar and packaging applications.
Coating and extrusion anchor high-volume production. Vacuum deposition captures the steepest technology premium expansion.
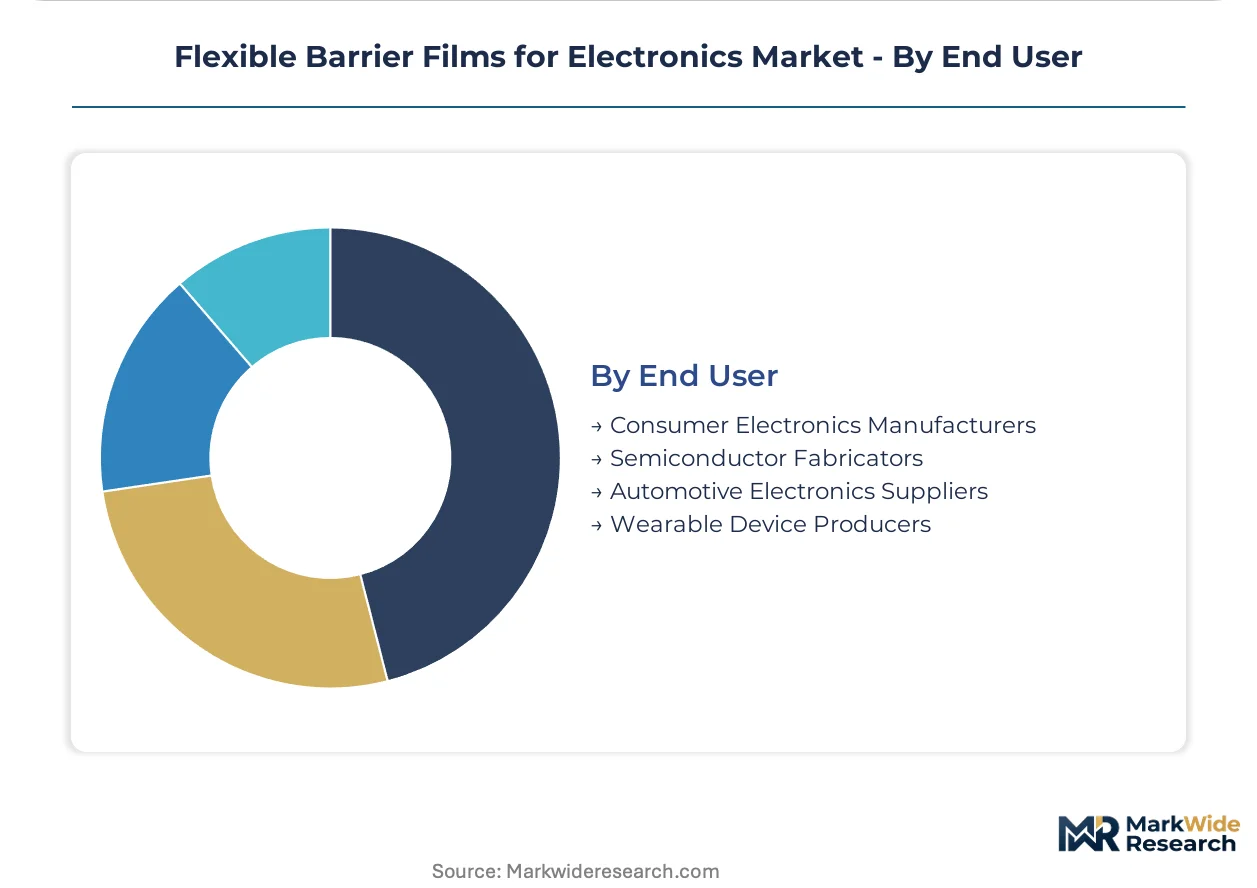
End User:
Customer concentration varies from fragmented wearable startups to consolidated semiconductor fabricators with captive specification authority.
- Consumer Electronics Manufacturers:Smartphone and tablet OEMs in South Korea and China consolidate procurement for foldable display barriers, embedding quality engineers at substrate supplier facilities. Direct OEM contracting displaces distributor channels as specification intensity rises, compressing margin capture for intermediate traders.
- Semiconductor Fabricators:Advanced packaging operations for high-bandwidth memory and logic dies require polyimide barriers with thermal cycling resilience. Taiwan Semiconductor Manufacturing and similar foundries specify polyimide-based thermal stability above 300°C for fan-out wafer-level packaging, occupying premium tier where performance overrides cost sensitivity.
- Automotive Electronics Suppliers:German and Japanese tier-1 suppliers drive in-cabin flexible sensor applications with sustained operation above 150°C.
- Wearable Device Producers:Skin-contact electronics for health monitoring require FDA biocompatibility pathways and ultra-thin conformal barriers.
Consumer electronics manufacturers concentrate volume demand. Semiconductor fabricators generate the fastest specification premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan and adjacent Gwangyang Bay industrial corridor anchor East Asian metallization capacity, with vacuum deposition equipment clustering within 500 kilometers of Korean display fabrication sites. This logistics infrastructure underwrites the region's dominance in ultra-high-barrier substrate supply chains.
South Korea
Gyeonggi Province display fabs drive specification intensity for foldable OLED encapsulation, with procurement teams embedding quality engineers at substrate supplier facilities. Korean OEMs now mandate sub-10⁻⁶ g/m²/day water vapor transmission rates for panels rated above 200,000 bend cycles. The Seoul Capital Area concentrates precision vacuum deposition expertise, with equipment suppliers piloting 1.5-meter-wide roll-to-roll atomic layer deposition drums.
China
Jiangsu and Anhui province solar panel manufacturers consume polyethylene terephthalate barrier laminates in hectare-equivalent volumes, though perovskite tandem architectures are pushing UV stability requirements beyond current substrate limits. MIIT dual carbon goals are accelerating non-fluorinated barrier chemistry migration in domestic coating operations. Shenzhen and Dongguan electronics clusters are scaling local metallization partnerships to reduce import dependency.
United States
EPA per- and polyfluoroalkyl substance restrictions are constraining fluorinated barrier chemistries in domestic manufacturing, forcing migration to silicon oxide-aluminum oxide hybrid deposition systems. FDA indirect food-contact standards additionally influence barrier film selection for wearable devices with skin-contact interfaces. Texas and Arizona semiconductor packaging operations specify polyimide barriers with thermal cycling resilience above 300°C.
Germany
Automotive electronics suppliers in Bavaria and Baden-Württemberg drive in-cabin flexible sensor applications requiring sustained operation above 150°C. REACH restrictions on organotin catalysts are forcing 18-24 month certification cycles for novel polyurethane adhesive formulations. The ECHA compliance timeline is compressing margin capture for European coating operations.
Japan
Japanese equipment suppliers dominate precision deposition tool installation, with METI industrial policy supporting atomic layer deposition technology migration from batch wafer to continuous roll-to-roll configurations. Nagoya and Osaka industrial corridors host vacuum metallization lines serving Korean display fabs through just-in-time supply arrangements. JIS standards for barrier film performance are diverging from Western chemical compliance regimes.
Flexible Barrier Films for Electronics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, anchoring substrate and deposition technology supply. The vendor base stratifies across three tiers: diversified materials conglomerates with multi-layer adhesive-coating portfolios, precision metallization houses with captive vacuum deposition lines, and regional extrusion specialists serving cost-scaled solar encapsulation. Two competitive moves dominate: direct OEM contracting displacing distributor channels, and co-location of metallization capacity within 500 kilometers of display fabrication clusters.
Within the diversified materials tier, 3M Company and DuPont exemplify platform breadth, with the former anchoring high-barrier specifications for foldable display laminates and the latter occupying premium thermal stability positioning. Toppan Printing Co., Ltd. represents the precision metallization archetype, sustaining dominance in metallized film roll goods through vacuum deposition expertise. These three entities illustrate the competitive structure: materials platforms compete on specification breadth, while deposition specialists compete on proximity to fabrication demand.
| Leading Market Players |
|---|
| 3M Company |
| Amcor Plc |
| Toppan Printing Co., Ltd. |
| Honeywell International Inc. |
| Eastman Chemical Company |
| Tera-Barrier Films Pte Ltd |
| DuPont |
| Materion Corporation |
| Beneq |
| Others |
Supply & Pricing Matrix
Gwangyang Bay metallization corridors concentrate vacuum deposition capacity within 500 kilometers of Korean display fabrication clusters, compressing logistics costs while amplifying supplier pricing power for ultra-high-barrier substrates. This geographic anchoring forces downstream OEMs into long-term offtake contracts with limited spot-market alternatives, embedding cost pass-through mechanisms for trimethylaluminum precursor volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates polyimide thermal-stability specifications from polyethylene terephthalate solar laminates and commodity metallized packaging films. Price differentiation hinges on water vapor transmission certification grade and volume scale, with Korean display fabs commanding steepest discounts through embedded quality engineer arrangements. Cost compression in standard-tier solar encapsulation is intensifying because Chinese module assemblers consolidate hectare-equivalent orders. Semiconductor fabricators exhibit least price sensitivity, prioritizing thermal cycling resilience above cost optimization.
Supply Chain Analysis
Export controls on precision deposition equipment limit technology flows from Japan and South Korea to emerging metallization hubs, constraining capacity expansion outside established East Asian corridors. Raw material dependencies center on trimethylaluminum precursors, aluminum oxide feedstocks, and polyimide resin supplies. Single-source vulnerability concentrates in organotin catalyst formulations facing REACH certification delays. Distribution runs through direct OEM contracting channels displacing traditional distributor mediation, with substrate suppliers embedding technical staff at display fabrication facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible barrier films constitute a platform-economics inflection where atomic layer deposition interoperability standards are consolidating around Korean equipment supplier ecosystems, locking in specification authority for substrate-chemistry combinations that dominate foldable display procurement.
For Market Incumbents: Pre-empt margin erosion in polyethylene terephthalate solar tiers by accelerating backward integration into polyimide resin production, while securing captive trimethylaluminum supply agreements before precursor volatility intensifies. Defend specification authority in Gyeonggi Province display clusters through co-located quality engineering teams that deepen OEM switching costs.
For New Entrants and Emerging Players: Establish a beachhead in Indian electronics manufacturing corridors where production-linked incentive schemes for semiconductor fabrication are attracting barrier film suppliers without entrenched East Asian supplier relationships. Target wearable medical patch applications requiring FDA biocompatibility pathways, leveraging thinner qualification timelines versus display encapsulation certification.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty-materials platform play because atomic layer deposition equipment interoperability is consolidating procurement around substrate-chemistry combinations with decade-long specification lock-in. Acquisition candidates with roll-to-roll vacuum deposition expertise in underrepresented geographies offer geographic diversification value. Monitor EPA per- and polyfluoroalkyl substance enforcement intensity as inflection indicator for non-fluorinated chemistry migration speed.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive trimethylaluminum sourcing insulates coaters from three-supplier concentration risk. |
| Roll-to-Roll Atomic Layer Deposition Scale-Up | Korean equipment pilots at 1.5-meter width compress capital recovery timelines for metallization suppliers. |
| REACH-Compliant Catalyst Reformulation | Japanese catalyst partnerships accelerate European coating qualification cycles for organotin-free adhesives. |
| Direct OEM Contracting Migration | Embedded quality engineers at Korean display fabs displace distributor-mediated procurement channels. |
| Indian Metallization Partnership Formation | PLI scheme incentives for semiconductor fabrication attract barrier film co-location investments. |
Research Methodology
The analysis maps vacuum deposition technology tiers, substrate chemistry segments, and end-use application clusters, each validated through deposition equipment engineers, display fab procurement leads, automotive electronics suppliers, and coating operation technical directors. Primary interview findings triangulated against customs trade data for metallized film imports, SEC filings from diversified materials conglomerates, Korean display industry association production statistics, and ECHA REACH pre-registration databases. Bottom-up unit economics for atomic layer deposition throughput combined with top-down market sizing across electronics manufacturing value chains.
Assumptions held fixed include continuation of Korean and Chinese display fab consolidation patterns, stable EPA enforcement trajectory for per- and polyfluoroalkyl substance restrictions, and sustained organotin catalyst phase-out timelines under REACH. Segmentation modeling spanned substrate chemistry, deposition technology, application performance tier, and regional manufacturing cluster. CAGRs derived from elasticity-adjusted demand curves incorporating foldable display adoption rates and solar module deployment trajectories across the analysis window. Industry-specific inputs included water vapor transmission rate achievement curves and bend-cycle durability specifications.
Stress conditions across trimethylaluminum supply disruption scenarios, REACH enforcement acceleration, and display fab demand volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding equipment technology migration timelines and regulatory compliance cost trajectories. Material shifts in EPA per- and polyfluoroalkyl substance rulemaking or Korean display OEM procurement consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Nano Sealers Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Heat Seal Coating Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Europe Barrier Films Market