
 Cap Liner Films Market | 2026-2036
Cap Liner Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cap Liner Films Market Outlook
Skilled polymer compounding expertise is rotating toward multilayer coextrusion capabilities as converters face tighter seal-integrity specifications. Tekni-Plex leverages captive resin formulation to control oxygen transmission rates across pharmaceutical applications. Selig Group anchors European supply through induction seal specialization, while Berry Global sustains volume leadership via integrated film-to-liner manufacturing.
Cap liner films are multilayer laminated or coextruded structures, typically 0.5–2.0 mm in total thickness, engineered to provide hermetic sealing, chemical resistance, and tamper evidence across container closures. Their primary purpose is to create a functional barrier between product and external environment while enabling clean peel or weld-seal removal. Pressure-sensitive liners dominate unit volume due to universal compatibility with screw-cap geometries, though induction seal films capture disproportionate value in pharmaceutical and chemical end uses where zero-leak integrity is mandatory. Polypropylene-based constructions are displacing polyethylene in hot-fill applications, while aluminum-foil laminates retain premium positioning in moisture-sensitive drug packaging.
FDA compliance with 21 CFR 177.1520 for olefin polymers and EU REACH restrictions on adhesive monomers constrain material selection for export-oriented suppliers. India's BIS certification for food-contact plastics and the EU F-Gas Regulation's indirect pressure on fluorinated barrier films are reshaping regional sourcing patterns. Stakeholders must monitor how California's Proposition 65 litigation trends and evolving EU Packaging and Packaging Waste Regulation thresholds will redefine acceptable liner film chemistries before the next compliance cycle.
Market Dynamics
Multilayer coextrusion capability scarcity is concentrating converter margins toward firms with captive resin formulation and precision die engineering, while generic commodity liner producers face margin compression from specification tightening.
Growth Catalysts
- EU MDR migration limits:Pharmaceutical packaging lines are expanding liner film specifications to meet child-resistant and tamper-evident closure requirements across European export corridors.
- Induction seal specialization:Zero-leak integrity mandates in chemical and drug packaging are pulling demand toward aluminum-foil laminate constructions with hermetic weld-seal performance.
- India's generic drug export hubs:BIS certification requirements for food-contact plastics are driving localized compounding investments and technical partnership formation.
Market Restraints
- Fluorinated barrier input costs:The EU F-Gas Regulation's phase-down of hydrofluorocarbons is constraining supply of high-barrier fluoropolymer films and elevating raw material price volatility.
- Adhesive monomer restrictions:EU REACH limitations on specific adhesive chemistries are forcing reformulation cycles that extend qualification timelines for export-oriented suppliers.
- Polypropylene supply concentration:Hot-fill application growth is exposing converters to propylene feedstock tightness concentrated in Gulf Coast petrochemical corridors.
Strategic Opportunities
- California Proposition 65 litigation preparation:Anticipatory reformulation of liner chemistries to preempt warning label requirements creates first-mover positioning in US pharmaceutical exports.
- EU Packaging and Packaging Waste Regulation thresholds:Recyclability mandates are opening specification windows for mono-material polypropylene constructions that simplify end-of-life sorting.
- Pharmaceutical serialization integration:Convergence of tamper-evident liner films with track-and-trace authentication layers enables premium pricing in high-value drug packaging.
Industry Challenges
- Multilayer die engineering talent:Skilled polymer compounding expertise is rotating toward coextrusion capabilities faster than vocational training pipelines can replenish, creating wage pressure for specialized technicians.
- Migration testing protocol timelines:FDA compliance with 21 CFR 177.1520 and evolving EU MDR barrier standards require extended analytical validation that delays product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cap Liner Films Market |
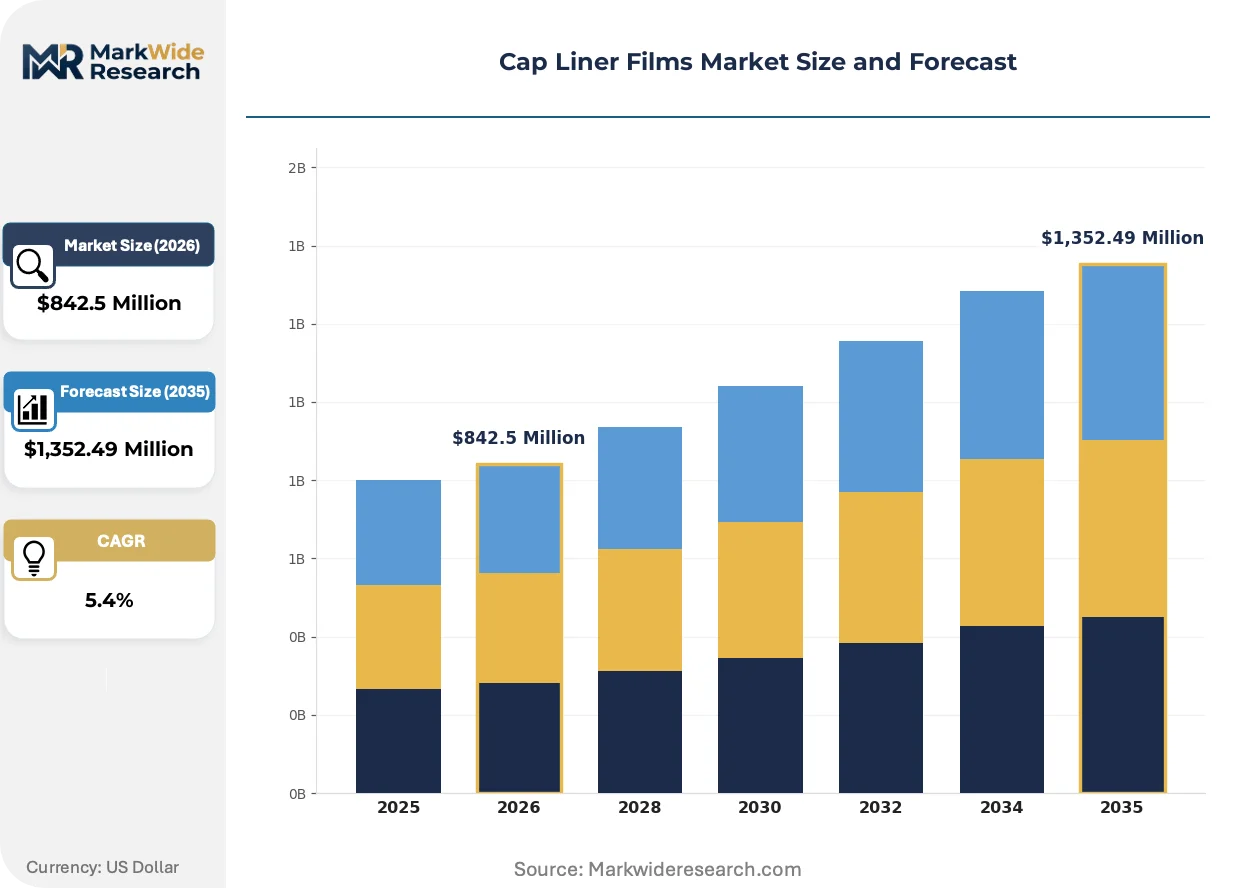
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,352.49 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensitive, Induction Seal, Roll-on Pilfer Proof, Foil Material: Polyethylene, Polypropylene, Aluminum, Paper End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Distribution Channel: Direct Sales, Online Retail, Distributors, Exporters |
| Companies Covered | Tekni-Plex, Selig Group, Tri-Seal, Amcor Limited, Berry Global, Pres-On, B&B Cap Liners, Bluemay Weston Limited, The Cary Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cap Liner Films Market Strategic Shifts
Active barrier layer engineering is compressing total film thicknesses while maintaining hermetic performance, forcing equipment reinvestment cycles across mid-tier converters.
Coextruded ethylene vinyl alcohol barrier films are miniaturizing total laminate gauges from 2.0 mm toward sub-1.0 mm specifications without sacrificing oxygen transmission resistance. Pharmaceutical contract packagers in Germany and Switzerland are adopting these constructions at accelerated qualification paces to meet vial and bottle downsizing trends. This gauge compression is miniaturizing material throughput per thousand closures and threatening volume-based revenue models at commodity liner suppliers.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is eliminating incumbent high-barrier fluoropolymer films from pharmaceutical specifications by 2030. Converters are responding with aluminum oxide metallized alternatives and silicon oxide coatings that achieve comparable moisture vapor transmission rates. German pharmaceutical packaging corridors are most affected, with induction seal specialists accelerating validation of oxide-coated polyethylene terephthalate laminates ahead of regulatory deadlines.
Specification consolidation among generic drug exporters is compressing supplier qualification cycles and favoring integrated film-to-liner manufacturers with in-house analytical laboratories. Indian pharmaceutical packaging hubs are consolidating procurement toward dual-source arrangements with European technical partners rather than spot-market commodity purchasing. This concentration pattern is most visible in Mumbai-Pune and Hyderabad clusters, where export registration requirements mandate documented supply chain continuity.
Cap Liner Films Market Segmentation
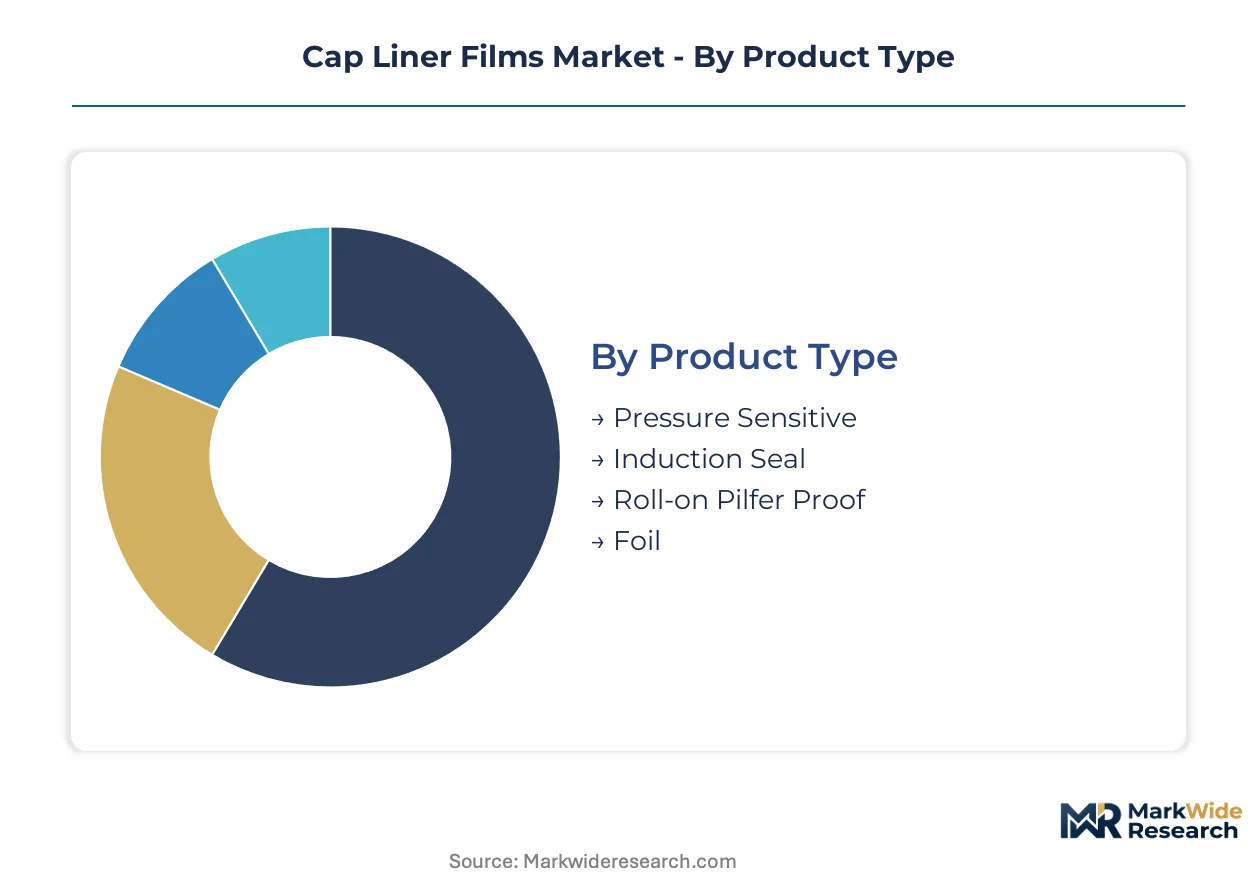
Cap liner film specifications diverge sharply across export corridors versus domestic supply chains. Pharmaceutical and food-contact applications demand certified material traceability that commodity segments rarely require.
Product Type:
Induction seal films dominate pharmaceutical export specifications from Germany and Switzerland, while pressure-sensitive constructions serve cost-sensitive domestic food markets.
- Pressure Sensitive:These liners employ adhesive-coated foams or laminates that activate under screw-cap compression without heat application. Indian generic drug exporters in Hyderabad and Mumbai-Pune clusters are qualifying pressure-sensitive alternatives for non-critical oral solid doses where induction equipment capital is prohibitive.
- Induction Seal:Aluminum-foil laminate constructions create hermetic weld-seals through electromagnetic heating, mandatory for zero-leak pharmaceutical and agrochemical packaging. German pharmaceutical packaging corridors specify these exclusively for vial and bottle closures subject to EU MDR migration limits.
- Roll-on Pilfer Proof:Tamper-evident bands shrink-fit to container necks during capping operations.
- Foil:Unlaminated aluminum foils serve basic barrier applications in developing markets.
Induction seal films command the established base in regulated export corridors. The steepest expansion runs through pressure-sensitive variants penetrating cost-constrained emerging markets.
Material:
Material selection tracks directly against thermal processing requirements and regulatory migration thresholds.
- Polypropylene:Displacing polyethylene in hot-fill beverage and pharmaceutical applications due to superior thermal stability above 120°C. Gulf Coast propylene feedstock tightness is exposing converters to price volatility as hot-fill demand concentrates in North American and European bottling operations.
- Polyethylene:Retaining volume leadership in ambient-fill food and cosmetic applications where cost minimization dominates specification. Indian BIS certification requirements for food-contact plastics are accelerating localized polyethylene compounding investments in Gujarat and Maharashtra states.
- Aluminum:Foil and metallized layers provide moisture and oxygen barriers in pharmaceutical induction seals.
- Paper:Pulp-based liners serve limited cosmetic and dry food applications with minimal barrier requirements.
Polyethylene retains the volume base across commodity applications. Polypropylene gains share fastest where hot-fill processing and sterilization compatibility are non-negotiable.
End User:
End-use concentration patterns split between FDA-regulated pharmaceutical exporters and domestically oriented food processors.
- Pharmaceuticals:Demands the most stringent barrier specifications with documented supply chain continuity for EU MDR and FDA 21 CFR 177.1520 compliance. German contract packagers and Swiss pharmaceutical manufacturers specify sub-1.0 mm EVOH barrier laminates for vial downsizing trends.
- Food & Beverage:Largest unit volume segment with diverging specification tiers between premium induction-sealed exports and domestic pressure-sensitive applications. California Proposition 65 litigation trends are forcing anticipatory reformulation of adhesive chemistries in US-bound food packaging.
- Cosmetics:Aesthetic peel requirements and fragrance barrier needs drive specialized foam constructions.
- Chemicals:Agrochemical and industrial chemical packaging mandates hermetic induction seals for hazardous material containment.
Food and beverage applications provide the volume foundation. Pharmaceutical specifications are climbing the fastest as serialization and tamper-evidence requirements tighten.
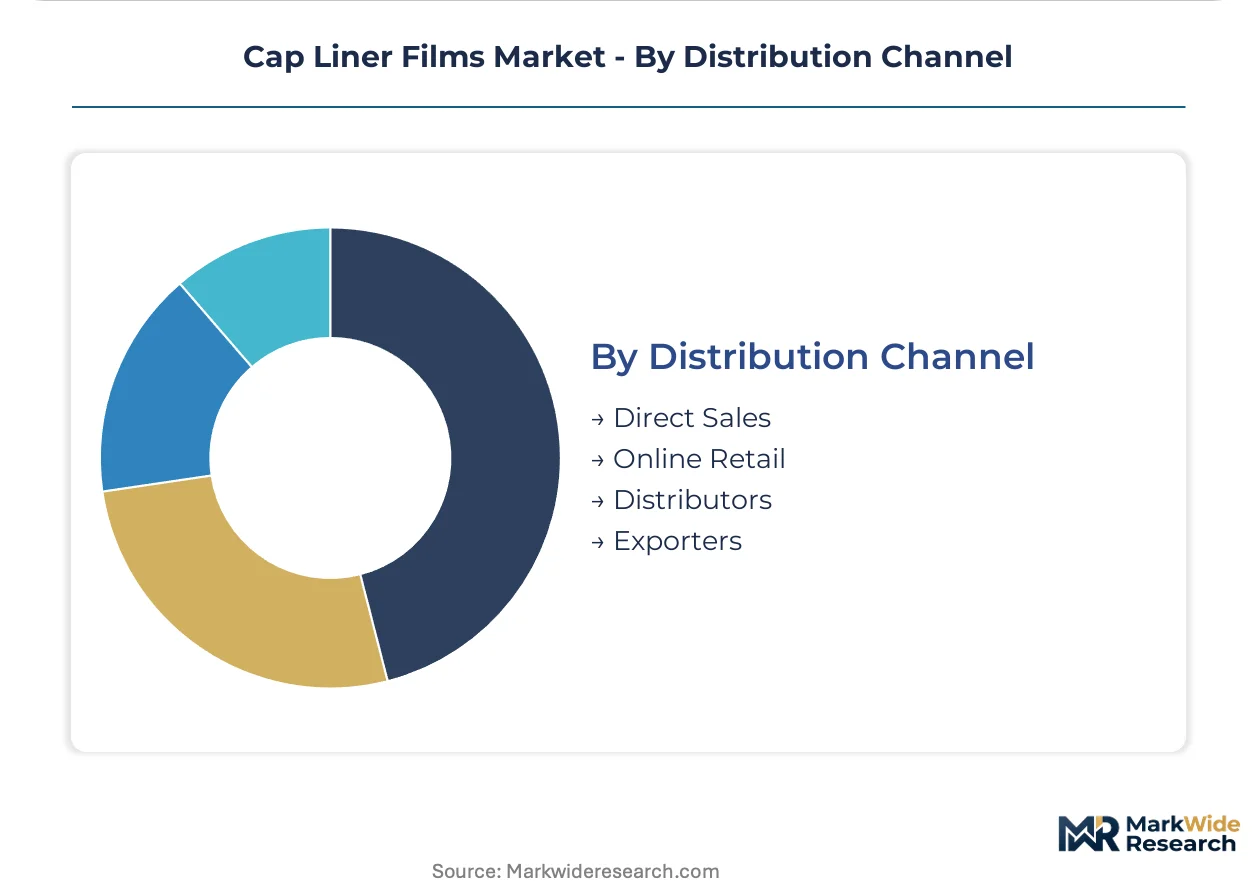
Distribution Channel:
Channel structure reflects the technical intensity of qualification requirements versus commodity spot purchasing.
- Direct Sales:Integrated film-to-liner manufacturers with in-house analytical laboratories capture pharmaceutical and large food processor accounts through documented technical partnership arrangements. Indian pharmaceutical hubs are consolidating procurement toward direct relationships with European technical partners rather than distributor intermediaries.
- Distributors:Serve mid-tier converters and regional food packagers with standardized pressure-sensitive inventory.
- Online Retail:Emerging channel for small-batch cosmetic and specialty chemical producers requiring rapid sample turnaround.
- Exporters:Specialized traders manage cross-border regulatory documentation for EU and US destination markets.
Direct sales anchor the high-value pharmaceutical segment. Distributor channels are expanding most quickly in mid-tier food and cosmetic applications where specification standardization permits inventory-based supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and India exhibit the sharpest consumption-mix differential: German pharmaceutical corridors demand sub-1.0 mm EVOH barrier laminates for vial downsizing, while Indian generic exporters in Hyderabad and Mumbai-Pune clusters qualify pressure-sensitive alternatives where induction equipment capital remains prohibitive.
Germany
Induction seal specialization and pharmaceutical contract packaging expansion drive specification tightening. EMA's EU MDR migration limits enforce child-resistant and tamper-evident closure requirements across export corridors. The Rhine-Main and Baden-Württemberg pharmaceutical packaging corridors accelerate validation of oxide-coated PET laminates ahead of F-Gas Regulation deadlines.
India
Generic drug export hub growth and localized compounding investments reshape procurement patterns. BIS certification requirements for food-contact plastics accelerate technical partnership formation with European suppliers. Mumbai-Pune and Hyderabad clusters consolidate procurement toward dual-source arrangements with documented supply chain continuity for US FDA and EU export registrations.
United States
Hot-fill beverage processing and pharmaceutical serialization integration pull demand toward polypropylene constructions. FDA's 21 CFR 177.1520 compliance and California Proposition 65 litigation trends force anticipatory adhesive reformulation. Gulf Coast petrochemical corridors expose converters to propylene feedstock tightness as hot-fill demand concentrates in North American bottling operations.
Switzerland
Pharmaceutical manufacturing precision and vial downsizing trends accelerate EVOH barrier laminate adoption. Swissmedic regulations align with EU MDR standards, tightening migration limits for indirect food-contact layers. Basel and Zurich pharmaceutical manufacturing zones specify hermetic weld-seal constructions exclusively for high-value drug packaging exports.
China
Domestic pharmaceutical packaging expansion and fluoropolymer barrier substitution reshape material sourcing. NMPA standards for drug packaging materials converge toward international migration limits. Yangtze River Delta pharmaceutical manufacturing clusters invest in aluminum oxide metallized alternatives as EU F-Gas Regulation eliminates incumbent fluoropolymer specifications.
Cap Liner Films Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive resin formulation and precision die engineering concentrating margins at the top. The market structure separates film-to-liner manufacturers with in-house analytical laboratories from commodity converters facing specification-driven margin compression. Three archetypes dominate: integrated resin-compounding leaders, induction seal specialists with hermetic weld-seal capabilities, and regional pressure-sensitive commodity suppliers. Competitive moves center on multilayer coextrusion capacity expansion and anticipatory reformulation for evolving EU and US regulatory thresholds.
Within the integrated leader tier, Tekni-Plex and Berry Global exemplify firms with captive resin formulation control over oxygen transmission specifications, while Selig Group anchors European supply through induction seal specialization. These three occupy positions spanning pharmaceutical export corridors and integrated film-to-liner manufacturing, representing the premium-tier vector where qualification timelines and technical partnership depth determine account retention.
| Leading Market Players |
|---|
| Tekni-Plex |
| Selig Group |
| Tri-Seal |
| Amcor Limited |
| Berry Global |
| Pres-On |
| B&B Cap Liners |
| Bluemay Weston Limited |
| The Cary Company |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German pharmaceutical contract packagers and integrated film-to-liner manufacturers lock in multilayer coextrusion capacity while insulating converters from Gulf Coast propylene volatility. These contracts bundle resin formulation control with hermetic seal qualification timelines, creating price visibility that spot-market commodity suppliers cannot match.
Pricing Analysis
Contract-based long-term offtake structures dominate pharmaceutical export corridors, while spot purchasing persists in domestic food applications. Price differentiation hinges on EU MDR certification tier and captive resin formulation capability, with induction seal films commanding substantial premiums over pressure-sensitive alternatives. Cost compression in commodity polyethylene liners is intensifying because Indian generic exporters are consolidating procurement toward dual-source technical partnerships. Small-batch cosmetic producers exhibit the highest price sensitivity, whereas Swiss pharmaceutical manufacturers prioritize seal integrity over unit economics.
Supply Chain Analysis
Gulf Coast petrochemical corridors concentrate propylene feedstock supply that underwrites North American polypropylene liner production. Raw material sourcing draws from Saudi Arabian ethylene crackers, South Korean EVOH barrier resin specialists, and domestic aluminum foil rolling mills. Single-source vulnerability runs through fluoropolymer film supply as EU F-Gas Regulation phase-downs eliminate incumbent high-barrier specifications. Distribution feeds from integrated film-to-liner manufacturers with in-house analytical laboratories directly to pharmaceutical contract packagers, bypassing distributor intermediaries in regulated export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification tightening across pharmaceutical export corridors fragments procurement patterns, creating defendable niches for converters with multilayer die engineering capabilities and documented EU MDR compliance pathways.
For Market Incumbents: Consolidate multilayer coextrusion capacity in Germany's Rhine-Main pharmaceutical packaging corridor to capture EVOH barrier laminate demand from vial downsizing trends. Deepen backward integration into captive resin formulation to offset Gulf Coast propylene feedstock tightness, while accelerating oxide-coated PET validation ahead of EU F-Gas Regulation deadlines to defend against aluminum oxide metallized alternatives. For New Entrants and Emerging Players: Differentiate on localized BIS certification capability for Indian generic drug exporters in Hyderabad and Mumbai-Pune clusters seeking documented supply chain continuity for US FDA registrations. Target pressure-sensitive liner segments where induction equipment capital constraints exclude integrated incumbents, leveraging rapid sample turnaround through online retail channels for small-batch cosmetic producers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated film-to-liner manufacturers with in-house analytical laboratories and established EU MDR qualification pathways. Long-term viability hinges on exposure to pharmaceutical serialization integration and tamper-evident authentication layer convergence. Watch for inflection signals in California Proposition 65 litigation settlements that force anticipatory adhesive reformulation and reshape acceptable liner chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capacity Expansion | Captures EVOH barrier laminate demand from German vial downsizing specifications. |
| Captive Resin Formulation Investment | Insulates converters from Gulf Coast propylene volatility and tightness exposure. |
| Oxide-Coated PET Validation Acceleration | Positions suppliers ahead of EU F-Gas Regulation fluoropolymer elimination deadlines. |
| BIS Certification Partnership Formation | Unlocks procurement consolidation among Indian generic drug export hubs. |
| Pharmaceutical Serialization Integration | Enables premium pricing through tamper-evident liner and track-and-trace convergence. |
Study Parameters
A spread of perspectives from polymer compounding engineers, pharmaceutical packaging procurement managers, regulatory affairs specialists at EU MDR notified bodies, and induction seal equipment manufacturers converged on the working assumptions. Primary fieldwork combined structured interviews with converter plant managers and downstream food processor technical directors, validated against secondary sources including FDA 21 CFR filings, EMA guidance documents, BIS certification registries, and EU F-Gas Regulation implementation reports. Bottom-up volume triangulation from resin throughput data and top-down value estimation from pharmaceutical packaging spend analysis were cross-referenced for consistency.
Segmentation dimensions modeled encompass product type hierarchy, material thermal stability tier, end-use regulatory intensity, and distribution channel technical depth across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific forecast inputs included EU MDR migration limit enforcement timelines and Indian generic drug export registration velocity.
Material uncertainties — regulatory deadline acceleration, feedstock disruption severity, and litigation settlement patterns — sit outside the modeled envelope. Forecasts reflect assumptions about qualification timeline stability and technical partnership durability. Practitioners should keep alternative scenarios live as EU Packaging and Packaging Waste Regulation recyclability thresholds and California Proposition 65 warning label requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Global Stretch and Shrink Film Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
Insulation Film Market