
 Stretch Hood Films Market | 2026-2036
Stretch Hood Films Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Hood Films Market Intelligence
Maintenance contracts for automated hooding equipment is broadening what converters sell alongside resin. Exxon Mobil leverages its metallocene polyethylene catalyst portfolio to sustain supply relationships with European machinery integrators. Dow anchors its position through backward integration into alpha-olefin production, while Manuli Stretch competes on film gauge reduction without sacrificing load containment force.
Stretch hood films are elastic polyethylene-based sleeves, typically 80–150 microns thick, that expand mechanically over palletized loads and contract to form a tight, weather-resistant enclosure for transport and outdoor storage. Blown film dominates current supply due to superior puncture resistance in construction material handling, though coextruded structures are gaining fastest as converters layer EVOH or tie resins to meet oxygen barrier requirements in food processing applications. Pallet wrapping remains the largest application by volume, but protection-focused formats for agricultural bulk goods now carry wider margin pools as seasonal harvest volatility demands just-in-time film availability.
The EU F-Gas Regulation and REACH chemical compliance frameworks constrain fluorinated additive use in anti-fog and UV-stabilized grades, redirecting formulation R&D toward bio-based stabilizers. FDA food-contact migration limits in the United States similarly restrict certain slip agents in films destined for food processing end users. Stakeholders must monitor how mechanical recycling certification standards evolve, as post-consumer content mandates in Germany and France will determine which film structures qualify for construction and agricultural supply contracts.
Market Dynamics
Construction material producers are consolidating palletizing operations into automated lines that favor stretch hood systems over conventional wrapping, compressing equipment replacement cycles and forcing film converters to bundle maintenance contracts with resin supply agreements.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for thinner, recyclable film structures are accelerating converter R&D into mono-material PE architectures that maintain load containment performance.
- Automated palletizing lines at cement and brick plants:German construction material producers are standardizing on hooding systems for transit stability, creating captive demand for compatible film specifications.
- Metallocene polyethylene catalyst advances:Enhanced elasticity and puncture resistance are enabling downgauging without sacrificing mechanical performance in rough-handling environments.
Market Restraints
- Alpha-olefin feedstock concentration:Dow's backward integration into octene and hexene production creates supply asymmetry for independent film converters lacking captive monomer access.
- REACH chemical compliance friction:ECHA restrictions on fluorinated additives for UV stabilization are forcing reformulation cycles that extend product qualification timelines by 12-18 months.
- Mechanical stretch wrapping substitution:Lower-capital rotary arm wrappers retain cost advantage for low-throughput operations, capping hooding penetration in smaller construction material yards.
Strategic Opportunities
- Agricultural bulk goods protection:Seasonal harvest volatility in grain and fertilizer handling is creating just-in-time film availability contracts with premium margin structures.
- Post-consumer content mandates in France:Mechanical recycling certification requirements are opening first-mover advantage for converters with qualified PCR supply chains.
- EVOH barrier layer convergence:Coextruded structures incorporating oxygen barriers are penetrating food processing applications previously served by shrink bags and modified atmosphere packaging.
Industry Challenges
- Metallocene catalyst operation expertise:Film extrusion technicians with deep knowledge of narrow MWD resin behavior command wage premiums that strain mid-converter cost structures.
- Food-contact migration testing backlog:FDA compliance documentation for slip agent packages is extending qualification timelines for North American food processing contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Hood Films Market |
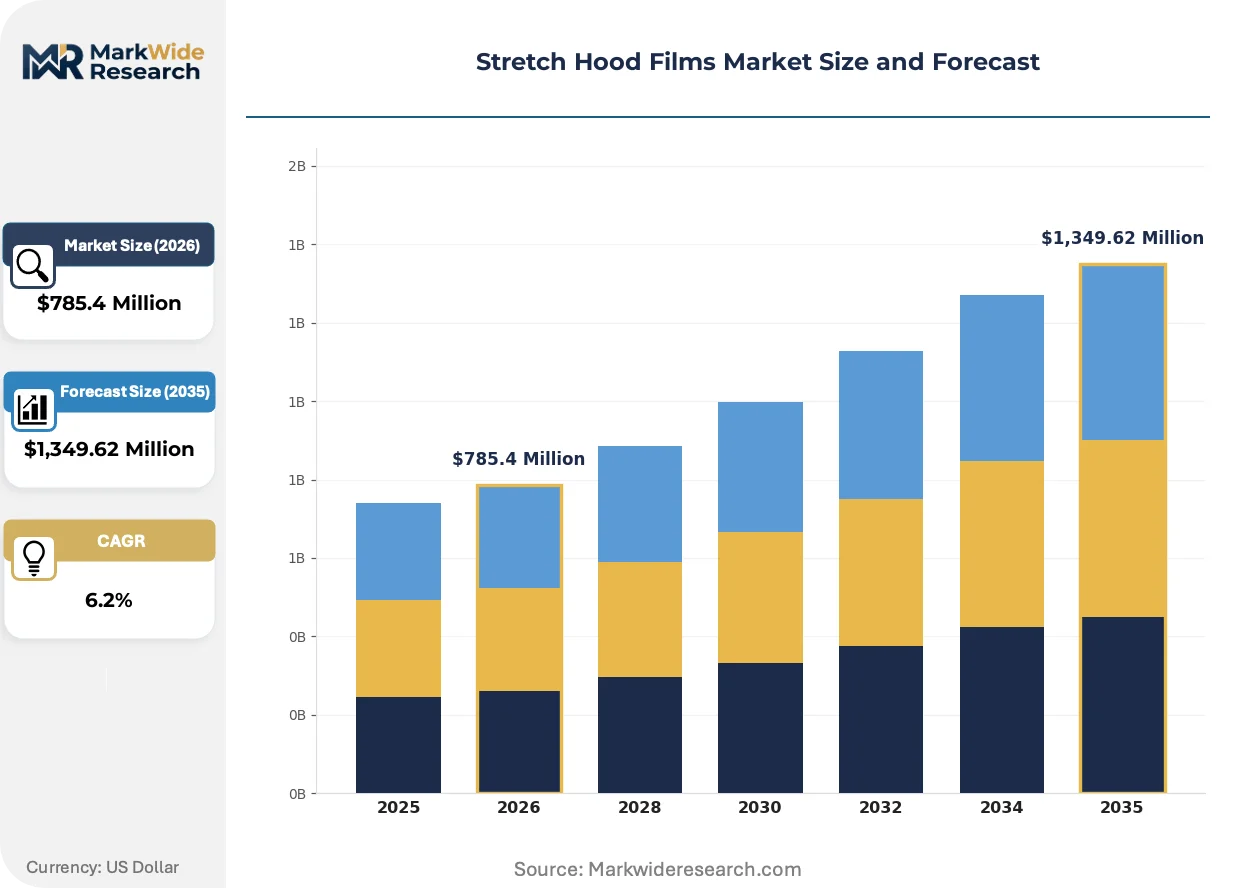
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,349.62 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Blown, Cast, Coextruded, Laminated, Coated Application: Pallet Wrapping, Shrink Wrapping, Product Bundling, Unitizing, Protection End User Industry: Consumer Goods, Agriculture, Construction Materials, Chemicals, Food Processing Packaging Format: Rolls, Sheets, Bags, Tubes, Customized Shapes |
| Companies Covered | Exxon Mobil, Manuli Stretch, Dow, Charter Next Generation, Innovia Films, Berry Global Inc., Sigma Plastics Group, Coveris Holdings S.A., RKW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Hood Films Market Strategic Shifts & Innovations
Formulation chemistry and equipment integration are converging to enable thinner films with equivalent mechanical performance, while regulatory pressure on chemical additives is redirecting stabilizer innovation toward bio-based alternatives.
Blown film extrusion is consolidating its position in construction material handling applications where puncture resistance dominates specification requirements. Cement and brick producers in automated facilities are specifying 100-120 micron blown structures over cast alternatives. This consolidation is compressing the addressable market for cast film converters unless they pivot to barrier-grade coextruded products.
REACH and the EU F-Gas Regulation are jointly constraining fluorinated anti-fog and UV additive use in outdoor storage grades. ECHA's sunset dates for perfluorinated substances are forcing reformulation toward hindered amine light stabilizers and bio-derived surfactants. Agricultural film suppliers serving seasonal bulk goods markets are absorbing extended field-testing cycles to validate alternative additive packages.
Maintenance unbundling is altering how construction material producers contract for hooding operations. Equipment integrators in Germany are separating film supply from service agreements, enabling end-users to dual-source resin while retaining single-source mechanical support. This pattern is most visible in cement sector palletizing lines where uptime guarantees override material loyalty.
Stretch Hood Films Market Segmentation
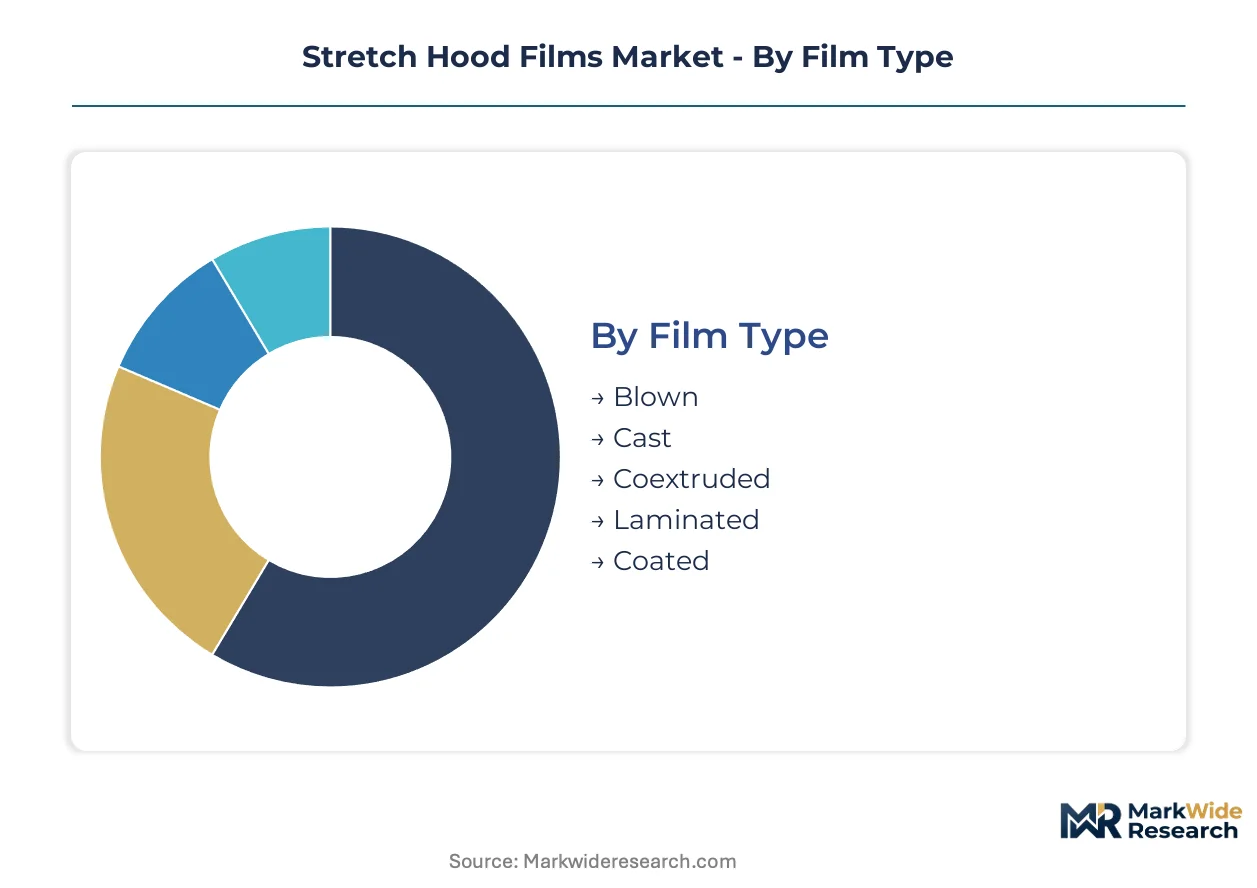
Segmentation in stretch hood films reveals how equipment compatibility and end-use specifications drive purchasing decisions. Converters must align film structures with automated hooding systems while navigating divergent regulatory requirements across construction, food, and agricultural supply chains.
Film Type:
Equipment upgrade cycles at German cement plants and French brick facilities are accelerating replacement of legacy cast films with blown and coextruded alternatives that integrate with newer palletizing lines.
- Blown:Manufactured through bubble extrusion with biaxial orientation, blown films deliver superior puncture resistance for rough-handling environments. Cement producers in Germany specify 100-120 micron blown structures almost exclusively for automated palletizing lines handling abrasive building materials.
- Coextruded:Multi-layer architectures incorporate EVOH or tie resins to achieve oxygen barriers previously unattainable in mono-material formats. Food processors in France are qualifying coextruded hoods for modified atmosphere applications where shelf-life extension justifies premium film costs.
- Cast:Chill-roll extrusion yields optical clarity and gauge consistency for applications where appearance matters more than puncture toughness. Limited penetration in construction materials due to inferior performance against sharp-edged bricks and aggregates.
- Laminated:Bonded multi-ply structures combine dissimilar materials for specialized barrier performance. Higher cost position restricts deployment to premium agricultural bulk goods requiring extended outdoor storage durability.
- Coated:Surface-treated films carry anti-fog or UV-stabilized layers for seasonal agricultural protection. REACH compliance constraints on fluorinated additives are extending reformulation timelines for coated grades destined for EU markets.
Volume placements concentrate in Blown; the faster expansion belongs to Coextruded.
Application:
Cost tier differentiation separates high-throughput pallet operations from lower-volume bundling tasks, with automation level determining film specification intensity.
- Pallet Wrapping:The dominant volume application where elastic sleeves expand mechanically over unitized loads and contract for weather-resistant enclosure. Construction material producers in Germany running automated lines generate captive demand for compatible 80-150 micron specifications.
- Protection:Seasonal agricultural bulk goods—grain harvests, fertilizer stockpiles—drive just-in-time film contracts with premium margin structures. French cooperatives are negotiating availability guarantees ahead of harvest volatility.
- Shrink Wrapping:Heat-activated film contraction for product display and retail-ready packaging. Limited overlap with stretch hood technology due to different equipment requirements and load containment mechanisms.
- Product Bundling:Lower-gauge applications for consumer goods aggregation. Rotary arm wrappers retain cost advantage here, capping hooding penetration in smaller yards.
- Unitizing:Intermediate-scale consolidation of mixed SKUs for distribution center handling. Margin pressure from mechanical stretch wrapping alternatives constrains growth in this mid-tier segment.
Revenue concentrates in Pallet Wrapping; Protection applications are gaining share fastest.
End User Industry:
Customer type segmentation exposes how regulatory exposure and automation maturity shape film specification requirements across divergent supply chains.
- Construction Materials:Cement and brick producers are consolidating palletizing into automated lines that standardize on hooding systems for transit stability. German facilities lead this transition, creating specification lock-in for compatible film structures.
- Food Processing:FDA migration limits on slip agents and EFSA food-contact requirements are extending qualification timelines. Coextruded barrier grades are penetrating applications previously served by shrink bags.
- Agriculture:Seasonal harvest volatility demands just-in-time film availability contracts. French and German agricultural cooperatives absorb extended field-testing cycles for bio-based stabilizer formulations under REACH constraints.
- Consumer Goods:Brand-sensitive applications where optical properties and printability matter. Lower puncture requirements enable thinner gauge specifications than construction or agricultural grades.
- Chemicals:Hazardous material handling drives specification toward puncture-resistant blown structures with static-dissipative additives. Regulatory compliance with dangerous goods transport rules adds qualification complexity.
Contract volume concentrates in Construction Materials; Food Processing is expanding most quickly.
Packaging Format:
Supply concentration in roll formats reflects equipment integration requirements, while customized shapes capture margin from specialized agricultural and chemical applications.
- Rolls:Standard supply format for automated hooding equipment with continuous feed mechanisms. German machinery integrators specify roll dimensions that lock in film converter relationships.
- Customized Shapes:Pre-cut sleeves and gusseted tubes for irregular agricultural bulk containers. Premium positioning reflects setup changeover costs and smaller production runs.
- Sheets:Flat film for manual or semi-automated wrapping operations. Limited penetration in high-throughput construction material handling.
- Bags:Pre-formed hoods for low-volume or specialty chemical applications. Higher per-unit cost restricts deployment outside hazardous material handling.
- Tubes:Continuous seamless sleeves for specific agricultural grain handling systems. Narrow addressable market tied to legacy equipment installations.
Production gravity centers on Rolls; Customized Shapes are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor in western Germany concentrates automated palletizing infrastructure for cement and brick producers, establishing specification standards that ripple across European supply chains. German machinery integrators set equipment compatibility requirements that lock in film converter relationships across the continent.
Germany
Cement producers in the Ruhr and Bavaria operate Europe's densest concentration of automated hooding lines, generating captive demand for 100-120 micron blown film specifications. REACH compliance deadlines for fluorinated additive phase-out are forcing reformulation investments at converter facilities near Cologne and Frankfurt. The KBA transport safety framework influences load containment testing protocols adopted by machinery builders in Stuttgart.
France
Agricultural cooperatives in the Paris Basin and Provence-Alpes-Côte d'Azur negotiate just-in-time film availability contracts ahead of grain harvest volatility. ANSM food-contact regulations extend qualification timelines for coextruded barrier grades entering dairy processing applications. Brick manufacturers in Hauts-de-France are consolidating palletizing operations that standardize on hooding systems for transit stability.
United States
Construction material distributors in Texas and the Southeast operate high-throughput distribution centers favoring automated hooding over mechanical stretch wrapping. FDA migration limits on slip agents restrict film qualification for food processing contracts in California's Central Valley. Cement producers in the Midwest are compressing equipment replacement cycles as they consolidate palletizing lines.
China
Chemical producers in the Yangtze River Delta specify puncture-resistant blown structures with static-dissipative additives for hazardous material handling. GB standards for packaging dangerous goods add qualification complexity for converters serving Shanghai and Jiangsu province facilities. Agricultural bulk goods handlers in Shandong province are testing bio-based stabilizer formulations under MEE environmental compliance frameworks.
Italy
Food processors in Lombardy and Emilia-Romagna are qualifying coextruded hoods with EVOH barriers for modified atmosphere applications previously served by shrink bags. CE marking requirements for automated packaging machinery influence film specification standards adopted by machinery integrators near Bologna. Brick and tile producers in Veneto are transitioning from cast to blown film formats as they upgrade palletizing infrastructure.
Stretch Hood Films Market Key Industry Players
Capital-heavy resin producers compete with specialized film converters in a structure where backward integration into alpha-olefin feedstocks creates supply asymmetry. The vendor base clusters around three strategic archetypes: integrated petrochemical majors with captive catalyst technology, mid-scale converters competing on gauge reduction, and regional specialists serving agricultural just-in-time contracts. Dominant competitive moves include machinery integrator partnerships that bundle film supply with equipment service agreements, and R&D investments into mono-material PE architectures that maintain mechanical performance at reduced thickness.
Among integrated petrochemical majors, Exxon Mobil and Dow exemplify the catalyst-technology archetype, with the latter anchoring its position through upstream control over octene and hexene production. Manuli Stretch occupies a position within the specialized converter tier, representing competitive pressure on film gauge without sacrificing load containment force. These three entities illustrate how supply chain configuration and equipment integration capabilities determine competitive positioning in automated hooding applications.
| Leading Market Players |
|---|
| Exxon Mobil |
| Manuli Stretch |
| Dow |
| Charter Next Generation |
| Innovia Films |
| Berry Global Inc. |
| Sigma Plastics Group |
| Coveris Holdings S.A. |
| RKW Group |
| Others |
Cost & Logistics Intelligence
EU mandates for thinner, recyclable film structures are forcing converters to absorb reformulation costs while maintaining mechanical performance specifications, compressing margin structures and redrawing competitive boundaries around catalyst technology access.
Pricing Analysis
Cost-down pressure on standard blown film grades accelerates as German cement producers consolidate procurement volumes and demand extended payment terms. Three-tier pricing structure across premium metallocene-enhanced, standard LLDPE, and economy recycled-content levels separates converters by catalyst access and PCR qualification status. Price differentiation hinges on gauge reduction capability and REACH-compliant additive packages. Smaller construction material yards in southern Europe exhibit highest price sensitivity, while automated palletizing lines in Germany prioritize uptime guarantees over per-kilogram film costs.
Supply Chain Analysis
Alpha-olefin feedstock supply rests on integrated petrochemical complexes in the United States, western Europe, and the Middle East Gulf. Octene and hexene co-monomer availability, metallocene catalyst manufacturing, and specialized blown film extrusion equipment constitute critical input dependencies. Single-source vulnerability concentrates in catalyst technology holders who license narrow MWD resin production capabilities. Distribution runs through machinery integrator partnerships that bundle film supply with automated hooding equipment service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical compliance deadlines and metallocene catalyst expertise scarcity are forcing sub-scale converters toward exit or acquisition, consolidating competitive position around integrated resin producers and specialized equipment-integrated suppliers.
For Market Incumbents: Anticipate fluorinated additive phase-out timelines by accelerating bio-based stabilizer field-testing partnerships with French agricultural cooperatives. Lock in machinery integrator exclusivity through maintenance contract bundling that raises switching costs for German cement producers. Prioritize backward integration into octene supply or captive catalyst licensing to defend margin position against Dow's upstream control. For New Entrants and Emerging Players: Begin with agricultural just-in-time availability contracts in France and Shandong province, where seasonal volatility and bio-based formulation requirements create specification gaps that integrated majors underserve. Target coextruded barrier grades for food processing applications in Italy's Emilia-Romagna dairy corridor, where EVOH integration complexity deters commodity converters. Pursue equipment-agnostic positioning that separates film supply from machinery service relationships. For Investors and Strategic Acquirers: The window for entry favors mid-scale converters with qualified mechanical recycling supply chains and existing machinery integrator relationships in Germany or France. Long-term viability hinges on PCR content mandate compliance ahead of regulatory deadlines. Watch for inflection signals in cement sector equipment replacement cycle announcements and ECHA sunset date enforcement patterns for perfluorinated substances.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Production | Dow's captive octene supply anchors cost position against independent converters lacking monomer access. |
| Machinery Integrator Partnership Expansion | Exxon Mobil's catalyst-technology bundling with German equipment builders locks in specification standards. |
| Mechanical Recycling Certification Investment | Post-consumer content mandates in France and Germany will disqualify non-qualified converters from public procurement. |
| Bio-Based Stabilizer Formulation Development | REACH sunset dates for fluorinated additives force 12-18 month reformulation cycles that strain mid-tier R&D capacity. |
| Coextruded Barrier Grade Capacity Addition | EVOH integration capabilities open food processing applications previously served by shrink bag competitors in Italy. |
Research Approach
Document review covered customs and trade flow databases, EU regulatory filings through ECHA and national competent authorities, SEC 10-K disclosures from integrated petrochemical majors, and machinery builder technical specifications, complemented by interviews with blown film extrusion plant managers, procurement leads at German cement producers, French agricultural cooperative supply directors, and technical R&D directors at catalyst technology licensors. Bottom-up volume modeling triangulated against top-down resin demand allocation across the analysis window.
Segment-level value outputs derived from film type, application intensity, end-use industry regulatory exposure, and regional automation maturity dimensions modeled across the projection horizon. CAGRs were computed from annualized shipment data reconciled against machinery installation records and palletizing line upgrade announcements. Key inputs included metallocene polyethylene penetration rates by country and REACH compliance cost pass-through assumptions.
Feedstock price volatility, ECHA enforcement timing, and cement sector capital expenditure cycles are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about catalyst technology licensing availability and machinery integrator consolidation patterns. A concentrated set of regulatory and procurement triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Insulation Film Market
Packaging Barrier Films
Moisture Barrier Bags Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Barrier Foil Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Saudi Arabia Plastic Packaging Films Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market