
 Global Medical Packaging Films Market | 2026-2036
Global Medical Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Packaging Films Market Foresight
European flexible film producers is consolidating output around multi-layer coextrusion lines serving Class II and III medical devices. Amcor plc leverages vertical integration from resin compounding to sterile converting across its healthcare network. Berry Global Inc. anchors North American supply through blown film capacity dedicated to pharmaceutical pouching. Sealed Air differentiates via cleanroom-certified manufacturing for diagnostic device packaging.
Medical packaging films are multi-layer polymer laminates, typically 50–250 micron thickness, engineered to maintain sterile barrier integrity through EO, gamma, or steam sterilization cycles while permitting gas permeation control. Their primary purpose is to protect instruments, implants, and pharmaceuticals from microbial ingress and environmental degradation through shelf life. Polyethylene dominates volume in pouch and sachet formats due to seal reliability and cost efficiency, while polyester leads in blister pack lidding where dimensional stability and printability command premium positioning. Nylon coextrusions occupy the fastest-growing niche in vacuum-sealed implant packaging where puncture resistance and oxygen barrier performance justify higher unit economics.
FDA 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements shape material validation protocols, forcing film suppliers to maintain batch-level extractables and leachables data. ISO 11607 standards for sterile barrier systems directly determine seal strength, peelability, and accelerated aging test regimes that manufacturers must pass before commercial release. Stakeholders must monitor evolving EPA and ECHA restrictions on per- and polyfluoroalkyl substances, as PFAS-free alternatives will require reformulation of high-barrier multilayer structures without compromising sterilization compatibility.
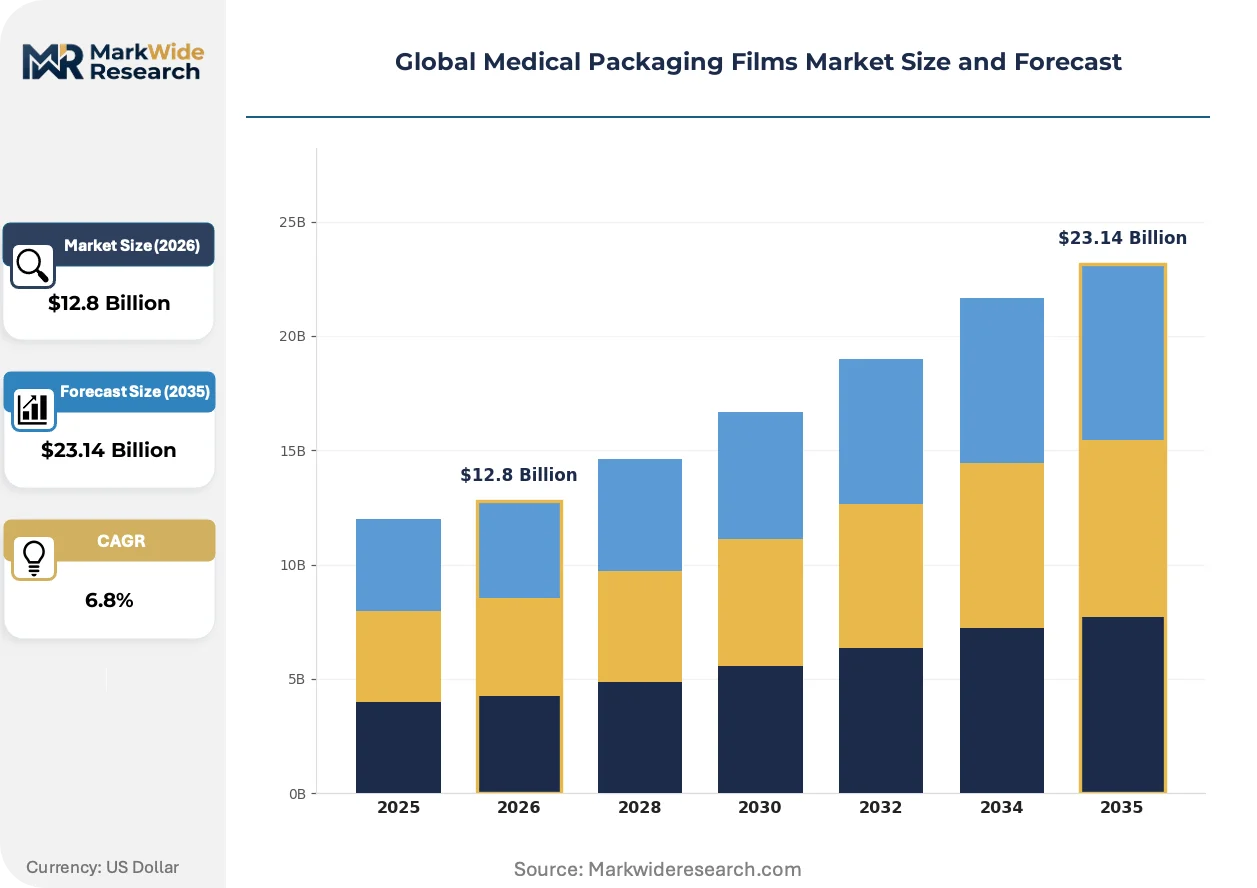
Market Dynamics
Multi-layer coextrusion technology is compressing the supplier base as pharmaceutical manufacturers consolidate purchasing around film converters capable of ISO 11607-validated sterile barrier production at scale.
Growth Catalysts
- EU MDR traceability mandates:Device manufacturers in Germany and Ireland now require batch-level extractables documentation, pulling demand toward certified film suppliers with dedicated healthcare converting lines.
- Implant packaging specifications:Orthopedic device producers specify nylon coextrusions for vacuum-sealed barrier systems where puncture resistance and oxygen exclusion extend shelf stability.
- Sterilization modality diversification:Gamma and EO sterilization cycles dominate Class II device packaging, with steam-compatible high-temperature films gaining share in surgical instrument kits.
Market Restraints
- Resin cost volatility:Polyethylene and polyester feedstock prices fluctuate with naphtha and paraxylene markets, compressing converter margins on fixed-price pharmaceutical contracts.
- Cleanroom capacity concentration:Sterile film converting capacity clusters in southern Germany, the US upper Midwest, and Japan's Kansai region, creating geographic supply risk for device manufacturers elsewhere.
- PFAS regulatory friction:EPA and ECHA restrictions on per- and polyfluoroalkyl substances threaten existing high-barrier multilayer structures, forcing reformulation without proven alternatives.
Strategic Opportunities
- India pharmaceutical export growth:CDSCO-aligned contract manufacturers in Hyderabad and Ahmedabad seek ISO-certified pouch films for US and EU-bound generic drug exports.
- Biologics cold-chain expansion:Temperature-stable barrier films with integrated desiccant layers address mRNA vaccine and cell therapy transport requirements.
- Sustainable material incentives:EU Green Deal circular economy requirements and extended producer responsibility schemes favor recyclable mono-material structures over multilayer laminates.
Industry Challenges
- Accelerated aging validation timelines:ISO 11607 real-time and accelerated aging protocols demand 6-24 month stability documentation before commercial release, slowing new product introduction.
- Extractables testing capacity constraints:Specialized analytical chemistry for USP Class VI and ISO 10993 biocompatibility screening faces backlog at certified laboratories in Switzerland and the US.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Packaging Films Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $23.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Polyester, Nylon, Polycarbonate Application: Surgical Kits, Diagnostic Devices, Pharmaceutical Blister Packs, Implant Packaging, Medical Instruments, Wound Care End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Pharmaceutical Manufacturers, Health Clinics, Specialized Care Centers Packaging Type: Blister Packs, Pouches, Sachets, Sterile Wraps, Vacuum Seals, Heat-Sealed Packs |
| Companies Covered | Klöckner Pentaplast Group, Uflex Ltd., Amcor plc, Sealed Air, Wipak Group, Berry Global Inc., Constantia Flexibles Group GmbH, Tekni-Plex, Inc., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Packaging Films Market Shifts & Advancements
Material science advances and regulatory tightening are converging to reshape sterile barrier specifications, with sustainability mandates and sterilization compatibility emerging as the dominant technical battlegrounds.
High-barrier cyclic olefin copolymer films are consolidating position in diagnostic device packaging where moisture and oxygen exclusion preserve reagent stability. In-vitro diagnostic manufacturers in the US and Germany specify these materials for lateral flow cassettes and microfluidic cartridges. The technology is consolidating supply relationships around converters with captive resin compounding and cleanroom slitting capabilities.
REACH restrictions on fluorinated compounds and EPA PFAS action plans are forcing reformulation of legacy high-barrier structures. Film suppliers must validate alternative oxygen and moisture barriers without sacrificing steam or gamma sterilization compatibility. European medical device manufacturers face the most immediate compliance pressure, with technical documentation deadlines under EU MDR Article 10 accelerating material qualification cycles.
Pharmaceutical procurement departments now specify total cost of ownership metrics extending beyond unit price to include validation support, regulatory filing assistance, and supply assurance commitments. Large molecule drug sponsors in the US Northeast and Switzerland negotiate multi-year film supply agreements with dedicated capacity clauses. This contracting pattern concentrates volume among converters with healthcare-dedicated assets and regulatory affairs staffing.
Global Medical Packaging Films Market Segmentation
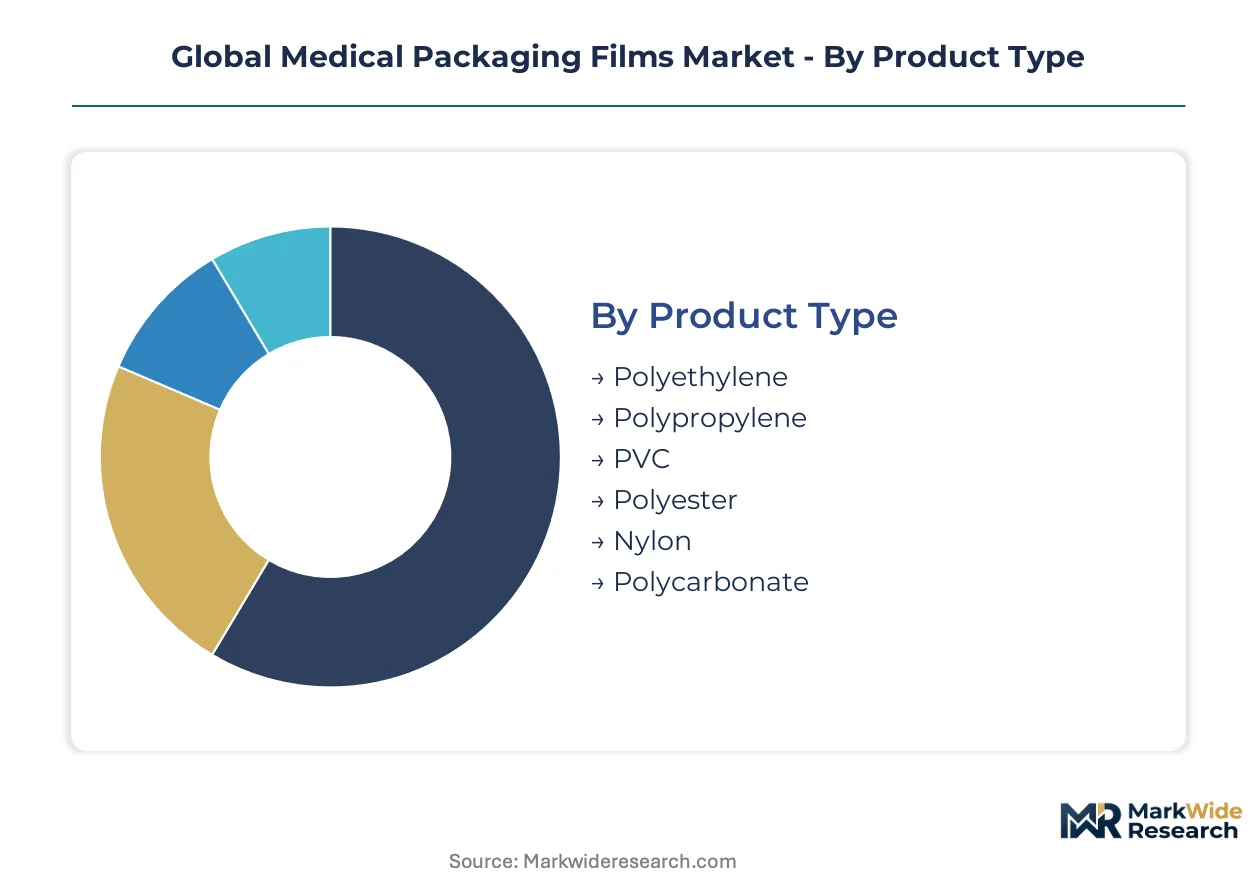
Medical packaging film specifications diverge sharply across polymer chemistry, sterilization modality, and barrier requirements. Each segment carries distinct regulatory validation burdens and margin structures that reshape supplier economics.
Product Type:
Polyethylene dominates volume throughput while polyester and nylon command premium positioning through specialized barrier performance.
- Polyethylene:Linear low-density and metallocene grades provide seal reliability and cost efficiency for high-volume pouch and sachet formats. Pharmaceutical manufacturers in India and Brazil specify PE for generic drug exports where unit economics dominate procurement decisions.
- Polyester:Biaxially oriented PET films deliver dimensional stability and printability for blister pack lidding where premium branding commands price premiums. German and Swiss device manufacturers specify polyester for diagnostic device visibility requirements.
- Polypropylene:Cast PP films serve steam-sterilization applications with higher temperature tolerance than PE alternatives.
- PVC:Rigid PVC maintains position in legacy pharmaceutical blister formats despite environmental scrutiny.
- Nylon:Coextruded nylon structures provide puncture resistance for orthopedic implant vacuum packaging.
- Polycarbonate:High-clarity films serve diagnostic cartridge applications requiring optical readability.
Mature deployment sits with polyethylene. Newer deployment is concentrated in nylon coextrusions for implant barrier systems.
Application:
Surgical and diagnostic applications anchor current volume while biologics cold-chain requirements are expanding fastest.
- Surgical Kits:Multi-instrument sterile barrier systems require puncture-resistant laminates with peelable seal interfaces. US hospital purchasing consortiums specify ISO 11607-validated films with 5-year shelf stability documentation.
- Diagnostic Devices:Lateral flow cassettes and microfluidic cartridges demand moisture and oxygen exclusion through cyclic olefin copolymer or high-barrier polyester structures. German and US in-vitro diagnostic manufacturers consolidate supply around converters with captive resin compounding.
- Pharmaceutical Blister Packs:Unit-dose oral solid formats specify lidding foils with push-through or peel-open child resistance.
- Implant Packaging:Orthopedic and cardiovascular devices require vacuum-sealed nylon coextrusions with oxygen transmission below 0.1 cc/m²/day.
- Medical Instruments:Reusable surgical tool packaging specifies steam-compatible high-temperature films.
- Wound Care:Advanced dressing formats use breathable polyurethane films with controlled moisture vapor transmission.
Procurement centralization favors surgical kit suppliers with dedicated healthcare converting lines. Implant packaging specifications are climbing the fastest as EU MDR traceability mandates intensify documentation requirements.
End User:
Hospital systems drive standardization while pharmaceutical manufacturers impose the most stringent validation protocols.
- Hospitals:Integrated delivery networks in the US and NHS trusts in England consolidate purchasing around sterile barrier systems with established supply assurance records.
- Ambulatory Surgical Centers:Outpatient procedure growth in Germany and Japan generates demand for pre-sterilized kit formats with reduced handling requirements.
- Diagnostic Laboratories:Reference labs and point-of-care testing networks specify film packaging with integrated desiccant layers for reagent stability.
- Pharmaceutical Manufacturers:Large molecule sponsors in Switzerland and the US Northeast negotiate multi-year supply agreements with dedicated capacity clauses and regulatory filing support.
- Health Clinics:Primary care vaccination programs require temperature-stable barrier films for cold-chain distribution.
- Specialized Care Centers:Dialysis and oncology infusion centers specify unit-dose packaging with tamper-evident features.
Contracting patterns concentrate volume among pharmaceutical manufacturers with the longest validation timelines. Ambulatory surgical centers are expanding most quickly as procedure migration accelerates.
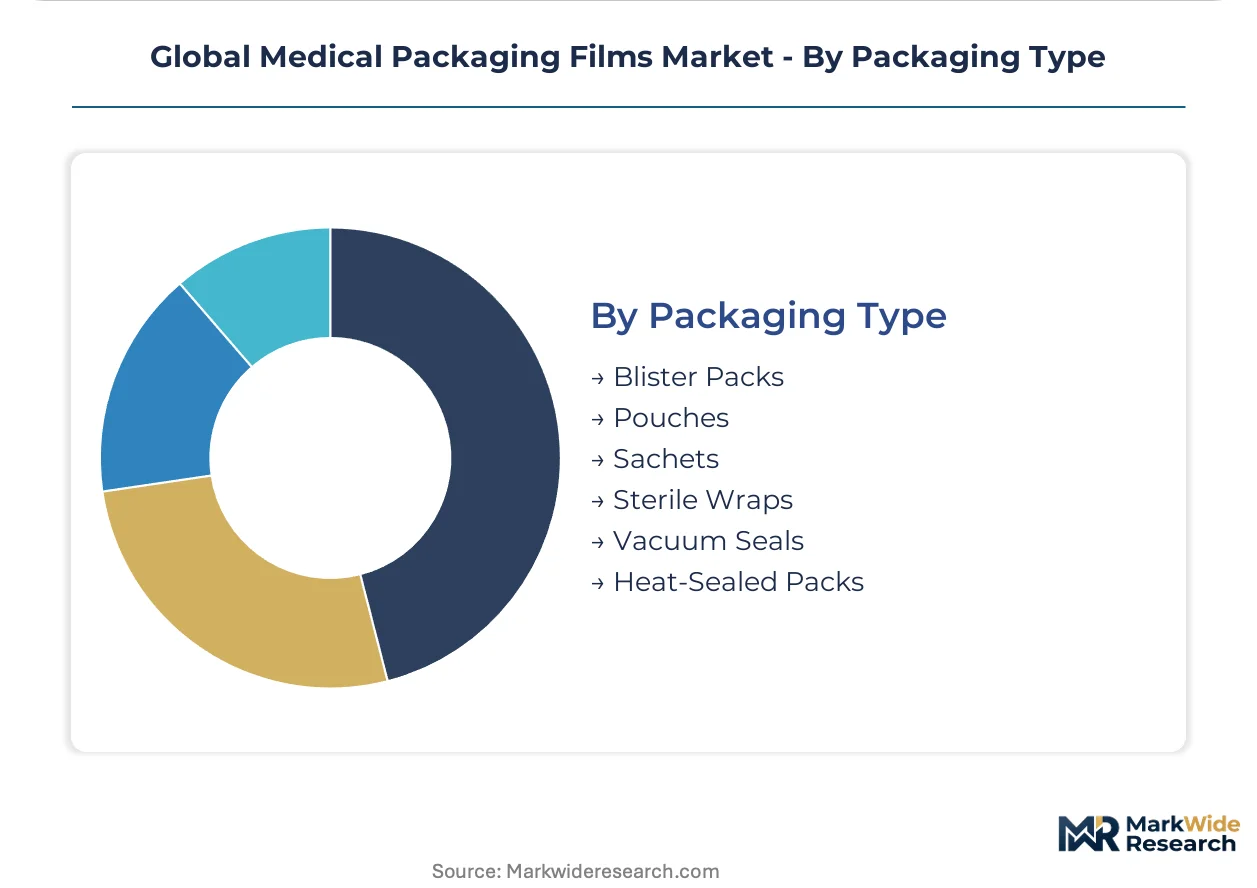
Packaging Type:
Pouch formats dominate unit volume while vacuum seals and sterile wraps capture premium positioning through specialized barrier performance.
- Blister Packs:Thermoformed cavities with lidding seals provide unit-dose protection for oral solids and diagnostic devices. European pharmaceutical manufacturers specify cold-form foil alternatives to aluminum for sustainability compliance.
- Pouches:Three-side-seal and stand-up formats serve the broadest application range from surgical instruments to pharmaceutical sachets. Indian and Chinese contract manufacturers specify PE-based pouches for cost-sensitive generic exports.
- Sachets:Single-dose flexible formats accommodate powder and liquid pharmaceuticals with tear-notch accessibility.
- Sterile Wraps:SMS nonwoven laminates provide breathable barrier protection for surgical instrument sterilization.
- Vacuum Seals:Nylon coextrusion-based formats exclude oxygen for implant shelf life extension.
- Heat-Sealed Packs:Custom-shaped formats accommodate irregular device geometries with validated seal strength protocols.
Standardized pouch formats anchor volume procurement. Vacuum seal specifications are gaining share fastest as orthopedic device manufacturers extend implant shelf stability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naphtha feedstock availability in the US Gulf Coast and paraxylene production in East Asia anchor polyethylene and polyester supply chains serving medical film converters worldwide.
United States
Hospital purchasing consortiums and diagnostic device manufacturers drive sterile barrier demand. FDA 21 CFR Part 820 quality system regulations enforce batch-level extractables documentation. The upper Midwest hosts concentrated cleanroom converting capacity for pharmaceutical pouching.
Germany
EU MDR traceability mandates pull device manufacturers toward certified film suppliers. ECHA restrictions on fluorinated compounds accelerate PFAS-free reformulation timelines. The Tuttlingen-Freiburg medical technology cluster concentrates orthopedic implant packaging specifications.
India
Contract manufacturers in Hyderabad and Ahmedabad seek ISO-certified pouch films for generic drug exports. CDSCO alignment with international standards enables US and EU-bound pharmaceutical shipments. Western India hosts expanding blown film capacity dedicated to pharmaceutical applications.
Japan
PMDA biocompatibility requirements shape material validation protocols for domestic device manufacturers. METI industrial standards support high-barrier film development for diagnostic applications. The Kansai region maintains sterile converting infrastructure serving domestic and export markets.
Switzerland
Large molecule drug sponsors negotiate multi-year supply agreements with dedicated capacity clauses. Swissmedic technical documentation requirements accelerate material qualification cycles. The Basel-Zurich corridor concentrates pharmaceutical packaging procurement decision-making.
Global Medical Packaging Films Market Competitive Landscape
Global majors compete with regional champions across sterile barrier certification and healthcare-dedicated asset bases. The supplier base compresses around multi-layer coextrusion specialists capable of ISO 11607-validated production at scale. Three archetypes dominate: vertically integrated resin-to-film converters, healthcare-focused specialists with captive cleanroom capacity, and diversified packaging groups with healthcare divisions. Competitive moves center on M&A to secure healthcare-dedicated assets and capacity expansion in regulatory-advantaged geographies.
Within the integrated converter tier, Amcor plc and Berry Global Inc. exemplify scale-driven positioning through healthcare network coverage. Sealed Air occupies a specialist position emphasizing cleanroom-certified manufacturing infrastructure. These three represent distinct strategic postures: backward integration into resin compounding, North American blown film concentration, and diagnostic device packaging focus respectively.
| Leading Market Players |
|---|
| Klöckner Pentaplast Group |
| Uflex Ltd. |
| Amcor plc |
| Sealed Air |
| Wipak Group |
| Berry Global Inc. |
| Constantia Flexibles Group GmbH |
| Tekni-Plex, Inc. |
| DuPont de Nemours, Inc. |
| Others |
Supply & Pricing Matrix
Multi-layer coextrusion line deployment in southern Germany and the US upper Midwest simultaneously compresses per-unit conversion costs and concentrates supply leverage among ISO 11607-certified converters. Pharmaceutical manufacturers with dedicated capacity clauses now extract pricing concessions from film suppliers locked into fixed-price contracts amid volatile naphtha and paraxylene feedstock markets.
Pricing Analysis
Validation support bundling separates premium-tier film suppliers from commodity converters competing purely on unit price. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by ISO 11607 certification grade and batch-level extractables documentation. Cost compression in standard-tier polyethylene pouch films is intensifying because Indian and Chinese contract manufacturers prioritize unit economics for generic drug exports. Pharmaceutical manufacturers with large molecule pipelines exhibit lowest price sensitivity due to regulatory filing support requirements.
Supply Chain Analysis
Specialty resin compounding rests on captive production facilities in Germany, the United States, and Japan serving healthcare-dedicated film converters. Naphtha-derived polyethylene pellets, biaxially oriented polyester substrates, and nylon barrier layers constitute critical input dependencies. Single-source vulnerability concentrates in southern Germany's Tuttlingen-Freiburg cluster where orthopedic implant packaging specifications dominate capacity allocation. Distribution runs through pharmaceutical contract manufacturers and device OEMs with multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
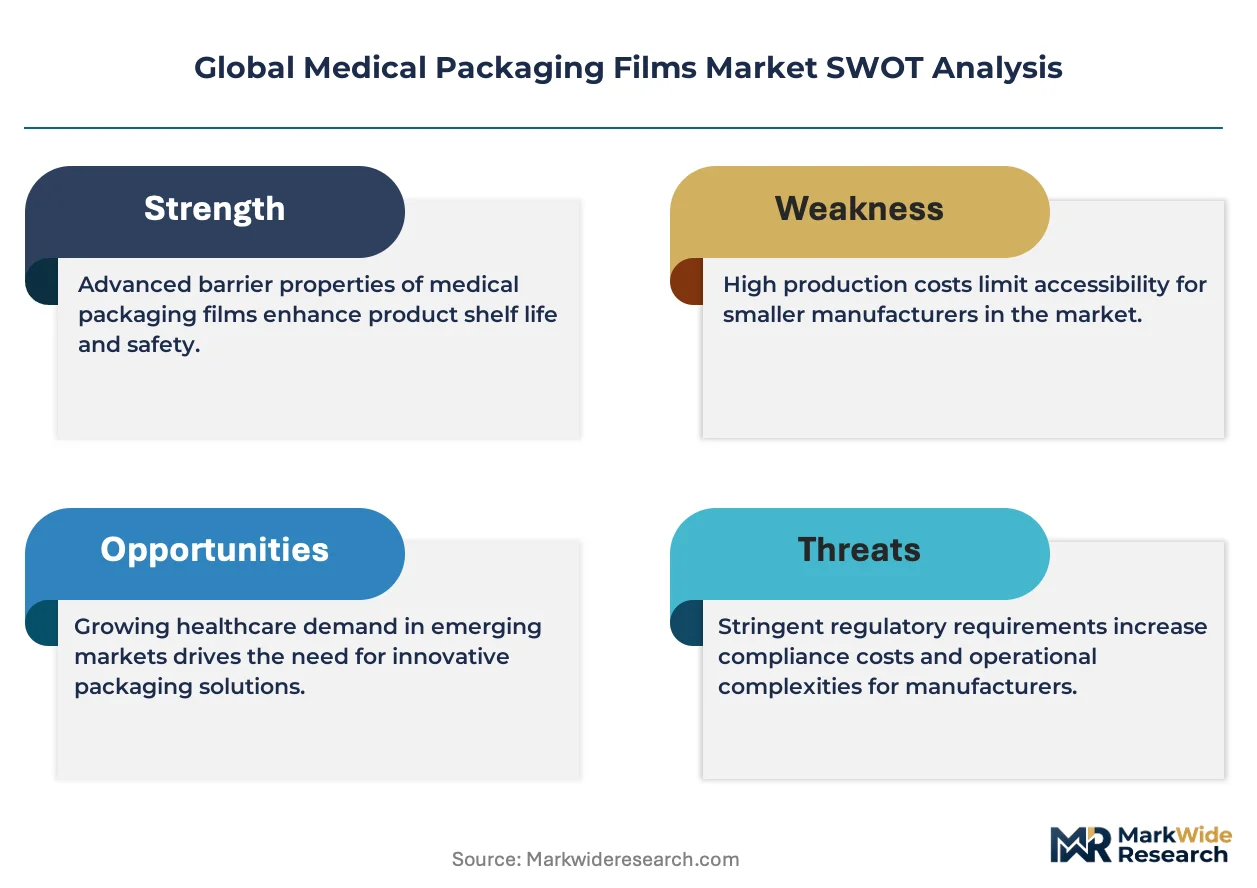
EU MDR traceability mandates and PFAS regulatory friction are forcing sub-scale converters without healthcare-dedicated assets toward exit or acquisition, consolidating viable supply around certified multi-layer specialists.
For Market Incumbents: Deepen backward integration into resin compounding to secure input cost control against naphtha volatility. Expand cleanroom converting capacity in regulatory-advantaged geographies such as Switzerland and the US upper Midwest to capture pharmaceutical manufacturer procurement consolidation. PFAS-free reformulation timelines threaten converters lacking R&D scale.
For New Entrants and Emerging Players: Capture white-space demand from Indian pharmaceutical exporters in Hyderabad and Ahmedabad seeking ISO-certified pouch films for US and EU-bound generic shipments. Target biologics cold-chain applications with temperature-stable barrier films integrating desiccant layers. Partner with CDSCO-aligned contract manufacturers for regulatory pathway acceleration.
For Investors and Strategic Acquirers: Exit pathways concentrate in healthcare-dedicated converters with captive cleanroom infrastructure and established pharmaceutical customer relationships. Long-term viability over the next decade hinges on PFAS-free barrier technology readiness and EU MDR technical documentation capabilities. Watch EPA and ECHA regulatory enforcement intensity as inflection indicator for asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Barrier Reformulation | ECHA restrictions force material requalification without proven oxygen barrier alternatives. |
| Healthcare-Dedicated Capacity Expansion | Cleanroom-certified lines in Germany and US upper Midwest capture pharmaceutical procurement consolidation. |
| Backward Integration into Resin Compounding | In-house polyethylene and polyester production insulates margins from naphtha feedstock volatility. |
| ISO 11607 Validation Investment | Batch-level extractables documentation satisfies EU MDR traceability mandates for Class III devices. |
| Biologics Cold-Chain Film Development | Temperature-stable barriers with integrated desiccant address mRNA vaccine transport requirements. |
Research Methodology
Trade association filings, customs import records, and pharmaceutical regulatory submissions formed the secondary backbone of this analysis. Primary interviews with film converter plant managers, pharmaceutical procurement directors, biomedical packaging engineers, and GPO contracts managers validated supply-side capacity data and demand-side specification trends. Bottom-up triangulation across polymer throughput volumes and top-down cross-check against sterile barrier system deployment rates ensured segmentation consistency.
Historical trendline analysis of medical packaging film shipments established baseline growth patterns across the projection horizon. Segmentation modeling incorporated polymer chemistry, sterilization modality compatibility, barrier performance tier, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Forecast inputs included orthopedic implant procedure volumes and diagnostic device production indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA PFAS enforcement actions and EU MDR implementation delays. Forecasts reflect documented assumptions regarding resin cost trajectories and sterilization modality adoption rates. A small set of named triggers—including ECHA fluorinated compound restrictions and CDSCO alignment pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Insulation Film Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Microwavable Barrier Films Market