
 Global High Barrier Packaging Films Market | 2026-2036
Global High Barrier Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Barrier Packaging Films Market Analysis
Modular pouch configurations with resealable fitments is rebalancing buyer preference away from rigid containers in ready-meal and pharmaceutical applications. Amcor plc leverages its integrated film-to-pouch manufacturing footprint across North America and Europe to sustain price competitiveness in retort-compatible structures. Sealed Air Corporation anchors its position through proprietary vacuum skin packaging technologies that extend protein shelf life. Mondi Group differentiates via kraft-paper-barrier hybrid solutions that navigate rising paper-based packaging mandates in the EU.
Global High Barrier Packaging Films are multilayer polymer structures, typically incorporating ethylene vinyl alcohol copolymers or aluminum oxide vapor-deposited layers at thicknesses below twelve micrometers, engineered to restrict oxygen transmission below one cubic centimeter per square meter per day and water vapor transmission below one gram per square meter per day. These specifications preserve sensory quality and safety in oxygen-sensitive foodstuffs, sterile medical devices, and moisture-critical electronics throughout distribution cycles. Polyethylene dominates volume production due to its heat-seal compatibility and cost position in frozen food and snack applications, though polyester is capturing margin pools in pharmaceutical blister lidding where dimensional stability and optical clarity command premium positioning. Metallized films sustain leadership in savory snack and confectionery sectors where metallic aesthetics combine with functional oxygen barrier, while biodegradable films represent the fastest-growing material trajectory as brand owners face compliance deadlines under extended producer responsibility frameworks.
The FDA enforces stringent extractables and leachables testing for pharmaceutical-contact barrier films under container closure system guidelines, while the EU F-Gas Regulation restricts hydrofluorocarbon use in foam-laminated barrier structures and REACH mandates disclosure of Substances of Very High Concern in adhesive lamination chemistries. These overlapping compliance obligations elevate R&D expenditure thresholds and favor suppliers with established regulatory dossiers and toxicology testing capabilities. Stakeholders must monitor pending revisions to FDA guidance on post-consumer recycled content incorporation into food-contact layers, as these determinations will reshape material qualification timelines and capital allocation toward coextrusion equipment capable of processing recycled feedstocks without compromising barrier integrity.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing qualification timelines for multilayer structures, forcing converters to accelerate recyclability redesigns while maintaining oxygen transmission specifications below one cubic centimeter per square meter per day.
Growth Catalysts
- Pharmaceutical cold-chain logistics:Temperature-sensitive biologics distribution across Germany's Frankfurt-Ludwigshafen corridor is pulling demand for ethylene vinyl alcohol copolymer multilayer solutions with cryogenic integrity.
- REACH SVHC disclosure mandates:Substances of Very High Concern tracking requirements are consolidating supplier relationships toward toxicology-tested adhesive laminators with established dossiers.
- Retort-compatible flexible pouches:Ready-meal processors in North America are displacing rigid trays with high-temperature sterilizable film structures that reduce freight cube by forty percent.
Market Restraints
- Aluminum oxide deposition capacity:Vapor-deposition equipment for sub-twelve-micrometer barrier layers concentrates among Japanese and German equipment builders, creating eighteen-month lead times for new capacity.
- Post-consumer recycled feedstock contamination:FDA guidance uncertainty on food-contact layer incorporation is freezing capital allocation toward coextrusion lines capable of processing recycled polyethylene.
- Mono-material substitution pressure:Polypropylene barrier films with equivalent oxygen transmission specifications are capturing share in frozen vegetable applications where optical clarity requirements are minimal.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO serialization requirements for export-oriented blister packaging are creating qualification windows for polyester-barrier film suppliers with track-and-trace integration capabilities.
- Kraft-paper-barrier hybrids:EU Green Deal paper-based packaging mandates are opening margin pools for converters combining cellulose substrates with vapor-deposited aluminum oxide functional layers.
- Biodegradable film convergence:Polyhydroxyalkanoate barrier structures with polylactic acid seal layers are penetrating premium organic snack channels where extended producer responsibility fees apply.
Industry Challenges
- Multilayer delamination expertise:Separating incompatible polymer layers for mechanical recycling requires solvent-based or thermal processes that exceed current operational capabilities at most European converters.
- Extractables and leachables documentation:FDA container closure system testing timelines for new pharmaceutical-contact films extend qualification cycles to thirty-six months, compressing product lifecycle returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Barrier Packaging Films Market |
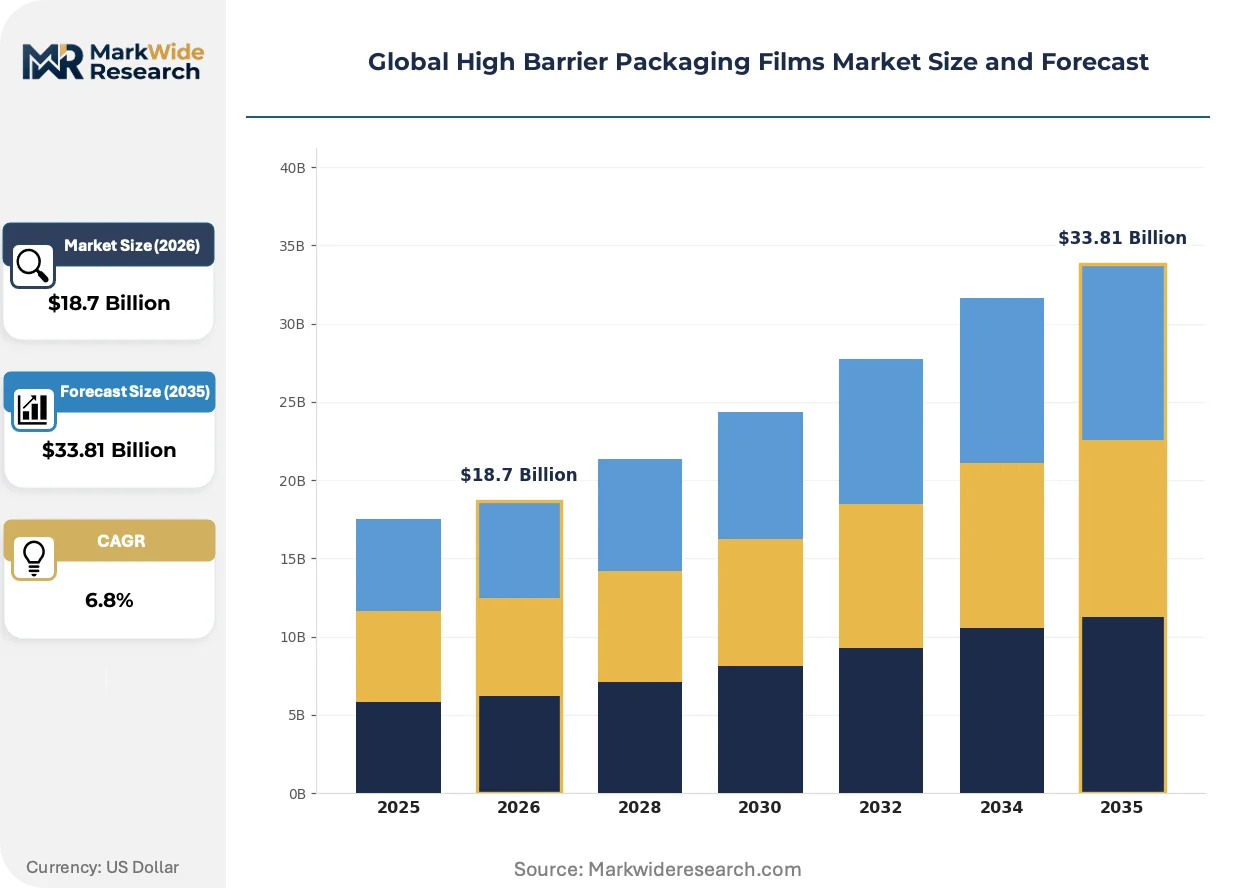
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyester, Nylon Application: Food Packaging, Medical Packaging, Pharmaceuticals, Electronics Material: Metallized Films, Coated Films, Laminated Films, Biodegradable Films End Use Industry: Food & Beverage, Healthcare, Consumer Goods, Industrial |
| Companies Covered | Amcor plc, Sealed Air Corporation, Berry Global Inc., Mondi Group, Huhtamaki Oyj, Constantia Flexibles, Winpak Ltd., Toray Industries, Inc., Uflex Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Barrier Packaging Films Market Emerging Trajectories
Barrier film architecture is converging toward thinner, higher-functioning structures as deposition precision and polymer rheology advance simultaneously. Three developments are compressing conventional specification boundaries.
Atomic layer deposition of aluminum oxide is unifying nanometer-scale barrier precision with mechanical flexibility previously exclusive to thicker metallized films. Pharmaceutical blister manufacturers in Switzerland and Japan are qualifying these structures for moisture-critical solid-dose applications. The technology is unifying optical clarity requirements with water vapor transmission specifications below 0.5 grams per square meter per day, collapsing the traditional trade-off between barrier performance and visual inspection capability.
REACH F-Gas Regulation restrictions on hydrofluorocarbon blowing agents are eliminating foam-laminated barrier structures from EU medical device packaging applications. Converters are pivoting toward solid polyethylene or ionomer foam alternatives with equivalent cushioning properties. German orthopedic device manufacturers are absorbing twelve to eighteen percent material cost increases while requalifying sterilization barrier systems for ethylene oxide and gamma radiation compatibility.
Consolidated buying desks at North American protein processors are compressing supplier rosters from twelve to three qualified film vendors per facility. Volume commitments now span thirty-six-month horizons with price-adjustment clauses tied to polyethylene resin indices. This concentration is most visible in vacuum skin packaging for fresh beef and pork, where Sealed Air Corporation's proprietary technologies have captured disproportionate share among top-ten US meatpackers.
Global High Barrier Packaging Films Market Segmentation
Barrier film specifications diverge sharply across end-use requirements, with oxygen transmission rates and sterilization compatibility determining material selection. Segmentation reveals where commodity polymers compete on cost and where specialty structures command premium positioning.
Product Type:
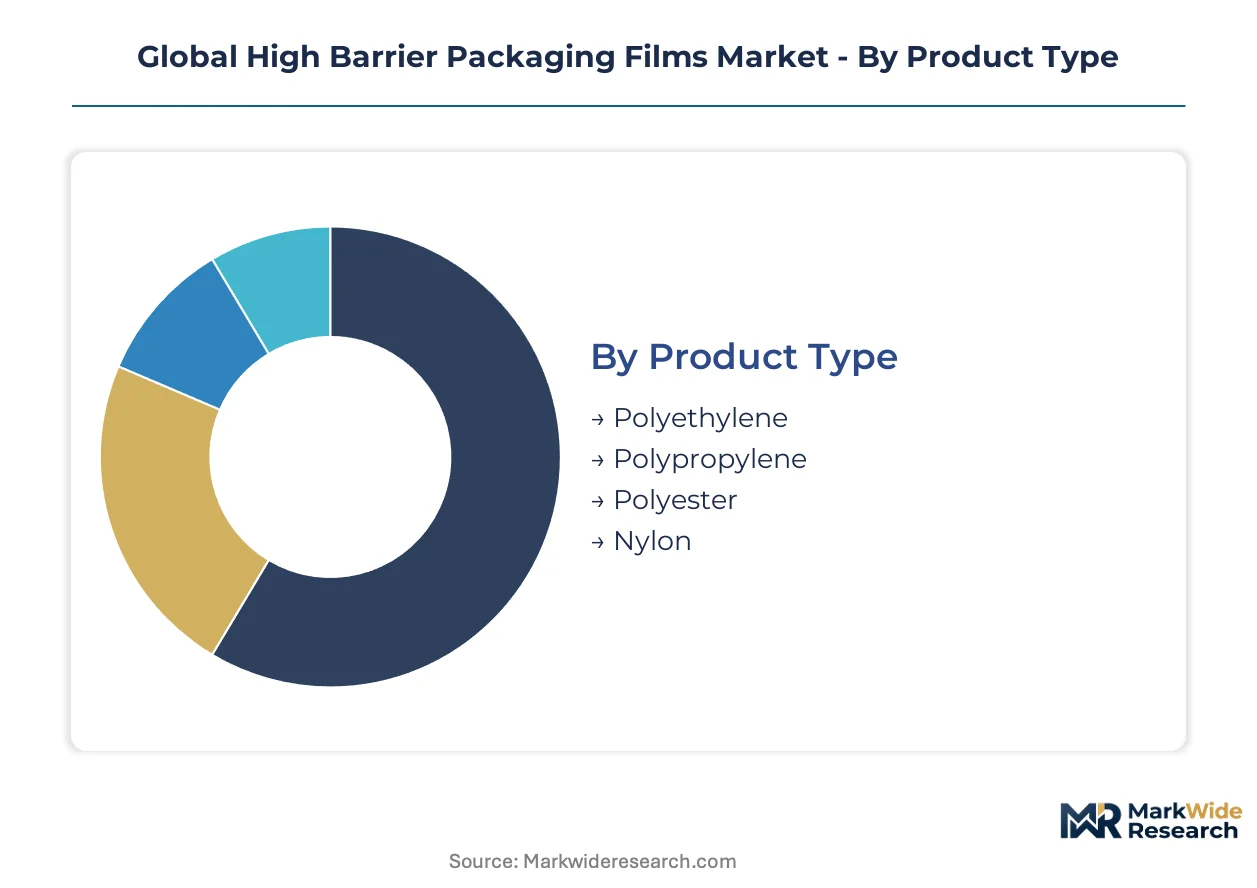
Polyethylene dominates frozen food and snack volumes while polyester captures pharmaceutical premium tiers.
- Polyethylene:Heat-seal compatibility and cost efficiency anchor frozen vegetable and snack applications. Demand concentrates in North American retail private-label channels where freight cube reduction drives flexible pouch adoption over rigid alternatives.
- Polyester:Dimensional stability and optical clarity command blister lidding applications for moisture-critical solid-dose pharmaceuticals. Swiss and Japanese manufacturers are qualifying atomic-layer-deposited variants with water vapor transmission below 0.5 grams per square meter per day.
- Polypropylene:Mono-material substitution pressure is capturing frozen vegetable share where optical clarity requirements are minimal.
- Nylon:Puncture resistance and thermoformability serve vacuum skin packaging for fresh protein distribution.
Today's leader: Polyethylene. Tomorrow's challenger: Polyester.
Application:
Food packaging absorbs volume while pharmaceutical cold-chain logistics accelerates multilayer qualification.
- Food Packaging:Retort-compatible flexible pouches displace rigid trays in ready-meal processing, cutting freight cube by forty percent. North American protein processors are consolidating supplier rosters to three qualified vendors per facility.
- Pharmaceuticals:Temperature-sensitive biologics distribution across Germany's Frankfurt-Ludwigshafen corridor pulls demand for ethylene vinyl alcohol copolymer structures with cryogenic integrity. FDA extractables and leachables testing extends qualification cycles to thirty-six months.
- Medical Packaging:REACH F-Gas restrictions eliminate foam-laminated structures, forcing pivot to solid polyethylene alternatives with equivalent cushioning.
- Electronics:Moisture-critical component protection drives vapor-deposited aluminum oxide specifications below twelve micrometers.
Food packaging holds volume dominance. Pharmaceutical applications show the steepest expansion trajectory.
Material:
Metallized films sustain savory snack leadership while biodegradable structures penetrate premium organic channels.
- Metallized Films:Metallic aesthetics combine with functional oxygen barrier in confectionery and savory snack sectors. Japanese and German equipment builders control vapor-deposition capacity, creating eighteen-month lead times for expansion.
- Biodegradable Films:Polyhydroxyalkanoate barrier structures with polylactic acid seal layers penetrate organic snack channels where extended producer responsibility fees apply. EU Green Deal compliance deadlines accelerate brand owner adoption.
- Coated Films:Atomic layer deposition unifies nanometer-scale precision with mechanical flexibility for pharmaceutical blister applications.
- Laminated Films:Multilayer delamination challenges constrain European mechanical recycling capabilities.
Metallized films defend incumbent position. Biodegradable films gain regulatory tailwinds fastest.
End Use Industry:
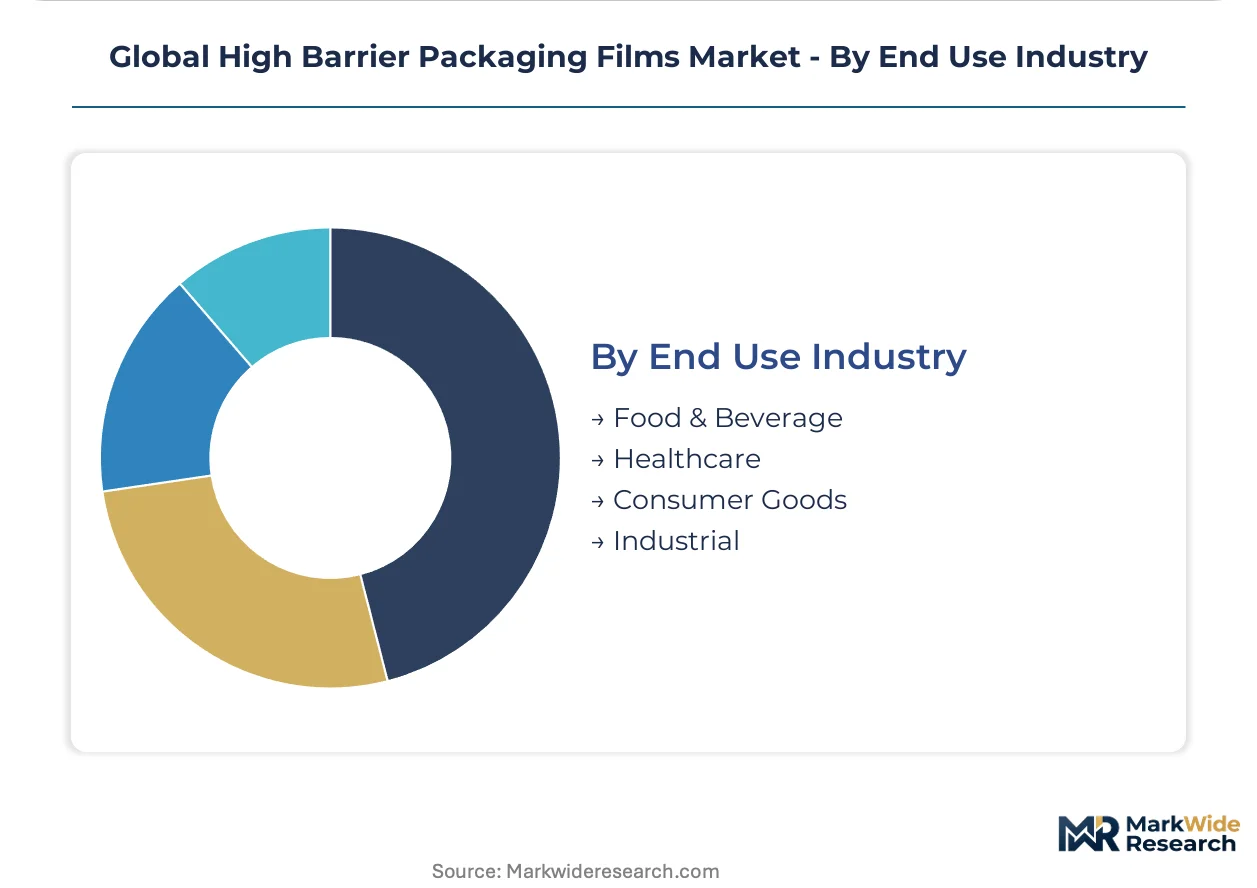
Food and beverage commands resin tonnage while healthcare drives specification intensity.
- Food & Beverage:Modular pouch configurations with resealable fitments rebalance buyer preference away from rigid containers in ready-meal segments.
- Healthcare:Orthopedic device manufacturers absorb twelve to eighteen percent material cost increases while requalifying sterilization barrier systems for ethylene oxide and gamma radiation compatibility.
- Consumer Goods:Kraft-paper-barrier hybrids navigate rising paper-based packaging mandates in EU member states.
- Industrial:Chemical and agricultural applications demand puncture resistance and UV stability in outdoor storage conditions.
Food and beverage anchors volume scale. Healthcare concentrates margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier film manufacturing originated in German chemical corridors during the 1960s multilayer coextrusion revolution. The industry's geographic footprint now spans polymer production clusters, pharmaceutical manufacturing corridors, and flexible packaging conversion centers across five continents.
United States
North American protein processors and ready-meal manufacturers drive retort-compatible pouch demand. FDA extractables and leachables testing protocols govern pharmaceutical-contact film qualification. The Midwest packaging belt around Chicago and Wisconsin concentrates flexible film conversion capacity serving retail private-label channels.
Germany
Temperature-sensitive biologics distribution through the Frankfurt-Ludwigshafen corridor accelerates ethylene vinyl alcohol copolymer multilayer adoption. REACH F-Gas Regulation restrictions eliminate hydrofluorocarbon foam-laminated structures from medical device packaging. Bavarian orthopedic device manufacturers absorb material cost increases while requalifying sterilization barrier systems.
Japan
Atomic layer deposition equipment builders control vapor-deposition capacity for sub-twelve-micrometer pharmaceutical blister applications. PMDA pharmaceutical packaging guidelines align with FDA container closure system standards. Swiss and Japanese manufacturers co-develop moisture-critical solid-dose barrier structures with water vapor transmission below 0.5 grams per square meter per day.
India
CDSCO serialization requirements for export-oriented pharmaceutical packaging create qualification windows for polyester-barrier film suppliers. The country's national pharmaceutical regulator mandates track-and-trace integration capabilities for blister lidding suppliers. Maharashtra and Gujarat pharmaceutical manufacturing clusters absorb imported barrier films for domestic formulation and export packaging.
Switzerland
Swissmedic pharmaceutical packaging standards drive specification intensity for moisture-critical applications. Alpine precision manufacturing clusters specialize in atomic-layer-deposited aluminum oxide structures combining optical clarity with barrier performance. Basel pharmaceutical headquarters demand barrier films meeting simultaneous FDA, EMA, and Swissmedic dossier requirements.
Global High Barrier Packaging Films Market Vendor Landscape
Premium-margin players sit above commodity-margin players across barrier performance tiers and regulatory qualification depth. The vendor base organizes into three strata: integrated multinational film-to-pouch manufacturers, specialized deposition technology licensors, and regional converters serving single-country pharmaceutical markets. Two dominant competitive moves define current positioning: backward integration into polymer resin production to secure feedstock cost stability, and technology licensing partnerships to access atomic layer deposition capabilities without capital-intensive equipment acquisition.
Among integrated multinational suppliers, Amcor plc and Sealed Air Corporation exemplify distinct archetype positioning. Amcor leverages captive film-to-pouch manufacturing footprints across North America and Europe to sustain price competitiveness in retort-compatible structures. Sealed Air anchors its position through proprietary vacuum skin packaging technologies that extend protein shelf life. Mondi Group occupies a separate tier as a kraft-paper-barrier hybrid specialist navigating EU Green Deal paper-based packaging mandates. These three entities represent the spectrum from commodity-scale polymer conversion to specialty hybrid material innovation.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Berry Global Inc. |
| Mondi Group |
| Huhtamaki Oyj |
| Constantia Flexibles |
| Winpak Ltd. |
| Toray Industries, Inc. |
| Uflex Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive film-to-pouch manufacturing across North America and Europe anchors both supply security and pricing power for integrated converters serving retort-compatible and pharmaceutical barrier applications. This backward integration into polymer conversion insulates margin positions from resin volatility while enabling volume-based price competitiveness against non-integrated regional competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical-contact films from food-grade retort structures and commodity frozen food applications. Certification tier and volume scale drive price differentiation, with pharmaceutical blister lidding commanding substantial premiums over snack packaging equivalents. Cost compression in frozen food polyethylene films is intensifying because mono-material polypropylene substitutes are capturing share in clarity-tolerant applications. Retail private-label channels exhibit highest price sensitivity, while Swiss and Japanese pharmaceutical manufacturers show lowest sensitivity due to qualification timelines and dossier requirements.
Supply Chain Analysis
Ethylene vinyl alcohol copolymer supply rests on Japanese and German petrochemical producers with specialized barrier resin production capabilities. Vapor-deposition equipment for sub-twelve-micrometer aluminum oxide layers draws from Japanese and German equipment builders, while polyethylene feedstock sources from US Gulf Coast and Middle Eastern polymer complexes. Single-source vulnerability concentrates in atomic layer deposition equipment, where eighteen-month lead times for new capacity create qualification bottlenecks for pharmaceutical blister manufacturers. Distribution runs through integrated multinational converters with captive pouch manufacturing, regional flexible packaging specialists, and single-country pharmaceutical film converters serving localized regulatory markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through biodegradable film premiumization as EU Green Deal compliance deadlines shift brand owner procurement toward extended producer responsibility-compliant structures.
For Market Incumbents: Acquire atomic layer deposition equipment capabilities to secure pharmaceutical blister qualification windows before Japanese and German equipment builders extend lead times further. Consolidate adhesive lamination toxicology dossiers under REACH SVHC tracking requirements to defend share against non-compliant regional converters. Mono-material polypropylene substitution in frozen vegetables threatens polyethylene volume positions; counter with hybrid kraft-paper-barrier innovations that navigate EU paper-based packaging mandates. For New Entrants and Emerging Players: Capture India pharmaceutical manufacturing qualification windows opened by CDSCO serialization requirements for export-oriented blister packaging. Target Maharashtra and Gujarat formulation clusters with polyester-barrier film offerings integrated with track-and-trace capabilities. Organic snack channels in EU member states present penetrable entry points for polyhydroxyalkanoate barrier structures with polylactic acid seal layers, where extended producer responsibility fees create pricing tolerance for biodegradable premiums. For Investors and Strategic Acquirers: Roll-up economics work for regional European converters with delamination expertise because EU Packaging and Packaging Waste Regulation recyclability mandates are compressing qualification timelines for multilayer structures. Target mid-cap adhesive laminators with established REACH toxicology dossiers and pharmaceutical regulatory relationships. Watch FDA guidance revisions on post-consumer recycled content incorporation into food-contact layers as the inflection trigger for capital reallocation toward coextrusion equipment capable of processing recycled feedstocks.| Strategic Initiative | Industry Significance |
|---|---|
| Atomic Layer Deposition Capacity Expansion | Swiss and Japanese pharmaceutical manufacturers qualify moisture-critical solid-dose barrier structures with sub-0.5 gram water vapor transmission specifications. |
| Backward Integration into EVOH Resin Production | German biologics distribution through Frankfurt-Ludwigshafen corridor secures cryogenic-integrity multilayer supply chains. |
| Kraft-Paper-Barrier Hybrid Development | EU Green Deal paper-based packaging mandates open margin pools for cellulose substrate converters with vapor-deposited functional layers. |
| Biodegradable Film Certification Investment | Extended producer responsibility fee structures in EU member states accelerate brand owner adoption of polyhydroxyalkanoate structures. |
| Pharmaceutical Track-and-Trace Integration | CDSCO serialization requirements in India create qualification differentiation for polyester-barrier suppliers with integrated traceability. |
Methodological Framework
Direct dialogue with flexible packaging converters, pharmaceutical manufacturing procurement leads, adhesive lamination R&D directors, and EU regulatory affairs specialists grounded qualitative insights. Secondary validation drew from FDA container closure system guidance documents, ECHA REACH SVHC candidate lists, EU Packaging and Packaging Waste Regulation drafts, and customs trade data for ethylene vinyl alcohol copolymer imports. Bottom-up and top-down triangulation cross-checked volume estimates against resin production disclosures and end-use application audits.
Bottom-up modeling aggregated segment-level demand across frozen food, ready-meal, pharmaceutical blister, and medical device sterilization applications. Top-down verification benchmarked against polymer feedstock consumption patterns and flexible packaging conversion capacity utilization across the analysis window. Segmentation dimensions included material type, barrier performance tier, sterilization compatibility, and regional regulatory cluster. CAGRs derived from weighted average of historical elasticity patterns and projected qualification timeline compressions under evolving EU mandates.
Regulatory guidance revisions, equipment capacity lead time extensions, and feedstock price volatility are the dominant revision risks to forecast outputs. Forecasts reflect assumptions regarding FDA post-consumer recycled content determinations and EU F-Gas Regulation enforcement timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Saudi Arabia Plastic Packaging Films Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Moisture Barrier Bags Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Sealant Web Films Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Heat Transfer Films Market
Packaging Barrier Films
Release Coatings Market