
 Cling Films Market | 2026-2036
Cling Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cling Films Market Intelligence
The EU Single-Use Plastics Directive is hardening the cost-of-entry calculus for cling film suppliers serving European food packaging accounts. Amcor plc leverages its integrated resin-to-film operations to sustain margin structures under tightening compliance timelines. Berry Global Inc. anchors its competitive position through geographic dominance in North American retail channels. Mitsubishi Chemical Group Corporation differentiates via technology leadership in metallocene-catalyzed polyethylene formulations with superior puncture resistance.
Cling films are thin, self-adhering polymer sheets manufactured through blown or cast extrusion, typically 8-12 microns thick, composed primarily of linear low-density polyethylene with tackifying additives that enable surface cohesion without adhesive coatings. Their primary commercial purpose is oxygen and moisture barrier protection for perishable goods across food service, retail, and healthcare supply chains. Polyethylene grades dominate volume due to cost efficiency and recyclability alignment, while polyvinyl chloride retains niche medical sterilization applications where clarity and conformability command premium positioning. The 30-50 micron thickness bands capture mainstream food packaging demand, whereas 70-90 micron specifications serve industrial pallet wrapping where tensile strength requirements escalate.
The FDA governs food-contact substance compliance under 21 CFR 177.1520 for polyethylene cling films distributed in the United States, while the European Food Safety Authority enforces migration limits on plasticizers and additives under EU 10/2011. REACH registration obligations for novel monomers and additives shape R&D investment priorities for material suppliers seeking European market access. Japan's Ministry of Health, Labour and Welfare maintains positive list requirements for food-contact polymers that constrain formulation flexibility for exporters. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to prioritize mechanical recycling compatibility or advance chemical recycling partnerships before compliance deadlines crystallize.
Market Dynamics
The EU Single-Use Plastics Directive is compressing formulation timelines and forcing polyethylene resin suppliers to validate bio-based feedstocks before 2030 compliance deadlines crystallize. Food processors in Germany's industrial corridor now specify high-clarity grades certified under EFSA migration limits, shifting procurement power toward integrated resin-to-film operators with captive bio-polyethylene pilot lines.
Growth Catalysts
- Prepared Meal Packaging Surge:North American food service operators are expanding automated wrapping line deployments. These buyers specify 30-50 micron metallocene-catalyzed films for oxygen barrier performance in refrigerated distribution.
- REACH-Compliant Bio-Polyethylene:The EU Green Deal's packaging waste targets are accelerating ECHA registration of novel monomers from agricultural feedstocks. Material suppliers with validated bio-based polyethylene grades secure preferential access to German retail chains.
- Healthcare Sterilization Demand:Polyvinyl chloride retains premium positioning in medical device packaging where conformability and optical clarity command specification priority. Japanese hospitals specify 70-90 micron grades under MHLW positive list requirements.
Market Restraints
- Ethylene Feedstock Volatility:Naphtha-derived ethylene price swings compress margin structures for non-integrated film extruders. Smaller converters in Italy's Emilia-Romagna packaging cluster lack backward integration into cracker operations.
- Chinese Resin Overcapacity:State-owned polyethylene producers in Shandong Province are dumping standard LLDPE grades into Southeast Asian export channels. European converters face price pressure on commodity specifications lacking differentiation.
- Mechanical Recycling Contamination:Multi-layer barrier films with EVOH or PA interlayers defeat near-infrared sorting systems at European mechanical recycling facilities. The resulting downcycling limits closed-loop claims under EU Packaging and Packaging Waste Regulation.
Strategic Opportunities
- India Cold Chain Infrastructure:The country's PLI scheme for food processing is attracting cling film distributors to Maharashtra's Mumbai-Pune industrial corridor. Temperature-controlled logistics expansion creates specification pull for high-puncture resistance grades in poultry and dairy packaging.
- Chemical Recycling Partnerships:Pyrolysis-based polyethylene regeneration is expanding into food-contact applications as EFSA evaluates monomer recycling processes. Early movers in Netherlands-Germany border clusters secure offtake agreements with major retail private label programs.
- Automated Wrapping Line Integration:Machine OEMs in Italy's Bologna region are bundling film supply contracts with equipment leases. Film suppliers with predictive tension control algorithms capture multi-year service agreements.
Industry Challenges
- Metallocene Catalyst Talent Scarcity:Polymerization process engineers with single-site catalyst expertise command premium compensation. European resin producers compete with Middle Eastern expansions for this limited technical workforce.
- EFSA Novel Food Contact Substance Timelines:Migration testing protocols for bio-based additives extend certification cycles to 18-24 months. Formulation teams must front-load toxicology investment before commercial scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cling Films Market |
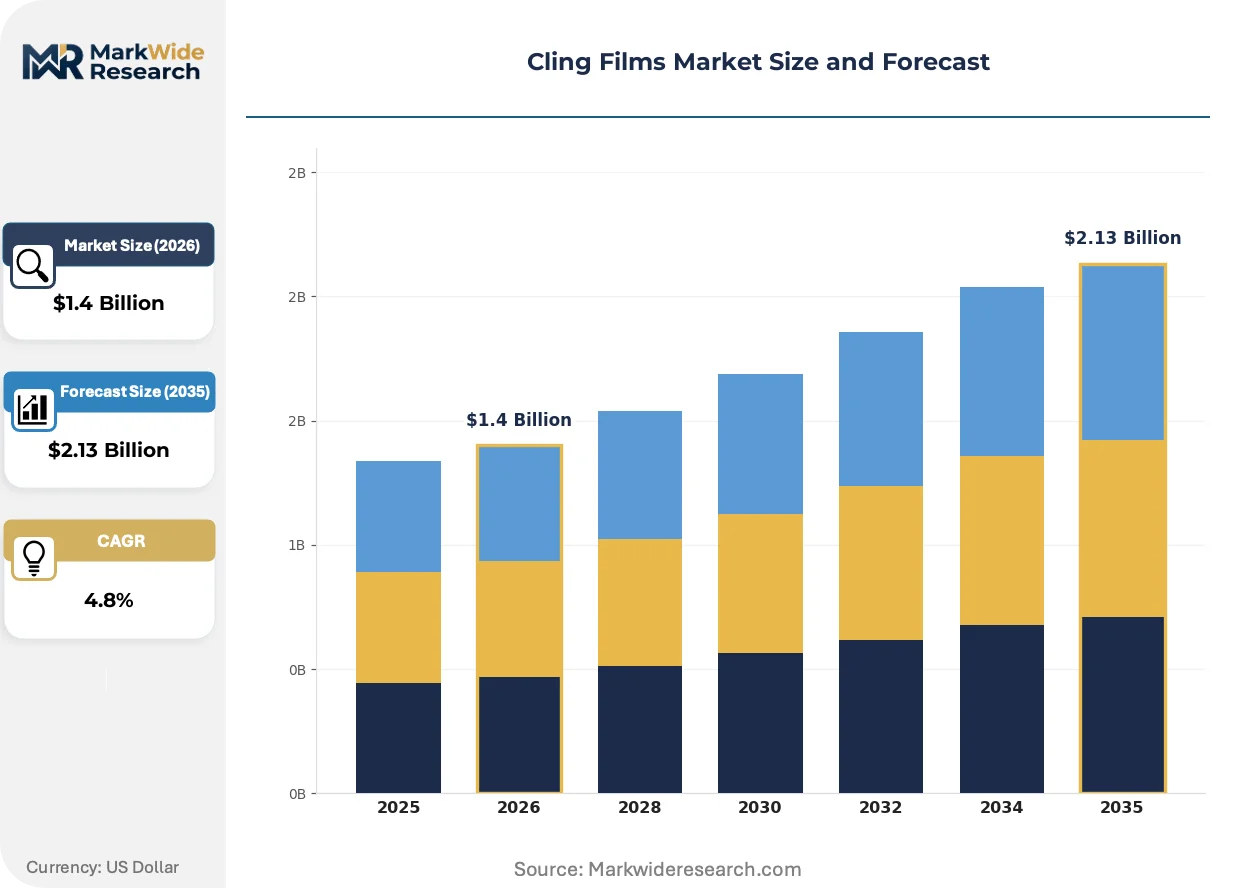
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyethylene, Polyvinyl Chloride, Polypropylene, Others Thickness: 30 Micron, 50 Micron, 70 Micron, 90 Micron Application: Food Packaging, Medical Use, Household, Industrial End User: Retail, Food Service, Healthcare, Manufacturing |
| Companies Covered | Sigma Plastics Group, Intertape Polymer Group Inc., Berry Global Inc., Anchor Packaging Inc., Sealed Air, Amcor plc, Mondi Group, Mitsubishi Chemical Group Corporation, Reynolds Consumer Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cling Films Market Strategic Shifts & Innovations
Bio-based polyethylene is migrating from niche premium positioning toward mainstream food packaging specifications as EFSA validates migration profiles for agricultural feedstock-derived resins. Three converging developments are compressing the technology adoption cycle and reshaping competitive positioning among resin suppliers and film converters.
Metallocene-catalyzed linear low-density polyethylene is expanding into automated high-speed wrapping lines across German and Dutch food processing facilities. These single-site catalyst grades deliver puncture resistance and optical clarity that commodity Ziegler-Natta resins cannot match. Bakery and fresh produce packagers in Rotterdam's distribution hub specify 10-12 micron downgauged films that maintain barrier performance.
REACH registration obligations for novel monomers are compressing R&D investment timelines for material suppliers seeking European market access. The ECHA evaluation process for bio-based feedstock derivatives now requires extended toxicological dossiers. Resin producers with existing polyethylene 10-2011 compliance frameworks adapt faster than entrants facing de novo substance notifications.
Direct procurement relationships between food manufacturers and resin producers are displacing distributor-mediated film supply in North American retail channels. Large protein processors in Nebraska and Iowa specify custom melt-index grades with captive additive packages. This channel consolidation squeezes independent converters lacking technical service capabilities or regional warehousing density.
Cling Films Market Segmentation
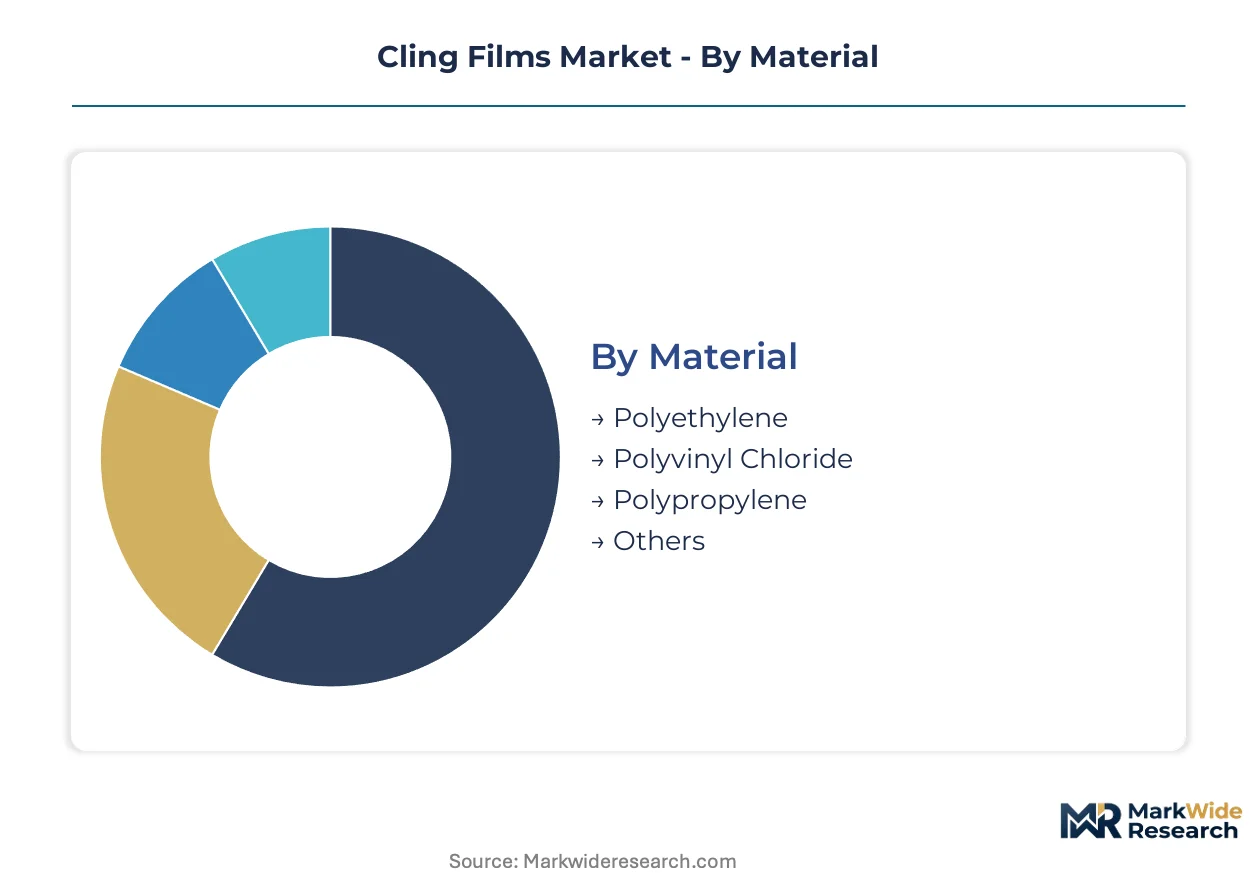
Cling film procurement decisions cluster around material chemistry, gauge specification, and end-use compliance requirements. Industrial buyers in food processing and healthcare maintain distinct technical specifications that reshape supplier competitive priorities across each segment boundary.
Material:
Resin supply concentration in Middle Eastern and North American crackers determines regional cost structures and formulation flexibility for film converters.
- Polyethylene:Linear low-density polyethylene dominates volume through blown and cast extrusion, typically 8-12 microns with tackifying additives. German food processors specify metallocene-catalyzed grades for automated wrapping lines under EFSA migration limits. Demand concentrates in Rotterdam's distribution hub where downgauged 10-12 micron films reduce material intensity.
- Polyvinyl Chloride:Retains premium positioning in medical sterilization where optical clarity and conformability command specification priority. Japanese hospitals specify 70-90 micron grades under MHLW positive list requirements for device packaging.
- Polypropylene:Offers higher temperature resistance for microwaveable applications and hot-fill food packaging.
- Others:Bio-based polyethylene from agricultural feedstocks and novel polyesters for compostable specifications.
Today's leader: Polyethylene. Tomorrow's challenger: Bio-based polyethylene grades.
Thickness:
Cost tier differentiation separates commodity food wrapping from industrial pallet containment applications.
- 30 Micron:Standard specification for retail food wrapping and deli counter applications.
- 50 Micron:Balanced barrier and handling properties for prepared meal packaging and protein trays.
- 70 Micron:Puncture-resistant grades for poultry and dairy distribution in India's expanding cold chain.
- 90 Micron:Maximum tensile strength for industrial pallet wrapping where load stability requirements escalate.
Volume concentrates at 30-50 micron bands. Margin expansion sits with 70-90 micron industrial specifications.
Application:
Regulatory fragmentation across food contact, medical device, and industrial safety standards fragments supplier qualification requirements.
- Food Packaging:Oxygen and moisture barrier protection for perishable goods across retail and food service channels. North American operators expand automated wrapping line deployments specifying metallocene-catalyzed films for refrigerated distribution.
- Medical Use:Sterilization-grade films requiring conformance to FDA 21 CFR 177.1520 or EU MDR requirements.
- Household:Consumer retail formats with emphasis on cutter box design and cling performance.
- Industrial:Pallet containment and surface protection with emphasis on tensile strength and UV stability.
Food packaging anchors current revenue. Medical use offers the steepest expansion trajectory through aging demographics and surgical procedure volume.
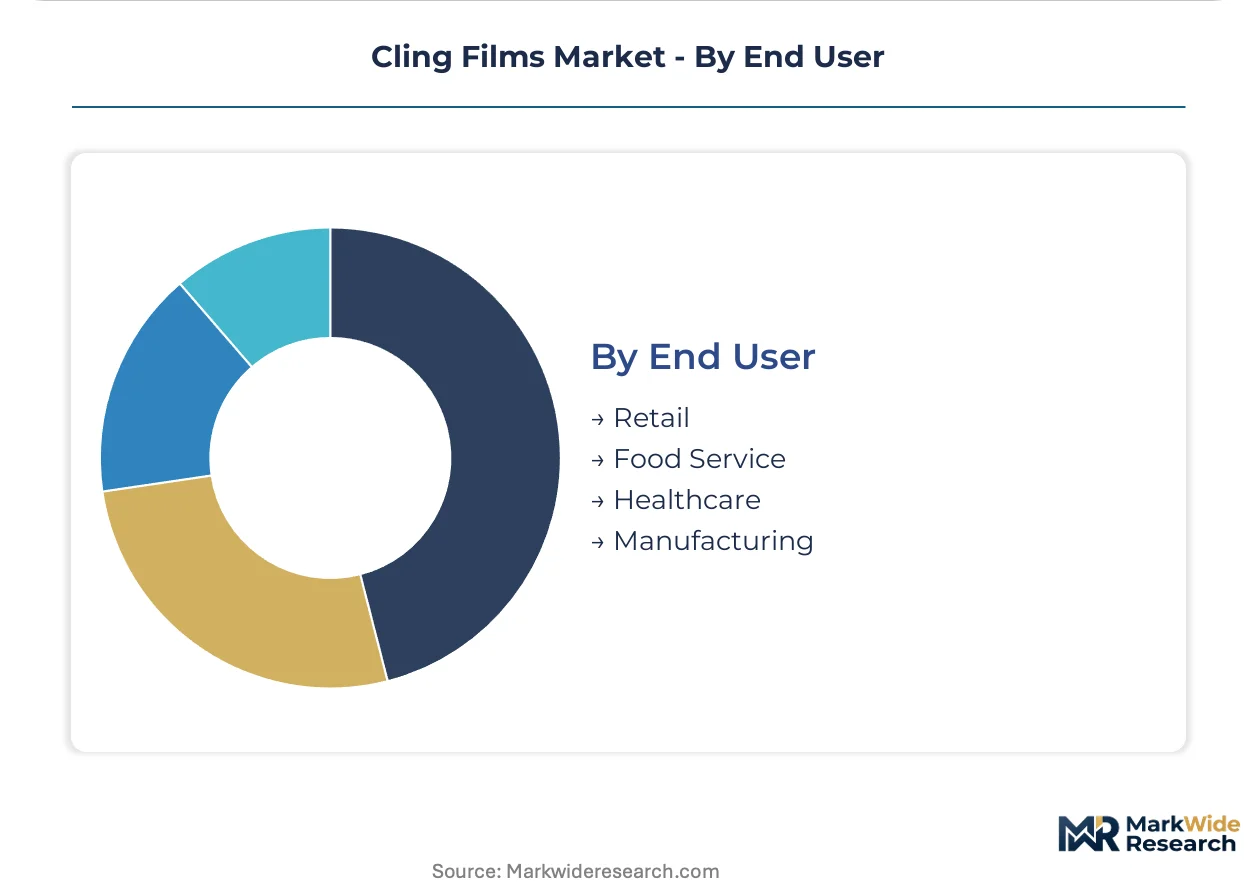
End User:
Customer type determines procurement channel structure and technical service intensity requirements.
- Retail:Supermarket chains and mass merchants specifying private label programs with volume commitments.
- Food Service:Restaurants, catering operations, and institutional kitchens with emphasis on portion control and hygiene.
- Healthcare:Hospitals, clinics, and medical device manufacturers with stringent sterilization validation requirements.
- Manufacturing:Industrial processors using films for in-process protection and finished goods containment.
Food service procurement is climbing the fastest through prepared meal format expansion. Healthcare offers premium pricing stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymerization engineers with metallocene catalyst expertise cluster in Germany's industrial corridor, anchoring Europe's cling film formulation leadership. Japanese resin specialists concentrate around Osaka's chemical complex, supplying medical-grade specifications. Indian operations managers with cold chain logistics experience are concentrating in Maharashtra as food processing infrastructure expands.
Germany
Food processors in the Rhine-Ruhr industrial belt specify high-clarity metallocene-catalyzed grades for automated wrapping lines. REACH registration obligations for novel bio-based monomers compress R&D timelines for resin suppliers seeking ECHA compliance. Stuttgart's packaging machinery OEMs bundle film supply contracts with equipment leases, capturing multi-year service agreements.
United States
Large protein processors in Nebraska and Iowa specify custom melt-index grades with captive additive packages for refrigerated distribution. FDA 21 CFR 177.1520 governs food-contact substance compliance for polyethylene cling films distributed domestically. Direct procurement relationships between food manufacturers and resin producers are displacing distributor-mediated supply in retail channels.
Japan
Japanese hospitals specify 70-90 micron polyvinyl chloride grades under MHLW positive list requirements for medical device packaging. METI maintains standards for food-contact polymers that constrain formulation flexibility for imported films. Osaka's chemical complex hosts resin specialists supplying sterilization-grade specifications where optical clarity commands premium positioning.
India
The PLI scheme for food processing is attracting cling film distributors to Maharashtra's Mumbai-Pune industrial corridor. FSSAI regulates food-contact materials with migration limits that shape importer qualification requirements. Temperature-controlled logistics expansion creates specification pull for high-puncture resistance grades in poultry and dairy packaging across the state's cold chain infrastructure.
Netherlands
Rotterdam's distribution hub concentrates demand for downgauged 10-12 micron films that maintain barrier performance in bakery and fresh produce applications. EFSA migration limits on plasticizers and additives enforce strict formulation discipline under EU 10/2011. Pyrolysis-based polyethylene regeneration facilities near the German border secure offtake agreements with retail private label programs as chemical recycling expands.
Cling Films Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Integrated resin-to-film operators sustain margin structures under tightening EU compliance timelines, while independent converters face channel consolidation pressure. Three archetypes dominate: multinational packaging conglomerates with captive resin operations, regional film converters with technical service capabilities, and machinery-integrated suppliers bundling equipment with material supply. Capacity expansion in bio-based polyethylene pilot lines and chemical recycling partnerships represent the dominant competitive moves reshaping supplier positioning.
Among North American packaging conglomerates, Berry Global Inc. and Sealed Air occupy positions exemplifying scale-driven channel dominance in retail and food service distribution. Sigma Plastics Group represents the specialized converter archetype with regional manufacturing density. These companies anchor competitive dynamics through backward integration into resin supply, geographic warehousing coverage, and technical service intensity that independent converters struggle to match.
| Leading Market Players |
|---|
| Sigma Plastics Group |
| Intertape Polymer Group Inc. |
| Berry Global Inc. |
| Anchor Packaging Inc. |
| Sealed Air |
| Amcor plc |
| Mondi Group |
| Mitsubishi Chemical Group Corporation |
| Reynolds Consumer Products |
| Others |
Cost & Logistics Intelligence
Metallocene-catalyzed premium grades command three-to-five-fold markups over commodity Ziegler-Natta resins, with that divergence manifesting in both film pricing and the geographic clustering of integrated resin-to-film operations around Germany's industrial corridor and Rotterdam's distribution hub. Bio-based polyethylene certifications under REACH and EFSA migration limits add further pricing stratification, as validated feedstock suppliers capture preferential procurement relationships with automated wrapping line operators while unvalidated converters face margin compression from compliance timeline pressures.
Pricing Analysis
Bundled equipment-and-film service contracts from Italian machinery OEMs in the Bologna region command premium positioning against unbundled commodity film supply, with three-tier pricing structure across premium, standard, and economy levels differentiating by certification grade and technical service intensity. Price differentiation stems from EFSA migration limit compliance status and captive additive package customization, with pricing pressure intensifying in standard LLDPE grades due to Chinese state-owned producer dumping into Southeast Asian export channels. Food service operators with automated line deployments show lowest price sensitivity, while independent Italian converters in the Emilia-Romagna cluster face acute cost compression.
Supply Chain Analysis
Direct-to-food-procurement channels displace distributor-mediated supply for large protein processors in Nebraska and Iowa, while distributor networks retain relevance for mid-tier retail and food service accounts lacking technical specification capabilities. Raw material supply concentrates in Saudi Arabian and Qatari ethylene crackers, with naphtha-derived feedstock costs and metallocene catalyst availability as critical dependencies. Supply chain risk centers on ethylene feedstock price volatility from naphtha-cracker margin swings, with European converters particularly exposed due to limited backward integration. Distribution runs through integrated resin-to-film operators with regional warehousing density in North America and captive bio-polyethylene pilot lines in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cling films market functions as a geographic-arbitrage play where bio-based polyethylene validation costs in Europe run substantially higher than conventional resin scale-up in the US Gulf Coast, creating divergent margin structures across regulatory jurisdictions.
For Market Incumbents: Anchor competitive position through captive bio-polyethylene pilot line expansion in the Netherlands-Germany border cluster, securing EFSA pre-registration for agricultural feedstock-derived monomers before compliance deadlines crystallize. Defend against Chinese resin dumping pressure by deepening technical service relationships with automated wrapping line operators in North American protein processing, where specification stickiness exceeds price sensitivity. Prioritize chemical recycling partnership offtake agreements with retail private label programs to preempt mechanical recycling contamination liabilities. For New Entrants and Emerging Players: Metallocene catalyst formulation expertise offers a technology-first wedge into the European market, where polymerization process engineer scarcity constrains incumbent expansion velocity. Target India's Maharashtra cold chain infrastructure buildout as the most penetrable geography, where PLI scheme incentives attract food processing investment but local film specification capabilities remain underdeveloped. Pursue machine OEM bundling partnerships as the dominant go-to-market angle, leveraging predictive tension control algorithms to capture multi-year service agreements. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration obligations for novel monomers exceed smaller converters' R&D investment capacity, creating acquisition opportunities for integrated operators with existing EU 10/2011 compliance frameworks. Long-term viability favors resin-to-film operators with validated bio-based feedstock pipelines and chemical recycling infrastructure positions over commodity converters lacking differentiation. Target mid-scale European converters with EFSA pre-submission dossiers as acquisition archetypes. Monitor EFSA novel food contact substance approval timelines as the critical inflection signal for bio-polyethylene market penetration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Polyethylene Pilot Line Expansion | Secures preferential access to German retail chains under EU Green Deal packaging targets. |
| Chemical Recycling Partnership | Pyrolysis-based regeneration addresses EVOH contamination barriers in European mechanical recycling facilities. |
| Machine OEM Bundling Agreement | Predictive tension control algorithms capture multi-year service contracts in Italian packaging machinery corridors. |
| EFSA Pre-Registration Investment | Front-loaded toxicology dossiers compress certification cycles for agricultural feedstock-derived monomers. |
| India Cold Chain Distribution Buildout | Maharashtra's Mumbai-Pune corridor offers specification pull for high-puncture resistance poultry and dairy grades. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with resin procurement directors at food processing conglomerates, polymerization process engineers at integrated chemical producers, packaging machinery OEM technical sales leads, and retail private label program managers with secondary validation from customs trade data, SEC 10-K filings of listed packaging conglomerates, ECHA registration databases, and FSSAI food-contact material notifications. Bottom-up volume modeling triangulates against top-down macroeconomic demand indicators.
Rate-of-change decomposition separates volume growth from price/mix effects across material chemistry, thickness specification, and end-use compliance segments, with analytical framework spanning the projection horizon. Segmentation dimensions modeled include resin grade tier, automated line compatibility, and regional regulatory cluster. CAGRs derive from historical trajectory analysis adjusted for structural shift assumptions including bio-based feedstock penetration and chemical recycling capacity expansion, with ethylene feedstock cost curves and metallocene catalyst supply constraints as industry-specific forecast inputs.
The model holds under stable regulatory compliance timelines and continued ethylene cracker operating rates; deviation in EFSA novel substance evaluation paces or naphtha-derived feedstock volatility would shift penetration assumptions. Forecasts reflect documented base-case assumptions regarding bio-polyethylene cost parity achievement and chemical recycling food-contact approval pathways. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
Barrier Bags Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Global Stretch and Shrink Film Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market