
 Biobased Anti-Blocking Agents for Flexible Packaging Films Market | 2026-2036
Biobased Anti-Blocking Agents for Flexible Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Biobased Anti-Blocking Agents for Flexible Packaging Films Market Insights
Green project finance and sustainability-linked leasing is tilting competitive dynamics toward capital-rich chemical conglomerates with verified bio-feedstock supply chains. Cargill leverages its agricultural commodity infrastructure to secure cost-advantaged raw material positions across multiple continents. Evonik Industries AG sustains R&D intensity in specialty silica and bio-derived polymer additives through dedicated innovation centers. Clariant AG anchors its competitive position with backward integration into natural wax refining and regional compounding assets.
Biobased anti-blocking agents comprise plant-derived particulates and surface-modified natural polymers that reduce adhesion between coextruded film layers at loadings of 500–3,000 ppm, enabling high-speed packaging line throughput. Polysaccharide grades dominate current volume as established supply chains from corn and tapioca starch keep unit economics predictable. Cellulose derivatives represent the fastest-expanding product class where nano-fibrillated formats command margin premiums in pharmaceutical blister films. Food packaging absorbs the largest application share, though agricultural films show the steepest growth trajectory as mulch and greenhouse films face heightened scrutiny for soil microplastic contamination.
REACH registration requirements and the EU F-Gas Regulation constrain conventional fluorinated anti-blocking chemistries, redirecting formulation budgets toward bio-alternatives. FDA food contact notification pathways and EFSA positive opinions on specific polysaccharide grades determine which suppliers qualify for branded food packaging contracts. Stakeholders must monitor evolving compostability certification standards from TÜV Austria and BPI, as film converters increasingly bundle anti-blocking performance with end-of-life claims in procurement specifications.
Market Dynamics
The EU Green Deal's tightening restrictions on petrochemical film additives are forcing converters to requalify entire additive portfolios, creating procurement urgency around verified biobased supply chains.
Growth Catalysts
- REACH Phase-Down of Fluorinated Additives:The EU F-Gas Regulation and ECHA restrictions on perfluorinated compounds redirect formulation budgets toward polysaccharide and natural wax alternatives in food-contact films.
- Agricultural Film Microplastic Scrutiny:Soil contamination mandates in Germany and France accelerate mulch and greenhouse film conversions to compostable structures requiring bio-derived anti-blocking agents.
- High-Speed Packaging Line Throughput Demands:Coextrusion lines running at 600+ meters per minute require anti-blocking loadings of 500–3,000 ppm, specifications that nano-fibrillated cellulose grades now satisfy.
Market Restraints
- Corn Starch Price Volatility:Polysaccharide feedstock costs fluctuate with agricultural commodity cycles, compressing margin predictability for compounders lacking backward integration into crop processing.
- Regional Supply Concentration:Natural wax refining capacity clusters in Southeast Asia, exposing European formulators to freight cost spikes and extended lead times during container shortages.
- Performance Ceiling in High-Temperature Films:Biobased particulates degrade above 180°C, excluding them from retort pouch and aseptic packaging applications where synthetic silica maintains dominance.
Strategic Opportunities
- Pharmaceutical Blister Film Certification:Nano-fibrillated cellulose grades command margin premiums in drug packaging where EMA stability requirements and FDA Type III DMF pathways create qualification barriers for commodity suppliers.
- Compostability Certification Bundling:TÜV Austria OK Compost and BPI certification allow film converters to bundle anti-blocking performance with end-of-life claims, differentiating procurement specifications from undifferentiated synthetic alternatives.
- Industrial Cluster Proximity:Packaging machinery OEMs and film extruders co-located near Düsseldorf and Hamburg create concentrated demand nodes where regional compounding assets capture logistics advantages.
Industry Challenges
- Bio-Feedstock Traceability Expertise:Mass balance accounting and ISCC PLUS certification require specialized procurement and audit functions scarce among mid-size compounders.
- Food Contact Notification Timelines:FDA FCN submissions and EFSA scientific opinions on novel polysaccharide grades extend qualification cycles to 18–36 months, freezing supplier switching.
- Legacy Extrusion Equipment Retrofit Costs:Existing lines configured for synthetic additive dispersion require screw and die modifications to process hygroscopic natural polymers without degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobased Anti-Blocking Agents for Flexible Packaging Films Market |
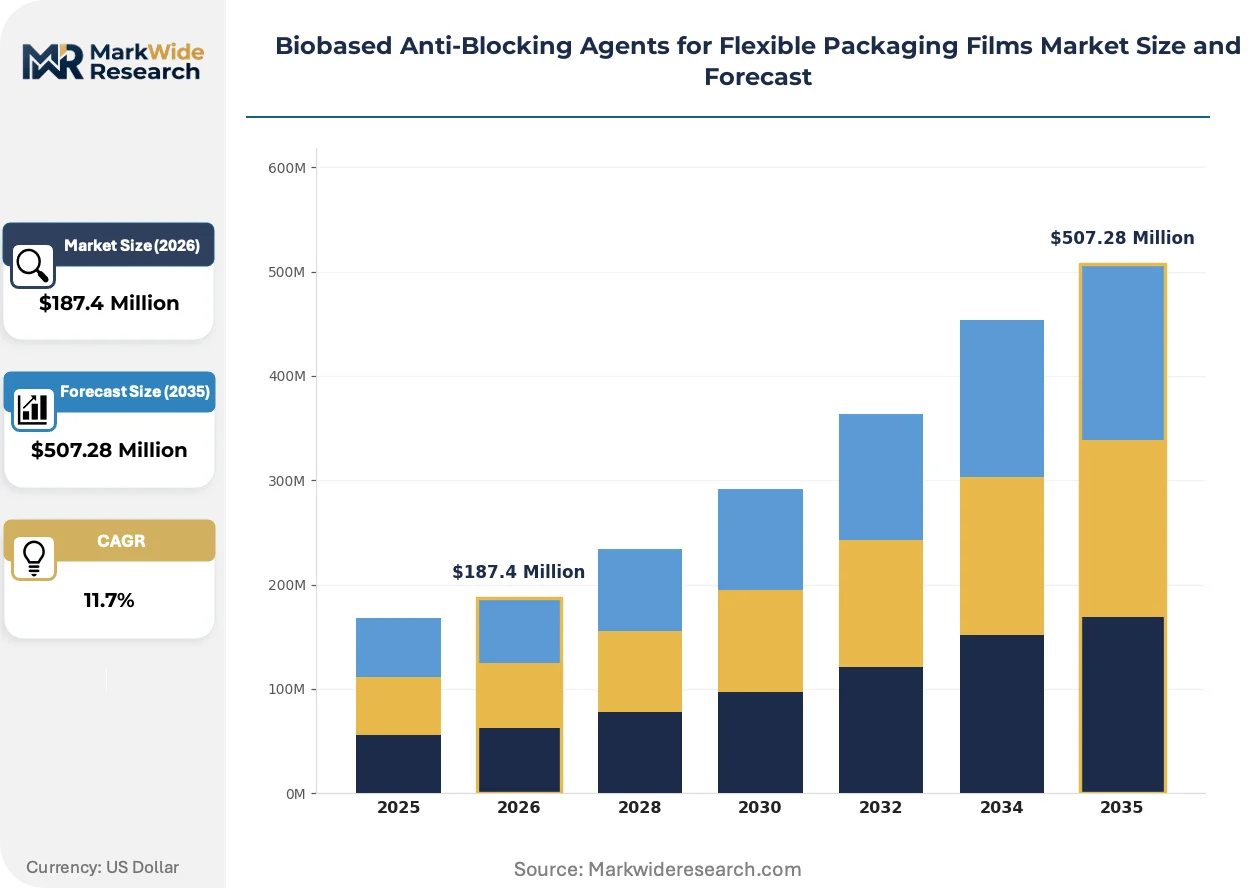
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polysaccharides, Cellulose Derivatives, Natural Waxes, Protein-Based Agents, Starch-Based Agents Application: Food Packaging, Pharmaceutical Wrapping, Cosmetic Packaging, Agricultural Films, Industrial Packaging Film Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Biodegradable Polymers, Polyester End User Industry: Packing Manufacturers, Pharmaceutical Manufacturers, Cosmetic Producers, Agricultural Suppliers, Industrial Fabricators |
| Companies Covered | Cargill, Evonik Industries AG, Clariant AG, Avient Corporation, Ampacet Corporation, LyondellBasell Industries, BYK, W. R. Grace, Fuji Silysia Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobased Anti-Blocking Agents for Flexible Packaging Films Market Trends and Innovations
Formulation science is converging with sustainability verification systems, creating new technical specifications that prioritize traceability and end-of-life performance alongside traditional anti-blocking metrics.
Nano-fibrillated cellulose is hybridizing surface-modified natural polymers with synthetic polymer matrices to achieve sub-micron film surface roughness. Pharmaceutical blister manufacturers in Germany and Switzerland are adopting these grades at twice the pace of food packaging converters. This hybridization is compressing the performance gap between biobased and synthetic silica in high-clarity applications.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon blowing and processing aids is eliminating conventional fluorinated anti-blocking chemistries from REACH-registered formulations. Film converters serving EU retail chains must now document additive biobased content percentages in supplier declarations. Agricultural film segments face the steepest compliance burden as national extended producer responsibility schemes expand to cover soil-applied plastics.
Certification-driven procurement now dominates branded food packaging contracts where sustainability-linked leasing terms require verified bio-feedstock percentages. Distributor and compounder relationships are fragmenting as converters establish direct supply agreements with agricultural commodity processors. This pattern is most visible in the Benelux region where co-packer consolidation has concentrated buying power among three major film extrusion groups.
Biobased Anti-Blocking Agents for Flexible Packaging Films Market Segmentation
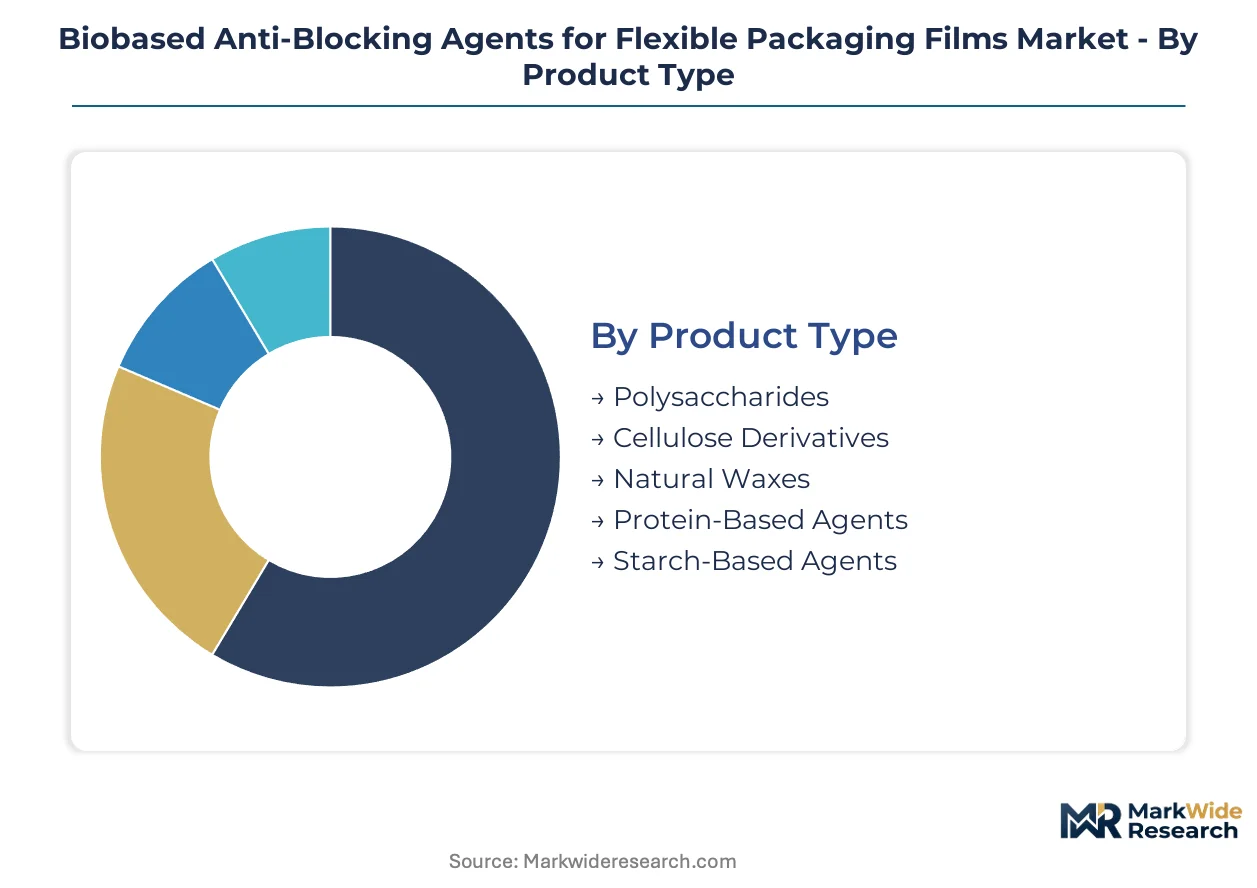
Segmentation in this market reflects divergent technical requirements across film conversion technologies and end-of-life performance claims. Procurement specifications now bundle anti-blocking efficacy with compostability certification, reshaping how suppliers align product portfolios to buyer segments.
Product Type:
Cost tier determines raw material sourcing strategies and margin exposure to agricultural commodity cycles.
- Polysaccharides:Corn and tapioca starch derivatives dominate current volume through established supply chains that keep unit economics predictable for compounders. Food packaging converters in Germany absorb the largest share as EU Green Deal restrictions tighten on petrochemical alternatives.
- Cellulose Derivatives:Nano-fibrillated formats command margin premiums through sub-micron surface roughness specifications that satisfy pharmaceutical blister film requirements. Swiss and German drug packaging manufacturers adopt these grades at twice the pace of food packaging converters.
- Natural Waxes:Backward integration into refining secures supply security for regional compounders.
- Protein-Based Agents:Emerging grades from zein and wheat gluten face hydrolysis stability challenges.
- Starch-Based Agents:Modified amylopectin structures serve cost-sensitive agricultural film applications.
Polysaccharides hold installed capacity. Cellulose derivatives are rotating up the share rankings.
Application:
Application segmentation tracks where regulatory pressure is forcing fastest formulation conversion timelines.
- Food Packaging:Branded retail chains now require documented biobased content percentages in supplier declarations, bundling anti-blocking performance with sustainability-linked leasing terms. REACH F-Gas Regulation phase-downs eliminate fluorinated alternatives from EU food-contact formulations.
- Agricultural Films:Soil microplastic mandates in Germany and France accelerate mulch and greenhouse film conversions to compostable structures. National extended producer responsibility schemes expand coverage to soil-applied plastics, creating procurement urgency.
- Pharmaceutical Wrapping:EMA stability requirements and FDA Type III DMF pathways create qualification barriers.
- Cosmetic Packaging:Premium positioning favors natural wax aesthetics over synthetic silica.
- Industrial Packaging:Cost-driven specifications lag food and pharma segments in biobased conversion.
Food packaging commands current volume concentration. Agricultural films are climbing the fastest on regulatory compliance deadlines.
Film Material:
Material compatibility dictates processing temperature ceilings and anti-blocking agent thermal stability requirements.
- Polyethylene:LDPE and LLDPE films process below 180°C, accommodating the full range of biobased particulates without thermal degradation. Coextrusion lines near Düsseldorf and Hamburg run these materials at 600+ meters per minute.
- Biodegradable Polymers:PLA and PBAT structures require anti-blocking agents that maintain compostability certification through TÜV Austria OK Compost and BPI pathways. Film converters bundle performance claims with end-of-life verification.
- Polypropylene:Higher melting points restrict biobased agent selection.
- Polyvinyl Chloride:Plasticizer migration concerns limit natural polymer compatibility.
- Polyester:Retort applications exclude biobased options above thermal ceilings.
Polyethylene holds installed capacity. Biodegradable polymers are gaining share fastest on packaging circularity mandates.
End User Industry:
Customer type determines qualification complexity and direct versus distributor procurement relationships.
- Packing Manufacturers:Consolidated film extrusion groups in the Benelux region concentrate buying power and establish direct supply agreements with agricultural commodity processors. Co-packer consolidation fragments traditional distributor relationships.
- Pharmaceutical Manufacturers:FDA food contact notification timelines and EFSA scientific opinions extend qualification cycles to 18–36 months, freezing supplier switching and favoring incumbents with established regulatory dossiers.
- Cosmetic Producers:Premium brand positioning drives natural ingredient marketing claims.
- Agricultural Suppliers:Extended producer responsibility schemes alter procurement specifications.
- Industrial Fabricators:Price-sensitive purchasing delays biobased conversion.
Packing manufacturers hold installed capacity. Pharmaceutical manufacturers are rotating up the share rankings on qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in biobased anti-blocking agents tilt toward deficit in Europe and surplus in agricultural commodity processing regions. Germany absorbs the largest share of intra-EU imports as film extruders cluster near packaging machinery hubs. Southeast Asian natural wax refining capacity supplies European formulators through extended supply chains vulnerable to freight volatility.
Germany
Film extruders and packaging machinery OEMs co-locate around Düsseldorf and Hamburg industrial corridors. The EU F-Gas Regulation and REACH restrictions on perfluorinated compounds force converters to requalify additive portfolios. High-speed coextrusion lines running at 600+ meters per minute concentrate demand for nano-fibrillated cellulose grades.
United States
Food packaging converters accelerate procurement of plant-derived additives as branded retail chains mandate documented biobased content. FDA food contact notification pathways determine supplier qualification timelines. Agricultural film demand concentrates in Midwest processing corridors where mulch and greenhouse applications face emerging soil microplastic scrutiny.
France
National extended producer responsibility schemes expand coverage to soil-applied plastics, accelerating agricultural film conversions to compostable structures. EFSA scientific opinions on novel polysaccharide grades create regulatory gatekeeping for food-contact applications. Lyon and Paris basin industrial zones host film converters bundling anti-blocking performance with TÜV Austria certification claims.
China
Dual carbon goals and tightening environmental standards redirect domestic film additive demand toward bio-alternatives. SAMR and GB standards on food-contact materials create parallel qualification pathways to Western regulatory frameworks. Yangtze River Delta packaging clusters source polysaccharide feedstocks through captive agricultural commodity processing infrastructure.
Switzerland
Pharmaceutical blister film manufacturers adopt nano-fibrillated cellulose grades at twice the pace of food packaging converters. Swissmedic stability requirements and FDA Type III DMF pathways create qualification barriers favoring incumbent suppliers. Basel and Zurich pharmaceutical packaging clusters command margin premiums for certified bio-derived additives.
Biobased Anti-Blocking Agents for Flexible Packaging Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock refining and surface modification chemistry. The vendor base organizes around agricultural commodity processors with captive crop infrastructure, specialty chemical conglomerates with dedicated innovation centers, and regional compounders with backward integration into natural wax refining. Three archetypes dominate: crop-to-chemical integrators, specialty additive innovators, and regional formulation compounders. Competitive moves concentrate on strategic partnerships for bio-feedstock traceability certification and capacity expansion near industrial demand clusters.
Within the crop-to-chemical integrator tier, Cargill leverages agricultural commodity infrastructure across multiple continents. Among specialty chemical innovators, Evonik Industries AG and Clariant AG occupy positions defined by R&D intensity in surface-modified natural polymers and regional compounding assets respectively. These three entities exemplify how verified bio-feedstock supply chains and backward integration into refining anchor competitive positioning as sustainability-linked leasing terms reshape procurement relationships.
| Leading Market Players |
|---|
| Cargill |
| Evonik Industries AG |
| Clariant AG |
| Avient Corporation |
| Ampacet Corporation |
| LyondellBasell Industries |
| BYK |
| W. R. Grace |
| Fuji Silysia Chemical |
| Others |
Pricing and Supply Chain Analysis
Corn starch price volatility determines both margin compression in the polysaccharide tier and the geographic configuration of compounder assets. Agricultural commodity cycles expose European formulators to feedstock cost spikes that reshape procurement relationships toward backward-integrated suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical blister film certification commands the premium tier where EMA stability requirements create qualification barriers. Cost compression in the agricultural film tier intensifies because national extended producer responsibility schemes shift compliance burdens to converters. Mid-size compounders lacking captive crop processing show the highest price sensitivity.
Supply Chain Analysis
Extended payment terms from Southeast Asian natural wax refiners strain working capital for European distributors. Supply concentrates in Thailand, Indonesia, and Malaysia for wax refining, while Germany and the United States host film extrusion clusters. Raw material flows rest on corn and tapioca starch from North American and Southeast Asian processors. Single-source vulnerability runs through containerized freight lanes connecting Asian refiners to Hamburg and Rotterdam ports. Distribution runs through regional compounding assets near Düsseldorf and Hamburg industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks an agricultural commodity recovery cycle where corn starch price normalization would restore margin predictability for polysaccharide compounders.
For Market Incumbents: Insulate margin positions through backward integration into crop processing infrastructure near Midwest agricultural corridors. Secure ISCC PLUS certification ahead of compostability bundling requirements from branded retail chains. Capacity addition in the Benelux region captures consolidated buying power from co-packer film extrusion groups. For New Entrants and Emerging Players: Pursue pharmaceutical blister film qualification where FDA Type III DMF pathways create incumbent protection and margin premiums. Agricultural mulch films in France and Germany offer the most penetrable segment given soil microplastic mandate deadlines. A go-to-market angle anchored on TÜV Austria OK Compost certification bundling differentiates from undifferentiated synthetic suppliers. For Investors and Strategic Acquirers: The market sits at a regulatory enforcement phase that favors crop-to-chemical integrators with verified bio-feedstock supply chains. Long-term viability over the next decade hinges on mass balance accounting expertise and regional compounding asset control. Acquisition targets should display captive agricultural commodity infrastructure. The signal to watch is EU F-Gas Regulation enforcement intensity against fluorinated additive incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crop Processing | Cargill leverages agricultural infrastructure to secure cost-advantaged feedstock positions across multiple continents. |
| Compostability Certification Investment | TÜV Austria OK Compost pathways allow film converters to bundle anti-blocking performance with end-of-life claims. |
| Regional Compounding Capacity Expansion | Assets near Düsseldorf and Hamburg capture logistics advantages from co-located packaging machinery OEMs. |
| Pharmaceutical Blister Film Qualification | EMA stability requirements and FDA Type III DMF pathways create margin premiums for certified suppliers. |
| Long-term Supply Agreement with Agricultural Processors | Direct agreements with commodity processors fragment traditional distributor relationships in the Benelux region. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed chemical conglomerates, EFSA scientific opinion registers, and compostability certification databases. Primary interviews engaged plant managers at film extrusion facilities, procurement leads at packaging converters, technical R&D directors at specialty chemical firms, and distribution channel partners serving the Benelux region. Bottom-up volume estimates from additive loading specifications triangulate against top-down market sizing from trade flow analysis.
Forecast inputs incorporate polysaccharide and cellulose derivative grade tiers, food packaging versus agricultural film end-use splits, biodegradable polymer versus polyethylene material compatibility, and regional production hub concentration. CAGRs derive from segment-level growth rate blending across the projection horizon. Industry-specific inputs include EU F-Gas Regulation phase-down timelines and national extended producer responsibility scheme implementation schedules.
Sensitivities concentrate around corn starch price volatility, REACH enforcement intensity, and compostability certification adoption rates. Forecasts reflect assumptions about regulatory compliance deadlines and agricultural commodity cycle positioning. Macroeconomic deviation, regulatory acceleration or delay, or breakthrough synthetic additive performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Saudi Arabia Plastic Packaging Films Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market