
 Heat Insulating Films Market | 2026-2036
Heat Insulating Films Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Insulating Films Market Analysis
Project finance for large-scale window retrofit programs is rewriting competitive access in the heat insulating films sector. Saint-Gobain leverages its integrated glass-film distribution to dominate European commercial building retrofits. Toray Industries anchors Asian supply through captive polymer resin production and precision coating lines. Eastman Chemical Company differentiates via specialty polyester substrate formulations that sustain optical clarity under thermal stress.
Heat insulating films are multilayer laminates, typically 25–100 microns thick, combining metalized or ceramic-coated substrates with pressure-sensitive adhesives to reject infrared radiation while transmitting visible light. Their primary purpose is reducing thermal load in enclosed spaces and active systems, thereby cutting HVAC energy draw and extending component life. Metalized films currently occupy the largest volume share due to mature sputtering infrastructure and proven solar control performance, while nano-coating technology represents the fastest-expanding margin pool as manufacturers seek thinner, spectrally selective layers. Hybrid technology competes for automotive glazing integration where both reflective and absorptive mechanisms must coexist with embedded antenna and sensor functions.
The US Department of Energy building codes and EPA Energy Star certification programs shape product performance thresholds for residential and commercial specification. In Europe, REACH compliance and the EU Green Deal's building renovation targets force reformulation of adhesive chemistries and drive demand for low-emissivity constructions. China's GB standards for building energy efficiency and MIIT directives on automotive lightweighting further tighten material requirements. Stakeholders must monitor how evolving multi-jurisdictional certification regimes affect cross-border product platform strategies and regional manufacturing location decisions.
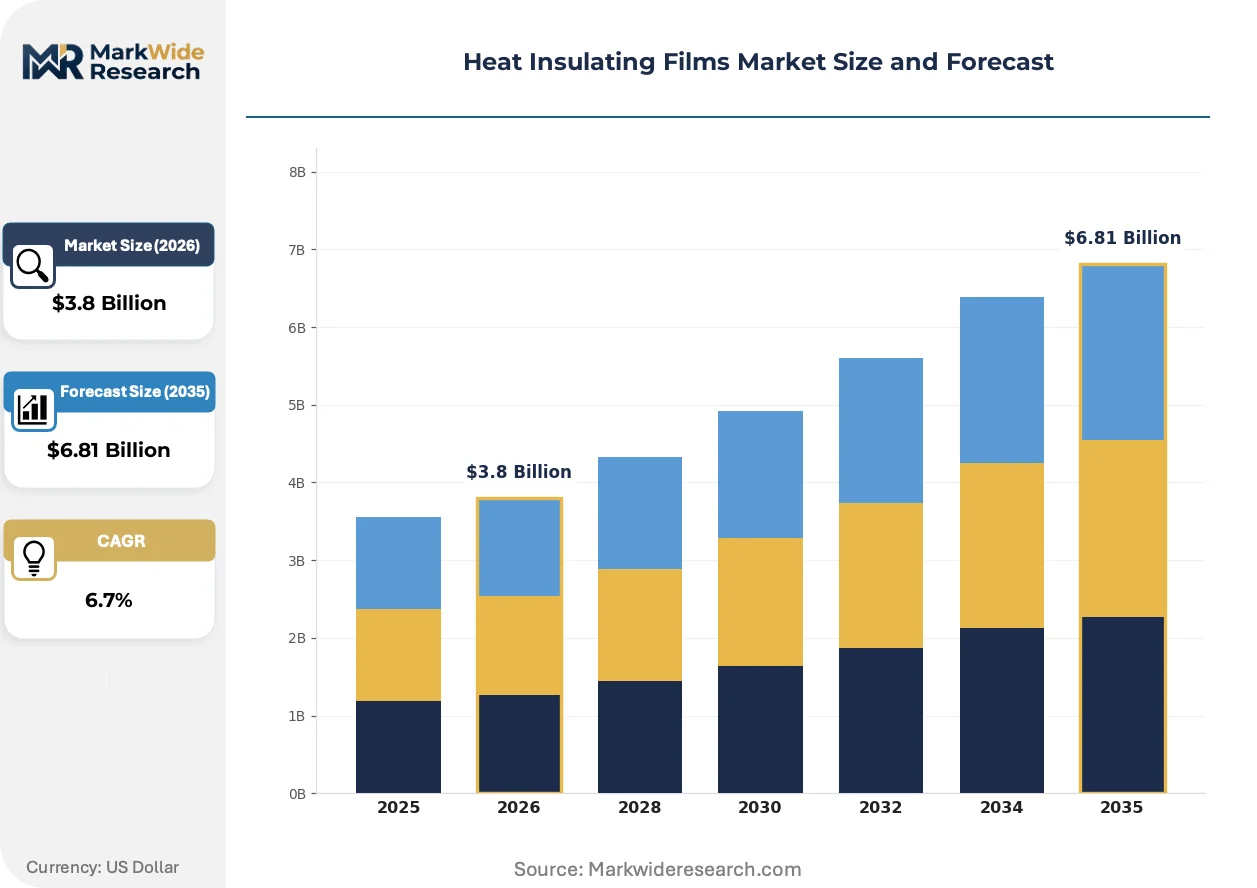
Market Dynamics
Automotive electrification and building energy code tightening are compressing specification cycles for spectrally selective films, forcing manufacturers to reconcile optical clarity targets with infrared rejection performance in thinner substrate formats.
Growth Catalysts
- EU Green Deal building renovation mandates:Member states must double renovation rates by 2030, accelerating specification of low-emissivity window films in commercial and residential retrofits across Germany, France, and Italy.
- MIIT automotive lightweighting directives:China's Ministry of Industry and Information Technology imposes strict fuel economy standards that push EV manufacturers toward thinner, lighter thermal management films for battery enclosures and cabin glazing.
- Sputtering infrastructure maturation:Vacuum deposition equipment availability in East Asian manufacturing clusters enables cost-competitive metalized film production at scale for export markets.
Market Restraints
- Silver and indium price volatility:Metalized films depend on precious metal sputtering targets, creating margin pressure when commodity markets spike.
- East Asian substrate concentration:Biaxially oriented polyester film supply concentrates in China, Japan, and South Korea, exposing buyers to logistics disruptions and tariff exposure.
- REACH adhesive reformulation costs:ECHA restrictions on solvent-based pressure-sensitive adhesives force European manufacturers to retool coating lines for water-based or UV-cured chemistries.
Strategic Opportunities
- India building energy efficiency codes:The Bureau of Indian Standards is finalizing stringent envelope performance standards for commercial construction, creating first-mover advantage for film suppliers establishing local toll-coating partnerships.
- Photovoltaic-integrated glazing:Building-integrated photovoltaics manufacturers seek spectrally selective interlayers that manage thermal load without degrading cell efficiency, opening adjacent demand.
- Direct-to-facility distribution platforms:Digital procurement channels for window retrofit contractors bypass traditional glass-film distribution tiers, capturing margin and specification data.
Industry Challenges
- Vacuum coating technician scarcity:Precision sputtering and plasma-enhanced chemical vapor deposition operations require specialized operators whose training pipelines lag capacity expansion plans.
- Multi-jurisdictional certification timelines:Simultaneous pursuit of EPA Energy Star, REACH compliance, and GB standard testing extends product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Insulating Films Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Films, Metalized Films, Coated Films, Specialty Films Technology: Reflective Technology, Absorptive Technology, Hybrid Technology, Nano-Coating Technology End User: Automotive, Construction, Electronics, Furniture Application: Solar Control, Thermal Management, Insulation, Aesthetic Enhancement |
| Companies Covered | 3M, Saint-Gobain, DuPont, Toray Industries, Avery Dennison Corporation, UBE Corporation, Eastman Chemical Company, Johnson Window Films, Cosmo Films Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Insulating Films Market Emerging Trajectories
Film architecture is converging toward sub-50-micron multilayer stacks that integrate passive thermal control with active system compatibility, compressing the performance gap between metalized and ceramic solutions.
Ceramic nanoparticle dispersion technology is migrating from automotive OEM specification toward commercial building retrofits. German glazing contractors now specify nano-coated films for listed heritage structures where metallic interference disrupts wireless building systems. This shift is compressing the addressable market for conventional sputtered silver stacks in premium architectural segments.
REACH and the EU F-Gas Regulation are tightening the allowable volatile organic compound content in pressure-sensitive adhesives. Coating houses serving the European market are reformulating toward UV-cured acrylic systems that eliminate solvent drying stages. Automotive glazing integrators face the steepest compliance burden, as cabin air quality standards now extend to film outgassing specifications.
Facility managers are consolidating window retrofit decisions under energy service company contracts that bundle film installation with guaranteed HVAC savings. This procurement compression disadvantages independent film distributors lacking performance underwriting capabilities. The model is most advanced in California and New York, where utility demand-response programs validate savings claims through metered verification.
Heat Insulating Films Market Segmentation
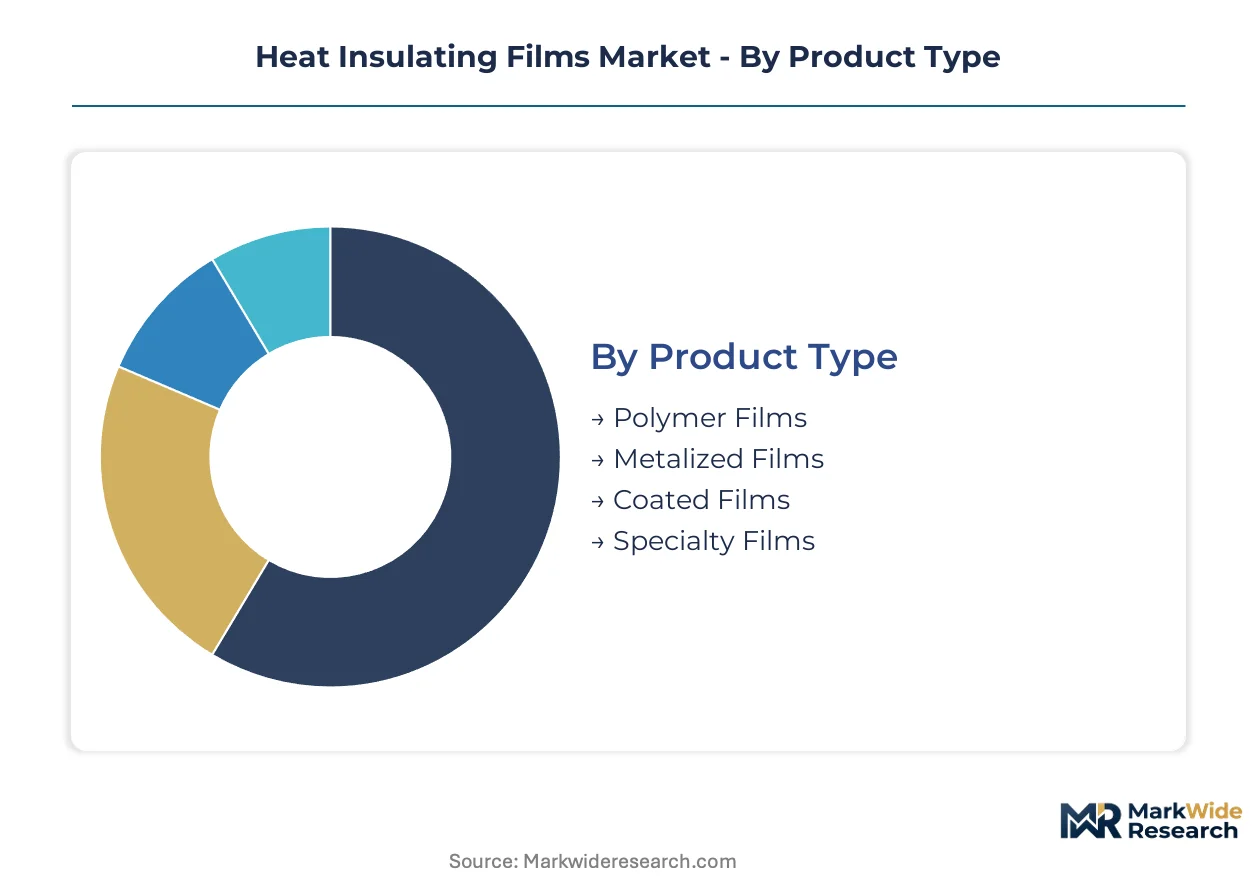
Segmentation in heat insulating films determines specification pathways, margin structures, and service intensity requirements. Product architecture and technology choices lock in performance ceilings, while end-use and application segments dictate certification burdens and distribution channel selection.
Product Type:
After-sales service intensity varies sharply across product categories, with metalized films demanding vacuum equipment maintenance contracts and specialty films requiring application training and warranty support.
- Metalized Films:These laminates incorporate sputtered aluminum or silver layers on polyester substrates to reflect infrared radiation. German automotive suppliers specify these for EV battery enclosures, though silver price volatility compresses margins during commodity spikes.
- Coated Films:Ceramic or dielectric coatings deposited via sol-gel or CVD processes absorb and re-radiate thermal energy. Japanese glazing contractors favor these for heritage building retrofits where metallic interference disrupts wireless systems.
- Polymer Films:Intrinsic infrared-absorbing polymers blended into extruded substrates serve cost-sensitive furniture and appliance applications with minimal technical support requirements.
- Specialty Films:Electromagnetic interference-shielding and electrochromic variants command premium pricing in aerospace and medical electronics, with application certification driving intensive field service.
By volume, metalized films lead. By growth pace, coated films are ahead.
Technology:
Technology selection tracks end-use performance thresholds, with automotive and electronics segments pushing toward thinner, spectrally selective solutions.
- Reflective Technology:Vacuum-deposited metallic layers achieve the highest infrared rejection ratios. East Asian manufacturing clusters dominate production, though REACH adhesive reformulation adds compliance costs for European export.
- Nano-Coating Technology:Dispersed ceramic nanoparticles in polymer matrices enable sub-50-micron constructions. MIIT automotive lightweighting directives in China accelerate specification for cabin glazing and battery thermal management.
- Absorptive Technology:Dye- and pigment-loaded substrates convert radiant energy to conducted heat, finding residual demand in residential solar control where cost trumps longevity.
- Hybrid Technology:Combined reflective-absorptive stacks balance optical clarity with thermal performance. Building-integrated photovoltaics manufacturers specify these for glazing interlayers that manage cell temperature without efficiency degradation.
Reflective technology holds installed base dominance. Nano-coating technology is climbing the fastest.
End User:
End-user concentration shapes regional manufacturing location decisions and certification portfolio investments.
- Automotive:OEM and tier-one supplier specifications demand MIL-STD thermal cycling validation and zero-defect traceability. German and Japanese manufacturers now mandate heat insulating films for EV battery pack thermal management.
- Construction:Energy service company procurement models bundle film installation with guaranteed HVAC savings, favoring suppliers with performance underwriting capabilities. EU Green Deal renovation targets concentrate demand in Germany, France, and Italy.
- Electronics:Miniaturization trends in smartphones and laptops drive demand for ultra-thin thermal management films with dielectric properties.
- Furniture:Appliance and fixture manufacturers specify cost-optimized films for aesthetic and moderate thermal control applications with minimal regulatory burden.
Construction commands volume leadership. Automotive is gaining share fastest.
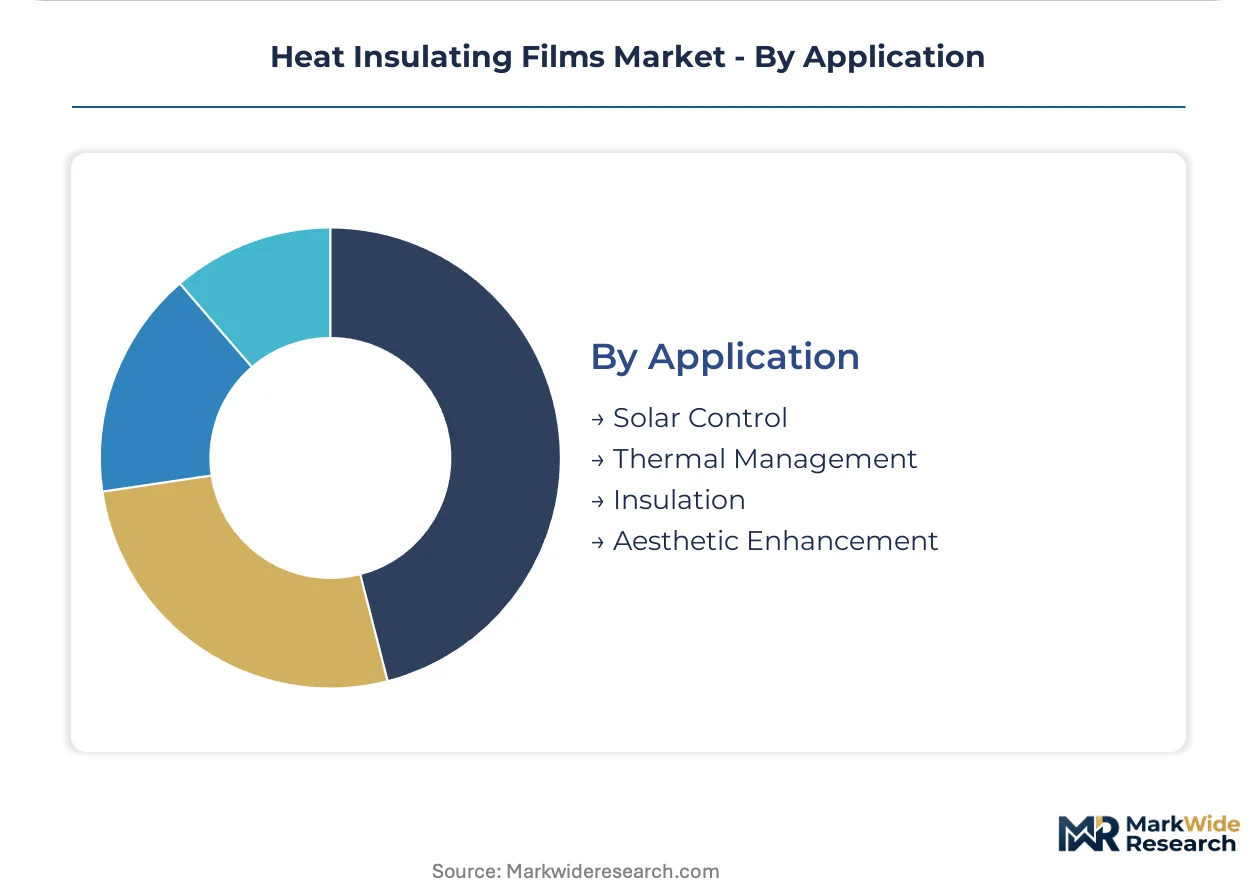
Application:
Application segmentation determines whether films compete on energy payback metrics or aesthetic and functional integration.
- Solar Control:Window retrofit programs in California and New York validate energy savings through utility demand-response metering, compressing procurement toward ESCO-channel suppliers.
- Thermal Management:Active system protection for batteries, electronics, and HVAC components requires films that sustain performance under thermal stress and mechanical flexure.
- Insulation:Building envelope applications compete with low-emissivity glass and aerogel alternatives on whole-wall R-value economics.
- Aesthetic Enhancement:Decorative and privacy-tinted films in commercial interiors prioritize visible light transmission and color stability over thermal performance.
Solar control leads by specification frequency. Thermal management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters export metalized films to European retrofit contractors, while German automotive supply chains import nano-coated variants for EV thermal management. This trade pattern concentrates value capture in coating technology licensors and toll-coating operators.
China
MIIT automotive lightweighting directives accelerate specification of sub-50-micron films for battery enclosures and cabin glazing. GB standards for building energy efficiency tighten envelope performance thresholds, forcing reformulation of adhesive chemistries. Yangtze River Delta coating houses scale vacuum deposition capacity for export to European window retrofit programs.
Germany
OEM and tier-one suppliers mandate heat insulating films for EV battery pack thermal management under KBA validation protocols. EU Green Deal renovation targets concentrate commercial building retrofit demand in Bavaria and North Rhine-Westphalia. Stuttgart automotive glazing integrators specify hybrid reflective-absorptive stacks for embedded sensor compatibility.
Japan
METI efficiency standards push appliance manufacturers toward ultra-thin thermal management films. JIS certification requirements extend product launch cycles for European export. Chubu precision coating lines supply captive polymer resin formulations to Asian automotive clusters.
United States
EPA Energy Star certification programs shape performance thresholds for residential and commercial specification. California and New York utility demand-response programs validate window retrofit savings through metered verification, compressing procurement toward ESCO-channel suppliers. Southeast toll-coating partnerships serve furniture and appliance OEMs with cost-optimized polymer variants.
India
Bureau of Indian Standards envelope performance standards for commercial construction create first-mover opportunity for film suppliers establishing local partnerships. Maharashtra and Gujarat manufacturing clusters attract toll-coating investments targeting Middle East export. Central electricity authority codes tighten HVAC efficiency requirements, accelerating solar control film specification in commercial retrofits.
Heat Insulating Films Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and coating technology. The vendor base organizes around three archetypes: integrated glass-film distributors, captive resin-coating houses, and specialty substrate formulators. Consolidation pressures concentrate in European commercial retrofit channels where energy service company procurement models bundle installation with performance guarantees. Dominant competitive moves include backward integration into polymer resin production and geographic expansion through toll-coating joint ventures.
Among diversified materials conglomerates, 3M and Saint-Gobain exemplify platform integrators with glass-film distribution reach. Toray Industries anchors the captive production archetype through precision coating infrastructure. Eastman Chemical Company represents specialty substrate formulation, sustaining optical clarity under thermal stress.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| DuPont |
| Toray Industries |
| Avery Dennison Corporation |
| UBE Corporation |
| Eastman Chemical Company |
| Johnson Window Films |
| Cosmo Films Ltd |
| Others |
Supply Flow & Price Mechanics
Biaxially oriented polyester substrate production concentrates in China, Japan, and South Korea, tethering margin capture to coating technology licensors and toll-coating operators who command pricing power over downstream film converters.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by certification grade and volume scale. Premium tiers carry REACH-compliant adhesive formulations and MIL-STD thermal cycling validation, while economy tiers serve furniture and appliance OEMs with minimal regulatory burden. Price differentiation stems from silver and indium commodity exposure in metalized films, compressing margins during precious metal spikes. Construction ESCOs show lowest price sensitivity due to performance underwriting requirements, whereas residential retrofit contractors exhibit highest sensitivity to per-square-meter costs.
Supply Chain Analysis
Polyester resin feedstock draws from petrochemical complexes in China, South Korea, and Japan, with vacuum deposition equipment and sputtering targets as critical component dependencies. Raw material sourcing hinges on silver and indium spot markets, with ceramic nanoparticle precursors adding secondary supply complexity. Single-source vulnerability concentrates in East Asian coating houses serving European export markets, exposing buyers to logistics disruptions and tariff exposure. Distribution runs through integrated glass-film distributors for commercial retrofits, while automotive channels rely on direct tier-one supplier relationships with captive toll-coating partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat insulating films constitute a defensive-moat market where regulatory entrenchment creates sticky specification relationships; REACH compliance and multi-jurisdictional certification timelines embed switching costs that protect incumbent positions.
For Market Incumbents: Pre-empt nano-coating technology displacement by securing captive resin production and precision coating capacity in Yangtze River Delta clusters. Accelerate backward integration into polymer substrate formulation to offset silver price volatility. Defensive priority centers on locking ESCO channel relationships through performance underwriting capabilities before digital procurement platforms disintermediate traditional distribution tiers. For New Entrants and Emerging Players: Mid-market commercial buildings in India represent the most penetrable entry point, with Bureau of Indian Standards envelope codes creating first-mover advantage for local toll-coating partnerships. Building-integrated photovoltaics interlayer applications offer adjacent white-space with lower certification barriers than automotive or heritage building segments. Go-to-market execution should target Maharashtra and Gujarat manufacturing clusters with cost-optimized polymer variants for Middle East export. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European window retrofit specialists lacking upstream coating infrastructure. Five-to-ten year viability hinges on regulatory tightening trajectories in building energy codes and automotive lightweighting mandates. Acquisition priority targets toll-coating operators with vacuum deposition technician pipelines and established MIIT or KBA validation protocols. Signal to monitor: pace of EU Green Deal renovation fund disbursement and corresponding ESCO procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | Captive substrate supply insulates margin from East Asian PET film concentration and logistics disruption. |
| REACH-Compliant Adhesive Reformulation | UV-cured acrylic chemistry eliminates solvent drying stages and secures European commercial retrofit specification. |
| Toll-Coating Joint Venture in India | Maharashtra and Gujarat partnerships capture Bureau of Indian Standards first-mover advantage for Middle East export. |
| ESCO Channel Performance Underwriting | Guaranteed HVAC savings bundling locks out independent distributors lacking metered verification capabilities. |
| Nano-Coating Capacity Expansion | Sub-50-micron ceramic dispersion lines serve MIIT automotive lightweighting directives and heritage building wireless compatibility requirements. |
Methodological Framework
Cross-validation between primary interviews and secondary validation anchors the qualitative findings. Stakeholder engagement encompassed coating house technical directors, automotive tier-one procurement leads, ESCO contract managers, and glazing contractor specification teams. Secondary sources included customs trade data for polyester film and precious metal sputtering targets, SEC filings from diversified materials conglomerates, and MIIT automotive efficiency directive documentation. Bottom-up demand modeling triangulated against top-down macroeconomic overlays across the analysis window.
Calibration against historical capacity utilization rates and sputtering equipment installation databases refined segment-level projections. Segmentation dimensions spanned product architecture, coating technology, end-use industry, and regional regulatory cluster. CAGRs derived from trend extrapolation of specification cycle compression and code tightening trajectories, with automotive electrification and EU Green Deal renovation targets as primary demand drivers.
Macroeconomic conditions sit as an overlay; deviation in construction activity indices, precious metal commodity curves, or automotive production schedules would shift the trajectory. Forecasts embed assumptions on REACH adhesive reformulation timelines and MIIT enforcement intensity that warrant periodic reassessment. Cross-checking against EIA building energy consumption surveys and IEA efficiency policy databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Packaging Barrier Films Market