
 Retort Cartons Market | 2026-2036
Retort Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Retort Cartons Market Analytics
Multi-layer composite bundling is consolidating as the dominant configuration pattern for high-barrier retort applications. Tetra Pak leverages its aseptic technology heritage to anchor positions in ambient dairy and broth segments. Amcor competes through geographic dominance in Asia-Pacific flexible retort formats. SIG Combibloc differentiates via aluminum-integrated carton structures for extended shelf-life applications.
Retort cartons are laminated paperboard-based containers engineered with aluminum foil and polymer layers to withstand sterilization temperatures exceeding 121°C while preserving oxygen and light barriers. Their primary purpose centers on enabling shelf-stable food distribution without refrigeration dependency. Composite material configurations command the widest application scope across ready meals and pet food segments, while stand-up pouch formats sustain the fastest structural expansion in single-serve beverage and sauce applications. Rigid packaging types occupy mature margin pools in institutional foodservice channels.
EU REACH compliance and FDA food-contact substance notifications shape material selection and migration limits for retort carton barrier layers. The EU Green Deal's packaging recyclability mandates and California's SB 54 extended producer responsibility framework are forcing substrate redesign toward fiber-dominant structures. Stakeholders must monitor how evolving extended producer responsibility schemes in the European Union and United States alter cost allocation between brand owners and converter networks.
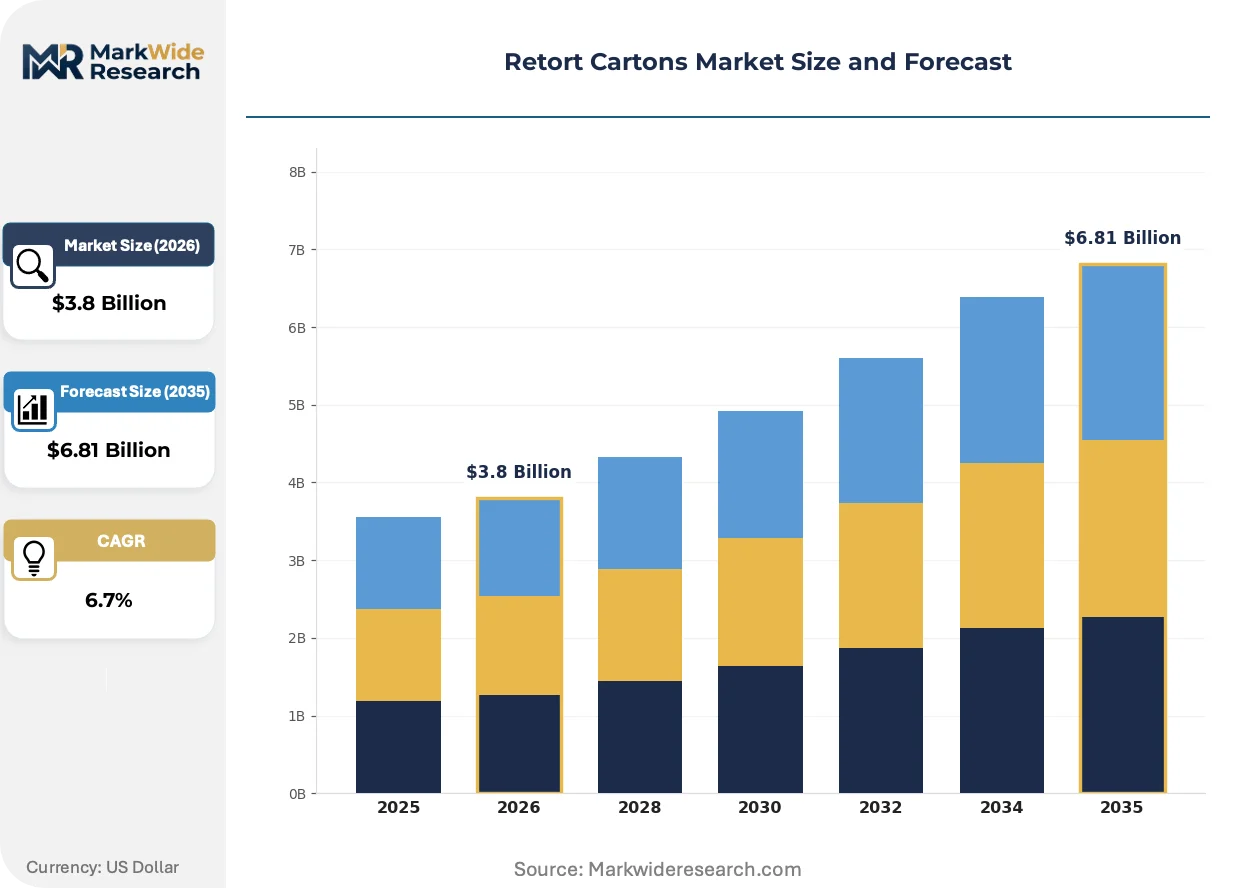
Market Dynamics
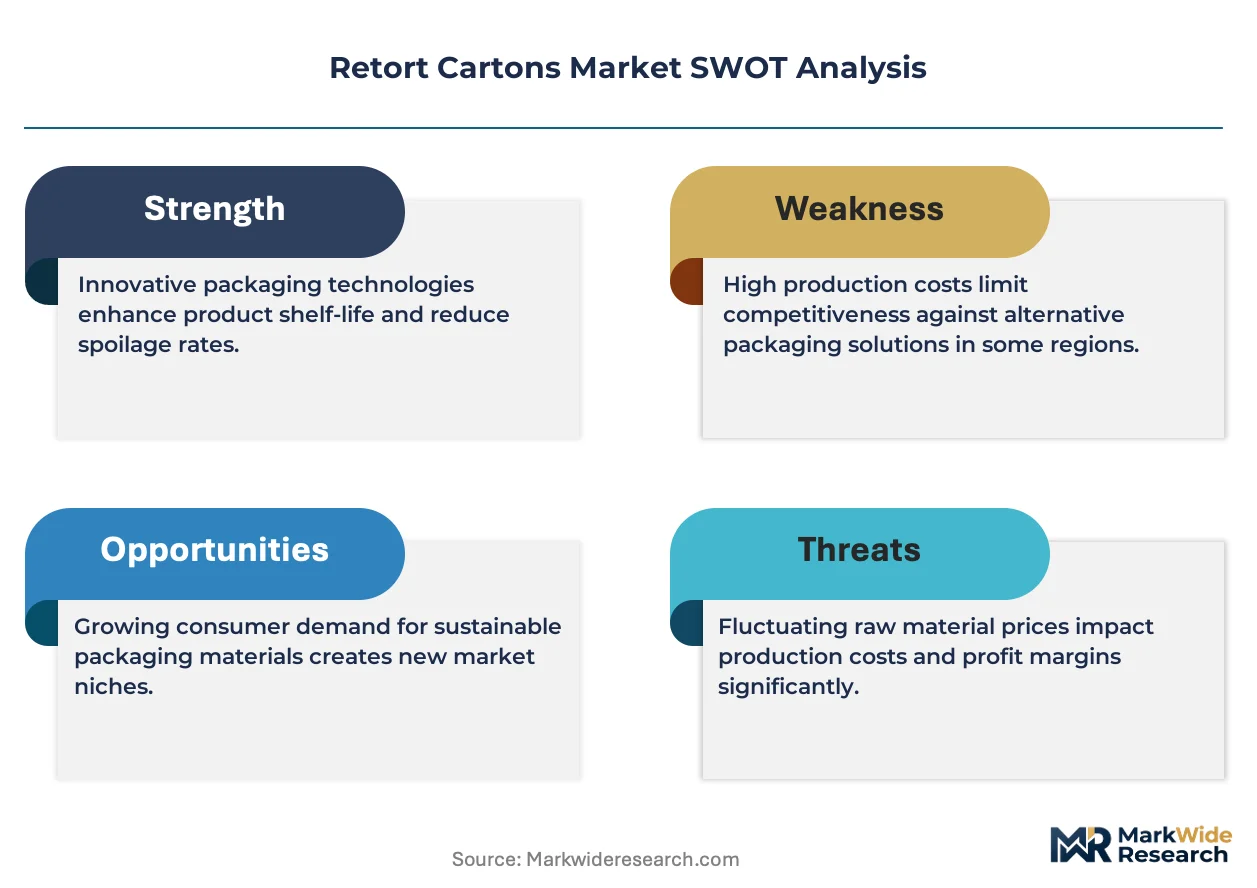
EU Green Deal recyclability mandates are forcing substrate redesign toward fiber-dominant structures, compressing converter margins while opening paths for aluminum-reduction technologies.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightened material recovery targets compel brand owners to adopt mono-material-compatible retort formats, accelerating converter R&D investment in separable barrier layers.
- Urban ready-to-eat meal demand:German food processors are prioritizing shelf-stable carton formats for single-serve curry and stew applications, pulling capacity expansion across Central European converter networks.
- Aluminum foil substitution:Metallized polymer and silicon oxide coatings are gaining technical validation for medium-barrier applications, reducing dependency on primary aluminum supply chains.
Market Restraints
- Aluminum price volatility:Primary aluminum input costs swing with energy-intensive smelter economics in China and Russia, squeezing laminate converters who cannot pass through indexed pricing.
- Adhesive supply concentration:Polyurethane and epoxy lamination chemistries depend on a narrow German and Japanese supplier base, creating vulnerability to force majeure disruptions.
- Retort temperature ceiling:Current polymer barriers degrade above 135°C, blocking penetration into ultra-high-temperature sterilized seafood and medical nutrition segments.
Strategic Opportunities
- India shelf-stable dairy:FSSAI-compliant retort gable-top formats for flavored milk and lassi remain underpenetrated versus polyethylene pouches, offering first-mover positioning.
- California SB 54 EPR framework:Extended producer responsibility cost allocation creates incentive for brand owners to fund fiber-dominant retort development through converter partnerships.
- Digital printing convergence:HP Indigo and Xeikon technologies enable short-run SKU proliferation for ethnic cuisine startups, collapsing minimum order quantities from 500,000 to 50,000 units.
Industry Challenges
- Migration testing capacity:EU REACH compliance requires specialized laboratories for simulant-based extraction studies, creating 12-18 month certification backlogs for new barrier formulations.
- Retort equipment retrofit costs:Converting legacy horizontal sterilizers to handle thinner-gauge aluminum-integrated cartons demands capital outlays that mid-tier co-packers defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retort Cartons Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Trays, Containers, Various Shapes Material: Paperboard, Aluminum, Plastic, Composite End Use: Food, Beverages, Pet Food, Pharmaceuticals Packaging Type: Flexible Packaging, Rigid Packaging, Eco-Friendly, Multi-Layer |
| Companies Covered | Tetra Pak, SIG Combibloc, Amcor, Elopak, Mondi, Sealed Air, Sonoco, ProAmpac, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retort Cartons Market Evolving Landscape
Material science breakthroughs and regulatory pressure are converging to restructure retort carton architecture, with sustainability metrics now dictating technical roadmaps ahead of cost optimization.
Paperboard fiber orientation technologies are decentralizing barrier function assignment across substrate layers rather than concentrating it in aluminum foil. German packaging engineers at Fraunhofer IVV are validating cross-laminated cellulose structures that distribute oxygen scavenging throughout the board matrix. Ready meal brand owners in France and the Netherlands are piloting these formats for 12-month ambient shelf life, compressing aluminum content by 40 percent while maintaining retort survivability.
REACH Article 33 substance disclosure requirements are tightening migration limits for bisphenol-derived epoxy phenolic coatings in European food-contact applications. ECHA's 2023 restriction proposal on intentionally added microplastics is forcing adhesive suppliers to reformulate solvent-based lamination systems. Infant nutrition and organic meal segments are responding fastest, specifying water-based or UV-cured alternatives that extend qualification timelines by 8-14 months.
Direct-to-retailer procurement contracts are displacing traditional distributor-mediated buying for private-label ready meals. Aldi and Lidl's centralized technical teams now specify carton barrier specifications directly, compressing converter sales cycles and unbundling technical service from volume commitments. This pattern is most visible in Germany and Poland, where discounter concentration exceeds 45 percent of ambient meal volumes.
Retort Cartons Market Segmentation
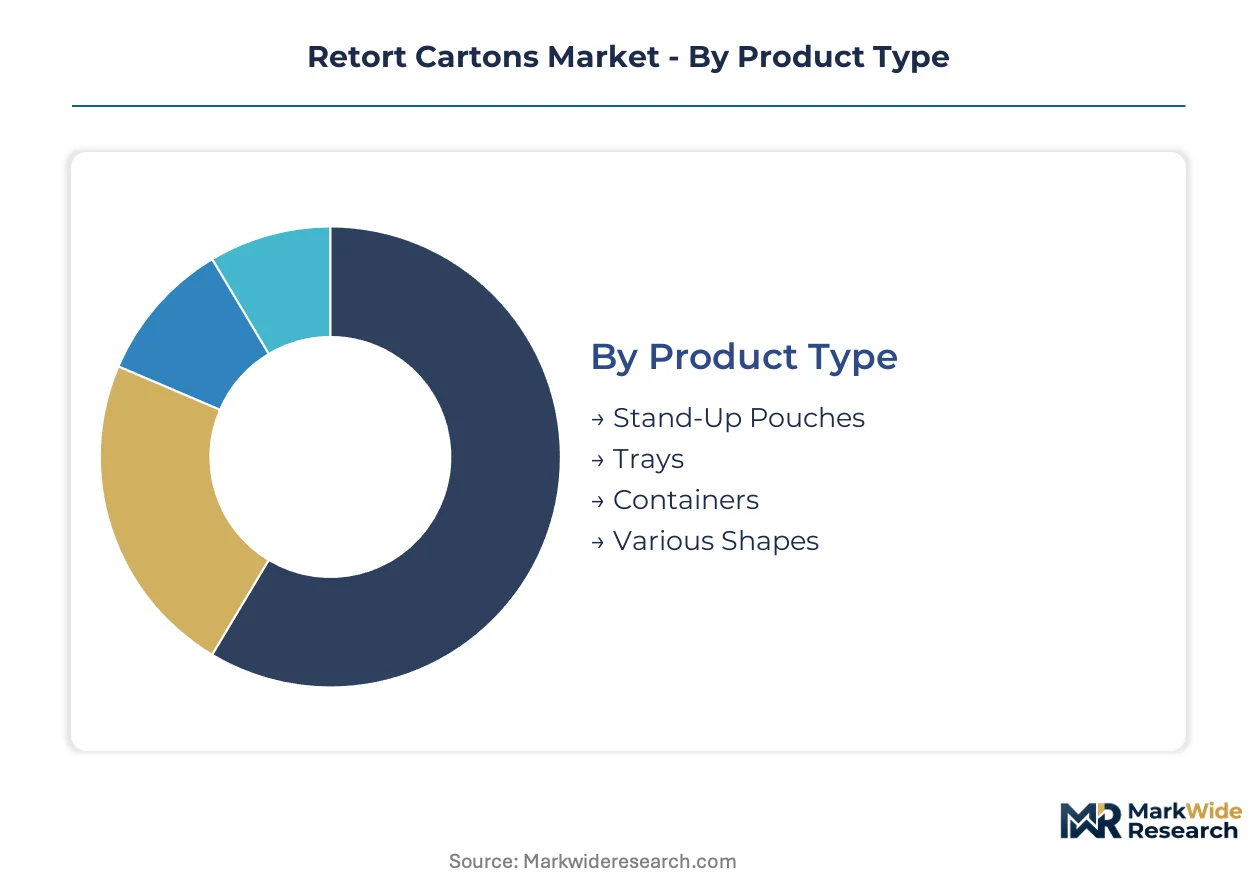
Retort carton architecture fragments across four intersecting dimensions that determine sterilization performance, recyclability compliance, and margin structure. Converter specialization concentrates in material science and barrier engineering, while brand owner procurement splits between shelf-stable food and emerging pharmaceutical applications.
Product Type:
Converter capacity concentrates in high-throughput formats where equipment amortization spreads across longer production runs.
- Stand-Up Pouches:Self-supporting laminated structures with bottom gussets optimize retail shelf presence and consumer handling. Single-serve beverage and sauce startups in Germany and Poland are pulling capacity expansion here, though thinner gauge films create retort equipment compatibility challenges.
- Trays:Rigid paperboard-based containers with sealed lidding films withstand horizontal sterilization cycles for ready meals. French and Dutch food processors specify these for 12-month ambient curry and stew applications where stackability matters.
- Containers:Cylindrical or rectangular formats with integrated closures serve institutional foodservice channels. German hospital and aged-care procurement teams favor these for portion control and reheat convenience.
- Various Shapes:Custom geometries for ethnic cuisine and premium gifting segments command prototype-to-production lead times of 16-24 weeks.
Today's leader: Trays. Tomorrow's challenger: Stand-Up Pouches.
Material:
Cost tier stratification separates commodity converters from specialty barrier suppliers.
- Paperboard:Kraft pulp-based substrates provide structural rigidity and fiber-dominant recyclability credentials. EU Green Deal mandates are accelerating Fraunhofer IVV-validated cross-laminated cellulose structures that distribute oxygen scavenging throughout the board matrix.
- Aluminum:Foil layers deliver sub-0.01 g/m²/day oxygen transmission rates for 24-month shelf life. Primary aluminum price volatility from Chinese and Russian smelter economics squeezes laminate converters who cannot pass through indexed pricing.
- Plastic:Polypropylene and polyethylene terephthalate films provide seal integrity and puncture resistance. Polymer barriers degrade above 135°C, blocking penetration into ultra-high-temperature sterilized seafood segments.
- Composite:Multi-layer configurations integrating paperboard, aluminum, and polymer dominate technical specifications for retort survivability. German and Japanese adhesive suppliers control polyurethane and epoxy lamination chemistries, creating force majeure vulnerability.
Composite structures command current volume. Fiber-dominant redesigns are climbing the fastest.
End Use:
Application maturity separates margin-stable foodservice contracts from speculative pharmaceutical qualification timelines.
- Food:Ready-to-eat meals, soups, and sauces constitute the installed base. Aldi and Lidl's centralized technical teams in Germany and Poland now specify carton barrier specifications directly, compressing converter sales cycles.
- Beverages:Shelf-stable dairy and broth segments leverage aseptic technology heritage. FSSAI-compliant retort gable-top formats for flavored milk and lassi remain underpenetrated in India versus polyethylene pouches.
- Pet Food:High-barrier requirements for nutrient preservation match human food specifications. Migration testing capacity for EU REACH compliance creates 12-18 month certification backlogs for new barrier formulations in this segment.
- Pharmaceuticals:Medical nutrition and enteral feeding demand sterility assurance beyond food-grade protocols. Infant nutrition segments specify water-based or UV-cured adhesives that extend qualification timelines by 8-14 months.
Food anchors revenue. Pharmaceuticals represent the steepest expansion trajectory.
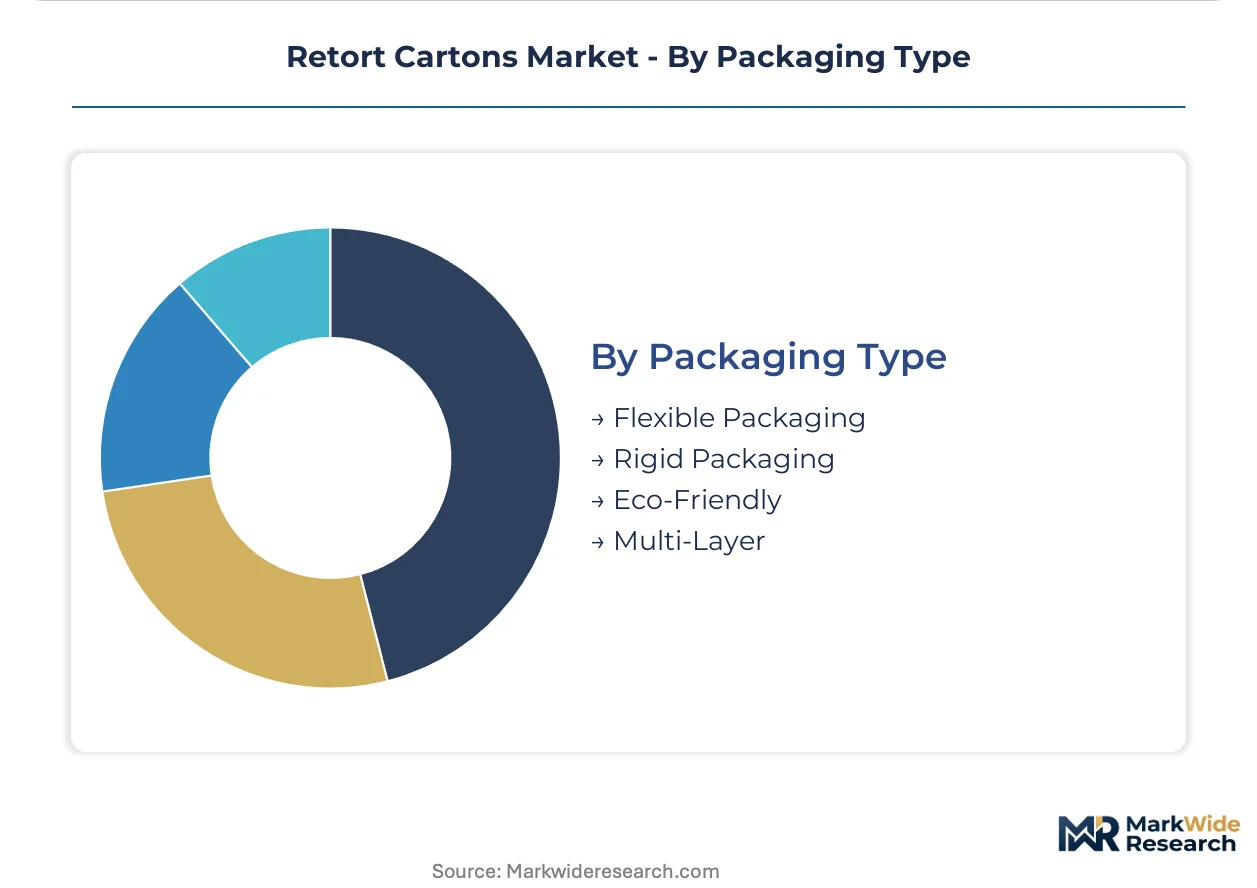
Packaging Type:
Customer procurement patterns split between cost-optimized flexible formats and performance-premium rigid structures.
- Flexible Packaging:Pouch and bag formats minimize material weight and shipping cube. Amcor competes through geographic dominance in Asia-Pacific flexible retort formats.
- Rigid Packaging:Structural integrity for automated handling and retail stacking commands mature margin pools. Institutional foodservice channels in Germany specify these for distribution robustness.
- Eco-Friendly:Aluminum-reduction and fiber-dominant structures respond to California SB 54 extended producer responsibility frameworks. Brand owners fund development through converter partnerships to shift cost allocation.
- Multi-Layer:Composite barrier architectures concentrate oxygen and light protection in discrete substrate layers. SIG Combibloc differentiates via aluminum-integrated carton structures for extended shelf-life applications.
Multi-Layer dominates technical specifications. Eco-Friendly formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retort carton technology originated in Sweden with Tetra Pak's 1951 aseptic breakthrough, establishing Scandinavian engineering dominance that persists in barrier lamination patents and sterilization protocol standards.
Germany
Aldi and Lidl's centralized procurement teams in Essen and Neckarsulm specify carton barrier requirements directly for private-label ready meals. The EU Packaging and Packaging Waste Regulation tightens material recovery targets for converters in Baden-Württemberg. Fraunhofer IVV in Freising validates cross-laminated cellulose structures that reduce aluminum content by 40 percent.
United States
California's SB 54 extended producer responsibility framework shifts cost allocation toward brand owners funding fiber-dominant retort development. FDA food-contact substance notifications govern migration limits for epoxy phenolic coatings in infant nutrition applications. Chicago and Milwaukee co-packing clusters face retrofit costs for legacy horizontal sterilizers handling thinner-gauge aluminum-integrated cartons.
India
FSSAI-compliant retort gable-top formats for flavored milk and lassi remain underpenetrated versus polyethylene pouches in Maharashtra and Gujarat. The Food Safety and Standards Authority of India mandates additive migration testing that creates certification backlogs for new barrier formulations. Pune-based dairy processors are piloting ambient shelf-stable carton capacity for ethnic beverage distribution.
France
Ready meal brand owners in Île-de-France pilot Fraunhofer-validated fiber-dominant formats for 12-month ambient curry and stew applications. ECHA's 2023 restriction proposal on intentionally added microplastics forces adhesive suppliers to reformulate solvent-based lamination systems. Lyon and Lille converter networks concentrate on aluminum-reduction technologies for organic meal segments.
Japan
PMDA sterility assurance protocols exceed food-grade specifications for medical nutrition and enteral feeding applications. METI supports metallized polymer coating R&D to reduce primary aluminum dependency in Osaka-Kobe industrial corridors. Polyurethane and epoxy lamination chemistry suppliers in Kansai face force majeure vulnerability from concentrated German and Japanese feedstock sources.
Retort Cartons Market Competitive Landscape
The competitive structure tilts toward integrated packaging conglomerates with aseptic technology heritage. Tier-one positions concentrate around beverage and dairy specialists possessing sterilization protocol expertise, while mid-tier converters compete on geographic proximity to food processing clusters. Two strategic archetypes dominate: aluminum-integrated barrier engineers and fiber-dominant sustainability innovators. M&A activity targets adhesive formulation capabilities, and capacity expansion concentrates in Central European converter networks serving German discount retail procurement.
Within the heritage-technology tier, Tetra Pak and SIG Combibloc exemplify Scandinavian engineering lineage in aseptic carton architecture. Amcor occupies a position among Asia-Pacific flexible format specialists. These three anchors demonstrate how geographic origin and company structure correlate with barrier technology specialization—Swiss-registered entities with GmbH or AG suffixes cluster around aluminum-integrated extended shelf-life applications, while Australia-registered PLCs emphasize flexible retort geographic coverage.
| Leading Market Players |
|---|
| Tetra Pak |
| SIG Combibloc |
| Amcor |
| Elopak |
| Mondi |
| Sealed Air |
| Sonoco |
| ProAmpac |
| Huhtamaki |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EU REACH-compliant barrier laminates and commodity-grade Asian imports manifests in both unit economics and procurement geography. German converters command 40 percent aluminum-reduction premiums for Fraunhofer-validated fiber-dominant structures, while spot-market purchasers in India absorb volatility from Chinese smelter output swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade sterilization assurance from foodservice commodity contracts. Price differentiation hinges on migration-testing certification depth and volume-scale commitments above 50,000 units. Cost compression in the economy tier intensifies because Indian dairy processors prioritize polyethylene pouch substitution over barrier performance. Private-label buyers at Aldi and Lidl exhibit highest price sensitivity; infant nutrition brand owners show least.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese adhesive suppliers controlling polyurethane and epoxy lamination chemistries. Primary aluminum feeds from Chinese and Russian smelter networks; kraft pulp draws from Scandinavian and Brazilian forestry operations; polymer films rest on South Korean and Thai extrusion capacity. Tariff exposure runs through EU carbon border adjustment mechanisms targeting energy-intensive inputs. Distribution runs through converter-co-packer-brand owner direct contracts, bypassing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort carton manufacturing functions as a geographic-arbitrage play where California SB 54 compliance costs exceed Indian FSSAI qualification expenses by multiples, rewarding early positioning in lower-regulation jurisdictions with export-ready technical capabilities.
For Market Incumbents: Deploy metallized polymer coating R&D to reduce primary aluminum dependency before EU Green Deal mandates accelerate. SIG Combibloc and Tetra Pak should backward integrate into adhesive formulation capabilities to neutralize force majeure risk from concentrated German-Japanese suppliers. Capacity expansion in Central European converter networks defends position against Asia-Pacific flexible format encroachment.
For New Entrants and Emerging Players: Begin with FSSAI-compliant retort gable-top formats for Maharashtra and Gujarat dairy processors, where polyethylene pouch substitution lags technical readiness. Target ethnic beverage startups in Pune seeking ambient shelf-stable distribution without cold-chain investment. Digital printing partnerships with HP Indigo or Xeikon collapse minimum order thresholds for SKU proliferation.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack capital for legacy horizontal sterilizer retrofits and thinner-gauge aluminum-integrated carton handling. Long-term viability favors adhesive formulation specialists with water-based or UV-cured alternatives qualified for infant nutrition segments. Watch ECHA microplastics restriction implementation timelines as inflection indicator for solvent-based lamination system obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum-Reduction Technology Licensing | Fraunhofer IVV validation enables 40 percent content reduction while maintaining retort survivability. |
| Water-Based Adhesive Qualification | REACH Article 33 compliance extends certification timelines but locks infant nutrition segment access. |
| Digital Printing Integration | HP Indigo and Xeikon partnerships collapse minimum order quantities from 500,000 to 50,000 units. |
| Backward Integration into Adhesive Supply | Captive polyurethane and epoxy chemistry neutralizes force majeure vulnerability from German-Japanese concentration. |
| India Gable-Top Capacity Buildout | FSSAI-compliant flavored milk and lassi formats remain underpenetrated versus polyethylene pouch alternatives. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured converter technical directors, brand owner procurement leads at Aldi and Lidl, co-packer operations managers in Chicago and Milwaukee, and adhesive supplier R&D heads in Germany and Japan. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, FDA food-contact substance notification databases, FSSAI additive migration testing records, and ECHA restriction proposal documentation. Bottom-up capacity modeling triangulated against top-down demand aggregation from food processor procurement disclosures.
Segment-weighting approaches distributed value and volume across product type, material composition, end-use application, and packaging format dimensions. CAGRs derived from installed base erosion rates, substitution elasticity parameters, and regulatory compliance cost trajectories across the projection horizon. Forecast inputs incorporated aluminum price volatility indices, EU Green Deal implementation schedules, and digital printing adoption curves in ethnic cuisine startup segments.
Several conditions sit outside the modeled scope, including force majeure disruptions at single-source adhesive suppliers, unilateral tariff adjustments on Chinese aluminum imports, and breakthrough polymer barriers surviving above 135°C sterilization temperatures. Forecasts reflect documented assumptions about regulatory implementation timelines and substitution elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market