

Holographic Transfer Film Market Size, Share, and Industry Trends Forecast 2026-2036
Holographic Transfer Film Market Insights
Pharmaceutical labellers is unwinding share toward consumer electronics assemblers seeking anti-counterfeit traceability. Toray Industries leverages its polymer science heritage to dominate embossed film substrates for premium packaging. Avery Dennison anchors North American supply through vertically integrated hot-stamping adhesive systems. Uflex competes on cost-engineered metalized films for emerging-market consumer goods.
Holographic transfer film comprises a micro-embossed thermoplastic substrate, typically PET or BOPP, carrying a vacuum-deposited aluminum or diffractive oxide layer that reconstructs light interference patterns for visual authentication and decoration. The film transfers via heat-activated or pressure-sensitive adhesive to paper, board, or synthetic surfaces, serving anti-counterfeiting and brand-enhancement functions across packaged goods. Metalized product types sustain the largest volume position due to established use in tobacco and spirits tax stamps, while clear films represent the fastest structural expansion as brands pursue visible-product aesthetics. Hot stamping technology leads equipment-installed base, though cold foil adoption accelerates in narrow-web label operations where setup speed determines job economics.
REACH compliance in Europe constrains chromium-based holographic pigments, redirecting formulation R&D toward vacuum-deposited oxides. FDA 21 CFR regulations for indirect food contact govern adhesive migration limits in US packaging applications, shaping laminate architecture decisions. China's GB standards for packaging recyclability, enforced by SAMR, mandate mono-material compatibility that holographic film suppliers must engineer around. Stakeholders should monitor evolving extended producer responsibility schemes, as these will determine whether decorative security films remain economically viable against digital watermark alternatives.
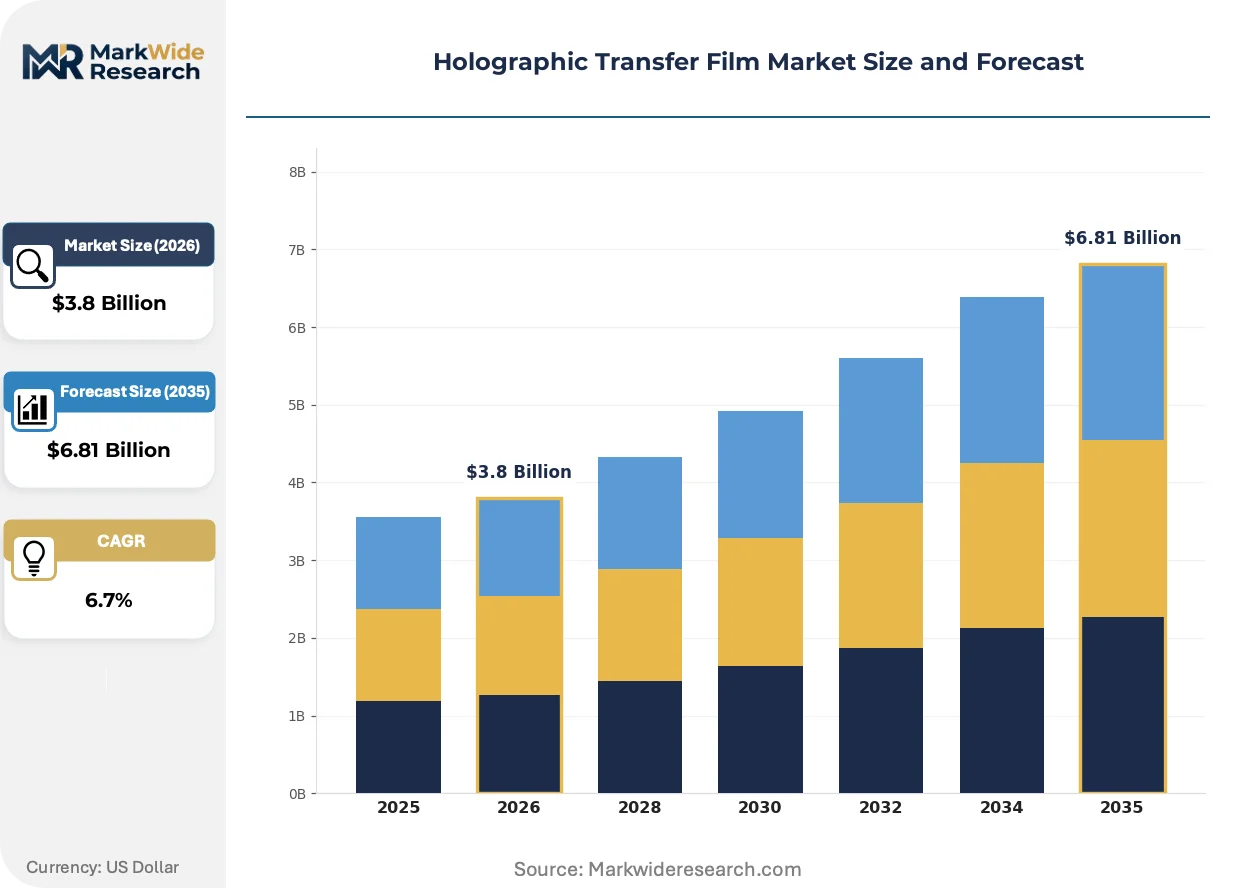
Market Dynamics
Pharmaceutical counterfeiters have forced labellers toward tamper-evident holographic substrates, while EU packaging waste directives simultaneously mandate PET recyclability. These dual pressures compress film architecture into mono-material designs that must satisfy both security performance and circular economy compliance.
Growth Catalysts
- EU Green Deal packaging directives:The EU Green Deal's waste reduction frameworks accelerate substrate innovation toward recyclable PET films. German automotive and pharmaceutical clusters drive precision security printing demand.
- Anti-counterfeiting mandates:Pharmaceutical regulators worldwide tighten traceability requirements. Tax stamp applications in tobacco and spirits sustain metalized film volumes.
- Cold foil technology:Narrow-web label operations adopt cold foil systems to compress job setup times. This equipment shift expands addressable market for holographic transfer films.
Market Restraints
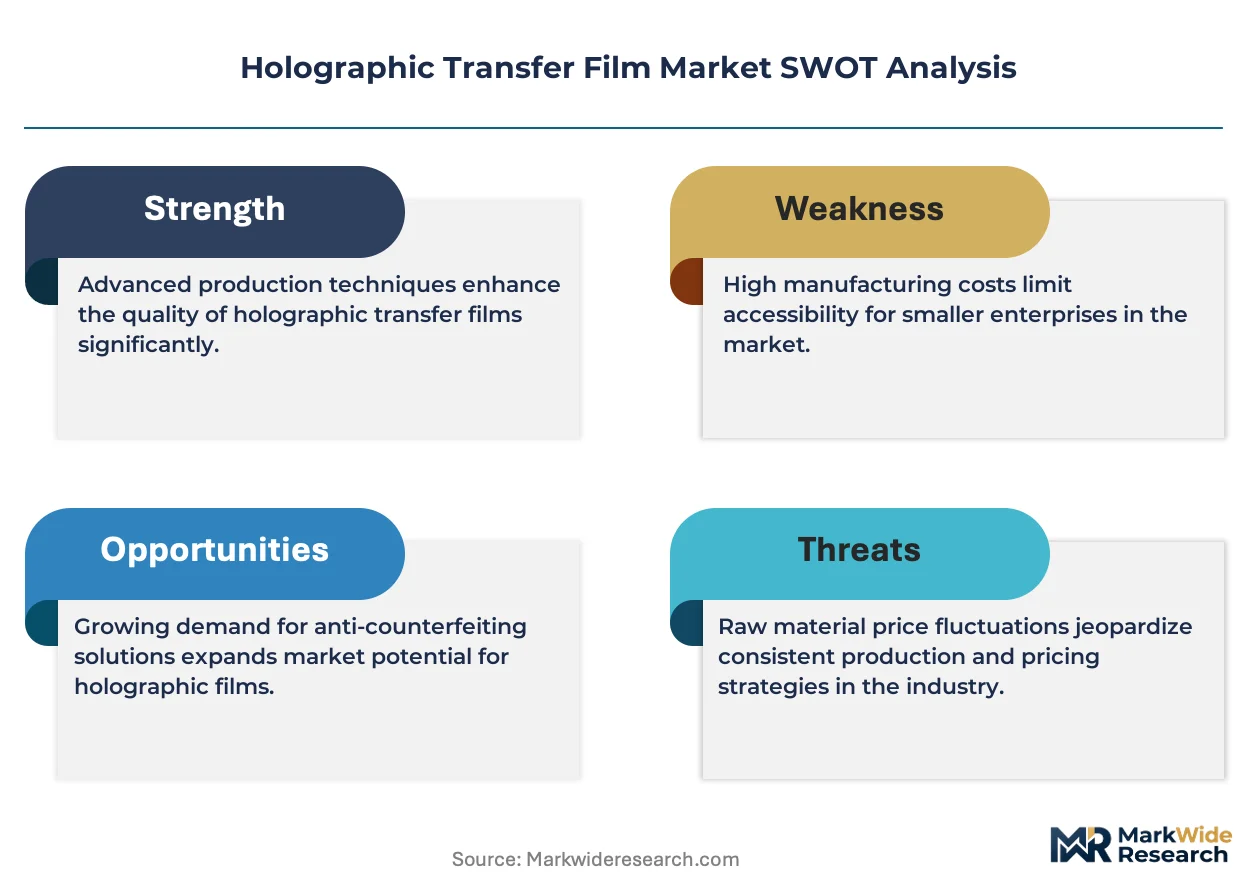
- Chromium pigment restrictions:REACH compliance constrains traditional holographic pigment formulations. Vacuum-deposited oxide alternatives require capital-intensive retooling.
- Raw material concentration:PET substrate supply concentrates among Asian polymer producers. European converters face freight cost volatility and extended lead times.
- Digital watermark substitution:Blockchain-integrated digital authentication threatens decorative security films. Extended producer responsibility schemes may tilt economics toward software-based alternatives.
Strategic Opportunities
- Consumer electronics traceability:Smartphone and wearable assemblers seek anti-counterfeit labels. This segment unwinds share from traditional pharmaceutical dominance.
- Clear film aesthetics:Premium cosmetics and spirits brands pursue visible-product packaging. Diffractive oxide layers enable security without metalized opacity.
- China's GB recyclability standards:SAMR-enforced mono-material compatibility mandates create specification windows. Suppliers engineering compatible films capture state-backed packaging modernization contracts.
Industry Challenges
- Adhesive migration compliance:FDA 21 CFR indirect food contact limits constrain laminate architecture. Reformulation cycles extend certification timelines.
- Micro-embossing talent scarcity:Precision thermoplastic patterning requires specialized optical engineering. European and North American converters compete for limited expertise pools.
- Legacy hot-stamp integration:Cold foil adoption demands equipment reconfiguration. Narrow-web operators face capital allocation decisions between speed gains and sunk installed base.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holographic Transfer Film Market Trends and Innovations
Material scientists and converters are re-engineering holographic film stacks to reconcile optical performance with circular material flows. Three concurrent developments reshape competitive positioning.
Nano-structured diffractive surfaces are displacing conventional aluminum vacuum deposition in premium packaging segments. Cosmetics houses and spirits marketers adopt these oxide-based films to maintain shelf visibility while satisfying recyclability audits. The shift compresses metalized film margins in discretionary categories.
REACH substance restrictions redirect European formulation R&D away from chromium-bearing holographic pigments. ECHA guidance on candidate list substances forces converters toward vacuum-deposited oxide chemistries. German automotive suppliers and pharmaceutical packagers absorb premium pricing for compliant substrates.
Brand owners now specify mono-material compatibility at contract inception. Procurement teams in France and Italy reject multi-layer laminates that complicate mechanical recycling streams. This specification tightening favors film suppliers with integrated polymer science capabilities over pure-play converters.
Holographic Transfer Film Market Segmentation
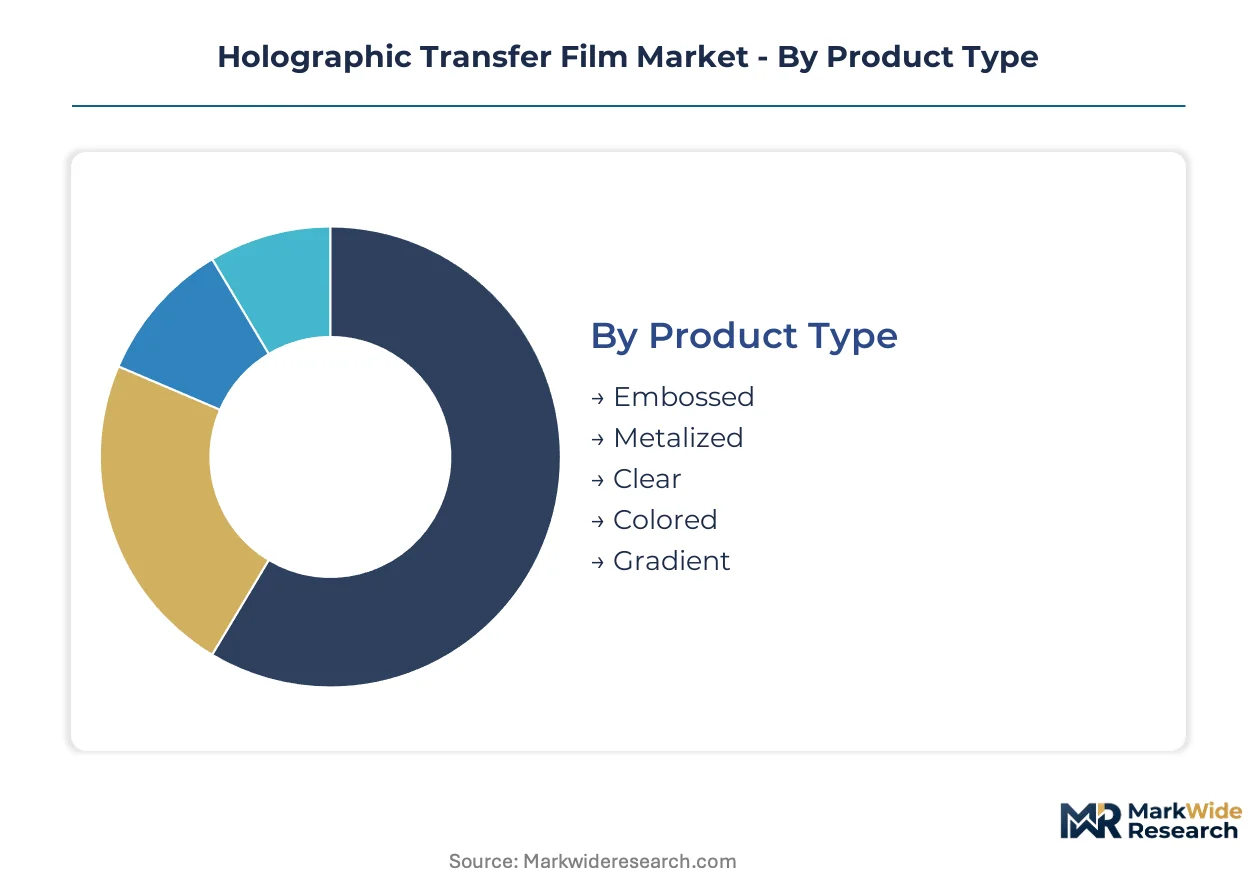
Holographic transfer film segmentation reflects divergent supply chain configurations across optical technologies and end-use specifications. Category boundaries determine whether converters compete on capital-intensive equipment integration or material formulation differentiation.
Product Type:
Metalized films anchor domestic production in Germany and Japan where precision vacuum deposition clusters serve regional automotive and pharmaceutical demand. Clear and gradient variants flow through export-oriented supply chains targeting premium cosmetics houses in France and spirits marketers in Scotland.
- Metalized:Aluminum vacuum-deposited layers on PET substrates deliver high-contrast diffraction for tax stamps and tobacco packaging. German automotive suppliers specify these films for dashboard authentication labels under KBA traceability guidelines. REACH compliance constraints on chromium pigments redirect formulation toward oxide alternatives at elevated cost positions.
- Clear:Diffractive oxide layers enable security functionality without metalized opacity, satisfying visible-product aesthetics in premium spirits and cosmetics. French procurement teams mandate mono-material compatibility under extended producer responsibility schemes, compressing multi-layer laminate acceptance.
- Embossed:Micro-patterned thermoplastic substrates serve decorative packaging where optical precision requirements moderate.
- Colored:Pigmented resin systems target brand-specific hue matching in consumer goods applications.
- Gradient:Variable-density deposition creates transitional optical effects for limited-edition packaging campaigns.
Metalized films command the established base. The steepest expansion runs through Clear films.
Application:
Cost tier stratification separates high-volume packaging converters from specialized security printers. Security printing commands premium pricing through certification requirements, while textiles and cosmetics decoration compete on batch flexibility and color fidelity.
- Packaging:Folding carton and flexible film applications consume the largest substrate volumes, with German pharmaceutical clusters driving tamper-evident specification adoption. EU Green Deal packaging waste directives force substrate redesign toward recyclable PET architectures.
- Security Printing:Tax stamps, identity documents, and banknote threads demand sub-micron pattern precision. Chinese state mints and European security printers maintain captive supply relationships with qualified film suppliers.
- Textiles:Heat-transfer applications on synthetic fabrics serve fashion and sportswear branding.
- Cosmetics Decoration:Premium skincare and fragrance houses specify clear diffractive films for visible-product secondary packaging.
- Consumer Electronics:Smartphone and wearable assemblers adopt anti-counterfeit labels for component traceability.
Packaging captures volume leadership. Security printing generates the highest margin contribution per square meter.
End User Industry:
Customer type determines specification complexity and contract duration. Pharmaceutical labellers demand multi-year supply agreements with audit trails, while consumer goods manufacturers operate on shorter procurement cycles with spot pricing.
- Pharmaceutical Labellers:FDA 21 CFR indirect food contact compliance and EMA serialization mandates drive specification rigor. German and Swiss packaging converters integrate tamper-evident holographic substrates into folding carton lines.
- Consumer Goods Manufacturers:Spirits and tobacco tax stamp applications sustain metalized film demand through state procurement contracts.
- Printing Companies:Commercial converters serve mid-market brand owners with hot-stamping integration.
- Textile Producers:Heat-transfer decorators target fast-fashion velocity with shorter run lengths.
- Electronics Assemblers:Component traceability requirements expand addressable market beyond traditional packaging.
Pharmaceutical labellers anchor specification development. Electronics assemblers are gaining share fastest among emerging demand segments.
Technology:
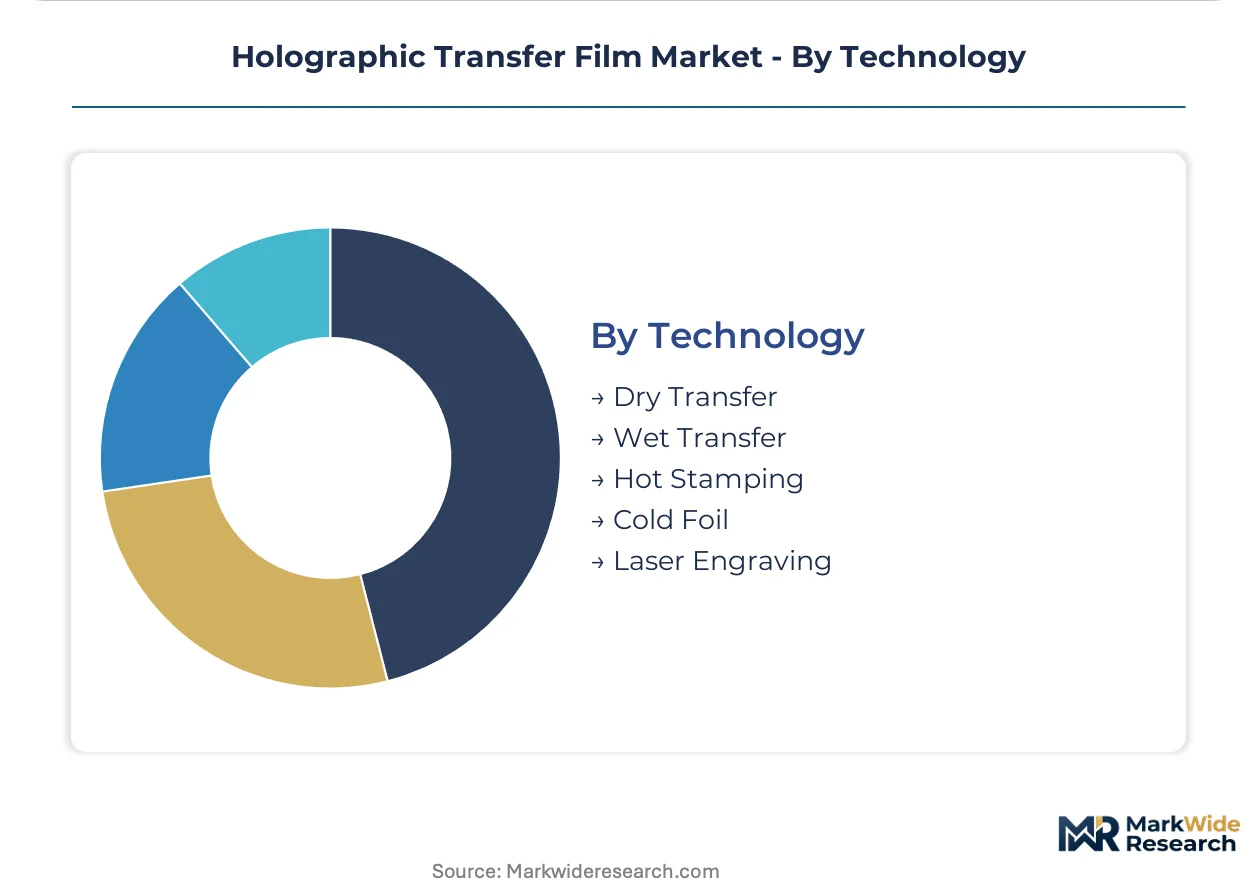
Equipment maturity curves separate installed-base dominance from adoption velocity. Hot stamping retains the largest equipment footprint, while cold foil systems capture narrow-web label economics.
- Hot Stamping:Heat-activated adhesive transfer through rotary dies dominates high-volume tobacco and spirits tax stamp production. German and Italian OEMs control equipment supply, constraining converter technology switching.
- Cold Foil:UV-curable adhesive systems compress job setup times in narrow-web label operations. French and UK converters adopt these systems for pharmaceutical serialization runs where changeover frequency determines economics.
- Dry Transfer:Pressure-sensitive adhesive films serve short-run decorative applications.
- Wet Transfer:Water-based adhesive systems target textile and paper substrates with specific surface energy requirements.
- Laser Engraving:Direct substrate ablation enables customized security features without master tooling.
Hot stamping retains the installed base advantage. Cold foil systems are climbing the fastest among technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters export precision holographic films to pharmaceutical packagers in Switzerland and France, while Chinese substrate manufacturers supply metalized PET to Southeast Asian tax stamp printers. Trade corridors reflect divergent specialization: European suppliers command security-printing premiums, Asian producers capture volume scale in consumer goods decoration.
Germany
Automotive dashboard authentication labels and pharmaceutical tamper-evident packaging drive substrate demand. KBA traceability guidelines mandate holographic verification for vehicle components. The Baden-Württemberg precision printing cluster hosts converters integrating REACH-compliant oxide films into serialization lines.
China
State mint procurement and spirits tax stamp applications sustain metalized film volumes. SAMR-enforced GB packaging recyclability standards force mono-material engineering. The Yangtze River Delta concentration of polymer producers supplies PET substrates to converters serving domestic and Southeast Asian brand owners.
United States
FDA 21 CFR indirect food contact compliance shapes adhesive formulation for folding carton applications. Spirits and tobacco tax stamps sustain metalized demand through state procurement contracts. The Pacific Northwest hosts narrow-web label converters adopting cold foil systems for pharmaceutical serialization runs.
France
Premium cosmetics houses specify clear diffractive films for visible-product secondary packaging. Extended producer responsibility schemes under EU Green Deal frameworks reject multi-layer laminates. The Île-de-France procurement corridor mandates mono-material compatibility at contract inception.
Japan
Precision electronics assemblers adopt anti-counterfeit labels for component traceability. METI circular economy guidelines accelerate substrate innovation toward recyclable architectures. The Kanto region hosts converters serving automotive and consumer electronics clusters with sub-micron pattern precision.
Holographic Transfer Film Market Competitive Landscape
Player mix skews toward diversified polymer science conglomerates with captive film substrate production. Market structure concentrates among Asian PET producers and European precision converters, with mid-tier specialists occupying narrow-web label niches. Strategic archetypes separate vertically integrated substrate suppliers, equipment-integrated adhesive system providers, and cost-engineered metalized film exporters. Competitive moves center on REACH-compliant formulation R&D and cold foil technology licensing partnerships.
Among Japanese and American diversified materials groups, Toray Industries and Avery Dennison occupy positions reflecting polymer science heritage and adhesive system integration respectively. Toray exemplifies the substrate-integrated archetype with embossed film capabilities. Avery Dennison represents equipment-adhesive bundling strategies in North American supply. Uflex anchors the cost-engineered metalized film tier serving emerging-market consumer goods.
| Leading Market Players |
|---|
| Toray Industries |
| Cosmo First |
| Avery Dennison |
| Uflex |
| K Laser Technology |
| Nan Ya Plastics Corporation |
| Jindal Poly Films |
| UNIVACCO Foils Corporation |
| Holostik India |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between German pharmaceutical packagers and PET substrate suppliers lock in volume commitments and price visibility across multi-year serialization mandates, insulating converters from spot resin volatility while embedding REACH compliance premiums into negotiated rates.
Pricing Analysis
Current-generation cold foil systems command 15-25% premiums over legacy hot-stamping equipment, while next-generation nano-structured diffractive surfaces extract further uplifts from cosmetics houses seeking visible-product aesthetics. Pricing stratifies across REACH-certified oxide films, standard metalized substrates, and cost-engineered BOPP alternatives. Price differentiation hinges on certification grade for EU Green Deal compliance and volume scale for tax stamp procurement contracts. Cost compression in metalized film tiers is intensifying because Chinese substrate manufacturers are expanding PET production capacity. Consumer electronics assemblers exhibit highest price sensitivity due to razor-thin component margins, while pharmaceutical labellers absorb premiums for tamper-evident traceability assurance.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for European converters sourcing PET resin from Yangtze River Delta polymer producers. Raw material supply concentrates in China, Germany, and Japan, where vacuum deposition equipment and precision embossing tooling cluster. The holographic film value chain draws from aluminum ingot suppliers, optical-grade PET substrate manufacturers, and UV-curable adhesive formulators. Single-source vulnerability in micro-embossing master tooling creates chokepoint exposure for narrow-web label converters. Distribution runs through qualified converter networks serving regional pharmaceutical clusters and state-backed security printers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Holographic transfer film manufacturers increasingly attach technical service contracts and serialization integration support to substrate sales, with recurring software-enabled authentication layers expanding faster than commodity film volumes. This service-attach dynamic reshapes margin architecture away from pure materials competition.
For Market Incumbents: Consolidate backward integration into REACH-compliant oxide deposition capabilities to defend against digital watermark substitution threats. Acquire narrow-web label converters in France and Germany to capture cold foil adoption velocity and lock in pharmaceutical serialization workflows. Capacity expansion in Baden-Württemberg reinforces proximity to automotive authentication demand while compressing logistics exposure to Asian resin supply. For New Entrants and Emerging Players: Differentiate on mono-material PET compatibility engineered for China's GB recyclability standards, targeting spirits and cosmetics packagers in Southeast Asia where SAMR-compliant specifications are diffusing. White-space opportunity concentrates in consumer electronics traceability labels for Japanese and South Korean wearable assemblers. Go-to-market leverage rests on licensing nano-embossing IP from European optical engineering boutiques rather than capital-intensive equipment buildout. For Investors and Strategic Acquirers: Specialized cold foil adhesive formulators with pharmaceutical certification track records represent the most defensible acquisition archetype in a market tilting toward equipment-integrated solution selling. Long-term viability hinges on whether decorative security films retain economic positioning against blockchain-integrated digital authentication over the next decade. Watch for extended producer responsibility scheme enforcement in France and Italy as the inflection signal determining laminate architecture winners.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Oxide Deposition Scale-Up | European converters absorb premium pricing for ECHA-compliant substrates under tightening candidate list restrictions. |
| Cold Foil Technology Licensing | French and UK narrow-web operators adopt UV-curable systems to compress pharmaceutical serialization changeover times. |
| Mono-Material PET Engineering | SAMR-enforced GB standards in China create specification windows for recyclable film architectures. |
| Consumer Electronics Label Integration | Japanese and South Korean smartphone assemblers expand anti-counterfeit traceability beyond traditional pharmaceutical demand. |
| Serialization Workflow Partnerships | German pharmaceutical packagers bundle tamper-evident substrates with track-and-trace software for multi-year contract lock-in. |
Research Methodology
Initial hypotheses were tested against primary input from holographic film converters, pharmaceutical packaging procurement managers, narrow-web label equipment OEMs, and optical engineering specialists, and refined through secondary validation against customs trade data, ECHA substance restriction updates, FDA 21 CFR guidance documents, and SAMR GB standard enforcement records. Bottom-up demand modeling across tax stamp, pharmaceutical serialization, and consumer electronics traceability applications was triangulated against top-down substrate production capacity estimates from PET polymer producers.
Variance decomposition across the projection horizon isolates volume drivers by product type, application, end-user industry, and technology adoption curve, with CAGRs derived from segment-level growth rate reconciliation against macro packaging spend indicators. Industry-specific forecast inputs include EU Green Deal implementation timelines for extended producer responsibility schemes and cold foil equipment installation rates in European narrow-web converter bases.
Material uncertainties — regulatory acceleration in digital watermark substitution, REACH substance list expansion, and PET resin supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding pharmaceutical serialization mandate enforcement and SAMR recyclability standard adoption trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.