
 Barrier Foil Market | 2026-2036
Barrier Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Foil Market Outlook
Southeast Asia is narrowing the supply gap for metallized films as Vietnam and Thailand add converting capacity. Mondi Group leverages its integrated pulp-to-packaging network to control substrate costs across European operations. Hindalco Industries Ltd anchors South Asian supply with captive aluminum smelting and rolling assets. Amcor Plc differentiates through pharmaceutical-grade cleanroom certification and barrier validation protocols.
Barrier foil consists of multi-layer laminates combining aluminum, polyester, polyethylene, or nylon substrates engineered to block moisture, oxygen, and light transmission, typically achieving water vapor transmission rates below 0.1 g/m²/day. Manufacturers produce these structures through adhesive lamination, extrusion coating, or vacuum metallization to protect oxygen-sensitive pharmaceuticals, moisture-critical electronics, and shelf-stable food matrices. Aluminum foil leads material value contribution due to near-zero gas permeability and established supply chains, while nylon film segments expand fastest in retort pouch applications requiring puncture resistance and thermal stability. Pharmaceutical packaging commands premium positioning as validation requirements and serialization mandates elevate technical barriers for new entrants.
FDA enforces strict barrier performance and extractables testing for primary pharmaceutical packaging under current Good Manufacturing Practice guidelines, while EMA's Medical Device Regulation extends conformity requirements to sterile barrier systems. REACH compliance in Europe restricts certain adhesive chemistries and mandates substance disclosure across laminate structures, redirecting formulation investment toward water-based and solvent-free bonding technologies. Stakeholders must monitor evolving extended producer responsibility frameworks and recyclability targets that threaten conventional multi-material constructions.
Market Dynamics
The EU Green Deal's recyclability mandates are forcing a structural pivot away from conventional multi-layer laminates toward mono-material and recyclable barrier constructions, compressing established formulation margins while opening technical white space for adhesive innovators.
Growth Catalysts
- Cold-chain biologics expansion:Temperature-sensitive pharmaceutical shipments require ultra-high barrier performance with thermal insulation, pulling foil laminates into specialized logistics packaging for cell and gene therapies.
- REACH substance disclosure mandates:European chemical transparency rules redirect R&D investment toward water-based and solvent-free bonding chemistries, accelerating compliant adhesive platforms.
- Vietnam and Thailand converting capacity:Southeast Asian metallized film production is narrowing regional supply gaps, shortening lead times for Asia-Pacific electronics and food packaging customers.
Market Restraints
- Aluminum ingot price volatility:Primary metal cost swings transmit directly into foil laminate economics, squeezing converter margins during commodity upswings.
- Multi-material construction incompatibility:Conventional aluminum-polyester-polyethylene structures face mechanical recycling exclusion under EU extended producer responsibility frameworks.
- Captive smelter concentration in South Asia:Hindalco's integrated aluminum supply anchors regional substrate availability, creating single-source dependency risk for downstream laminators.
Strategic Opportunities
- Pharmaceutical-grade cleanroom certification:Barrier validation protocols and serialization mandates erect technical moats that specialized converters can monetize through premium positioning.
- Nylon film retort pouch applications:Puncture resistance and thermal stability requirements in shelf-stable food matrices drive fastest-growing material substitution.
- Germany's industrial corridor demand:Concentrated pharmaceutical and electronics manufacturing around Düsseldorf and Cologne creates dense, high-specification customer clustering.
Industry Challenges
- Extractables and leachables validation:FDA cGMP guidelines for primary pharmaceutical packaging impose lengthy analytical testing timelines that delay new laminate qualification.
- Adhesive chemistry reformulation:REACH-restricted substances force rapid bonding platform transitions, requiring concurrent performance validation and supply chain requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Foil Market |
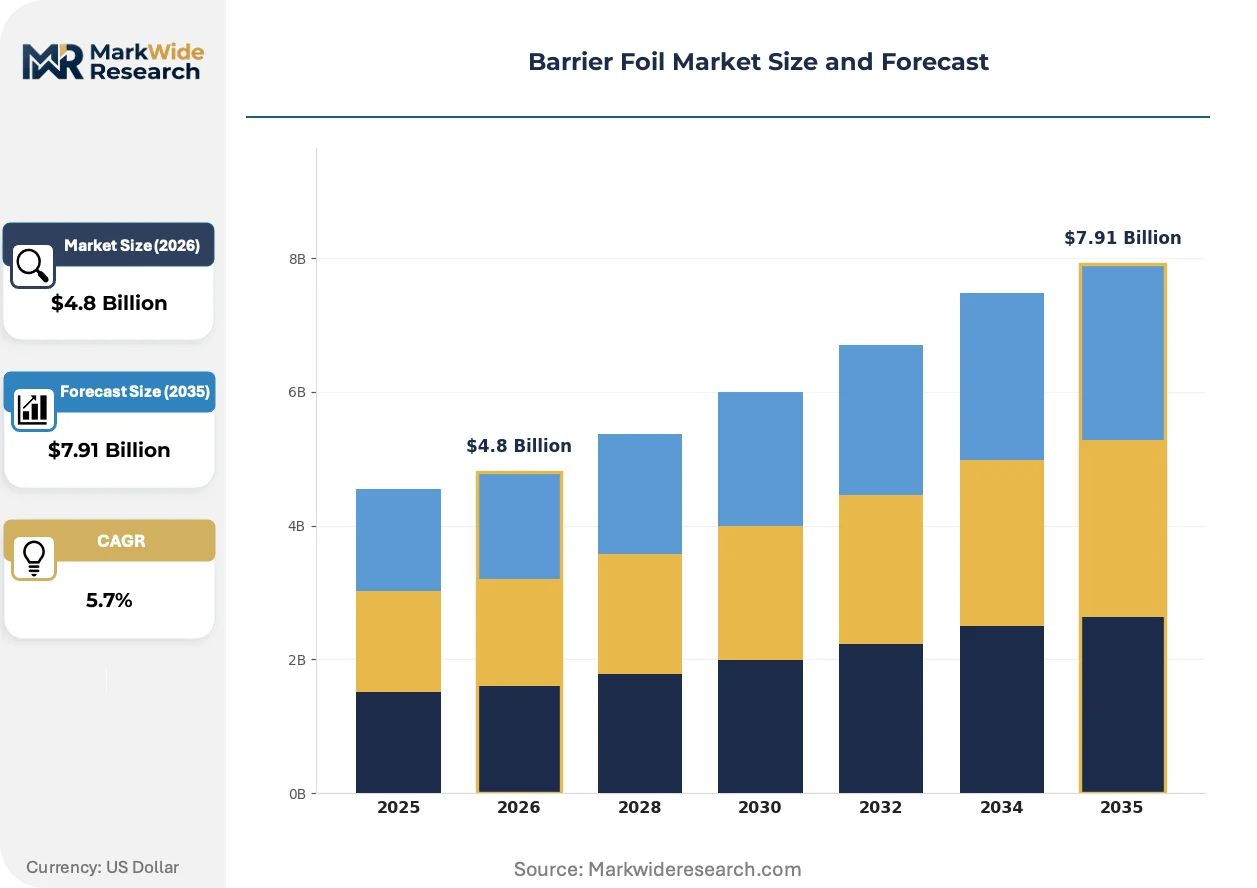
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum Foil, Polyester Film, Polyethylene Film, Nylon Film End Use Industry: Food Packaging, Pharmaceutical Packaging, Electronics, Industrial Applications Thickness: Below 20 Microns, 20-50 Microns, 51-100 Microns, Above 100 Microns Form: Roll, Sheet, Pouch, Bag |
| Companies Covered | Mondi Group, Hindalco Industries Ltd, Amcor Plc, Reynolds Consumer Products, Alcoa Corporation, Novelis Inc., Constantia Flexibles, Uflex Ltd, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Foil Market Strategic Shifts
Active barrier technologies and sustainable substrate alternatives are compressing the performance gap between conventional aluminum laminates and next-generation mono-material solutions, reshaping converter R&D priorities and customer specification processes.
Vacuum metallization is migrating from decorative and cost-driven applications into functional barrier layers for mid-performance pharmaceutical and electronics packaging. Generic drug manufacturers and secondary electronics suppliers are adopting metallized polyester at accelerated pace to meet sustainability targets without sacrificing shelf-life protection. This migration is compressing demand for full-gauge aluminum foil in non-critical barrier applications while expanding addressable volume for metallized film converters.
EMA's Medical Device Regulation extends conformity requirements to sterile barrier systems, imposing validation documentation burdens that favor established pharmaceutical-grade laminators with existing quality management systems. Sterile device packaging now requires demonstrable seal integrity and microbial barrier performance under accelerated aging protocols. European medical device contract manufacturers are consolidating supplier panels to reduce audit burden, concentrating volume with certified converters.
Buyer specification processes are compressing as pharmaceutical procurement teams consolidate laminate qualification around pre-validated platform constructions. Large molecule drug sponsors now favor barrier suppliers with existing drug master files and extractables libraries, displacing opportunistic sourcing from non-specialized converters. This concentration is most visible in Germany's Rhine-Ruhr pharmaceutical cluster, where serialization mandates and quality agreements have institutionalized preferred supplier relationships.
Barrier Foil Market Segmentation
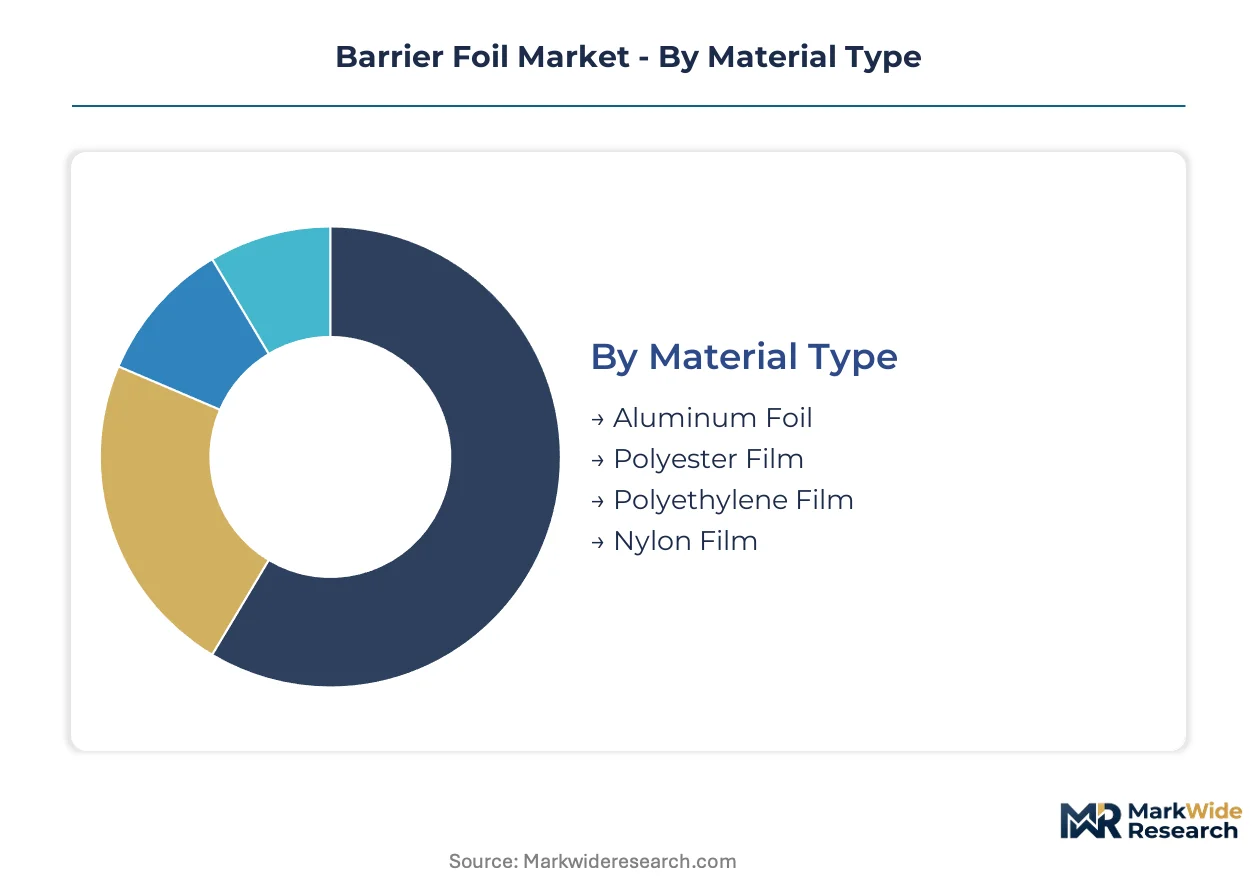
Barrier foil segmentation reveals how material specifications, end-use requirements, and processing formats create distinct commercial battlegrounds. Converter specialization concentrates around pharmaceutical-grade laminates and food-grade retort applications, while thickness and form factor choices reflect automation compatibility and logistics constraints.
Material Type:
Cost tier determines material selection trade-offs between barrier performance, substrate price, and sustainability compliance.
- Aluminum Foil:Near-zero gas permeability makes this the default for oxygen-sensitive pharmaceuticals and moisture-critical electronics. Demand concentrates in Germany's Rhine-Ruhr pharmaceutical cluster where serialization mandates validate established supply relationships.
- Nylon Film:Puncture resistance and thermal stability position this substrate for retort pouch applications in shelf-stable food matrices. Thailand's expanding converting capacity is narrowing regional supply gaps for Asia-Pacific food packaging customers.
- Polyester Film:Vacuum metallization migration is expanding functional barrier adoption for mid-performance electronics and generic drug packaging where sustainability targets compress aluminum demand.
- Polyethylene Film:Cost-driven moisture barriers serve industrial and secondary packaging where permeability requirements relax and mechanical recycling compatibility gains priority under EU extended producer responsibility frameworks.
Aluminum foil commands the established base. The steepest expansion runs through nylon film retort applications.
End Use Industry:
Application-specific validation requirements and specification processes create divergent margin structures across customer segments.
- Pharmaceutical Packaging:FDA cGMP guidelines and EMA Medical Device Regulation impose extractables testing and sterile barrier validation that erect technical moats for certified converters. Germany's Düsseldorf-Cologne corridor concentrates demand for cold-chain biologics logistics.
- Food Packaging:Retort pouch thermal stability and puncture resistance specifications drive nylon film substitution. Vietnam's metallized film capacity expansion is shortening lead times for Asia-Pacific shelf-stable food manufacturers.
- Electronics:Moisture-critical semiconductor and component packaging requires ultra-high barrier performance with electrostatic discharge protection.
- Industrial Applications:Cost-optimized moisture barriers serve chemical, automotive, and construction markets where specification processes allow commodity sourcing.
Pharmaceutical packaging commands premium positioning. Food packaging is gaining share fastest as retort applications expand.
Thickness:
Volume and performance requirements stratify converter equipment utilization and raw material yield economics.
- 20-50 Microns:Balanced barrier performance and convertibility dominate pharmaceutical primary packaging and mid-performance electronics where handling durability meets specification compliance.
- Below 20 Microns:Ultra-thin gauges serve cost-sensitive secondary packaging and decorative applications where vacuum metallization displaces full-gauge aluminum.
- 51-100 Microns:Heavy-duty industrial and logistics packaging requiring puncture resistance and thermal insulation for cold-chain biologics distribution.
- Above 100 Microns:Specialized rigid barrier constructions for reusable industrial containers and extreme environment protection.
The 20-50 micron band commands the established base. Below 20 micron gauges are climbing the fastest as metallization technology matures.
Form:
Customer type and automation compatibility determine format preferences across pharmaceutical, food, and industrial procurement channels.
- Roll:Continuous web formats integrate with high-speed form-fill-seal automation in pharmaceutical and food manufacturing lines where throughput economics dominate.
- Pouch:Pre-formed barrier pouches serve contract packaging operations and small-batch pharmaceutical runs where changeover flexibility outweighs unit cost.
- Sheet:Cut-to-size formats support manual handling operations and prototype validation in medical device and electronics contract manufacturing.
- Bag:Three-side-seal and stand-up configurations address retail-facing food and consumer electronics packaging where shelf presence matters.
Roll format commands the established base. Pouch configurations are expanding most quickly as contract manufacturing consolidates around flexible batch sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive aluminum smelting in South Asia and integrated pulp-to-packaging networks in Europe anchor supply-side control. Converter specialization clusters around pharmaceutical corridors and electronics manufacturing zones. Regulatory divergence between FDA cGMP and EMA Medical Device Regulation frameworks fragments qualification requirements across major demand centers.
Germany
Cold-chain biologics logistics and serialization mandates pull high-specification foil laminates into the Düsseldorf-Cologne pharmaceutical corridor. EU Green Deal recyclability targets under ECHA oversight force adhesive chemistry transitions toward solvent-free bonding platforms. The Rhine-Ruhr cluster concentrates preferred supplier relationships among certified converters serving large molecule drug sponsors.
United States
FDA extractables and leachables testing requirements for primary pharmaceutical packaging elevate technical barriers for laminate qualification. Temperature-sensitive cell and gene therapy distribution networks expand demand for ultra-high barrier thermal insulation solutions. The Boston-Cambridge biotech corridor and New Jersey pharmaceutical belt drive concentrated procurement from validated suppliers.
China
Dual carbon goals and NMPA pharmaceutical packaging standards redirect investment toward metallized film alternatives to full-gauge aluminum. Electronics manufacturing in the Yangtze River Delta and Pearl River Delta sustains moisture-critical semiconductor packaging demand. Vacuum metallization capacity expansion accelerates substitution in mid-performance barrier applications.
India
Hindalco's captive aluminum smelting and rolling assets anchor regional substrate availability for downstream laminators. CDSCO pharmaceutical packaging regulations and PLI scheme incentives for domestic manufacturing reshape procurement localization. Gujarat and Maharashtra industrial corridors concentrate converting capacity serving both export and domestic pharmaceutical markets.
Vietnam
Metallized film converting capacity expansion narrows Asia-Pacific supply gaps for electronics and food packaging customers. SAMR-aligned quality standards for export-oriented manufacturing elevate equipment investment requirements. The northern industrial zones around Hanoi and Hai Phong attract laminate conversion facilities targeting regional electronics supply chains.
Barrier Foil Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in substrate and adhesive supply. The vendor base stratifies between integrated packaging conglomerates with captive pulp-to-foil networks and independent converters competing on qualification speed and batch flexibility. Three archetypes dominate: vertically integrated material-science platforms, pharmaceutical-grade cleanroom-certified laminators, and regional metallized film specialists. Competitive moves concentrate on backward integration into aluminum smelting and rolling assets, plus adhesive chemistry reformulation to meet REACH and EU Green Deal compliance windows.
Among integrated packaging platforms, Mondi Group exemplifies the pulp-to-packaging archetype with European substrate cost control; Hindalco Industries Ltd anchors the captive aluminum supply model in South Asia; and Amcor Plc occupies the pharmaceutical-grade certification tier with barrier validation protocols. These three represent distinct strategic positions rather than direct overlap, with each sitting at a different node of the value chain from raw metal through validated drug packaging.
| Leading Market Players |
|---|
| Mondi Group |
| Hindalco Industries Ltd |
| Amcor Plc |
| Reynolds Consumer Products |
| Alcoa Corporation |
| Novelis Inc. |
| Constantia Flexibles |
| Uflex Ltd |
| Berry Global Inc. |
| Others |
Value Chain & Pricing Dynamics
Düsseldorf's pharmaceutical corridor concentrates high-specification foil laminate demand, translating serialization mandates and cold-chain biologics requirements into pricing power for certified converters serving large molecule drug sponsors. REACH compliance windows and aluminum ingot volatility feed cost compression back into supplier selection, favoring integrated players with captive substrate control.
Pricing Analysis
EU Green Deal recyclability mandates dictate the pricing tier structure across the barrier foil landscape, separating pharmaceutical-grade cleanroom-certified laminates from commodity industrial moisture barriers. Price differentiation hinges on FDA cGMP validation status and extractables library depth, with premium tiers commanding substantial spreads over standard food-grade retort constructions. Cost compression in mid-performance electronics packaging intensifies as vacuum metallization displaces full-gauge aluminum, while generic drug manufacturers exhibit highest price sensitivity against biologics sponsors.
Supply Chain Analysis
Extended payment terms from German pharmaceutical OEMs strain independent converter liquidity, accelerating consolidation toward integrated packaging platforms with balance-sheet depth. Raw material flows draw from Hindalco's captive Indian smelting, Novelis European rolling assets, and Southeast Asian metallized film expansion in Vietnam and Thailand. Single-source vulnerability concentrates around South Asian aluminum substrate, with tariff exposure on Chinese polyester film compounding formulation cost uncertainty. Distribution runs through regional converting hubs serving dense pharmaceutical and electronics manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier foil markets reward regulatory entrenchment over scale economies, as FDA cGMP and EMA Medical Device Regulation validation erect switching costs that institutionalize preferred supplier relationships across pharmaceutical procurement panels.
For Market Incumbents: Pre-empt adhesive chemistry transitions by accelerating solvent-free bonding platform validation before REACH compliance deadlines harden specification lock-in. Consolidate position through backward integration into aluminum rolling assets or exclusive tolling arrangements with Hindalco and Novelis, neutralizing commodity volatility exposure that threatens margin stability in mid-tier electronics laminates. For New Entrants and Emerging Players: Vietnam's metallized film capacity gap offers white-space entry for electronics packaging converters targeting Yangtze River Delta semiconductor manufacturers with SAMR-aligned quality systems. Nylon film retort pouch specialization in Thailand bypasses pharmaceutical validation moats while capturing fastest-growing food packaging substitution demand through puncture-resistant thermal stability specifications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical-grade cleanroom-certified laminators with existing drug master files and extractables libraries over commodity metallized film players facing sustainability-driven aluminum displacement. Long-term viability rests on regulatory validation depth rather than substrate scale. Monitor EMA sterile barrier system audit consolidation as inflection signal for supplier panel concentration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Chemistry Reformulation | REACH solvent-free bonding platforms secure European pharmaceutical qualification windows before EU Green Deal enforcement tightens. |
| Captive Aluminum Rolling Integration | Hindalco-style smelter control insulates margin stability against LME ingot volatility transmitted through converter economics. |
| Pharmaceutical Cleanroom Certification | FDA cGMP validation protocols erect technical moats that institutionalize preferred supplier relationships with biologics sponsors. |
| Metallized Film Capacity Expansion | Vietnam and Thailand converting investments narrow Asia-Pacific supply gaps for mid-performance electronics sustainability transitions. |
| Sterile Barrier Validation Investment | EMA Medical Device Regulation compliance concentrates contract manufacturer procurement panels around audited quality systems. |
Study Parameters
The analysis maps aluminum foil, nylon film, polyester metallization, and polyethylene substrate tiers, each validated through laminator plant managers, pharmaceutical packaging engineers, and food-grade retort pouch procurement leads. Primary fieldwork with CDSCO regulatory consultants and EMA quality system auditors combined with FDA 483 observation databases, REACH substance restriction filings, and EU ETS carbon cost disclosures. Secondary triangulation across SEC 10-K packaging segment disclosures, aluminum trade flow customs data, and pharmaceutical contract manufacturing GMP certificates enabled bottom-up volume reconciliation against top-down end-use demand aggregation.
Assumption sets held aluminum ingot price volatility within historical bands and pharmaceutical serialization mandate timelines as enacted, while varying EU Green Deal recyclability enforcement intensity and cold-chain biologics distribution network expansion rates. Segmentation modeling spanned material type, end-use industry, thickness gauge, and geographic regulatory cluster dimensions across the projection horizon. CAGRs derived from laminate volume intensity per pharmaceutical unit dose, semiconductor wafer shipment, and retort pouch food unit, cross-referenced against Hindalco and Novelis capacity expansion disclosures.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by independent converters or rapid metallization technology maturation would shift outcomes. Macroeconomic deviation in aluminum commodity cycles, regulatory acceleration of extended producer responsibility frameworks, or breakthrough mono-material barrier performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
North America Barrier Films Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market