
 Anti-Static Packaging Film Market | 2026-2036
Anti-Static Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Packaging Film Market Outlook
Semiconductor wafer shipping is repositioning demand toward ultra-clean, low-outgassing anti-static films that eliminate ionic contamination risks. Mitsubishi Polyester Film Group leverages captive resin compounding capabilities to supply fabs with batch-traceable film rolls. Toray Plastics Inc. anchors North American demand through ISO Class 3 cleanroom-certified extrusion lines. Kolon Industries Inc. competes on rapid thickness customization for OLED panel shippers needing substrate-specific ESD protection.
Anti-static packaging film denotes polymer sheet engineered with surface resistivity between 10^6 and 10^12 ohms per square, achieved through carbon nanotube, quaternary ammonium, or inherently conductive polymer loading, manufactured via blown or cast extrusion with controlled cooling to preserve dissipative layer integrity. Polyethylene formulations dominate volume due to cost-efficient extrusion and broad chemical compatibility with electronics cleaners. Barrier Films command premium positioning as hermetic ESD protection for moisture-sensitive medical device sterilization pouches. Thin Films are accelerating fastest in microelectronics where die-shrinkage demands minimal wrapping mass without compromising triboelectric charge dissipation.
FDA regulates anti-static films contacting sterile medical devices through biocompatibility and particulate shedding thresholds, while EPA oversees volatile organic compound emissions from solvent-based coating processes used in some conductive layer deposition. ECHA's REACH restrictions on perfluorinated additives and EU RoHS substance limits are forcing compounders to validate alternative ionic-free dissipative chemistries. Stakeholders must monitor evolving ESD Association standards and regional chemical registration requirements to preempt formulation obsolescence.
Market Dynamics
Semiconductor wafer shipments now demand migratory-free conductive formulations as ECHA REACH restrictions eliminate legacy quaternary ammonium additives from European supply chains, forcing compounders to revalidate entire additive portfolios.
Growth Catalysts
- ESD-safe material mandates:Semiconductor fabrication facilities in South Korea's Pyeongtaek complex now specify batch-traceable film rolls for all wafer shipments, creating procurement pull for certified converters.
- Medical sterilization pouch demand:Barrier-grade anti-static films meeting FDA biocompatibility thresholds are displacing conventional packaging in Class II device sterilization workflows.
- OLED substrate protection:Panel shippers require thickness-customized ESD films that match specific substrate dimensions without triboelectric charge accumulation.
Market Restraints
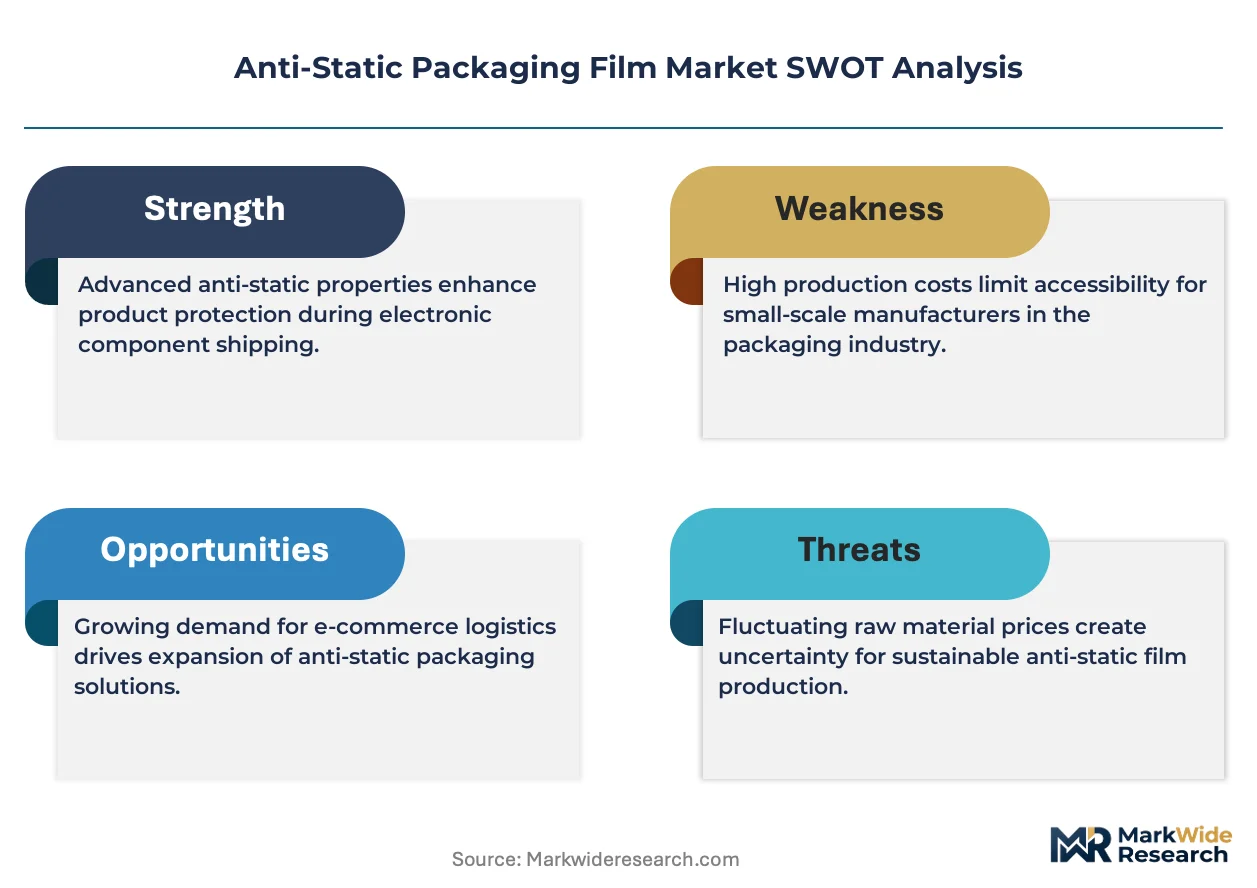
- Carbon nanotube feedstock concentration:High-purity CNT supply concentrates among limited specialty chemical producers, creating input cost volatility for conductive polymer compounders.
- Cleanroom extrusion capex barriers:ISO Class 3-certified blown film lines require capital outlays that exclude mid-scale converters from semiconductor-grade supply chains.
- Perfluorinated additive phase-outs:EU F-Gas Regulation and REACH restrictions on fluorinated chemistries eliminate proven dissipative additives before ionic-free alternatives achieve equivalent performance.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor assembly and testing facilities create first-mover advantage for ESD film converters establishing local compounding operations.
- Biodegradable conductive polymers:Convergence of polylactic acid substrates with inherently dissipative polymer architectures opens medical device segments seeking end-of-life compliance.
- Direct mill procurement channels:Wafer fabs are bypassing distributors to negotiate specification-locked supply agreements with film extruders possessing captive resin capabilities.
Industry Challenges
- Cleanroom technician scarcity:ISO Class 3 extrusion line operation requires specialized contamination control expertise that outpaces vocational training program output.
- Dual certification timelines:Simultaneous FDA biocompatibility validation and ESD Association standard compliance extends product launch cycles for medical-grade film variants.
- Legacy coating line stranding:Solvent-based conductive layer deposition assets face EPA VOC emission compliance costs that erode margins on non-specialty film grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Packaging Film Market |
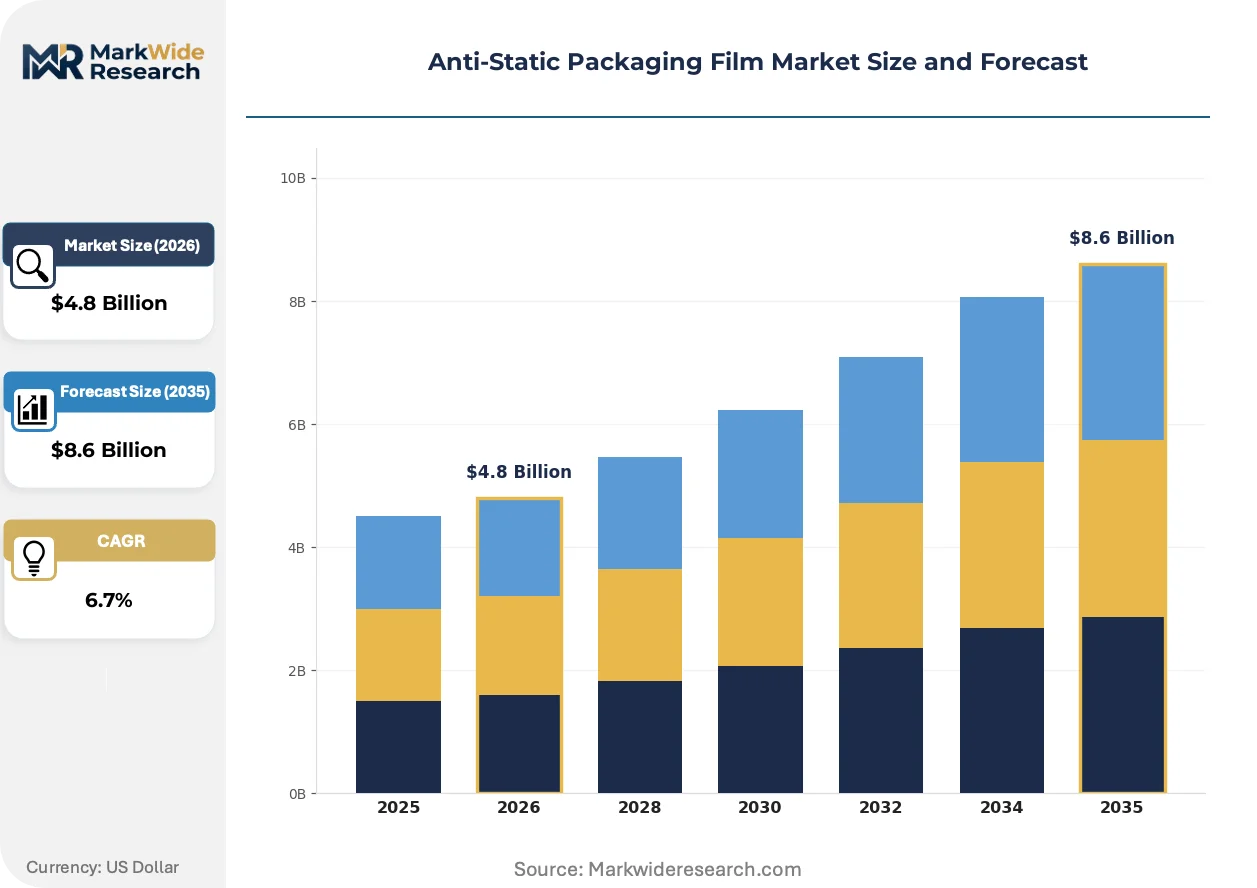
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Barrier Films End User: Electronics, Medical Devices, Automotive, Aerospace Application: Surface Protection, ESD Safe Packaging, Specialized Packaging, Shipping Thickness: Thin Films, Medium Films, Thick Films, Ultra-Thin Films |
| Companies Covered | Mitsubishi Polyester Film Group, Wiman Corporation, Achilles Corporation, Unitika Ltd., Klockner Pentaplast Group, Toyobo Co. Ltd., Toray Plastics Inc., Blueridge Films Inc., Kolon Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Packaging Film Market Strategic Shifts
Real-time resistivity monitoring during extrusion is compressing quality assurance cycles and enabling lot-specific certification that semiconductor fabs now mandate for wafer shipment protection.
Multi-layer coextrusion with embedded carbon nanotube networks is automating surface resistivity control across film width, eliminating manual sampling protocols that previously delayed roll release. Memory chip packagers in Taiwan's Hsinchu Science Park have adopted these systems at scale, reducing outgoing inspection labor while tightening specification bands for 300mm wafer shipments.
ECHA REACH Annex XVII restrictions on perfluorinated substances are forcing compounders to abandon legacy ionic additives ahead of sunset dates, redirecting R&D spend toward inherently conductive polymer architectures. Medical device sterilization pouch manufacturers face the steepest compliance curve, as FDA biocompatibility requirements overlap with substance restrictions to disqualify reformulated alternatives.
Specification-locked direct contracts between wafer fabs and film extruders are displacing distributor-mediated procurement in East Asian electronics clusters. Samsung's Pyeongtaek operations now source exclusively through mill-direct agreements that embed thickness tolerance and outgassing specifications into binding supply terms, compressing converter margins while securing supply continuity.
Anti-Static Packaging Film Market Segmentation
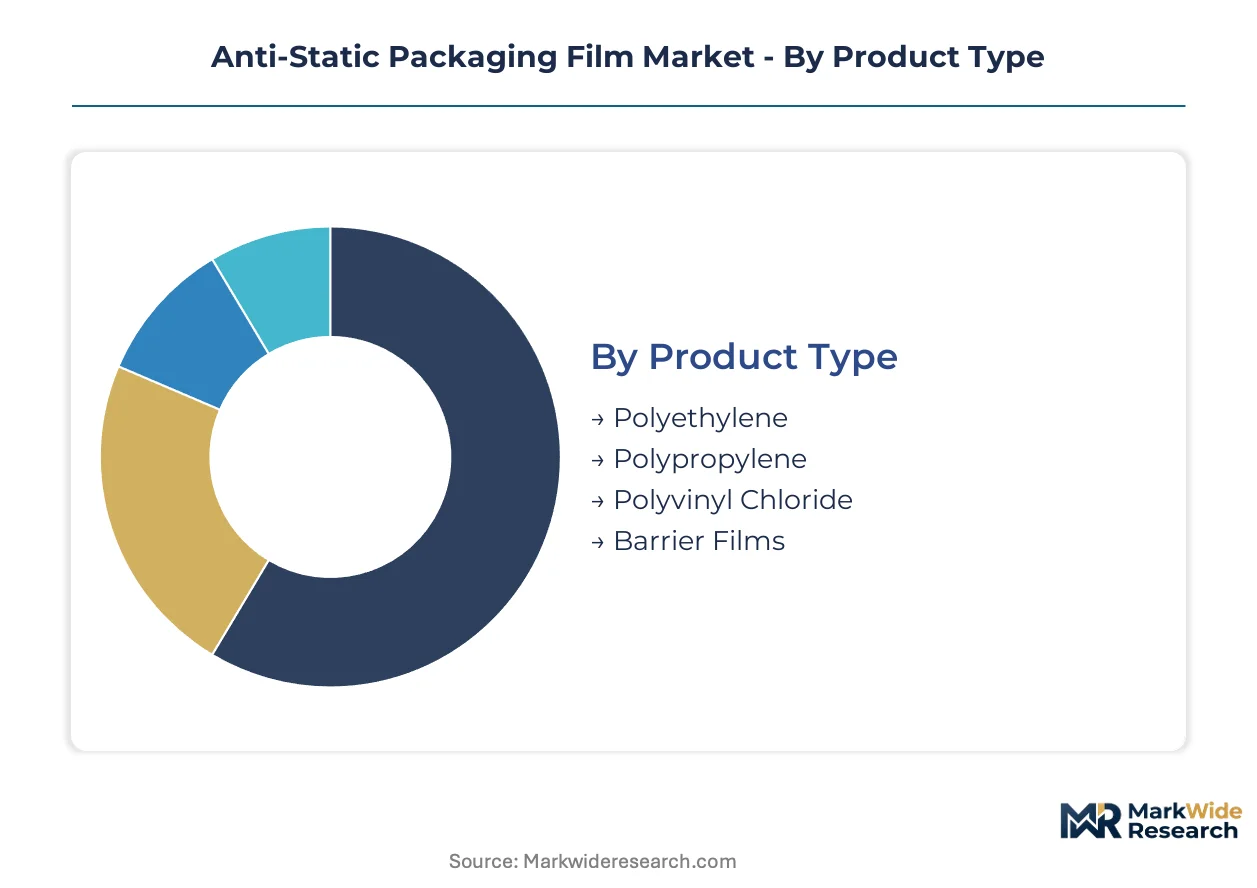
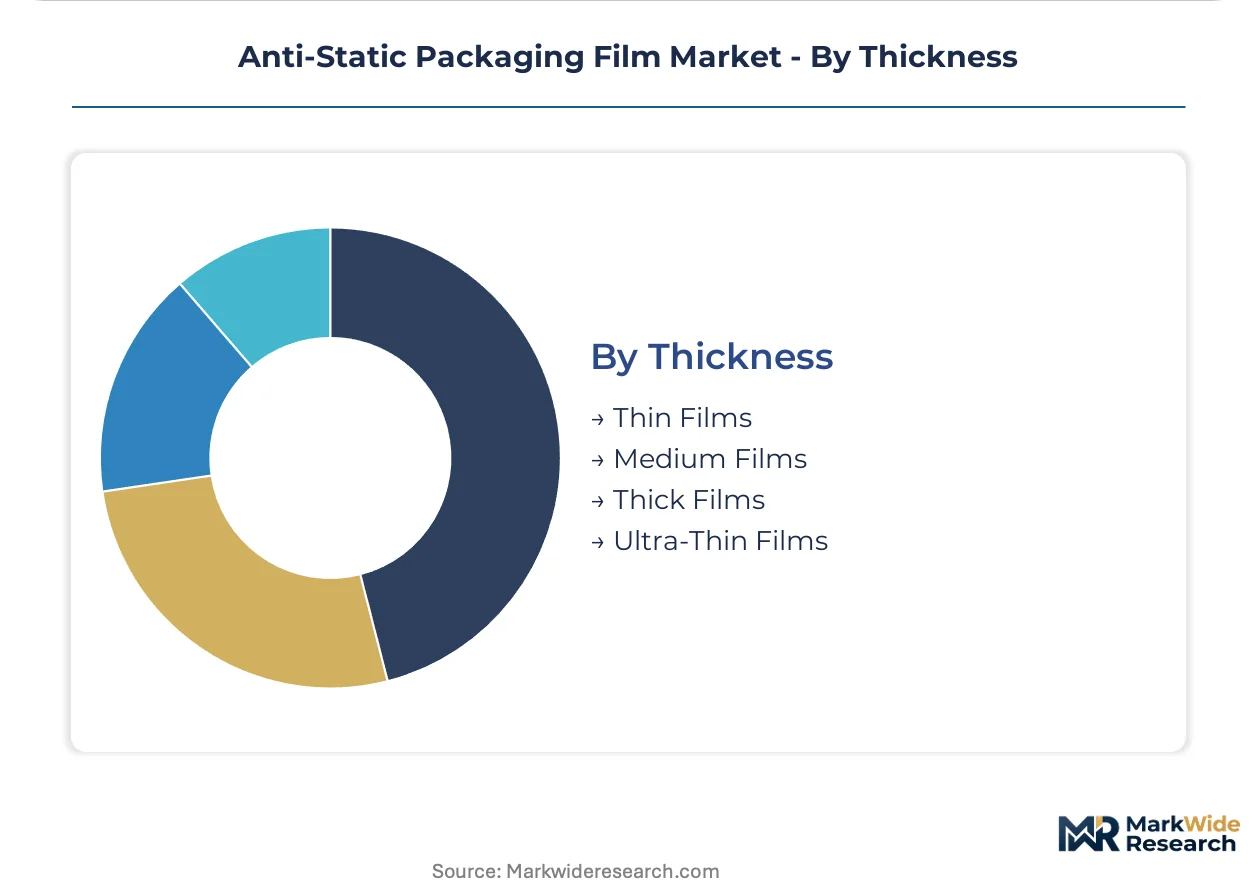
Anti-static packaging film specifications diverge sharply across end-use environments, from semiconductor cleanrooms requiring ultra-low outgassing to medical sterilization workflows demanding biocompatibility validation. Material selection and thickness calibration directly determine compliance eligibility and procurement access in regulated supply chains.
Product Type:
Polymer chemistry governs extrusion economics, surface resistivity stability, and regulatory clearance pathways across electronics and medical verticals.
- Polyethylene:Cost-efficient blown film extrusion enables broad chemical compatibility with electronics-grade cleaners and solvents. Dominates volume in East Asian electronics manufacturing clusters where Samsung's Pyeongtaek operations specify batch-traceable PE rolls for wafer shipments.
- Polypropylene:Higher thermal stability supports autoclave sterilization cycles in medical device packaging, though ECHA REACH restrictions on perfluorinated additives complicate migratory-free formulation development for European supply chains.
- Polyvinyl Chloride:Legacy calendering infrastructure persists in automotive component wrapping where pliability and puncture resistance outweigh regulatory complexity.
- Barrier Films:Hermetic ESD protection commands premium positioning in moisture-sensitive medical device sterilization pouches requiring FDA biocompatibility thresholds.
Polyethylene leads on scale; Barrier Films lead on momentum.
End User:
Customer procurement specifications range from ISO Class 3 cleanroom certification to automotive IATF quality system mandates.
- Electronics:Semiconductor fabs in Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek complex now mandate real-time resistivity monitoring data with every film roll, compressing quality assurance cycles and disqualifying non-certified converters.
- Medical Devices:FDA biocompatibility and particulate shedding thresholds overlap with ECHA REACH substance restrictions, extending dual certification timelines for sterilization pouch manufacturers.
- Automotive:EV battery module shippers require thickness-customized ESD films that accommodate irregular cell geometries without triboelectric charge accumulation during highway transit vibration.
- Aerospace:Mil-spec outgassing limits and flame-retardant ratings constrain material selection to narrow qualified product lists maintained by prime contractors.
Electronics commands procurement volume; Medical Devices faces the steepest compliance curve.
Application:
Functional deployment determines whether films serve temporary surface coverage or permanent ESD-safe enclosure roles.
- Surface Protection:Temporary die-cut sheets shield OLED panels and display glass during assembly line transit, with Kolon Industries competing on rapid thickness customization for substrate-specific protection.
- ESD Safe Packaging:Permanent dissipative enclosures for memory chips and processors require surface resistivity between 10^6 and 10^12 ohms per square maintained across temperature and humidity excursions.
- Specialized Packaging:Hermetic pouches for implantable devices combine moisture barriers with ionic-free conductive layers to prevent both ESD damage and corrosion.
- Shipping:Bulk roll formats for distributor channels emphasize puncture resistance and printability over precision resistivity control.
ESD Safe Packaging anchors specification intensity; Surface Protection expands most quickly with display manufacturing growth.
Thickness:
Gauge selection balances mechanical protection against mass minimization for weight-sensitive shipments.
- Thin Films:Microelectronics packaging where die-shrinkage demands minimal wrapping mass without compromising triboelectric charge dissipation. Toray Plastics anchors North American supply through ISO Class 3 cleanroom-certified extrusion lines.
- Medium Films:General-purpose electronics and automotive applications where puncture resistance must coexist with roll handling efficiency.
- Thick Films:Heavy-gauge formats for aerospace component crating and industrial equipment export packaging.
- Ultra-Thin Films:Emerging formats for flexible electronics and foldable display substrates where substrate curvature demands extreme pliability.
Thin Films dominate semiconductor procurement; Ultra-Thin Films gain share fastest with next-generation display architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are relocating compounding operations toward jurisdictions with lighter chemical registration burdens, exploiting gaps between EU REACH enforcement and Asian regulatory lag to preserve legacy additive formulations.
United States
Medical device sterilization pouch demand from Minnesota and Massachusetts medtech clusters drives FDA biocompatibility-certified film procurement. EPA VOC emission rules for solvent-based coating processes push converters toward aqueous conductive layer deposition. Toray Plastics anchors North American supply through ISO Class 3 cleanroom-certified extrusion lines in Rhode Island.
Germany
Automotive EV battery module shippers in Baden-Württemberg require thickness-customized ESD films for irregular cell geometries. ECHA REACH Annex XVII restrictions on perfluorinated substances eliminate proven dissipative additives before ionic-free alternatives achieve equivalent performance. Klockner Pentaplast Group maintains compounding operations serving IATF-certified automotive supply chains.
South Korea
Samsung's Pyeongtaek semiconductor complex mandates batch-traceable film rolls for all 300mm wafer shipments, creating procurement pull for certified converters. MFDS medical device packaging regulations overlap with corporate ESG mandates to accelerate migratory-free formulation adoption. Kolon Industries competes on rapid thickness customization for OLED panel shippers in Gyeonggi Province.
China
Memory chip packagers in the Yangtze River Delta have adopted real-time resistivity monitoring systems at scale, reducing outgoing inspection labor. MIIT dual carbon goals pressure converters to validate energy-efficient extrusion processes. Domestic compounders are backward integrating into carbon nanotube feedstock to reduce import dependency from specialty chemical producers.
India
PLI scheme incentives for semiconductor assembly and testing facilities in Gujarat and Karnataka create first-mover advantage for ESD film converters establishing local operations. BIS certification requirements for electronics-grade packaging materials lag behind fab procurement specifications. Maharashtra-based distributors currently mediate most imports from East Asian extruders.
Anti-Static Packaging Film Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with semiconductor-grade supply chains consolidating around ISO-certified extruders while medical and automotive verticals retain fragmented procurement channels. Three archetypes dominate: resin compounders with captive film extrusion, standalone converters sourcing additive masterbatches, and regional distributors specification-locking mill-direct agreements. Competitive moves concentrate on backward integration into conductive polymer R&D and geographic expansion toward India electronics manufacturing clusters.
Within the Asia-Pacific specialist tier, Mitsubishi Polyester Film Group and Kolon Industries Inc. exemplify compounder-extruder integration models, while Toray Plastics Inc. represents North American cleanroom-certified production archetypes. These entities occupy positions defined by regulatory certification depth rather than scale alone, with batch-traceability and migratory-free formulation capabilities serving as the primary differentiation vectors in semiconductor-facing procurement.
| Leading Market Players |
|---|
| Mitsubishi Polyester Film Group |
| Wiman Corporation |
| Achilles Corporation |
| Unitika Ltd. |
| Klockner Pentaplast Group |
| Toyobo Co. Ltd. |
| Toray Plastics Inc. |
| Blueridge Films Inc. |
| Kolon Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
ECHA REACH Annex XVII restrictions on perfluorinated substances gate qualified supply for semiconductor-grade anti-static films, reserving premium-tier pricing access to converters with validated migratory-free formulations and ISO Class 3 cleanroom certification. Buyers without mill-direct agreements absorb distributor markups that compress margins while procurement specifications tighten across East Asian electronics clusters.
Pricing Analysis
Distributor margins of 15-25 percent separate mill-direct contract pricing from spot market transactions, with premium-mid-economy pricing differentiation anchored by certification grade and batch-traceability capabilities. Semiconductor fabs in South Korea's Pyeongtaek complex demonstrate the least price sensitivity, prioritizing specification-locked supply agreements over cost optimization. Price erosion runs through standard-grade polyethylene formulations as Chinese compounders expand captive carbon nanotube production and compress input costs. Medical sterilization pouch manufacturers face the steepest cost pressure from dual FDA-ECHA compliance investments.
Supply Chain Analysis
ISO Class 3 cleanroom certification gates supply chain participation, concentrating qualified extrusion capacity in South Korea, Taiwan, and the United States where Samsung and TSMC procurement specifications have elevated compliance thresholds. Raw material dependencies center on high-purity carbon nanotube feedstock from specialty chemical producers, conductive polymer masterbatches, and migratory-free additive packages. Single-source vulnerability concentrates in carbon nanotube supply, with limited qualified producers creating input cost volatility. Distribution runs through specification-locked direct contracts between wafer fabs and certified extruders, displacing traditional distributor channels in semiconductor-facing procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-static packaging film market functions as a stable compounder, with semiconductor wafer shipment volumes providing predictable demand baselines that insulate certified converters from cyclical volatility. ESD-safe material mandates across East Asian fabrication facilities reinforce procurement continuity for qualified suppliers.
For Market Incumbents: Cement specification-lock relationships with Pyeongtaek and Hsinchu Science Park fabs through embedded thickness tolerance and outgassing terms that resist price renegotiation. Extend backward integration into carbon nanotube feedstock to neutralize single-source supply risk and capture margin from compounder-extruder integration. Defend against emerging Chinese compounders by accelerating migratory-free formulation R&D ahead of ECHA REACH sunset dates. For New Entrants and Emerging Players: The gap between premium semiconductor-grade pricing and economy-tier automotive wrapping films creates entry space for mid-tier converters targeting India's PLI-subsidized electronics assembly clusters. Establish local compounding operations in Gujarat or Karnataka ahead of BIS certification alignment with fab procurement specifications. Lead with rapid thickness customization capabilities for OLED panel shippers in Gyeonggi Province, where Kolon Industries has proven the model. For Investors and Strategic Acquirers: Roll-up economics work for ISO-certified mid-cap extruders because semiconductor supply chain consolidation has fragmented ownership of cleanroom assets across family-owned Asian converters and North American specialists. Five-to-ten year viability hinges on migratory-free formulation portfolios that outlast regulatory transition periods. Target converters with captive resin capabilities and existing mill-direct contracts. Watch for ECHA REACH enforcement acceleration in medical sterilization segments as the inflection signal that compresses non-compliant asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CNT Feedstock | Captive carbon nanotube production neutralizes input cost volatility from specialty chemical concentration. |
| ISO Class 3 Cleanroom Certification | Certification gates participation in Samsung and TSMC specification-locked procurement channels. |
| Migratory-Free Formulation Development | ECHA REACH compliance preserves European market access as perfluorinated additives face sunset dates. |
| Direct Mill Procurement Channels | Bypassing distributors embeds thickness and outgassing specifications in binding supply terms. |
| India Local Compounding Operations | PLI scheme incentives for semiconductor assembly create first-mover advantage in emerging electronics clusters. |
Study Parameters
Coverage spans East Asia, North America, and Europe, with primary inputs from each region's electronics manufacturing clusters and regulatory jurisdictions. Primary interviews combined extrusion line operators, semiconductor fab procurement managers, medical device packaging engineers, and conductive polymer R&D directors with secondary validation from ECHA substance restriction databases, FDA 510(k) filings, SEC 10-K disclosures from listed compounders, and customs trade data on carbon nanotube imports. Bottom-up wafer shipment forecasts triangulated against top-down electronics packaging spend estimates.
Granularity-level modeling deployed resistivity grade tiers, end-use verticals spanning semiconductor and medical device sterilization, thickness categories from ultra-thin to heavy-gauge, and regional production hub clusters. CAGRs derived from segment-specific volume trajectories across the analysis window, with semiconductor fab capex cycles and OLED panel shipment forecasts serving as primary demand-side inputs. Supply-side constraints incorporated carbon nanotube production capacity and cleanroom extrusion line installation rates.
The model assumes gradual ionic-free additive adoption; alternative pathways for inherently conductive polymer architectures would accelerate formulation transition timelines and alter competitive positioning. Forecasts reflect assumptions on ECHA REACH enforcement intensity and semiconductor fab localization patterns. A model refresh is warranted upon material change in carbon nanotube supply concentration or ESD Association standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Bonding Films Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Pan Liners Market