
 Europe Pharmaceutical Packaging Materials Market | 2026-2036
Europe Pharmaceutical Packaging Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Packaging Materials Market Intelligence
The substitution of Polyvinyl Chloride (PVC) with advanced Polyethylene Terephthalate (PET) grades in blister packs is hardening the economic case for circular material flows. Amcor plc leverages its scale in flexible packaging to lead this material transition. Gerresheimer AG specializes in high-value glass and plastic containers for sensitive biologics. Meanwhile, Nolato AB differentiates through its expertise in polymer-based solutions for complex delivery systems.
Europe's pharmaceutical packaging materials are primary containers directly contacting the drug, engineered for product integrity. These materials must demonstrate specific barrier properties, such as low water vapor transmission rates, to ensure drug stability and efficacy. While glass vials dominate the high-value injectables application, blister packs composed of polymers and aluminum foil command the largest volume for oral tablets and capsules.
The European Medicines Agency (EMA) sets stringent guidelines for packaging material qualification, impacting market access. Concurrently, the EU's Corporate Sustainability Reporting Directive (CSRD) is forcing manufacturers to provide transparent data on the environmental footprint of their packaging. Navigating the intersection of drug stability requirements and evolving sustainability mandates now defines strategic material selection for all market participants.
Market Dynamics
The dual pressure from stringent EMA drug stability requirements and EU Green Deal sustainability mandates is the central force defining material innovation and selection across the European pharmaceutical packaging landscape.
Growth Catalysts
- Biologics Expansion:A growing pipeline of sensitive biologics demands advanced primary packaging like coated glass vials and high-barrier polymer syringes for drug stability.
- EU Falsified Medicines Directive:The FMD’s serialization mandate drives demand for packaging with unique identifiers and anti-tampering features to secure the prescription drug supply chain.
- Circular Economy Incentives:EU Green Deal policies promote recyclable mono-materials, accelerating R&D into PET-based blister packs to replace less sustainable options.
Market Restraints
- High-Barrier Material Costs:Specialty polymers and coatings needed for high-barrier performance carry a significant cost premium over standard materials, impacting formulation choices.
- Regulatory Validation Cycles:Changing primary packaging materials requires lengthy and costly stability testing and re-qualification with regulators like the EMA or Swissmedic.
- Concentrated Glass Supply:The supply of specialized borosilicate glass tubing for vials is concentrated among few European producers, posing a bottleneck risk.
Strategic Opportunities
- Personalized Medicine Packaging:Cell and gene therapies create demand for small-batch, cryogenic-capable packaging with integrated tracking for individual patient doses.
- Eastern European Hubs:Expanding pharmaceutical manufacturing in Poland and Hungary presents opportunities for localized packaging production to reduce lead times and logistics costs.
- Smart Packaging Services:Integrating sensors for adherence monitoring or cold chain verification offers a new value-added service beyond simple containment.
Industry Challenges
- Recycling Infrastructure Scalability:Developing collection and sorting infrastructure capable of handling complex, multi-material pharmaceutical packaging waste at a pan-European scale remains a significant hurdle.
- Aseptic Line Re-tooling:Transitioning to new sustainable materials often requires substantial capital investment to re-tool and re-validate sterile filling lines without compromising contamination control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Packaging Materials Market |
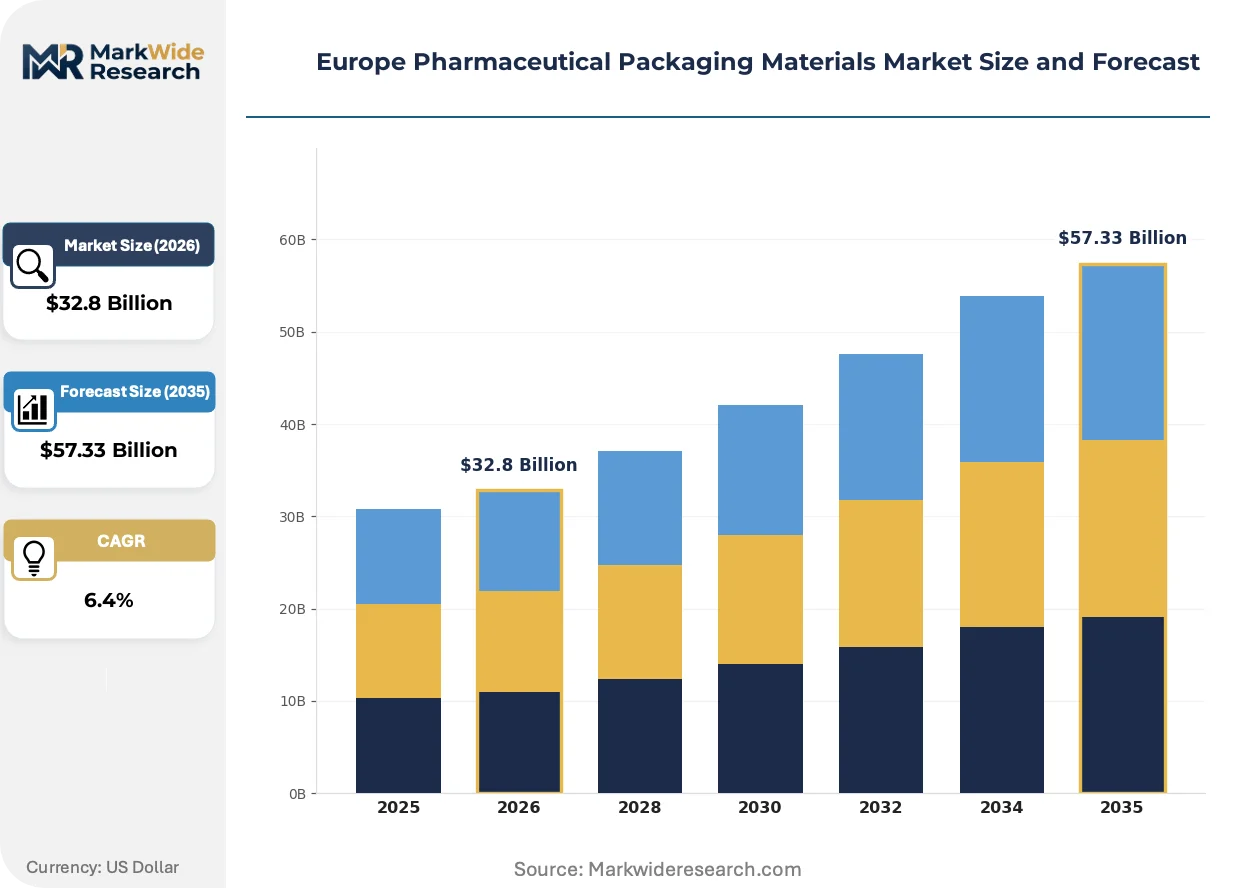
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Bottles, Vials, Sachets, Ampoules Material: Glass, Polyethylene Terephthalate, Polyvinyl Chloride, Aluminum Foil, Polypropylene Application: Tablets, Capsules, Injectables, Topicals, Oral Liquids End User: Pharmaceutical Manufacturers, Contract Packaging Providers, Research Laboratories, Retail Pharmacies |
| Companies Covered | AptarGroup, Inc., Stevanato Group S.p.A., Amcor plc, Nolato AB, Berry Global, Inc., Gerresheimer AG, West Pharmaceutical Services, Inc., SGD Pharma, Schott AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Packaging Materials Market Strategic Shifts & Innovations
Material science advancements are converging with digitalization to address the dual pressures of regulatory compliance and sustainability mandates. This intersection is creating new performance benchmarks and data requirements for packaging suppliers across Europe.
High-speed machine vision systems are a critical technology for quality assurance in pharmaceutical packaging lines. Pharmaceutical manufacturers are rapidly adopting these systems to detect microscopic defects in vials, syringes, and blister packs. This technology is automating the quality control function, reducing reliance on manual inspection and generating digital records for EMA compliance.
The EU's Corporate Sustainability Reporting Directive (CSRD) is a pivotal policy shift impacting the market. It compels manufacturers to provide transparent, audited data on the environmental footprint of their packaging materials. This most acutely affects suppliers to German and French pharmaceutical companies, who must now quantify lifecycle impacts to retain contracts.
A preference for single-source qualification for critical drug-package systems is gaining traction among large pharmaceutical firms. This move replaces multi-vendor bidding with long-term partnerships for complex delivery systems to mitigate regulatory and supply risks. The trend is most visible in the European biologics sector, where container closure integrity is paramount for drug efficacy.
Europe Pharmaceutical Packaging Materials Market Segmentation
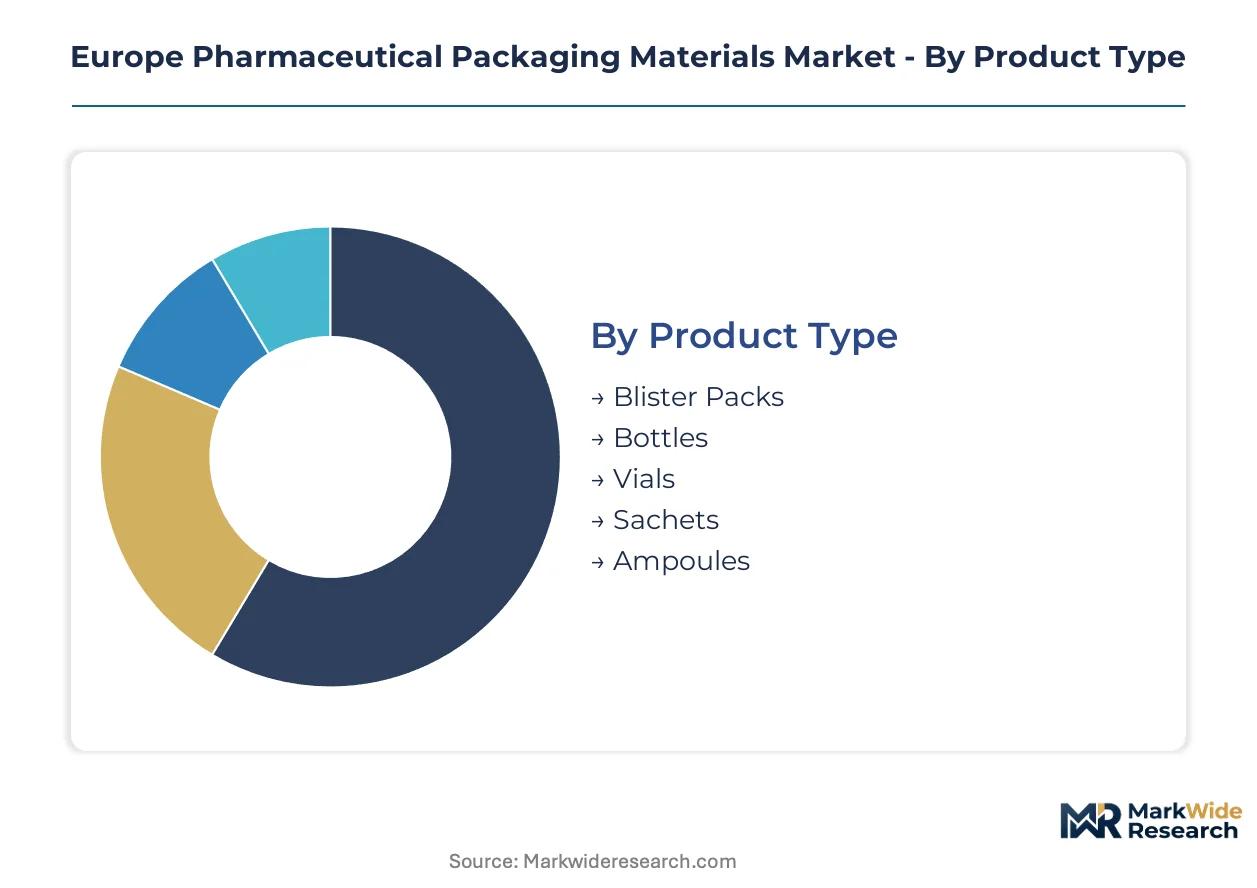
The Europe pharmaceutical packaging materials market is diverse, driven by varied drug delivery methods and stringent regulatory frameworks. Understanding these segments is crucial for manufacturers to align product development with specific drug stability requirements and evolving sustainability mandates. Material selection often dictates compliance pathways for new drug formulations.
Product Type:
The choice of packaging product type is often dictated by the drug's sensitivity and the necessary regulatory approvals, with specific formats like vials demanding rigorous container closure integrity validation from the EMA.
- Blister Packs:These thermoformed plastic and aluminum foil structures provide excellent barrier protection against moisture and oxygen for oral solid dosage forms. Demand for sustainable mono-material blister packs is rising across Germany and France due to CSRD reporting requirements.
- Vials:Small glass or plastic containers, primarily used for injectable drugs and biologics, require high precision manufacturing for sterility and integrity. The biologics pipeline expansion in Switzerland and Ireland drives demand for specialized coated glass vials.
- Bottles:Typically made from glass or polymers, bottles are versatile for oral liquids, tablets, and powders, offering protection and ease of dispensing. Polyethylene Terephthalate bottles are gaining preference over PVC due to circular economy incentives.
- Sachets:Flexible, single-dose pouches for powders, granules, or gels, offering convenience and precise dosing. These are commonly used for over-the-counter medications and dietary supplements.
- Ampoules:Sealed glass containers designed for sterile, single-dose injectable medications, ensuring product purity. Their use is common in emergency medicine and specific therapeutic areas.
Blister Packs sits at the top of the volume ranking, with Vials climbing the fastest.
Material:
Material selection significantly influences the cost structure of pharmaceutical packaging, with high-barrier options commanding a premium due to specialized manufacturing processes and performance characteristics.
- Glass:Known for its inertness and barrier properties, glass is preferred for sensitive injectables and biologics, particularly borosilicate variants. The concentration of specialized glass tubing supply in Europe creates potential bottlenecks.
- Polyethylene Terephthalate:A recyclable polymer gaining traction as a sustainable alternative to PVC in blister packs and bottles, offering good barrier properties. Its adoption is accelerating due to EU Green Deal policies promoting mono-materials.
- Polyvinyl Chloride:A cost-effective polymer widely used in blister packs due to its formability and barrier characteristics. Regulatory pressures from the EU Green Deal are driving its substitution with more sustainable materials.
- Aluminum Foil:Provides an excellent absolute barrier against moisture, oxygen, and light, often laminated with polymers for blister packs and sachets. It is a critical component for maintaining drug stability.
- Polypropylene:A versatile polymer used for caps, closures, and some containers due to its chemical resistance and heat stability. Its lightweight nature contributes to reduced logistics costs.
Glass materials hold the largest share of value, with Polyethylene Terephthalate expanding most quickly.
Application:
The application segment dictates the primary packaging format and material requirements, directly impacting drug stability and patient safety profiles.
- Injectables:Drugs administered via injection, requiring sterile, high-barrier primary packaging like vials, pre-filled syringes, and ampoules. The expansion of biologics pipelines in Europe drives demand for advanced injectable packaging.
- Tablets:Oral solid dosage forms, typically packaged in blister packs or bottles for protection against environmental factors. This segment represents the largest volume consumption of packaging materials.
- Capsules:Oral dosage forms enclosed in a gelatin or cellulose shell, sharing similar packaging requirements to tablets. They often require protection from moisture and light.
- Topicals:Medications applied to the skin, packaged in tubes, jars, or dispensers, requiring materials that do not interact with the formulation. Barrier properties are important for product integrity.
- Oral Liquids:Pharmaceutical solutions, suspensions, or syrups, predominantly packaged in bottles with appropriate closures. Child-resistant features are often a regulatory requirement.
Injectables command the highest value share, while Tablets represent the largest volume.
End User:
The end-user profile determines the scale of packaging procurement and the specific requirements for customization, quality control, and supply chain integration.
- Pharmaceutical Manufacturers:Large-scale producers of drugs, requiring high volumes of standardized and custom packaging materials. They often engage in long-term partnerships for critical drug-package systems to mitigate supply risks.
- Contract Packaging Providers:Companies specializing in packaging services for pharmaceutical firms, offering flexibility and expertise in various packaging formats. Their role is expanding with the outsourcing trend.
- Research Laboratories:Academic or corporate entities conducting drug discovery and development, needing specialized, small-batch packaging for clinical trials and stability studies. Cryogenic-capable packaging is essential for cell and gene therapies.
- Retail Pharmacies:Primarily involved in dispensing pre-packaged drugs, but also requiring packaging for compounding and patient-specific dose preparation. They prioritize ease of use and clear labeling.
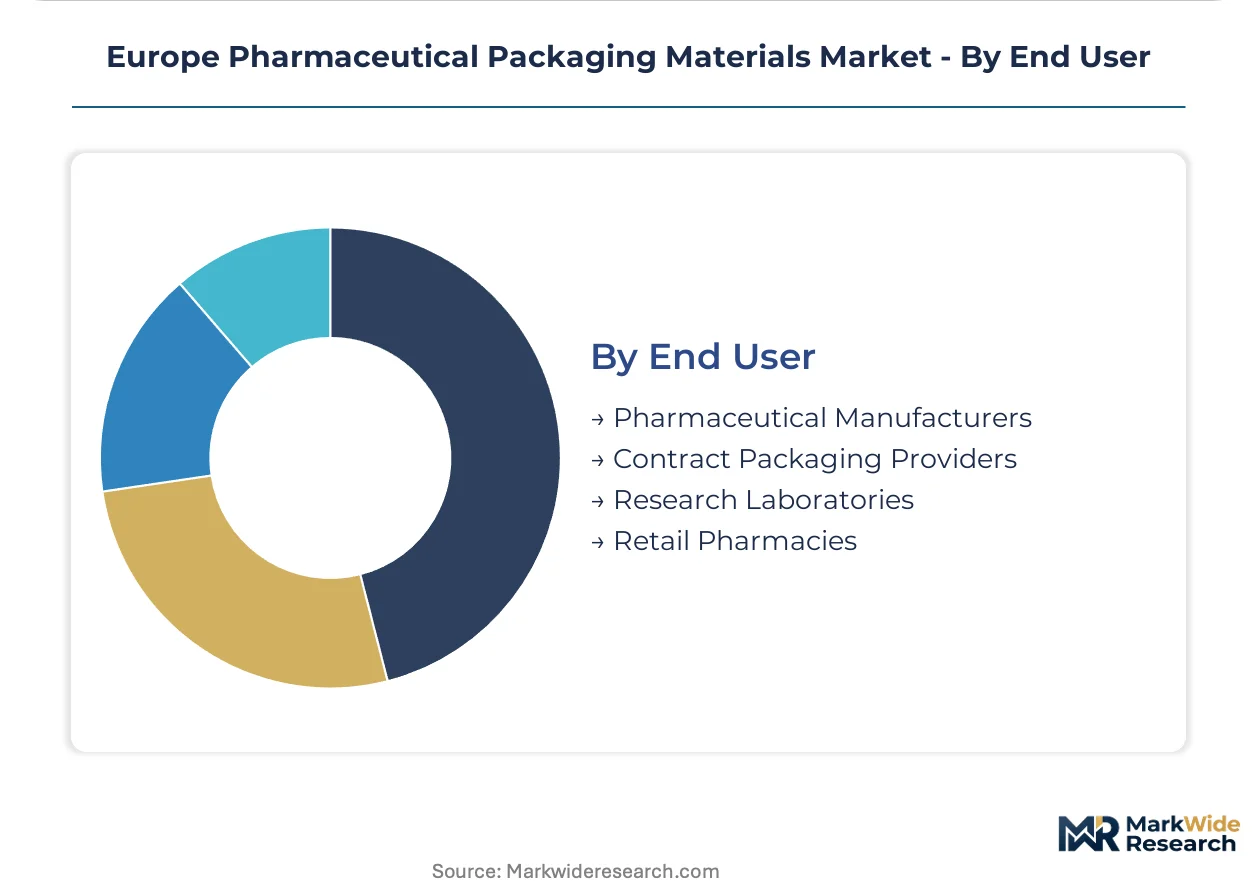
Pharmaceutical Manufacturers are the dominant buyers, with Contract Packaging Providers gaining share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical manufacturing sector drives significant demand for advanced packaging materials. This demand is influenced by stringent regulatory frameworks and the EU Green Deal's push for circularity. Packaging suppliers across Europe adapt to these evolving requirements.
Germany
German pharmaceutical manufacturers prioritize sustainable packaging solutions for their vast drug production. The EU's Corporate Sustainability Reporting Directive (CSRD) compels these companies to report transparent environmental data for packaging. The Rhine-Main region, a major pharmaceutical cluster, leads innovation in recyclable and low-carbon material development.
Switzerland
Switzerland's advanced biologics pipeline mandates specialized high-barrier containers for drug stability. Swissmedic validation processes ensure rigorous qualification for these sensitive primary packaging systems. Basel, a prominent biopharmaceutical hub, drives demand for high-value glass vials and pre-filled syringes.
France
French pharmaceutical companies face increasing pressure for transparent environmental data and sustainable packaging choices. The EU Green Deal incentivizes the substitution of traditional materials with mono-material alternatives in blister packs. The Paris-Saclay region, a scientific and business cluster, focuses on eco-design and material circularity for pharmaceutical packaging.
Poland
Poland's expanding pharmaceutical manufacturing hubs require localized packaging support to reduce lead times and logistics costs. Compliance with the EU Falsified Medicines Directive (FMD) drives demand for anti-tampering and serialization features. Warsaw and Kraków are emerging as key centers for packaging production and distribution within Central Europe.
Ireland
Ireland's robust biopharmaceutical sector demands highly specialized primary packaging for its growing biologics output. EMA's stringent qualification processes for injectables influence material selection and container closure integrity. Dublin and Cork, major pharmaceutical manufacturing centers, attract investment in advanced packaging solutions tailored for sensitive drugs.
Europe Pharmaceutical Packaging Materials Market Key Industry Players
Global majors compete with regional champions across material science innovation and supply chain resilience within the European pharmaceutical packaging market. The market structure is tiered, featuring large integrated players alongside specialized niche providers. Key strategic archetypes include scale producers, high-value specialists, and regional suppliers. Competitive moves include strategic partnerships for market access and capacity expansion to meet regional demand.
Within the high-volume flexible packaging segment, Amcor plc exemplifies a global major leveraging scale for material transition and circular economy principles. Gerresheimer AG, a German-based company, anchors the high-value glass and plastic container market, particularly for sensitive biologics and injectables. Nolato AB, a Swedish company, represents specialization in polymer-based solutions, focusing on complex drug delivery systems and medical devices. These companies collectively illustrate the diverse capabilities and strategic focus required to serve the demanding European pharmaceutical packaging landscape.
| Leading Market Players |
|---|
| AptarGroup, Inc. |
| Stevanato Group S.p.A. |
| Amcor plc |
| Nolato AB |
| Berry Global, Inc. |
| Gerresheimer AG |
| West Pharmaceutical Services, Inc. |
| SGD Pharma |
| Schott AG |
| Others |
Cost & Logistics Intelligence
Pharmaceutical Manufacturers' concentrated purchasing power for critical packaging components often dictates contract-based pricing models, ensuring long-term supply stability and quality adherence.
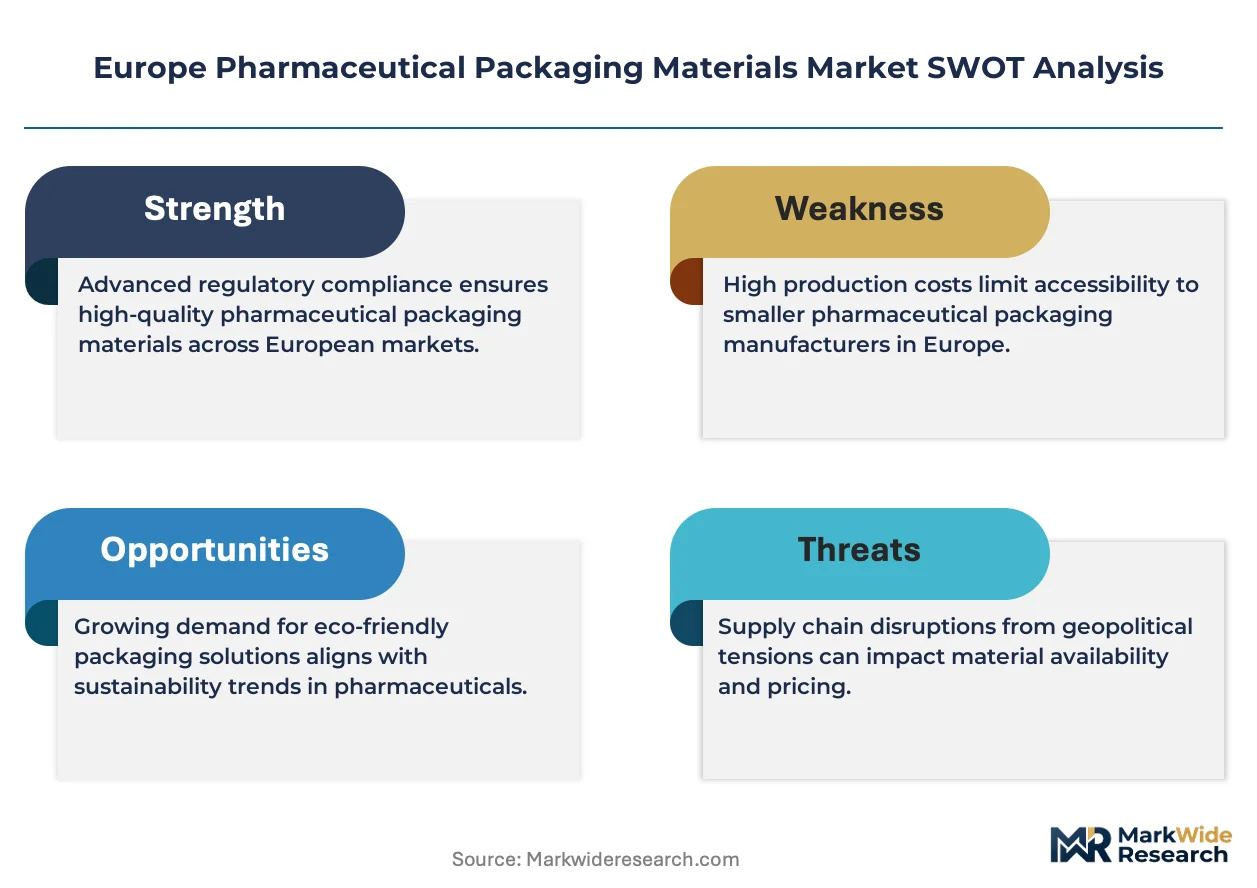
Pricing Analysis
Input cost pass-through for specialized materials, like borosilicate glass tubing and high-barrier polymers, influences final packaging prices. Contract-based long-term offtake agreements dominate for critical components, balancing supply security with cost predictability. Price differentiation stems from quality grade, EMA regulatory certification, and the level of customization required for complex drug delivery systems. Upward pricing pressure arises from the high cost of specialty materials and extensive regulatory validation cycles. Research Laboratories demonstrate less price sensitivity for small-batch, specialized packaging, while large Pharmaceutical Manufacturers prioritize cost-efficiency alongside compliance.
Supply Chain Analysis
Direct sales channels predominantly distribute primary pharmaceutical packaging materials to manufacturers and contract packaging providers, often through established long-term partnerships. Supply concentration for specialized borosilicate glass tubing primarily resides with a few European producers, creating potential bottleneck risks. Raw material dependencies include medical-grade polymers, high-purity aluminum foil, and specialized glass. The regulatory validation cycle for changing primary packaging materials represents a significant supply chain risk. Germany and Switzerland anchor the supply of high-value glass and polymer containers, with emerging production capabilities in Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the premium-tier shift towards high-barrier materials and specialized solutions for sensitive biologics.
For Market Incumbents: To counter the threat of lengthy regulatory validation cycles for new materials, invest heavily in R&D for advanced mono-material solutions that meet both drug stability and sustainability mandates. Expand capacity in specialized high-barrier films and coated glass vials to capitalize on the growing biologics pipeline. Form long-term co-development partnerships with pharmaceutical manufacturers to integrate packaging innovation early in the drug development process.
For New Entrants and Emerging Players: Contract packaging providers offer a viable entry point for specialized material suppliers. Target personalized medicine packaging, focusing on small-batch, cryogenic-capable solutions with integrated tracking for cell and gene therapies. Localized production in Eastern European hubs like Poland and Hungary represents an opportunity to reduce logistics costs and lead times. Offer integrated smart packaging services, such as sensors for adherence monitoring, as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Specialized packaging conglomerates are the most active acquirers in this space, seeking advanced material science capabilities. The market exhibits long-term viability, underpinned by consistent growth in biologics and evolving sustainability requirements over the next decade. Focus on niche providers with expertise in high-barrier polymers, specialized glass, or complex drug delivery systems. Consolidation in the specialized glass tubing or high-barrier film segments is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and aligns with EU Green Deal mandates for packaging production. |
| Long-term Supply Agreement | Secures critical material supply and mitigates risks associated with concentrated production. |
| Product Launch: Mono-material Blister Packs | Addresses demand for sustainable packaging alternatives, particularly in Germany and France. |
| Acquisition of Specialist Firm | Enhances capabilities in advanced materials or complex drug delivery systems for biologics. |
| Geographic Expansion into Eastern Europe | Supports localized production for expanding pharmaceutical manufacturing hubs in Poland and Hungary. |
Research Approach
Coverage spans Germany, Switzerland, France, Poland, and Ireland, with primary inputs from each region. This analysis combines in-depth primary interviews with pharmaceutical procurement managers, R&D leads for packaging, regulatory affairs specialists, and contract packaging executives. Secondary data sources include EMA guidelines, EU Green Deal policy documents, corporate sustainability reports mandated by CSRD, and industry association publications. A bottom-up and top-down triangulation approach validates market size and segment forecasts.
Market granularity was modeled at the product type, material, application, end-user, and country-level regulatory impact dimensions. The analytical framework projects market growth across the analysis window, with CAGRs derived from historical data analysis and projected market drivers. Key industry-specific forecast inputs include the biologics pipeline expansion and the ongoing implementation of EU Green Deal policies.
Revisions become necessary when significant shifts in EMA or EU Green Deal regulations materialize, or unforeseen disruptions impact specialized material supply chains. Forecasts reflect assumptions documented through extensive primary and secondary research. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Vaccine Shippers Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market