
 Sterile Barrier Packaging Market | 2026-2036
Sterile Barrier Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Barrier Packaging Market Analytics
Buyer concentration among pharmaceutical contract manufacturers is expanding as large CDMOs consolidate sterile fill-finish capacity and demand standardized barrier formats at scale. Amcor plc leverages its global converting footprint to serve these consolidated buyers with tailored pouch and lidding systems. DuPont de Nemours, Inc. sustains technology leadership through Tyvek-based breathable sterile barriers that dominate high-risk implantable applications. West Pharmaceutical Services, Inc. anchors its position in integrated drug containment, combining elastomer closure expertise with sterile barrier delivery formats.
Sterile barrier packaging denotes materials and systems engineered to maintain microbiological integrity of medical products from terminal sterilization through point of use, typically employing porous substrates such as medical-grade paper or Tyvek sealed to polymer films with controlled peel characteristics. Heat sealing technology dominates current production throughput due to its compatibility with in-line form-fill-seal automation and established validation protocols. Flexible packaging formats represent the fastest-expanding segment as ambulatory surgical centers and home infusion therapy shift toward lighter, lower-cube sterile delivery systems. Rigid packaging retains margin concentration in Class III device applications where dimensional stability and puncture resistance justify premium material stacks.
FDA enforces stringent sterility assurance level requirements through 21 CFR Part 820 quality system regulations, while the EU Medical Device Regulation mandates unique device identification traceability that extends to primary packaging layers. ISO 11607 standards govern validation of sterile barrier systems for terminally sterilized medical devices, creating compliance moats for qualified suppliers. Stakeholders must monitor evolving sustainability mandates from ECHA and state-level packaging waste directives that threaten to displace conventional multi-layer polymer constructions without certified recycling pathways.
Market Dynamics
Contract manufacturing consolidation is compressing buyer bases while tightening validation requirements for sterile barrier systems, forcing suppliers to standardize formats and accelerate qualification timelines to retain volume commitments.
Growth Catalysts
- EU MDR traceability mandates:Unique device identification requirements extending to primary packaging layers are forcing device makers to upgrade barrier systems, creating replacement demand for qualified suppliers.
- Ambulatory surgical center expansion:Same-day procedure volume growth in outpatient settings is pulling lighter, lower-cube sterile delivery formats into mainstream adoption.
- Tyvek breathable barriers:Dominance in high-risk implantable applications continues as porous substrate technology maintains sterility assurance levels for terminally sterilized devices.
Market Restraints
- Multi-layer polymer cost volatility:Ethylene and propylene feedstock price swings compress margins for film laminators serving high-volume pouch markets.
- German sterilization service concentration:Central European supply chains cluster specialized contract sterilization capacity, creating geographic chokepoints for just-in-time barrier validation.
- Recycling pathway absence:ECHA sustainability mandates threaten conventional multi-layer constructions lacking certified circular recovery streams.
Strategic Opportunities
- Home infusion therapy channels:Patient-administered biologics are opening direct-to-consumer sterile delivery formats bypassing traditional hospital procurement.
- ISO 11607-1:2019 revision alignment:Updated validation protocols create first-mover advantage for suppliers pre-qualifying to amended sterility assurance benchmarks.
- Digital printing convergence:On-demand variable data printing integrated with form-fill-seal lines enables lot-specific traceability without pre-printed inventory.
Industry Challenges
- Heat seal validation expertise scarcity:Qualified technicians capable of executing IQ/OQ/PQ protocols for in-line automation are concentrated among legacy medical device converters.
- Legacy ERP integration friction:New sterile barrier traceability systems must interface with decades-old manufacturing execution platforms at established device makers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Barrier Packaging Market |
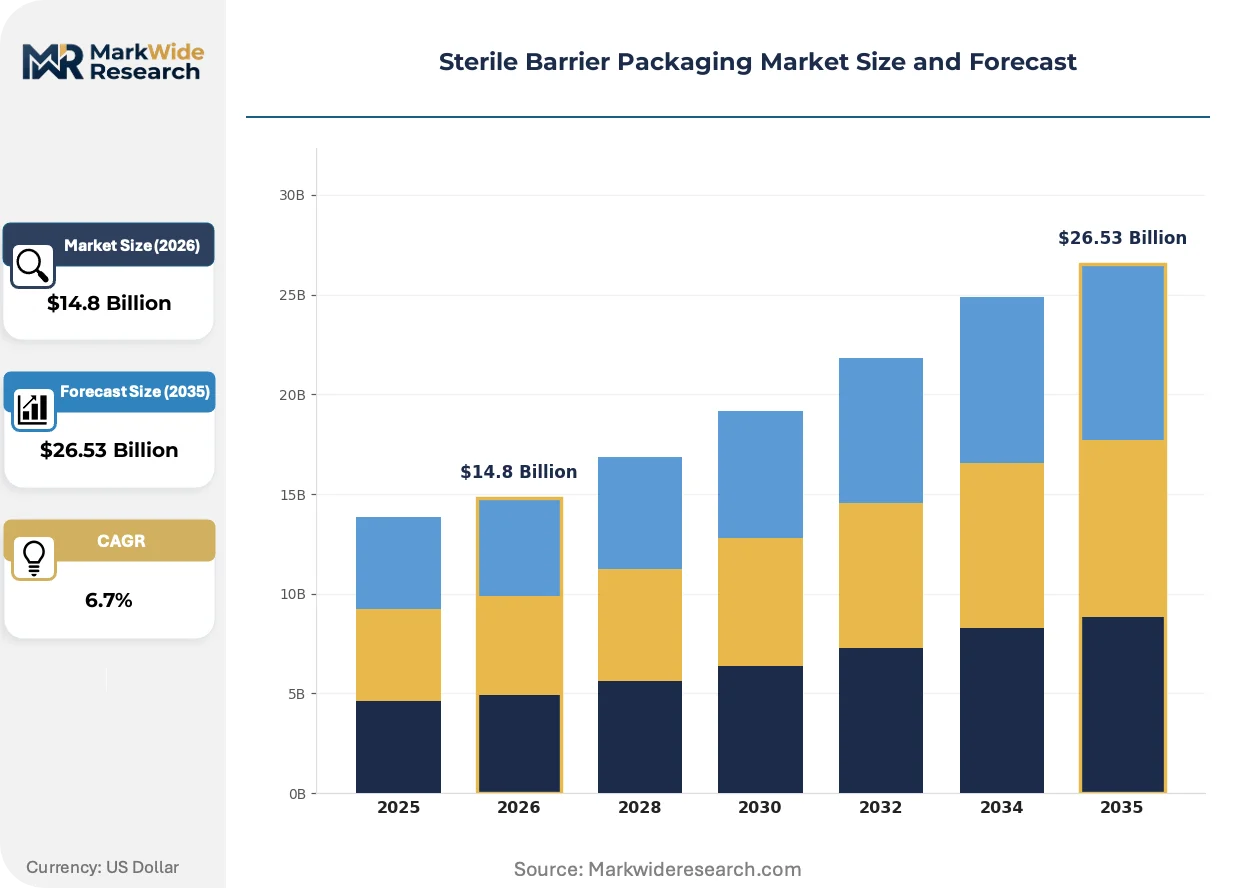
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Pouches, Wrappers Material: Polyethylene, Polypropylene, Paper, Aluminium End User: Pharmaceuticals, Medical Devices, Biotechnology, Diagnostics Technology: Heat Sealing, Radiation, Gas Sterilization, Electron Beam |
| Companies Covered | Amcor plc, DuPont de Nemours, Inc., Sealed Air Corporation, 3M Company, West Pharmaceutical Services, Inc., SteriPack Group, Gerresheimer AG, Berry Global, Inc., Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Barrier Packaging Market Evolving Landscape
Material science advances and regulatory digitization are converging to redefine how sterile barriers demonstrate integrity across distributed supply chains, with automation and sustainability emerging as dual performance axes.
Laser-perforated breathable films are electrifying sterile barrier design by replacing mechanical punching with precision energy-based pore formation. Ambulatory surgical centers and home infusion suppliers are adopting these formats for implantable device kits requiring controlled gas exchange. The technology is electrifying competitive positioning among film converters by collapsing lead times for custom porosity specifications while maintaining ISO 11607 compliance.
FDA 21 CFR Part 820 quality system enforcement is tightening sterility assurance documentation requirements for terminally sterilized devices. Device manufacturers must now demonstrate continuous seal integrity monitoring through automated vision systems rather than batch sampling. Class III implantable producers in the US are responding by retrofitting legacy form-fill-seal lines with in-line seal-strength verification modules.
Consolidated CDMO procurement desks are compressing supplier qualification cycles from eighteen months to six months for standardized barrier formats. Large pharmaceutical contract manufacturers are displacing fragmented regional converters with global framework agreements specifying pre-validated pouch and lidding systems. This concentration is most visible in Germany, where centralized purchasing at sterile fill-finish campuses is narrowing the qualified supplier base to three dominant converting networks.
Sterile Barrier Packaging Market Segmentation
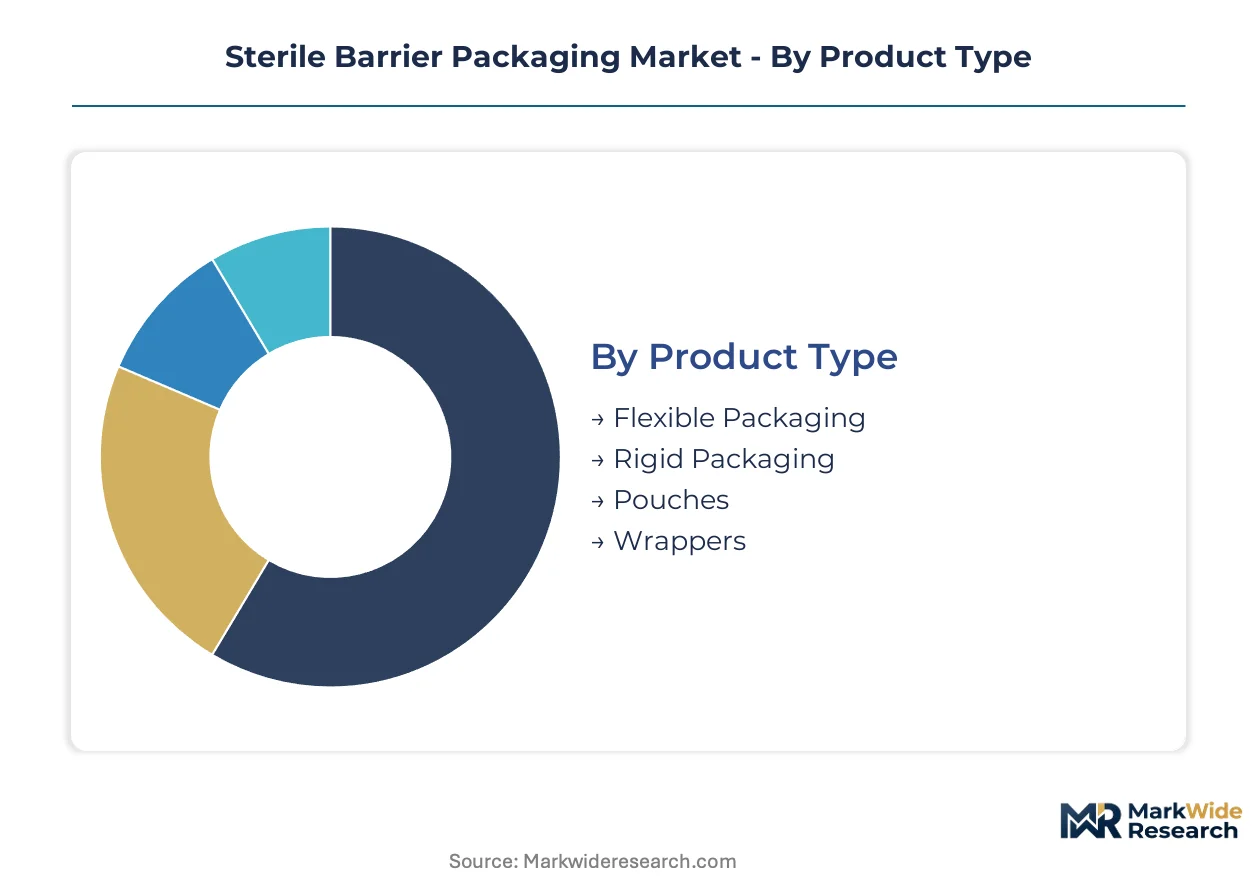
Sterile barrier packaging segmentation reflects divergent buyer priorities across pharmaceutical fill-finish operations, implantable device manufacturing, and point-of-care delivery. Material selection and format specifications cascade directly into validation timelines, sterilization compatibility, and total cost of ownership calculations that determine supplier relationships.
Product Type:
Buyers prioritize cube efficiency and automation compatibility when specifying barrier formats for high-volume pharmaceutical production.
- Flexible Packaging:Multi-layer polymer films sealed to porous substrates deliver the lowest delivered cost per unit for high-volume parenteral drugs. Ambulatory surgical centers in Germany and the United States are pulling lighter pouch formats into mainstream adoption as same-day procedures expand.
- Rigid Packaging:Thermoformed trays and injection-molded containers provide dimensional stability for Class III implantables where puncture resistance justifies premium material stacks. Medical device manufacturers in Switzerland and Ireland specify these formats for orthopedic and cardiovascular kits requiring nested instrument protection.
- Pouches:Three-side-seal and stand-up configurations dominate contract sterilization operations where throughput velocity depends on rapid loading and validated peel characteristics.
- Wrappers:Single-use sterile drapes and instrument covers serve hospital central supply departments with cost-minimized disposable options for general surgical instruments.
Volume sits with flexible formats; growth tilts toward rigid systems for complex implantable kits.
Material:
Feedstock cost volatility and recycling pathway availability increasingly constrain material selection for sustainability-conscious procurement desks.
- Polyethylene:Low-density and linear low-density grades dominate blown film production for pouch inner seal layers due to broad heat-seal latitude and established sterilization compatibility. Japanese and South Korean converters favor metallocene-catalyzed grades for enhanced clarity in high-visibility medical kits.
- Polypropylene:Cast and oriented films provide moisture barrier properties for hygroscopic drug protection. Biaxially oriented PP structures from Italian and Austrian suppliers serve European pharmaceutical contract manufacturers with ECHA-compliant material certifications.
- Paper:Medical-grade kraft and synthetic papers deliver breathable sterile barriers for ethylene oxide and steam sterilization cycles where gas permeability controls sterility assurance.
- Aluminium:Foil laminates provide absolute moisture and light barrier for oxygen-sensitive biologics and light-degradable active pharmaceutical ingredients.
Polyethylene commands current volume; polypropylene climbs fastest as barrier performance requirements tighten.
End User:
Validation complexity and regulatory scrutiny intensity separate end-user segments by qualification timeline and supplier stickiness.
- Pharmaceuticals:Sterile fill-finish operations for injectable and ophthalmic drugs demand the most stringent particulate and endotoxin specifications. FDA 21 CFR Part 820 compliance documentation requirements extend to primary packaging layers, creating multi-year supplier qualification cycles.
- Medical Devices:Implantable, surgical, and diagnostic equipment manufacturers balance barrier performance against sterilization modality compatibility. EU MDR unique device identification mandates are forcing barrier system upgrades across German, French, and Italian device clusters.
- Biotechnology:Cell and gene therapy producers require cryogenic-compatible barrier materials for ultra-low temperature distribution chains.
- Diagnostics:In-vitro diagnostic kit manufacturers prioritize cost-optimized pouches for single-use test components with shorter validation horizons.
Pharmaceutical procurement concentrates volume; biotechnology applications expand most quickly as advanced therapy manufacturing scales.
Technology:
Sterilization modality selection locks in barrier material specifications and determines validation protocol complexity for terminal sterilization applications.
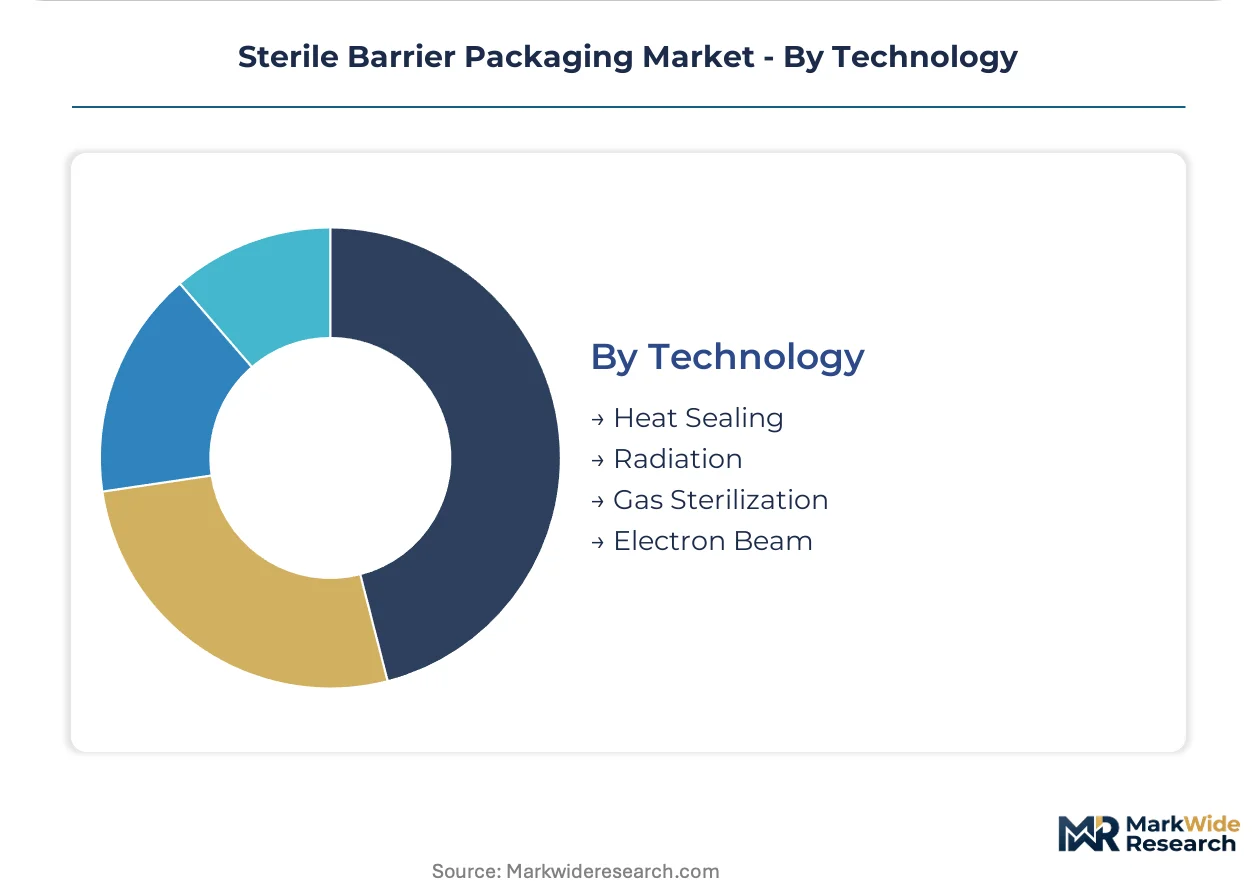
- Heat Sealing:Thermal bonding of polymer films to themselves or porous substrates dominates in-line form-fill-seal automation due to established IQ/OQ/PQ protocols and real-time seal integrity verification. Swiss and German packaging machinery OEMs supply validated heat-seal systems to contract manufacturers worldwide.
- Radiation:Gamma and electron beam sterilization modalities demand radiation-stable polymer formulations that resist embrittlement and discoloration at standard sterilization doses.
- Gas Sterilization:Ethylene oxide and vaporized hydrogen peroxide cycles require breathable barrier materials with controlled porosity for sterilant penetration and aeration.
- Electron Beam:E-beam sterilization offers faster turnaround than gamma for temperature-sensitive products, driving adoption at regional contract sterilization facilities in the United States and Western Europe.
Heat sealing anchors installed capacity; electron beam gains share fastest as device makers seek reduced sterilization cycle times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene and polypropylene feedstock clusters in the US Gulf Coast and German Rhine-Ruhr corridor anchor sterile barrier packaging supply chains. Terminal sterilization service concentration in Central Europe and pharmaceutical fill-finish expansion in Asia-Pacific redistribute demand geography.
United States
FDA 21 CFR Part 820 enforcement tightens sterility assurance documentation for terminally sterilized devices. Ambulatory surgical center expansion across Texas and Florida pulls lighter pouch formats into mainstream adoption. The Minneapolis-St. Paul corridor hosts medical device OEMs retrofitting legacy form-fill-seal lines with automated seal-strength verification.
Germany
EU MDR unique device identification mandates force barrier system upgrades across implantable device clusters. ECHA sustainability certifications constrain multi-layer polymer selections for export-oriented converters. Specialized sterilization service campuses in North Rhine-Westphalia create geographic chokepoints for just-in-time barrier validation.
China
NMPA alignment with ISO 11607 standards accelerates qualification timelines for domestic barrier suppliers. Contract manufacturing consolidation in Jiangsu and Zhejiang provinces concentrates procurement desks demanding standardized formats. Yangtze River Delta pharmaceutical clusters drive flexible packaging volume for high-volume parenteral drugs.
Japan
METI carbon neutrality roadmaps pressure medical packaging converters toward recyclable mono-material constructions. PMDA sterility assurance requirements maintain stringent validation protocols for imported barrier systems. Osaka-based medical device manufacturers specify rigid thermoformed trays for orthopedic and cardiovascular kits.
Switzerland
Swissmedic traceability mandates extend to primary packaging layers for Class III implantables. Precision manufacturing clusters in Basel and Zurich prioritize dimensional stability for nested instrument protection. Alpine pharmaceutical contract manufacturers source pre-validated lidding systems from qualified converting networks.
Sterile Barrier Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital printing integration and sustainable material certifications. The supplier base concentrates around three strategic archetypes: global diversified packaging conglomerates with medical-grade converting footprints, specialized pharmaceutical containment specialists combining elastomer and barrier expertise, and regional sterilization service integrators offering turnkey validation. Competitive positioning hardens through backward integration into polymer film extrusion and strategic partnerships with form-fill-seal machinery OEMs.
Within the diversified packaging tier, Amcor plc and Berry Global, Inc. exemplify scale-driven converters with broad medical-grade film and pouch portfolios. DuPont de Nemours, Inc. anchors the materials science vector through substrate technology leadership. West Pharmaceutical Services, Inc. occupies a position in integrated drug containment, bridging elastomer closure systems with sterile barrier delivery formats.
| Leading Market Players |
|---|
| Amcor plc |
| DuPont de Nemours, Inc. |
| Sealed Air Corporation |
| 3M Company |
| West Pharmaceutical Services, Inc. |
| SteriPack Group |
| Gerresheimer AG |
| Berry Global, Inc. |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
Qualified heat-seal validation technicians concentrated in Germany's North Rhine-Westphalia corridor command wage premiums that compress margins for converters serving economy-tier pouch markets, widening spreads between validated premium systems and commodity alternatives.
Pricing Analysis
Warranty coverage for seal-integrity failures and IQ/OQ/PQ documentation support are bundled into premium-tier contracts, while standard and economy tiers strip validation services to base material costs. Price differentiation hinges on ISO 11607 certification tier and sterilization modality compatibility breadth. Pricing pressure stems from CDMO procurement desks consolidating volume under framework agreements that demand year-over-year cost reductions. Biotechnology startups exhibit highest price sensitivity due to pre-revenue cash constraints, whereas Class III device manufacturers prioritize assurance over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from FDA-inspected device makers require qualification of redundant film extruders and converting lines, extending supplier onboarding timelines. Raw material supply draws from polyethylene and polypropylene feedstock clusters in the United States Gulf Coast, German Rhine-Ruhr corridor, and South Korean petrochemical complexes. Single-source vulnerability concentrates in Tyvek substrate supply where DuPont maintains proprietary breathable barrier technology. Distribution runs through sterilization service campuses that co-locate barrier validation with terminal sterilization capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained system where heat-seal validation expertise scarcity props pricing power for qualified converters against commodity film laminators.
For Market Incumbents: Hedge against CDMO procurement consolidation by embedding into global framework agreements as pre-qualified suppliers, while accelerating backward integration into metallocene-catalyzed polyethylene extrusion to capture margin from feedstock volatility. Certification investment in ECHA-compliant recycling pathways defends position against sustainability-driven specification shifts. For New Entrants and Emerging Players: Home infusion therapy suppliers represent an underserved buyer archetype bypassing traditional hospital procurement through direct-to-consumer channels. Cell and gene therapy producers offer the most penetrable segment given cryogenic barrier material gaps and abbreviated validation histories. Go-to-market execution should prioritize digital printing integration for lot-specific traceability without pre-printed inventory minimums. For Investors and Strategic Acquirers: Re-rating potential sits with specialized sterilization service integrators offering turnkey validation given EU MDR traceability mandate tailwinds. Long-term viability favors acquisition targets combining elastomer closure expertise with sterile barrier formats. Watch for inflection when FDA publishes revised 21 CFR Part 820 guidance on continuous seal integrity monitoring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Captures margin from ethylene feedstock volatility for high-volume pouch converters. |
| ISO 11607-1:2019 Pre-Qualification Investment | Creates first-mover advantage with CDMOs facing compressed eighteen-to-six-month qualification cycles. |
| Digital Printing Convergence with Form-Fill-Seal Lines | Enables lot-specific traceability for EU MDR unique device identification mandates. |
| ECHA-Compliant Recycling Pathway Certification | Defends multi-layer polymer constructions against sustainability-driven specification displacement. |
| Hospital System Partnership for Ambulatory Surgical Centers | Secures volume commitment for lighter pouch formats in same-day procedure expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with sterile fill-finish operations managers, biomedical engineers at Class III device manufacturers, GPO contracts managers, and sterilization service validation leads. Bottom-up triangulation against top-down demand modeling incorporated FDA 21 CFR Part 820 enforcement patterns, EU MDR implementation timelines, and ISO 11607 adoption curves.
Data-stream reconciliation across pharmaceutical production volume databases, medical device registration filings, and sterilization service capacity reports informed segment-level projections across the analysis window. Segmentation dimensions modeled include product format flexibility, material barrier performance tier, end-user validation intensity, and sterilization modality compatibility. CAGRs derived from elasticity-adjusted demand curves incorporating ambulatory surgical center expansion rates and home infusion therapy penetration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA sustainability mandate enforcement and Tyvek substrate supply continuity. A model refresh is warranted upon material change in FDA sterility assurance documentation requirements or CDMO consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
Pipe Insulation Film Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Holographic Transfer Film Market