
 Dual Ovenable Lidding Films Market | 2026-2036
Dual Ovenable Lidding Films Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Ovenable Lidding Films Market Foresight
REACH compliance is rebalancing the cost-of-entry calculus for European suppliers of dual ovenable lidding films. Sealed Air Corporation leverages its integrated film-to-package platform to sustain premium positioning across ready-meal applications. Amcor anchors its competitive stance through specialized high-barrier PET formulations that withstand convection and microwave cycles. Toray Plastics Inc. differentiates via precision-tuned roll stock manufacturing for automated tray-sealing lines in North American food processing plants.
Dual ovenable lidding films are multilayer polymer constructions, typically incorporating PET, polypropylene, or polyethylene substrates with sealant layers engineered to maintain integrity across temperature ranges from freezer storage through conventional and microwave oven exposure. Their primary commercial purpose is to replace separate packaging formats with a single lid that seals fresh or frozen food trays for distribution, retail display, and direct consumer heating without removal. PET-based lidding films dominate current volume due to superior clarity and thermal stability, while polypropylene formulations represent the fastest-growing material segment as processors seek lower-density alternatives with comparable barrier performance. Roll stock occupies the largest share of form segmentation by volume, though pre-cut lids command stronger margins through reduced downstream tooling requirements for mid-sized food manufacturers.
The FDA governs indirect food additive migration limits for ovenable films under 21 CFR, while the EU F-Gas Regulation constrains fluorinated barrier chemistries that historically enabled high-performance lidding. BIS certification requirements in India and GB standards in China add compliance layers for suppliers targeting Asia-Pacific expansion through localized production or export channels. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in the United States, where California and New York are advancing packaging reduction mandates that could accelerate material substitution timelines beyond federal baselines.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing food manufacturers to abandon single-use laminates in favor of recyclable dual-ovenable constructions, compressing material substitution timelines and rewiring supplier qualification protocols across European processing plants.
Growth Catalysts
- Meal kit channel expansion:Direct-to-consumer oven-ready meal subscriptions in North America and Western Europe require lidding films that withstand distribution freezing followed by direct oven heating without package failure.
- REACH compliance deadlines:The European Chemicals Agency's substance restriction timelines are accelerating R&D investment in fluorine-free high-barrier alternatives among film converters serving ready-meal brands.
- Polypropylene density advantages:Processors seeking lightweighting opportunities are converting PET lines to PP-based lidding where comparable clarity and thermal stability can be engineered through multilayer coextrusion.
Market Restraints
- Fluorinated chemistry phase-out:The EU F-Gas Regulation constrains access to legacy high-barrier sealant technologies, forcing expensive reformulation cycles for suppliers dependent on perfluorinated compounds.
- Petrochemical feedstock volatility:Crude oil price swings directly compress margins on PET and PP substrate production, particularly for non-integrated converters lacking captive resin supply.
- Equipment lock-in at processors:Existing tray-sealing lines calibrated for specific film thicknesses and seal temperatures create switching costs that slow material transitions even where superior films exist.
Strategic Opportunities
- India BIS certification pathway:Localized production or joint ventures with certified domestic converters unlocks access to India's expanding organized retail frozen food sector ahead of competitors relying solely on export channels.
- Monomaterial recyclability:Single-polymer lidding constructions that eliminate adhesive lamination layers align with extended producer responsibility frameworks advancing in California and New York.
- Smart packaging integration:RFID-enabled lidding films combining temperature indication with oven-safe substrates are converging with food safety traceability mandates in premium retail channels.
Industry Challenges
- Migration testing complexity:FDA 21 CFR indirect food additive compliance requires extended analytical timelines for new multilayer constructions, delaying commercial launch windows by 8-14 months.
- Automation engineering scarcity:Precision roll stock manufacturing for high-speed tray-sealing lines demands specialized extrusion and winding expertise that concentrates among a narrow technical workforce in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Ovenable Lidding Films Market |
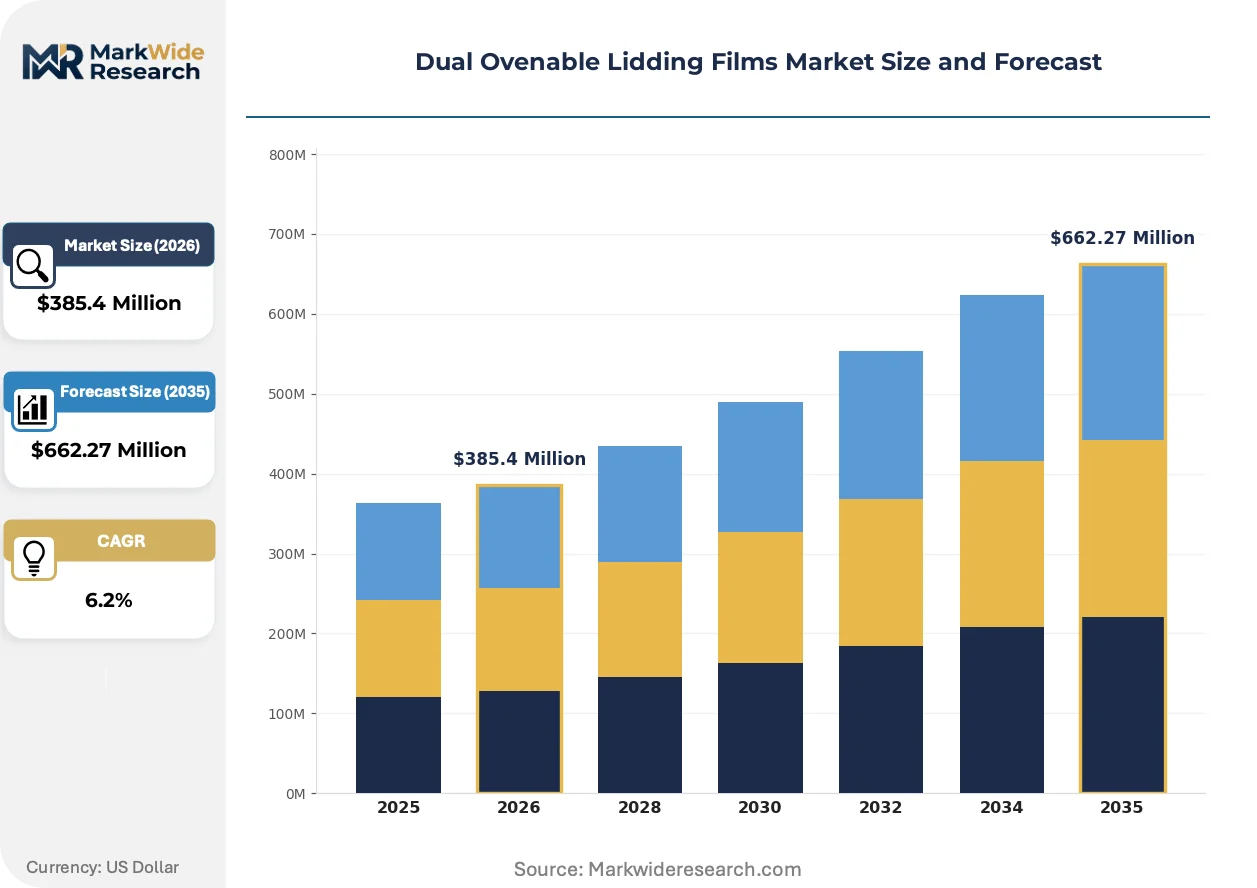
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyethylene, Polypropylene, PET, PVC Application: Ready Meals, Frozen Foods, Snacks, Deli Items Form: Roll Stock, Pre-Cut Lids, Sheets, Pouches End User: Food Manufacturers, Retailers, Foodservice Providers, Meal Kit Companies |
| Companies Covered | Sealed Air Corporation, Golden Eagle Extrusions, Inc., Amcor, Schur Flexibles Holding GmbH, CLIFTON PACKAGING GROUP LTD., DuPont, Bemis Company, Inc., Sonoco Products Company, Toray Plastics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Ovenable Lidding Films Market Shifts & Advancements
Material science breakthroughs and regulatory compression are jointly dismantling the historical trade-off between thermal performance and recyclability, opening design space for next-generation lidding constructions.
Coextruded barrier layers incorporating bio-based polyamide are converging with conventional PET substrates to maintain oxygen transmission rates below 0.5 cc/m²/day while enabling mechanical recycling stream compatibility. European ready-meal processors in Germany and France are piloting these constructions at commercial scale. This convergence is compressing the premium pricing historically commanded by fluorinated barrier chemistries.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbons is forcing sealant suppliers to abandon perfluoropolymer barrier technologies by 2030. Film converters are accelerating investment in plasma-enhanced chemical vapor deposition alternatives and ceramic oxide coatings. High-barrier lidding for seafood and sauce applications faces the steepest reformulation pressure, with Dutch and Danish processors already specifying fluorine-free qualifications in procurement tenders.
Consolidated retail buying power in the United Kingdom and Germany is compressing supplier margins while demanding shorter lead times and technical service integration. National supermarket chains are unbundling film supply from tray sourcing, creating direct relationships with lidding specialists that displace legacy converter-distributor intermediaries. This disintermediation is most advanced in the German discount retail channel, where Aldi and Lidl specifications now drive pan-European film formulation standards.
Dual Ovenable Lidding Films Market Segmentation
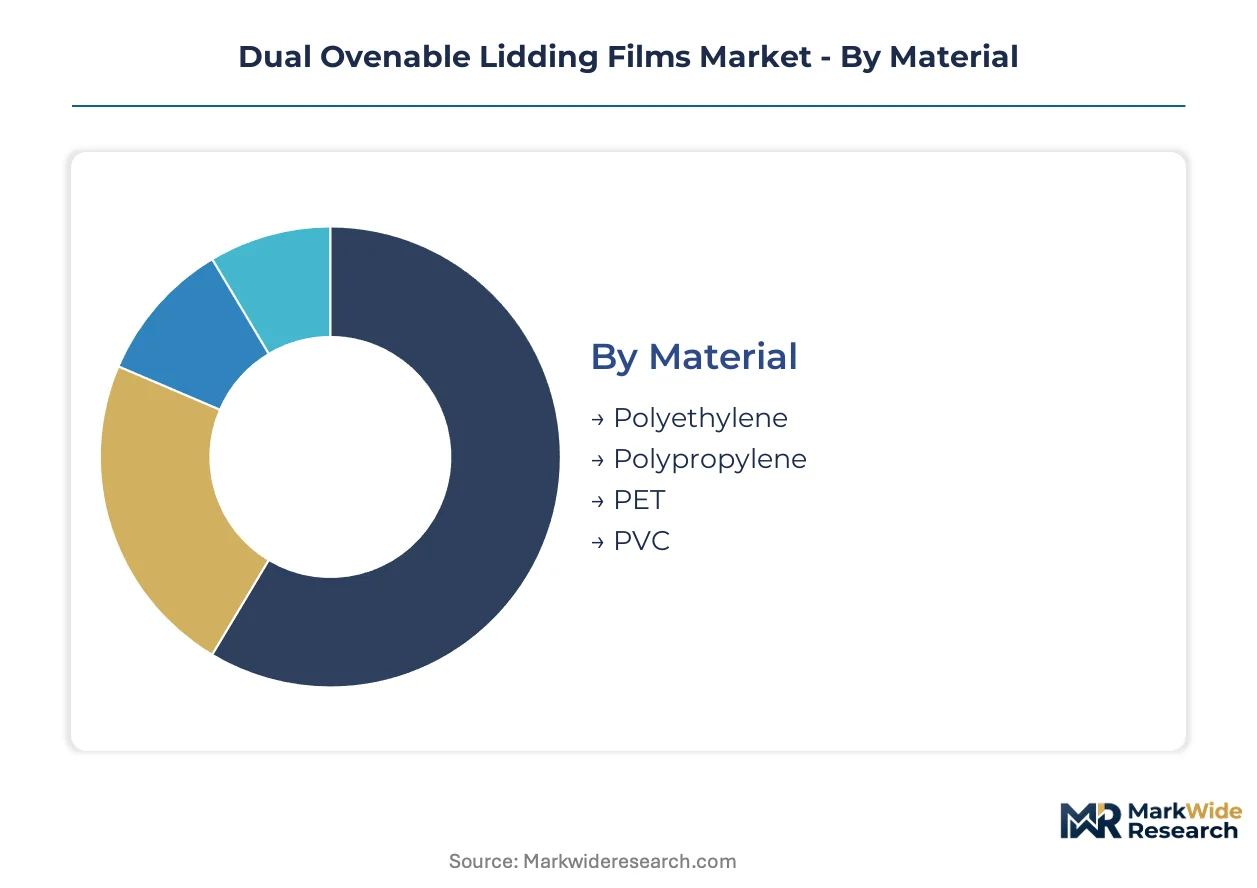
Material selection in dual ovenable lidding films determines thermal tolerance, barrier performance, and recyclability credentials. Processors evaluate substrate chemistry against equipment compatibility and regulatory compliance timelines.
Material:
Equipment upgrade cycles at tray-sealing lines are accelerating substrate transitions as processors seek to avoid stranded asset risk from fluorinated chemistry phase-outs.
- PET:Biaxially oriented polyethylene terephthalate delivers superior optical clarity and dimensional stability across convection and microwave temperature ranges. German ready-meal processors specify PET for premium retail applications where shelf presentation drives purchasing decisions, though density penalties complicate lightweighting targets.
- Polypropylene:Coextruded PP formulations achieve comparable barrier performance at lower basis weights through multilayer architectures incorporating ethylene-vinyl alcohol interlayers. French and Dutch converters are expanding PP capacity fastest as ECHA restriction timelines force fluorine-free qualification pathways.
- Polyethylene:Linear low-density PE serves cost-sensitive frozen food segments where extreme clarity is secondary to seal integrity and puncture resistance.
- PVC:Plasticized polyvinyl chloride retains niche usage in high-temperature roasting applications despite recyclability limitations and tightening EU substance restrictions.
Volume placements concentrate in PET; the faster expansion belongs to Polypropylene.
Application:
Application-driven procurement patterns reflect divergent barrier requirements and consumer heating behaviors across food categories.
- Ready Meals:Multi-component prepared dishes demand oxygen transmission rates below 0.5 cc/m²/day to prevent sauce oxidation and protein discoloration. UK supermarket chains specify high-barrier lidding for chilled ready-meal ranges with extended shelf-life claims.
- Frozen Foods:Ice crystal management and freezer burn prevention dominate specification sheets for vegetable and protein products distributed through temperature-controlled logistics networks.
- Snacks:Grease-resistant sealant layers accommodate fried and baked snack applications where oil migration would compromise package integrity.
- Deli Items:Modified atmosphere compatibility and easy-peel functionality characterize sliced meat and cheese applications in retail deli counters.
Ready Meals command the largest placement volumes; Meal Kit channel expansion is climbing the fastest.
Form:
Form factor decisions hinge on automation level, changeover frequency, and downstream tooling investment capacity at processing facilities.
- Roll Stock:Continuous wound film enables high-speed form-fill-seal operations with minimal material waste and real-time width adjustment. North American frozen food plants prefer roll stock for volume production lines running single SKUs for extended campaigns.
- Pre-Cut Lids:Die-cut dimensions eliminate slitting and registration steps on tray-sealing equipment, reducing changeover downtime for mid-sized manufacturers with diverse product portfolios.
- Sheets:Flat-cut film dimensions serve manual or semi-automatic sealing operations in foodservice and small-batch production environments.
- Pouches:Pre-formed lidding structures accommodate specialty tray geometries and dual-compartment configurations for sauce-separated meal designs.
Roll Stock dominates current volume; Pre-Cut Lids are gaining share fastest among mid-tier processors.
End User:
End-user procurement sophistication varies sharply across the value chain, from technical specification development to spot-buying behavior.
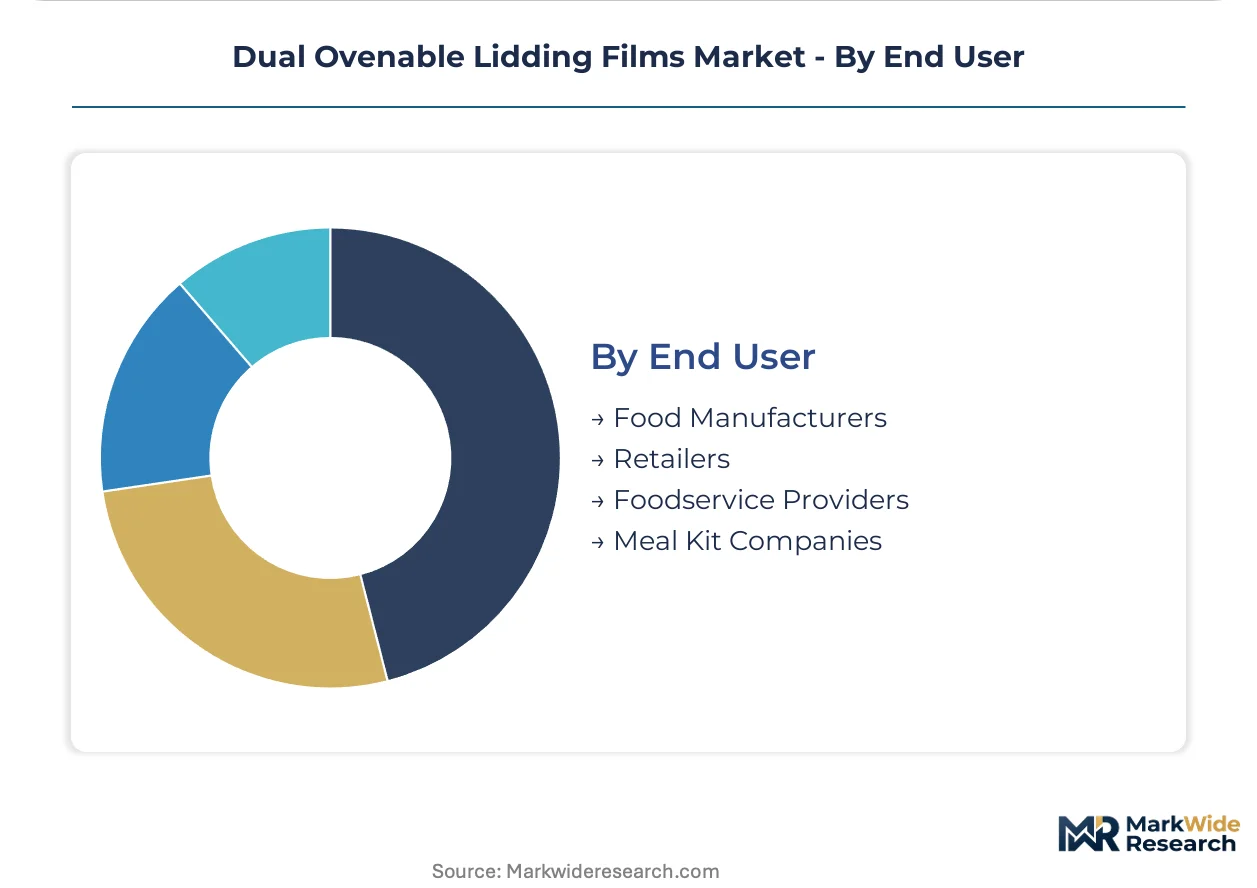
- Food Manufacturers:Integrated production facilities with captive tray-forming lines negotiate direct supply relationships with film converters, specifying barrier performance, seal strength, and regulatory documentation in multi-year agreements.
- Meal Kit Companies:Direct-to-consumer subscription services require oven-ready packaging that withstands frozen distribution followed by consumer heating without package removal or venting complexity.
- Retailers:Private-label program managers increasingly unbundle lidding supply from tray sourcing, creating direct specification authority over film formulations and sustainability credentials.
- Foodservice Providers:Contract catering and institutional feeding operations prioritize cost minimization and operational simplicity over premium barrier performance or optical properties.
Food Manufacturers account for the largest volume placements; Meal Kit Companies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical processing zones around Ludwigshafen and Leverkusen concentrate European film extrusion capacity, drawing converters seeking proximity to resin supply and REACH compliance infrastructure.
United States
FDA 21 CFR migration testing protocols govern lidding film qualification for frozen ready-meal processors in the Midwest. The Chicago-Joliet corridor hosts automated tray-sealing operations supplying national retail chains. Illinois-based food manufacturers are converting PET lines to fluorine-free barrier constructions ahead of anticipated state-level extended producer responsibility mandates.
Germany
The EU F-Gas Regulation is compressing reformulation timelines for high-barrier sealant technologies serving premium ready-meal brands. North Rhine-Westphalia's Ruhr industrial belt concentrates multilayer coextrusion expertise among specialized film converters. Aldi and Lidl procurement specifications now drive pan-European formulation standards for ovenable lidding.
China
GB standards compliance requirements are intensifying for imported dual-ovenable films targeting domestic frozen food processors. The Yangtze River Delta around Shanghai hosts the largest concentration of automated meal kit fulfillment centers in Asia. Local converters are investing in PET and PP substrate capacity to reduce dependence on Korean and Japanese roll stock imports.
India
BIS certification pathways are unlocking access to organized retail frozen food distribution networks in Mumbai and Delhi. Maharashtra's Thane-Bhiwandi industrial corridor is attracting joint ventures between European film specialists and domestic converters. Food manufacturers in Gujarat are piloting dual-ovenable formats for export-oriented ready-meal production.
United Kingdom
Consolidated supermarket buying power is compressing supplier margins while demanding shorter lead times from lidding specialists. The Midlands packaging cluster around Birmingham supplies automated tray-sealing equipment calibrated to European film specifications. Retail private-label program managers are unbundling film supply from tray sourcing to direct sustainability credential negotiations.
Dual Ovenable Lidding Films Market Competitive Landscape
German and Austrian producers anchor the premium barrier tier; North American specialists hold volume positions in frozen food roll stock. The vendor base separates into integrated resin-to-film operators, independent converters with specialized coextrusion lines, and regional distributors serving mid-tier processors. Three archetypes dominate: multinational packaging conglomerates with captive R&D, mid-cap European converters with REACH compliance depth, and Asian fabricators scaling cost-optimized substrate production. Competitive moves concentrate on fluorine-free barrier reformulation and automated roll stock manufacturing partnerships with tray-sealing equipment suppliers.
Within the integrated packaging tier, Sealed Air Corporation and Amcor exemplify the resin-to-package platform model that sustains premium positioning through technical service integration. Among independent European specialists, Schur Flexibles Holding GmbH and Toray Plastics Inc. occupy positions defined by precision-tuned manufacturing for high-speed automated lines. DuPont represents the materials science archetype, supplying barrier resin technologies to downstream converters rather than competing in finished lidding film markets.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Golden Eagle Extrusions, Inc. |
| Amcor |
| Schur Flexibles Holding GmbH |
| CLIFTON PACKAGING GROUP LTD. |
| DuPont |
| Bemis Company, Inc. |
| Sonoco Products Company |
| Toray Plastics Inc. |
| Others |
Supply & Pricing Matrix
Captive resin supply through backward integration into petrochemical feedstock anchors pricing power for integrated film converters serving European ready-meal processors, while non-integrated competitors absorb margin compression from crude oil volatility without offsetting volume leverage.
Pricing Analysis
Short lead-time premiums command pricing separation from standard contract terms as UK and German supermarket chains compress supplier margins through consolidated procurement. Three-tier pricing structure across premium fluorine-free barrier, standard PET-based, and economy PE-grade lidding separates procurement tiers by certification depth and technical service integration. Pricing pressure stems from Aldi and Lidl pan-European specifications standardizing formulations across multiple converters. Mid-sized food manufacturers exhibit highest price sensitivity due to limited volume leverage, while multinational ready-meal brands absorb premium pricing for REACH-compliant documentation.
Supply Chain Analysis
Specialized extrusion and winding expertise concentrates among technical workforces in Germany and Japan, constraining capacity expansion for precision roll stock manufacturing. Resin supply draws from Ludwigshafen chemical processing zones, Korean PET substrate imports, and domestic PP coextrusion lines in France and the Netherlands. Single-source vulnerability runs through fluorinated barrier chemistry suppliers facing EU F-Gas Regulation phase-out deadlines. Distribution runs through direct converter relationships with tray-sealing equipment OEMs and regional distributors serving mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over fluorine-free barrier resin technology and captive coextrusion capacity determines sustainable margin capture across regulatory compliance timelines.
For Market Incumbents: Anticipate ECHA substance restriction acceleration by securing plasma-enhanced chemical vapor deposition partnerships ahead of 2030 fluoropolymer phase-out deadlines. Deepen backward integration into bio-based polyamide barrier resin supply to defend formulation differentiation against Asian cost-optimized substrate entrants. Prioritize automated roll stock manufacturing partnerships with German tray-sealing equipment suppliers to lock in technical workforce scarcity advantages.
For New Entrants and Emerging Players: Direct-to-meal-kit-channel routes offer white-space penetration ahead of established converter relationships, targeting subscription services requiring oven-ready packaging without legacy equipment calibration constraints. India's BIS certification pathway presents the most penetrable geography, with Maharashtra industrial corridor joint ventures enabling organized retail frozen food access before export-dependent competitors establish localized production. Position through fluorine-free barrier qualification as a service, converting R&D investment into technical consulting revenue ahead of full film production scale.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated packaging conglomerates seeking REACH compliance depth and European food manufacturer relationships. Mid-cap German and Austrian converters with captive coextrusion lines and established Aldi or Lidl supply qualifications represent the priority acquisition archetype. Watch for inflection in EU F-Gas Regulation enforcement intensity as the signal triggering accelerated consolidation among fluorinated chemistry-dependent suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Reformulation | ECHA restriction timelines force R&D investment in plasma-enhanced deposition and ceramic oxide coatings by 2030. |
| Backward Integration into Bio-Based Polyamide | Coextruded barrier layers with mechanical recycling compatibility capture premium from extended producer responsibility frameworks. |
| Automated Roll Stock Manufacturing Partnerships | Precision-tuned supply agreements with German tray-sealing equipment OEMs concentrate scarce extrusion expertise. |
| BIS Certification Localization in India | Maharashtra joint ventures unlock organized retail frozen food distribution ahead of export-channel competitors. |
| Smart Packaging Integration | RFID-enabled temperature indication converges with food safety traceability mandates in premium UK and German retail channels. |
Research Methodology
Document review covered regulatory filings with ECHA and FDA, trade association reports from plastics industry associations, and customs data on resin and film imports, complemented by interviews with film converter technical directors, ready-meal processor procurement leads, tray-sealing equipment OEM sales engineers, and supermarket private-label program managers. Secondary validation drew from EU Packaging and Packaging Waste Regulation impact assessments, SEC 10-K disclosures from integrated packaging conglomerates, and German chemical industry production statistics. Bottom-up demand modeling from food manufacturer volume requirements and top-down supply assessment from extrusion capacity announcements were triangulated to constrain forecast variance.
Segment-level projections across material substrate, application category, form factor, and end-user archetype were generated through the analysis window using equipment upgrade cycle timing, regulatory compliance deadline clustering, and meal kit channel expansion rates as primary demand drivers. CAGRs were derived from slope-constrained growth curves fitted to historical volume trajectories and adjusted for fluorinated chemistry phase-out acceleration. Forecast inputs incorporated resin price elasticity coefficients from petrochemical market data and substitution elasticity estimates between PET and PP formulations.
The model holds under stable EU regulatory enforcement intensity and continued meal kit subscription growth; deviation in ECHA restriction timeline acceleration or crude oil price volatility exceeding historical bands would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Decorative Films and Foils Market