
 Cold Chain Packaging Materials Market | 2026-2036
Cold Chain Packaging Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Chain Packaging Materials Market Analysis
Modular packaging configurations that separate insulation cores from outer shells is broadening procurement flexibility for pharmaceutical logistics teams. Cold Chain Technologies leverages its North American manufacturing footprint to sustain rapid fulfillment cycles for vaccine shippers. Sealed Air Corporation anchors its position through proprietary foam-in-place insulation systems that dominate high-value biologics transport. Sofrigam competes across European corridors with reusable parcel shippers designed for last-mile pharmacy delivery.
Cold chain packaging materials comprise engineered thermal barriers, phase-change refrigerants, and sensor-integrated enclosures that maintain specified temperature bands for heat-sensitive cargo during transit and storage. Vacuum insulation panels achieve thermal resistance values five to ten times higher than expanded polystyrene at equivalent thickness, making them critical for ultra-frozen gene therapies and mRNA platforms. Insulated boxes and pallet covers command the largest product volume pools due to their ubiquity across pharmaceutical and food distribution networks, while temperature monitoring devices capture disproportionate margin expansion as regulatory traceability mandates intensify. Refrigerants represent the fastest-growing material category as phase-change formulations advance beyond water-based gels to engineered salt hydrates and organic compounds.
The FDA's 21 CFR Part 211 guidelines and the EU's Good Distribution Practice framework mandate documented temperature control across pharmaceutical supply chains, directly elevating specification thresholds for packaging validation. EPA regulations on hydrofluorocarbon phase-outs are accelerating refrigerant chemistry transitions toward lower-global-warming-potential formulations. Stakeholders must monitor evolving pharmacopeial standards from USP and EDQM that increasingly define excursion thresholds at the product level rather than the shipment level.
Market Dynamics
Reusable thermal shipper systems are compressing total cost of ownership for biopharmaceutical distributors while forcing single-use foam manufacturers to defend their installed base through performance guarantees and rapid fulfillment commitments.
Growth Catalysts
- EU GDP temperature documentation mandates:Pharmaceutical logistics providers must now maintain continuous digital records across distribution chains, elevating demand for sensor-integrated packaging assemblies.
- mRNA platform proliferation:Gene therapy developers require ultra-frozen shipment corridors maintained below minus sixty degrees Celsius, expanding addressable volume for vacuum insulation panel configurations.
- India vaccine manufacturing expansion:Domestic production capacity for COVID-19 and routine immunization programs is generating outbound cold chain packaging demand toward Southeast Asian and African markets.
Market Restraints
- Polystyrene feedstock volatility:Expanded polystyrene insulation cores face input cost pressure from benzene derivative markets, compressing margins for commodity shipper producers.
- Chinese refrigerant precursor concentration:Salt hydrate and organic phase-change material supply chains depend on concentrated intermediate chemical production in Shandong and Jiangsu provinces.
- Technical limitation in multi-use validation:Reusable shipper cleaning and requalification protocols create residual bioburden detection challenges that delay redeployment cycles.
Strategic Opportunities
- Cell therapy last-mile corridors:Autologous treatment delivery from manufacturing sites to infusion centers within seventy-two-hour windows requires specialized parcel shippers with active temperature modulation.
- EPA hydrofluorocarbon phase-out:Refrigerant chemistry transitions toward lower-global-warming-potential formulations create first-mover advantage for salt hydrate and paraffin-based phase-change material developers.
- Direct-to-patient pharmacy distribution:Specialty medication home delivery programs in Germany and the United States are bypassing wholesale distribution centers for temperature-controlled parcel networks.
Industry Challenges
- Thermal engineer talent scarcity:Packaging design teams lack sufficient expertise in computational fluid dynamics modeling for hybrid active-passive shipper configurations.
- IQ/OQ/PQ validation timeline compression:Pharmaceutical sponsors demand accelerated qualification protocols for new shipper designs, straining testing laboratory capacity.
- Interoperability with legacy warehouse management systems:Sensor data streams from intelligent shippers require middleware development to integrate with established ERP platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Chain Packaging Materials Market |
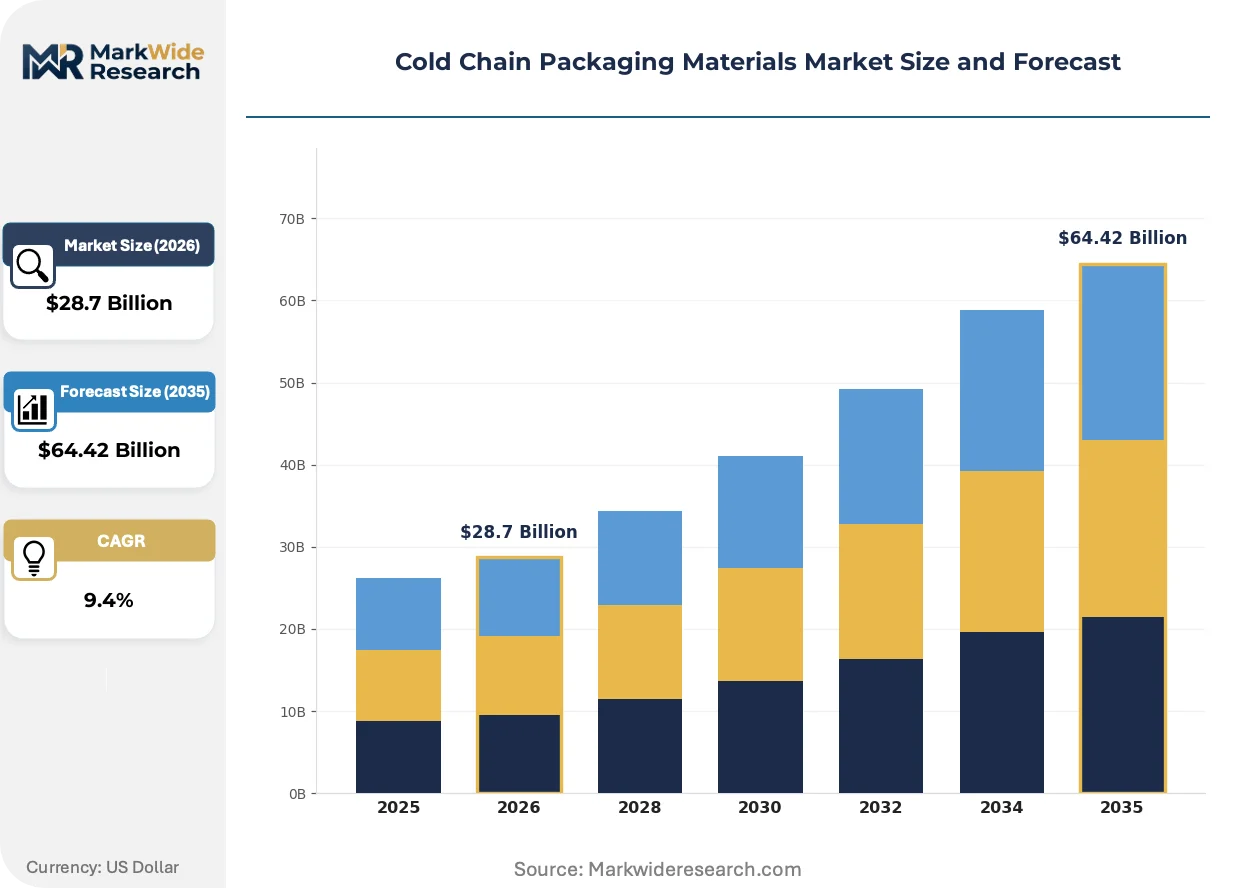
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Boxes, Refrigerants, Temperature Monitoring Devices, Pallet Covers Application: Pharmaceuticals, Food & Beverages, Biotechnology, Cosmetics Material: Polystyrene, Polyethylene, Aluminium, Vacuum Insulation Panels End User: Logistics Providers, Healthcare Facilities, Retailers, E-commerce |
| Companies Covered | Cold Chain Technologies, Sonoco ThermoSafe, Peli BioThermal, Sofrigam, Cryopak, Nordic Cold Chain Solutions, Sealed Air Corporation, CSafe, Intelsius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Chain Packaging Materials Market Emerging Trajectories
Material science advances and regulatory digitization mandates are converging to transform cold chain packaging from passive thermal protection into active data-generating supply chain nodes. Three developments dominate current competitive positioning.
Vacuum insulation panel technology is overtaking expanded polystyrene in high-value biologics transport. These panels achieve thermal resistance values five to ten times higher than conventional foam at equivalent thickness. Gene therapy developers and mRNA vaccine manufacturers are specifying VIP configurations for ultra-frozen shipments. The technology is compressing dry ice consumption rates and extending autonomous thermal protection duration from forty-eight to ninety-six hours.
REACH restrictions on persistent organic pollutants and the EU F-Gas Regulation are accelerating refrigerant chemistry transitions. Formulators are abandoning hydrofluorocarbon-based phase-change materials in favor of engineered salt hydrates and bio-based paraffin compounds. German pharmaceutical distributors are demanding refrigerant global warming potential documentation as a procurement gate. The regulatory pressure is elevating specification complexity for suppliers serving European corridors.
Pharmaceutical logistics teams are consolidating supplier relationships around packaging-as-a-service models. Rather than purchasing shipper inventory, temperature-controlled transport providers are contracting for guaranteed thermal performance per lane. This procurement evolution displaces capital-intensive shipper ownership with operational expenditure structures tied to successful delivery outcomes. The United States and Germany exhibit the most advanced adoption of outcome-based packaging contracts.
Cold Chain Packaging Materials Market Segmentation
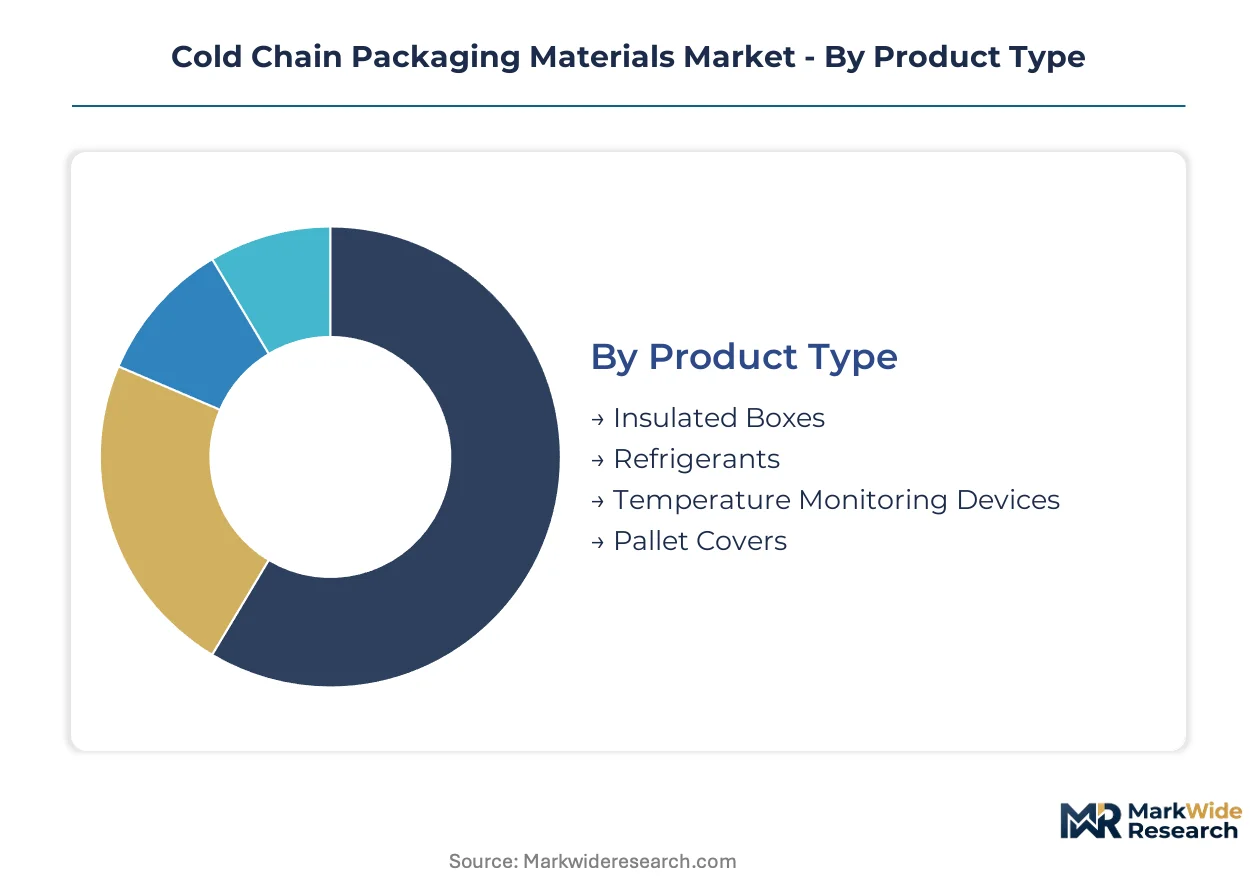
Cold chain packaging procurement hinges on matching thermal performance specifications to cargo value and transit duration. Pharmaceutical distributors prioritize validated temperature assurance over unit economics, while food logistics operators balance insulation efficiency against freight density constraints.
Product Type:
Logistics teams select product formats based on shipment scale, temperature band requirements, and return logistics feasibility for reusable assets.
- Insulated Boxes:These rigid enclosures combine expanded polystyrene or polyurethane cores with corrugated outer shells to protect palletized and parcel-scale pharmaceutical shipments. Demand concentrates in United States vaccine distribution networks where CDC cold chain guidelines mandate validated thermal protection for routine immunization programs.
- Refrigerants:Phase-change materials including water-based gels, salt hydrates, and engineered paraffin compounds absorb or release latent heat to maintain target temperature bands. German pharmaceutical distributors are driving specification shifts toward lower-global-warming-potential formulations ahead of EU F-Gas Regulation deadlines.
- Temperature Monitoring Devices:Sensor-integrated loggers and indicators provide digital evidence of temperature compliance for regulatory submissions.
- Pallet Covers:Flexible insulated blankets and hoods protect full pallet loads during warehouse transfers and short-haul distribution.
Insulated boxes lead on scale; refrigerants lead on momentum.
Application:
End-use industries impose distinct validation protocols, excursion tolerance thresholds, and documentation requirements that reshape packaging specifications.
- Pharmaceuticals:Temperature-sensitive drug products including vaccines, biologics, and gene therapies demand packaging systems qualified against ISTA thermal profiles. United States distributors face FDA 21 CFR Part 211 mandates for continuous temperature documentation across distribution chains.
- Food & Beverages:Fresh produce, dairy, and frozen meat shipments prioritize cost-efficient insulation over precision temperature control. Indian cold chain expansion for agricultural exports is generating demand for commodity-grade insulated containers suited to extended transit corridors.
- Biotechnology:Cell therapies and regenerative medicine products require ultra-frozen shipment corridors maintained below minus sixty degrees Celsius.
- Cosmetics:Active ingredient stability in premium skincare formulations drives temperature-controlled parcel requirements for direct-to-consumer channels.
Pharmaceuticals dominates revenue concentration; biotechnology exhibits the steepest expansion trajectory.
Material:
Material selection trade-offs center on thermal resistance per unit thickness, weight penalties, recyclability credentials, and feedstock cost volatility.
- Vacuum Insulation Panels:These evacuated silica-core panels achieve thermal conductivity values of 0.004 to 0.008 W/m·K, enabling compact shipper designs for ultra-frozen gene therapies. mRNA vaccine manufacturers in Germany and the United States are specifying VIP configurations to extend autonomous thermal protection duration beyond ninety-six hours.
- Polystyrene:Expanded polystyrene remains the default insulation material for commodity pharmaceutical and food shipments due to low unit cost and established molding infrastructure. Benzene derivative feedstock volatility is compressing margins for producers serving price-sensitive segments.
- Polyethylene:Extruded and molded polyethylene foams offer moisture resistance and durability for reusable shipper applications.
- Aluminium:Reflective barrier layers and rigid alloy panels provide radiant heat protection and structural integrity for active temperature-controlled containers.
Polystyrene leads on volume deployment; vacuum insulation panels lead on technology substitution.
End User:
Procurement authority and performance risk allocation vary sharply across customer types, with asset ownership models diverging between capital-intensive and service-based arrangements.
- Logistics Providers:Third-party cold chain operators including specialized pharmaceutical couriers and integrated freight forwarders purchase packaging inventory at scale. United States-based providers are adopting packaging-as-a-service contracts that convert capital expenditure to outcome-based operational expenditure.
- Healthcare Facilities:Hospital pharmacies and infusion centers require parcel-scale shippers for autologous cell therapy receipt within seventy-two-hour manufacturing-to-patient windows.
- Retailers:Grocery and pharmacy chains operating distribution centers specify pallet covers and insulated containers for internal stock rotation and last-mile delivery.
- E-commerce:Online pharmacy and meal-kit platforms demand single-use insulated packaging optimized for residential delivery density and consumer unboxing experience.
Logistics providers lead on procurement volume; e-commerce leads on format innovation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cold chain packaging industry traces its commercial origins to mid-twentieth century pharmaceutical distribution networks in the United States, where temperature-sensitive vaccine programs demanded engineered thermal protection for the first time at scale.
United States
Domestic vaccine manufacturing expansion and autologous cell therapy production drive packaging procurement across Massachusetts and North Carolina biotech clusters. FDA 21 CFR Part 211 guidelines mandate continuous temperature documentation, elevating specification thresholds for sensor-integrated shipper assemblies. Greater Boston anchors ultra-frozen gene therapy corridor demand with mRNA platform developers specifying vacuum insulation panel configurations.
Germany
European pharmaceutical distribution consolidation and last-mile pharmacy network expansion concentrate procurement authority in Rhine-Ruhr and Baden-Württemberg logistics hubs. EU GDP temperature documentation mandates and EU F-Gas Regulation deadlines accelerate refrigerant chemistry transitions toward salt hydrate formulations. Frankfurt logistics corridor operators are contracting packaging-as-a-service agreements that displace capital-intensive shipper ownership.
India
Domestic vaccine manufacturing capacity expansion for COVID-19 and routine immunization programs generates outbound cold chain packaging demand toward Southeast Asian and African markets. CDSCO import and distribution guidelines tighten temperature excursion documentation requirements for biopharmaceutical shipments. Hyderabad and Pune vaccine production clusters are driving specification shifts toward reusable thermal shipper systems for regional export corridors.
China
Biologics manufacturing scale-up and domestic cold chain infrastructure investment expand addressable volume for insulated container producers across Yangtze River Delta pharmaceutical zones. NMPA Good Supply Practice revisions align with international temperature control documentation standards. Shanghai and Suzhou biologics manufacturing parks are specifying hybrid active-passive shipper configurations for extended transit corridors.
United Kingdom
Cell therapy manufacturing facility expansion and direct-to-patient pharmacy distribution programs elevate demand for parcel-scale temperature-controlled packaging across London and Southeast England. MHRA alignment with EU GDP frameworks maintains stringent temperature documentation requirements post-Brexit. Stevenage cell therapy cluster developers are qualifying specialized shippers for seventy-two-hour manufacturing-to-patient delivery windows.
Cold Chain Packaging Materials Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory validation depth, creating a tiered competitive structure where vacuum insulation panel specialists command pricing power over expanded polystyrene molders. The vendor base distributes across three strategic archetypes: integrated thermal solution providers, specialized refrigerant formulators, and sensor-integrated packaging assemblers. Dominant competitive moves include packaging-as-a-service contract proliferation and refrigerant chemistry transitions ahead of regulatory phase-out deadlines.
Within the integrated thermal solution tier, Cold Chain Technologies and Sealed Air Corporation exemplify divergent geographic anchoring strategies, with the former representing North American manufacturing footprint concentration and the latter occupying a position defined by proprietary insulation system development. Sofrigam anchors the European reusable shipper specialization vector. These three entities collectively illustrate how competitive positioning fragments across regional corridor expertise and material science depth rather than consolidating around unified global scale.
| Leading Market Players |
|---|
| Cold Chain Technologies |
| Sonoco ThermoSafe |
| Peli BioThermal |
| Sofrigam |
| Cryopak |
| Nordic Cold Chain Solutions |
| Sealed Air Corporation |
| CSafe |
| Intelsius |
| Others |
Supply Flow & Price Mechanics
Vacuum insulation panel manufacturing migration from artisanal assembly to automated lamination lines is compressing unit economics for ultra-frozen shippers while concentrating production capability among German and United States equipment holders. This dual shift elevates pricing power for VIP-qualified suppliers serving gene therapy corridors while forcing expanded polystyrene molders into volume-based defensive contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates VIP-configured gene therapy shippers from validated pharmaceutical containers and commodity food-grade boxes. Price differentiation hinges on IQ/OQ/PQ certification depth and refrigerant chemistry specification, with EU F-Gas Regulation-compliant salt hydrate formulations commanding material premiums. Cost compression in expanded polystyrene cores is intensifying because benzene derivative feedstock volatility compresses commodity producer margins. Food logistics operators exhibit highest price sensitivity, while biotechnology sponsors accept premium positioning for validated ultra-frozen configurations.
Supply Chain Analysis
Phase-change material production rests on concentrated intermediate chemical manufacturing in Shandong and Jiangsu provinces, with salt hydrate precursors and engineered paraffin compounds drawing from Chinese petrochemical feedstocks. Silica-core VIP substrates source from Japanese and German specialty glass producers, while corrugated outer shells feed from regional paperboard converters. Single-source vulnerability in Chinese refrigerant precursor supply creates tariff exposure risk for Western formulators. Distribution runs through pharmaceutical logistics providers contracting packaging-as-a-service agreements that displace inventory ownership with outcome-based thermal performance guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cold chain packaging materials stems from refrigerant chemistry transitions toward lower-global-warming-potential formulations, where first-mover formulators capture specification premiums ahead of regulatory phase-out deadlines.
For Market Incumbents: Anticipate reusable thermal shipper proliferation compressing single-use foam demand by accelerating qualification laboratory capacity expansion and securing backward integration into refrigerant chemistry manufacturing. Defend installed base through performance-guaranteed rapid fulfillment commitments against emerging packaging-as-a-service competitors. Certification investment in EU GDP-aligned documentation systems represents the critical retention lever for pharmaceutical logistics contracts. For New Entrants and Emerging Players: Sensor-integrated packaging assemblies offer technology-first wedge into pharmaceutical logistics provider procurement cycles, with direct-to-patient pharmacy distribution in Germany and the United States presenting the most penetrable white-space corridor. Target cell therapy last-mile segments requiring seventy-two-hour validated thermal protection with active temperature modulation capabilities. Go-to-market execution should anchor on packaging-as-a-service contract structures that convert capital expenditure objections into operational expenditure acceptance. For Investors and Strategic Acquirers: Valuations sit cheapest among expanded polystyrene molders facing margin compression from benzene feedstock volatility and reusable shipper substitution. Long-term viability framing favors vacuum insulation panel specialists with automated manufacturing footprints and refrigerant formulators with salt hydrate intellectual property. Acquisition target archetype encompasses mid-scale reusable shipper developers with established IQ/OQ/PQ validation protocols. The signal to watch is EPA hydrofluorocarbon phase-out acceleration triggering specification cascade toward lower-global-warming-potential formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Transition | Salt hydrate formulation investment captures EU F-Gas Regulation compliance premiums ahead of deadlines. |
| Packaging-as-a-Service Expansion | Outcome-based contracts convert capital expenditure to operational expenditure for logistics providers. |
| Automated VIP Manufacturing Scale-Up | Lamination line automation compresses unit costs for gene therapy ultra-frozen configurations. |
| Qualification Laboratory Capacity Addition | IQ/OQ/PQ testing infrastructure relieves bottleneck for accelerated shipper validation timelines. |
| Sensor Integration Partnership | Middleware development bridges intelligent shipper data streams to legacy warehouse management systems. |
Methodological Framework
Direct dialogue with pharmaceutical logistics directors, thermal packaging engineers, regulatory affairs specialists, and biopharmaceutical supply chain managers grounded qualitative assessment in operational reality. Secondary validation drew from FDA 21 CFR Part 211 guidance documents, EU GDP framework publications, EPA refrigerant phase-out schedules, and customs trade data on insulated container flows. Bottom-up and top-down triangulation reconciled shipper unit economics with aggregate market value estimates.
Bottom-up modeling of insulated box, refrigerant, temperature monitoring device, and pallet cover volumes across pharmaceutical, food, biotechnology, and cosmetics applications fed into top-down regulatory mandate impact assessment. Segmentation dimensions included product format, temperature band specification, material chemistry, and end-user procurement authority. CAGRs derived from shipment volume trajectories correlated with vaccine manufacturing expansion, cell therapy pipeline advancement, and direct-to-patient distribution penetration across the analysis window. Forecast inputs incorporated benzene derivative price indices and refrigerant precursor trade flow data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA regulatory acceleration, Chinese supply chain disruption, and reusable shipper validation protocol standardization. Forecasts reflect documented assumptions on vaccine production capacity expansion and gene therapy commercialization timelines. Regulatory timeline slippage, feedstock price spikes, or bioburden detection breakthroughs in reusable systems warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
EPE Liner Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Global Strapping Market
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Window Packaging Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Cork Packaging Market