
 Barrier Coated Flexible Paper Packaging Market | 2026-2036
Barrier Coated Flexible Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Coated Flexible Paper Packaging Market Intelligence
High-barrier specification tiers for oxygen and moisture resistance is redrawing competitive priorities across the value chain. Mondi Group leverages integrated pulp-to-paper operations to control coating substrate quality from forest to finished reel. Huhtamaki Oyj anchors its position through specialized extrusion and dispersion coating lines serving quick-service restaurant chains. Stora Enso Oyj differentiates via biopolymer barrier research and pilot-scale cellulose derivative coatings for fresh produce applications.
Barrier coated flexible paper packaging combines kraft or specialty paper substrates with extruded polymers, waxes, or resin dispersions to achieve controlled permeability against water vapor, oxygen, and grease, typically measured in grams per square meter per day or cubic centimeters per square meter per day. The primary commercial purpose is to extend shelf life and protect sensory properties of packaged goods while maintaining fiber-based recyclability claims under prevailing collection and sorting infrastructure. Polyethylene remains the dominant barrier material in volume terms due to cost efficiency and established heat-seal performance, though coating resins represent the fastest-expanding category as water-based acrylic and polyvinyl alcohol formulations gain traction in premium personal care and pharmaceutical blister alternatives. Pouch formats command disproportionate margin attention as brand owners seek stand-up and flat pouch replacements for multilayer plastic structures in dry food and household product segments.
The EU Packaging and Packaging Waste Regulation alongside FDA food contact substance notifications and China's GB standards for composite packaging materials collectively elevate compliance costs while accelerating substitution away from non-recyclable multilayer plastics. REACH restrictions on per- and polyfluoroalkyl substances directly eliminate certain legacy grease-barrier chemistries, forcing reformulation toward mineral oil-free and fluorine-free alternatives. Stakeholders must monitor evolving extended producer responsibility fee structures and recyclability assessment protocols, as these mechanisms will determine which barrier technologies achieve scale economics in the next investment cycle.
Market Dynamics
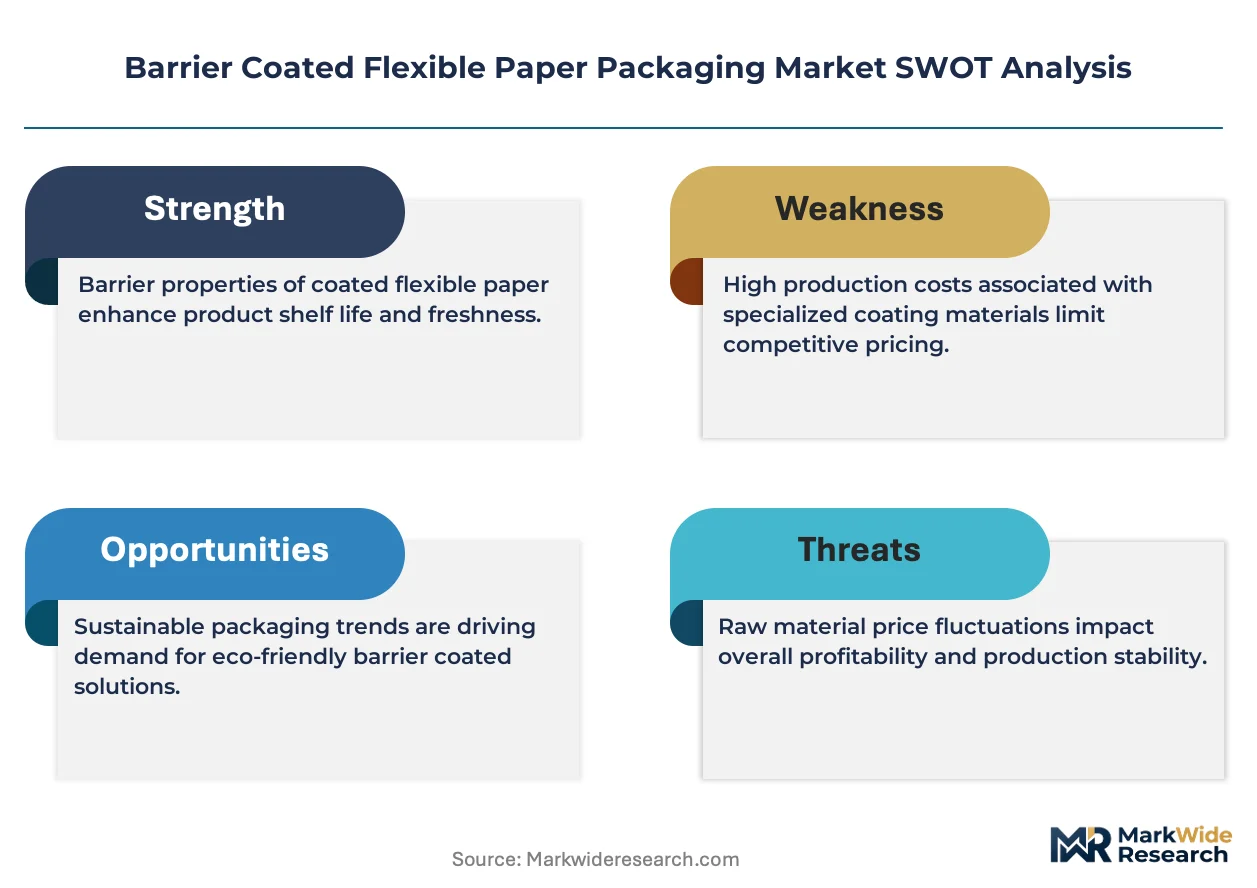
Water-based coating chemistry is displacing solvent-based and fluorinated systems as the dominant innovation vector, with converters investing in dispersion coating lines to meet EU Single-Use Plastics Directive deadlines and brand owner sustainability commitments.
Growth Catalysts
- EU Single-Use Plastics Directive:National transposition deadlines across France, Italy, and Spain mandate fiber-based alternatives for food service items, redirecting converter capex toward barrier paper extrusion capacity.
- Quick-service restaurant chains:Burger King, McDonald's, and independent regional operators in Germany are specifying grease-resistant paper for wrap and fry carton applications, creating pull-through demand for coating substrate suppliers.
- Cellulose nanofibril dispersions:Pilot-scale production at Nordic research institutes is demonstrating oxygen barrier performance competitive with metallized films, positioning the material for pharmaceutical blister pack trials.
Market Restraints
- Polyethylene resin price volatility:Ethylene feedstock fluctuations tied to naphtha cracking economics in Rotterdam and Singapore create margin compression for extrusion coating operators without long-term supply agreements.
- Fluorine-free grease barrier performance gap:Mineral oil and silicone alternatives currently fail hot-grease resistance tests above 80°C, limiting adoption in fried poultry and pastry segments where legacy PFAS-treated papers dominate.
- Recyclability certification bottlenecks:Extended producer responsibility fee structures in Italy and the Netherlands require third-party recyclability assessment, adding 6-12 month validation timelines that delay product launches.
Strategic Opportunities
- India quick-service penetration:Domino's Pizza and regional dosa chain expansion in Bangalore and Mumbai creates demand for moisture-barrier paper for delivery packaging, with local converters lacking specialized coating capacity.
- Pharmaceutical cold-chain:Temperature-sensitive biologics distribution is generating interest in paper-based thermal insulation with vapor barrier properties, displacing expanded polystyrene in European clinical trial logistics.
- Digital printing convergence:Water-based inkjet systems from Heidelberg and EFI are achieving food-contact compliance, enabling short-run customized barrier packaging for craft food brands without plate costs.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise spanning polymer science, paper physics, and food-contact regulatory compliance concentrates in a small cohort of specialists near Darmstadt and Espoo, constraining R&D expansion.
- Heat-seal compatibility validation:Each new water-based coating requires recalibration with existing form-fill-seal equipment at frozen food packagers, creating technical service bottlenecks and trial rejection risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Coated Flexible Paper Packaging Market |
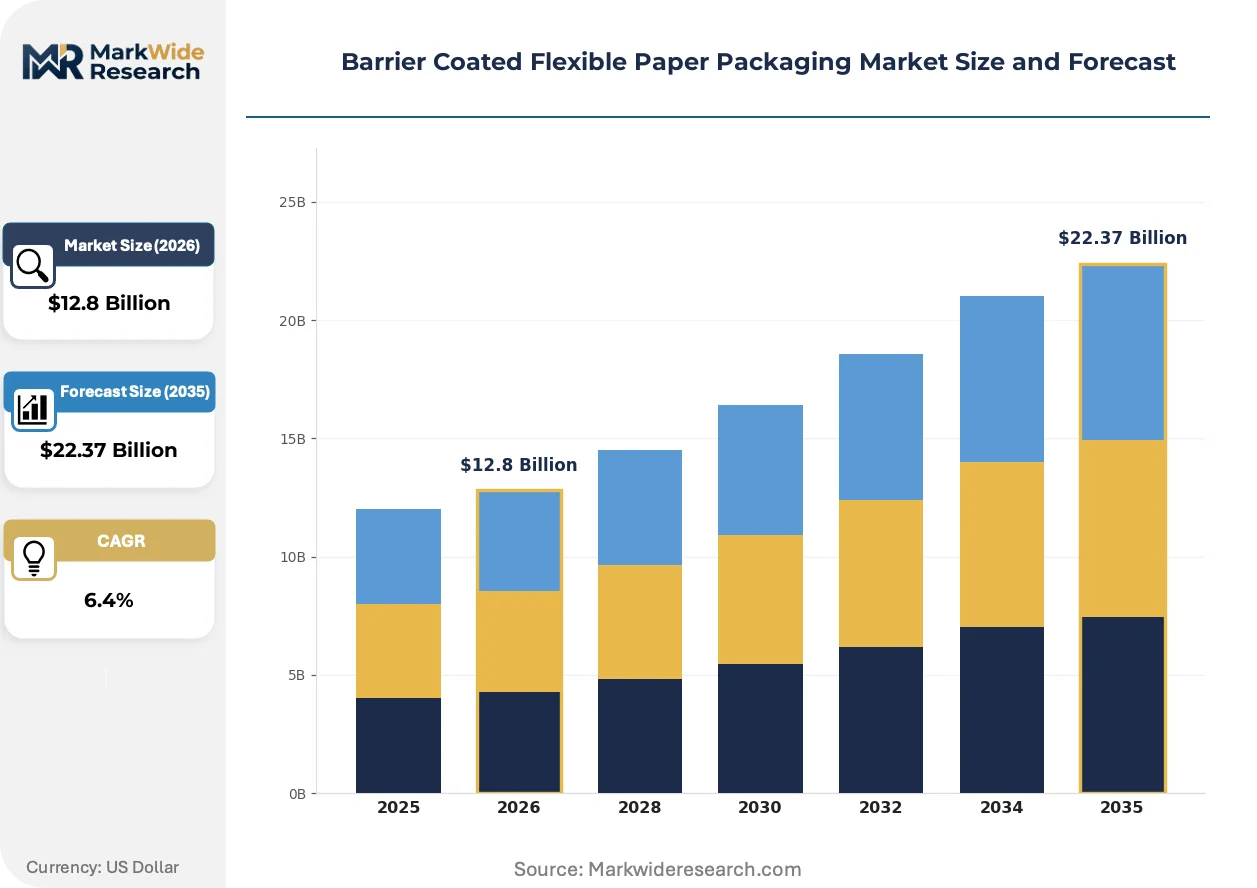
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyester, Others End Use Industry: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Barrier Material: Aluminum Foil, Wax, Coating Resins, Silicone Form: Rolls, Sheets, Pouches, Bags |
| Companies Covered | Stora Enso Oyj, Sappi Limited, Mondi Group, WestRock Company, DS Smith Plc, Amcor Plc, International Paper Company, UPM-Kymmene Corporation, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Coated Flexible Paper Packaging Market Strategic Shifts & Innovations
Coating technology development is splitting along performance-grade lines, with commodity polyethylene extrusion facing pressure from high-performance bio-based alternatives in premium segments.
Water-based acrylic barrier coatings is bifurcating the mid-tier packaging segment. These formulations provide moisture vapor transmission rates below 10 g/m²/day for dried fruit and nut applications. Premium organic brands in Switzerland and Austria are specifying acrylic-coated papers for stand-up pouches, displacing conventional plastic windows. The technology is bifurcating converter investment strategies between high-volume extrusion assets and flexible dispersion coating lines.
REACH restrictions on per- and polyfluoroalkyl substances eliminate legacy grease-barrier chemistries from EU supply chains by 2025. ECHA's restriction proposal forces reformulation toward mineral oil-free alternatives. Frozen food manufacturers in Germany and the Netherlands are accelerating qualification trials for silicone-based barriers, though hot-tack performance remains inferior to fluorinated predecessors.
Brand owner sustainability scorecards are reshaping supplier selection criteria. Unilever and Nestlé procurement teams now weight recyclability certification above unit cost for flexible packaging contracts. This preference shift compresses quoting cycles for unverified converters while rewarding mills with FSC chain-of-custody and Cradle to Cradle certification. The pattern is most visible in Dutch and Belgian retail private-label sourcing.
Barrier Coated Flexible Paper Packaging Market Segmentation
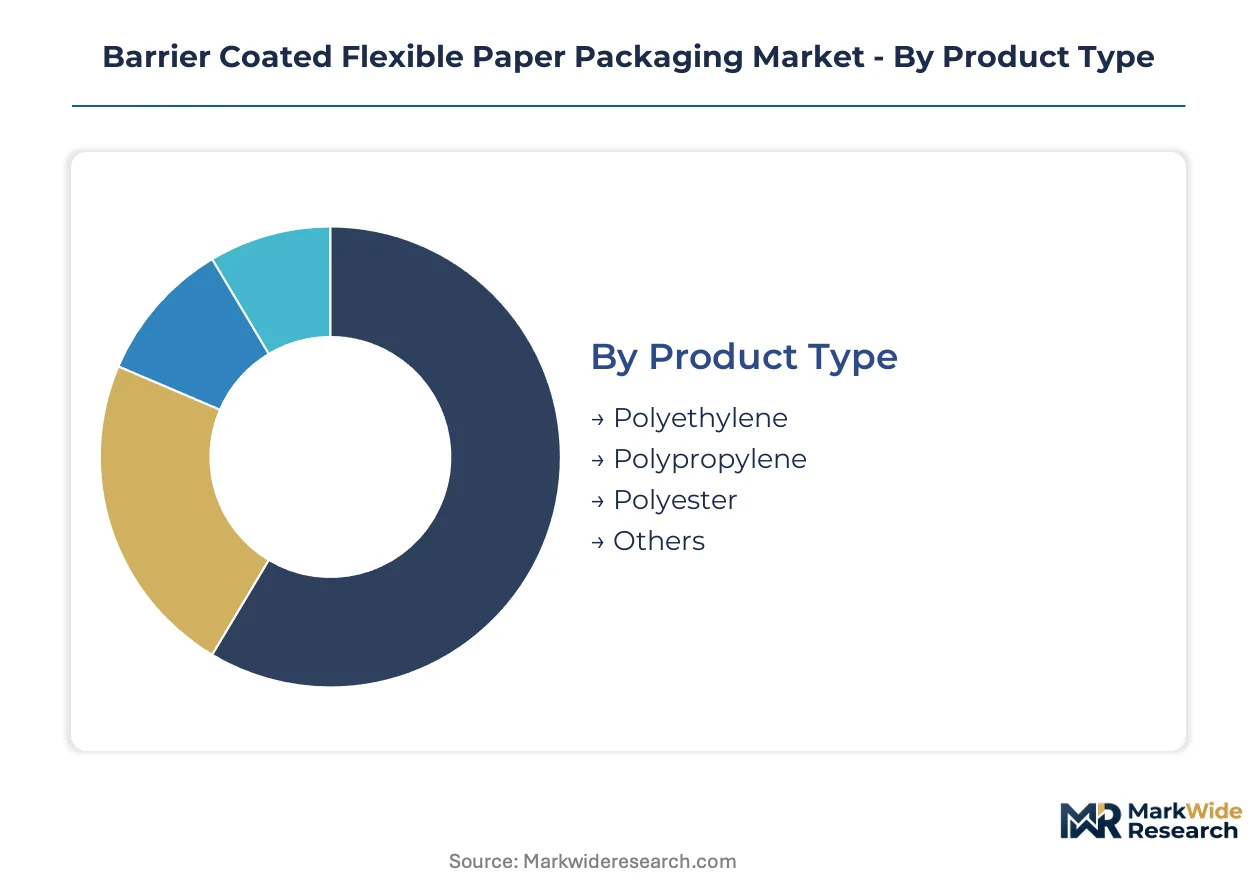
Segmentation in barrier coated flexible paper packaging reveals how coating chemistry, substrate selection, and format specifications align with distinct regulatory pressures and end-use performance requirements. Manufacturers configure production assets around specific barrier material and form combinations to capture margin pools in food service, pharmaceuticals, and personal care.
Product Type:
Domestic demand in Germany and France concentrates on polyethylene and polypropylene extrusion coatings for quick-service restaurant applications, while polyester and specialty resin systems serve export markets requiring higher oxygen barrier specifications for pharmaceutical and premium food segments.
- Polyethylene:Extruded low-density polyethylene dominates frozen food and bakery packaging in volume terms, with converters in the Netherlands and Belgium operating dedicated extrusion lines for McDonald's and Burger King supply contracts. Heat-seal strength and moisture vapor transmission performance meet EU Single-Use Plastics Directive recyclability thresholds without multilayer complexity.
- Polypropylene:Oriented polypropylene coatings provide higher temperature resistance for hot-fill and retort applications, attracting investment from Italian converters serving prepared meal manufacturers in Milan and Bologna where autoclave sterilization requirements exceed polyethylene capabilities.
- Polyester:PET extrusion and dispersion coatings serve pharmaceutical blister pack alternatives and high-barrier confectionery in Swiss and Austrian premium segments.
- Others:Bio-based polyhydroxyalkanoates and cellulose ester coatings from Nordic pilot facilities target Cradle to Cradle certified personal care packaging.
Polyethylene holds the largest share; momentum sits with bio-based alternatives in the Others category as ECHA restrictions accelerate fluorine-free reformulation.
End Use Industry:
Customer procurement patterns split between high-volume food service contracts with standardized specifications and pharmaceutical segments demanding batch-level documentation and cold-chain validation.
- Food & Beverage:Quick-service chains, frozen food manufacturers, and confectionery brands drive specification standards for grease resistance and moisture barrier. German frozen pizza producers in Osnabrück and Frechen specify water-based acrylic coatings for retail private-label lines, while EFSA compliance documentation accompanies each production lot.
- Personal Care:Organic cosmetics brands in Switzerland and natural hair care lines in Austria specify stand-up pouches with mineral oil-free barriers, displacing conventional plastic windows despite 15-20% unit cost premiums.
- Household Products:Detergent pods and cleaning wipe packaging in Dutch retail chains favor recyclable paper pouches over multilayer plastics under extended producer responsibility fee structures.
- Pharmaceuticals:Temperature-sensitive biologics distribution generates demand for vapor-barrier paper insulation in clinical trial logistics, with pilot programs at Nordic research institutes validating cellulose nanofibril oxygen barriers against metallized film benchmarks.
Food & Beverage commands the volume base; Pharmaceuticals shows the steepest expansion trajectory as cold-chain regulations tighten.
Barrier Material:
Material selection trade-offs center on barrier performance, regulatory compliance status, and compatibility with existing paper recycling streams across European collection infrastructure.
- Aluminum Foil:Metallized and aluminum-laminated papers provide oxygen transmission rates below 0.1 cc/m²/day for coffee and pharmaceutical applications, though recyclability certification requires separation at specialized mills in Germany and Sweden.
- Wax:Paraffin and microcrystalline wax coatings retain cost advantages for corrugated box liners and agricultural produce packaging, with Dutch horticultural exporters specifying moisture barriers for flower shipments to Middle Eastern markets.
- Coating Resins:Water-based acrylic and polyvinyl alcohol formulations represent the fastest-expanding category, achieving food-contact compliance through FDA notifications and EFSA evaluations for dried fruit and nut stand-up pouches.
- Silicone:Grease-barrier silicone coatings from German specialty chemical suppliers replace legacy PFAS treatments in pastry and fried poultry segments, though hot-tack performance gaps persist above 80°C.
Coating Resins is gaining share fastest; Aluminum Foil retains premium positioning where barrier performance outweighs recyclability scoring.
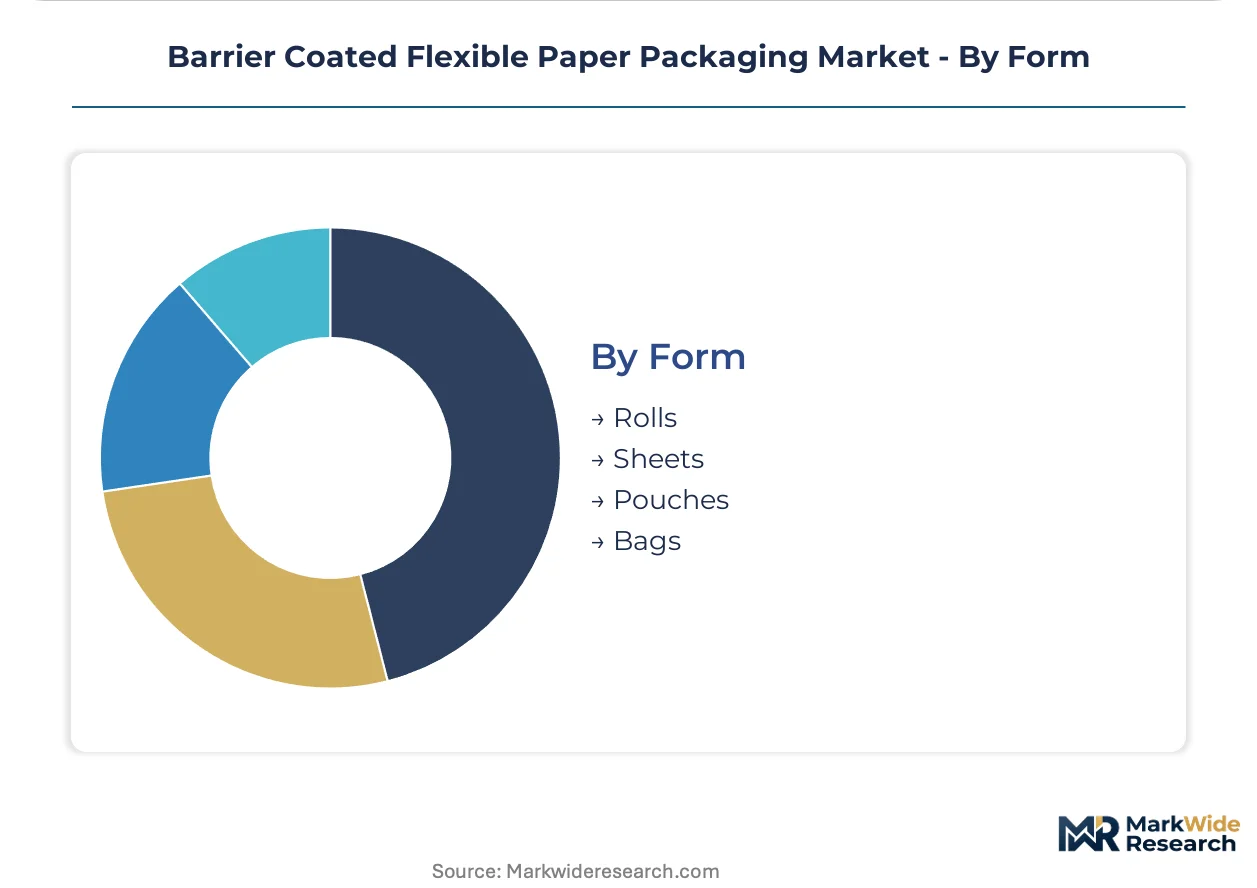
Form:
Format economics reflect capital intensity differences between roll-fed continuous processing and pre-formed pouch and bag operations requiring specialized sealing equipment.
- Rolls:Master rolls for downstream converting dominate volume shipments to flexible packaging printers in Italy and Spain, with standard widths of 800-1600mm optimized for form-fill-seal equipment at frozen food packagers.
- Sheets:Cut-size sheets serve craft bakeries and small-format confectionery operations in France and Belgium where short runs and frequent changeovers favor flatbed die-cutting over roll-fed systems.
- Pouches:Stand-up and flat pouch formats command disproportionate margin attention as brand owners seek replacements for multilayer plastic structures, with Heidelberg and EFI digital printing systems enabling short-run customization without plate costs.
- Bags:Side-gusseted and pinch-bottom bags target dry pet food and household product segments in German and Dutch retail, where FSC chain-of-custody certification influences private-label sourcing decisions.
Rolls maintain the production volume base; Pouches capture the margin expansion as digital printing convergence enables craft brand customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in barrier-coated paper exports to neighboring EU markets, while the Netherlands and Belgium serve as conversion hubs re-exporting finished pouches to UK and Nordic buyers. Import dependence concentrates in specialized coating resins and cellulose nanofibril precursors sourced from Nordic pilot facilities.
Germany
Quick-service restaurant chains and frozen food manufacturers in Osnabrück and Frechen drive specification standards for grease-resistant wraps. ECHA's REACH restrictions on per- and polyfluoroalkyl substances force reformulation toward silicone-based barriers by 2025. The Darmstadt-Rhine-Main corridor hosts coating chemist talent pools serving pilot trials for water-based acrylic systems.
Netherlands
Dutch retail private-label sourcing prioritizes FSC-certified pouches for detergent pods and cleaning wipes under extended producer responsibility fee structures. EFSA compliance documentation accompanies each production lot for export-bound dried fruit applications. Converters in the Randstad operate dedicated extrusion lines for McDonald's and Burger King supply contracts.
France
National transposition deadlines for the EU Single-Use Plastics Directive mandate fiber-based alternatives for food service items by 2025. ANSM food-contact substance evaluations create 6-12 month validation timelines for new coating formulations. Industrial clusters around Lyon and Paris pilot mineral oil-free barriers for pastry segments.
Switzerland
Swissmedic pharmaceutical regulations and premium organic cosmetics brands generate demand for high-barrier stand-up pouches displacing conventional plastic windows. Organic hair care lines specify mineral oil-free barriers despite 15-20% unit cost premiums. Basel-area research institutes validate cellulose nanofibril oxygen barriers against metallized film benchmarks.
India
Domino's Pizza and regional dosa chain expansion in Bangalore and Mumbai creates demand for moisture-barrier paper in delivery packaging. FSSAI food-contact notifications govern import qualification of water-based coating systems. Local converters lack specialized dispersion coating capacity, opening technical partnership opportunities with European equipment suppliers.
Barrier Coated Flexible Paper Packaging Market Key Industry Players
Listed leaders compete with private specialists across coating technology portfolios, with publicly traded Nordic and Anglo-American groups commanding integrated pulp-to-paper operations while family-owned Italian and German converters retain flexible dispersion coating assets. Market structure tilts toward consolidated upstream substrate supply and fragmented downstream converting. Three archetypes dominate: integrated forest products groups with captive coating resin development, specialized flexible packaging converters with quick-service restaurant relationships, and pilot-scale biopolymer research ventures. Competitive moves center on M&A for coating chemist talent and strategic partnerships for digital printing convergence.
Among Nordic integrated groups, Stora Enso Oyj, Huhtamaki Oyj, and UPM-Kymmene Corporation exemplify divergent strategic positions. Stora Enso Oyj represents the biopolymer research archetype through pilot-scale cellulose derivative operations. Huhtamaki Oyj occupies the quick-service converter position with specialized extrusion and dispersion coating lines. UPM-Kymmene Corporation anchors integrated substrate supply with forest-to-reel quality control. These three entities collectively illustrate how geographic clustering near Espoo and Nordic research institutes shapes competitive capability formation.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| Sappi Limited |
| Mondi Group |
| WestRock Company |
| DS Smith Plc |
| Amcor Plc |
| International Paper Company |
| UPM-Kymmene Corporation |
| Huhtamaki Oyj |
| Others |
Cost & Logistics Intelligence
Water-based acrylic coating chemistry replacing solvent-based and fluorinated systems is redrawing supply geography toward Nordic pilot facilities and German specialty chemical clusters while compressing margin premiums for legacy extrusion operators.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the barrier coated flexible paper packaging market. Price differentiation rests on FSC chain-of-custody certification tier and volume scale commitments, with quick-service restaurant chains commanding standard-tier contracts while Swiss organic cosmetics brands absorb premium-tier premiums. Cost compression in the economy tier is intensifying because local Indian converters lack specialized dispersion coating capacity. Frozen food manufacturers in Germany and the Netherlands show the highest price sensitivity due to extended producer responsibility fee structures, whereas pharmaceutical cold-chain logistics buyers prioritize barrier performance over unit cost.
Supply Chain Analysis
Finland and Sweden anchor cellulose nanofibril pilot production for high-oxygen barrier applications, while Germany and the Netherlands concentrate polyethylene extrusion coating capacity for quick-service supply contracts. Raw material dependencies draw from Nordic pulp operations, Rotterdam naphtha cracking economics for ethylene feedstock, and German specialty silicone suppliers for fluorine-free grease barriers. Single-source vulnerability concentrates in coating chemist talent pools near Darmstadt and Espoo. Distribution runs through Dutch and Belgian conversion hubs re-exporting finished pouches to UK and Nordic buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The barrier coated flexible paper packaging market functions as a regulatory-moat story where ECHA REACH restrictions on per- and polyfluoroalkyl substances create switching costs that entrench qualified incumbents against unverified competitors.
For Market Incumbents: Fortify position through captive coating resin development in the Darmstadt-Rhine-Main corridor and accelerated FSC chain-of-custody certification investment. The threat of mineral oil-free barrier performance gaps below 80°C hot-grease resistance demands technical service capacity expansion to manage form-fill-seal equipment recalibration bottlenecks at frozen food packagers. Backward integration into pulp substrate quality control preserves margin against polyethylene resin price volatility. For New Entrants and Emerging Players: Technical service gaps in heat-seal compatibility validation for water-based coatings open white-space opportunities for specialized equipment calibration consultancies. India's quick-service restaurant penetration in Bangalore and Mumbai represents the most penetrable geography given local converter capacity shortages. A partnership-based go-to-market angle with European dispersion coating equipment suppliers accelerates qualification timelines under FSSAI food-contact notification requirements. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors coating chemist talent acquisition over asset-heavy capacity builds. Long-term viability across the next decade hinges on biopolymer barrier research pipelines and digital printing convergence capabilities. The signal to watch as inflection indicator is third-party recyclability assessment certification velocity in Italy and the Netherlands, where extended producer responsibility fee structures are already operational.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Reformulation | ECHA REACH deadlines force silicone-based chemistry qualification trials at German frozen food manufacturers. |
| Cellulose Nanofibril Pilot Scale-Up | Nordic research institutes validate oxygen barrier performance against metallized film pharmaceutical benchmarks. |
| Digital Printing Equipment Partnership | Heidelberg and EFI food-contact compliant inkjet systems enable short-run craft brand customization without plate costs. |
| Extended Producer Responsibility Compliance | Third-party recyclability assessment certification compresses quoting cycles for unverified Italian and Dutch converters. |
| Quick-Service Restaurant Supply Contracts | McDonald's and Burger King specification standards in Germany and the Netherlands anchor volume commitments for extrusion coating operators. |
Research Approach
The analysis maps barrier material categories, end-use industry verticals, and regional production clusters, each validated through coating chemists at Nordic research institutes, procurement managers at quick-service restaurant chains, technical directors at frozen food packagers, and regulatory affairs specialists navigating EFSA and FDA food-contact notifications. Primary interview insights triangulate against secondary validation from ECHA restriction proposals, EU Single-Use Plastics Directive national transposition documents, FSC chain-of-custody certification databases, and customs trade data on coating resin imports. Bottom-up segment sizing and top-down market reconciliation ensure consistency across volume and value outputs.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include coating chemistry tier, substrate specification, barrier performance grade, end-use industry procurement pattern, and regional regulatory cluster. CAGRs derive from trend extrapolation anchored in documented substitution dynamics and capacity expansion announcements. Forecast inputs incorporate EU Packaging and Packaging Waste Regulation implementation timelines and cellulose nanofibril pilot production scale-up trajectories.
Forecasts assume regulatory continuity in EU REACH and FDA food-contact substance notification regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated ECHA restrictions on additional chemistries, polyethylene feedstock price shocks from Rotterdam naphtha cracking disruptions, and recyclability certification protocol changes in extended producer responsibility markets. Recalibration cycles align with material shifts in regulatory enforcement timelines and pilot-scale biopolymer barrier commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
Barrier Bags Market
Packaging Barrier Films
Release Liners Market