
 PCR Plastic Packaging Market | 2026-2036
PCR Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Plastic Packaging Market Outlook
The premium-commodity split in PCR plastic packaging is repositioning around certification grade and supply chain traceability rather than resin price alone. Amcor plc leverages its global recycling partnerships to secure food-grade rPET streams. Mondi plc anchors its European operations around kraft-PCR hybrid structures for e-commerce applications. ALPLA Group dominates bottle-to-bottle closed-loop systems through captive mechanical recycling assets.
PCR plastic packaging comprises containers, films, and rigid formats manufactured with resins derived from post-consumer waste streams, typically requiring decontamination to meet food-contact migration limits below specific threshold concentrations. Its primary purpose is to close material loops while satisfying brand-owner sustainability commitments and regulatory recycled content floors. Bottles lead volume due to established PET collection infrastructure, while films represent the fastest-expanding segment as flexibles producers solve optical and mechanical property degradation. Food packaging commands the deepest margin pools because safety certification barriers limit supplier entry.
The EU Green Deal and REACH frameworks set migration testing protocols that directly determine which PCR streams qualify for food contact. EPA guidelines and state-level extended producer responsibility statutes in the United States shape collection infrastructure investment and post-consumer resin availability. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance thresholds for odor, color, and contaminant levels are tightening unevenly and will fragment supplier qualification requirements.
Market Dynamics
PCR plastic packaging markets are compressing around certification-grade resin scarcity, as EU Green Deal mandates and California's extended producer responsibility laws tighten food-contact migration thresholds faster than decontamination capacity expands.
Growth Catalysts
- EU Green Deal recycled content floors:Packaging converters in Germany and France must source 25% post-consumer content by 2030, pulling rPET and rPP volumes into food-grade streams.
- Mechanical recycling infrastructure clustering:Industrial recycling parks near Cologne and Rotterdam supply bottle-to-bottle closed loops with decontaminated flake.
- Extended producer responsibility statutes:California's SB 54 and New York's pending legislation obligate brand owners to fund collection systems, expanding post-consumer feedstock availability.
Market Restraints
- Food-grade resin supply concentration:EFSA-qualified rPET output clusters in Germany and Austria, creating single-source dependency for converters in Southern Europe.
- Input cost volatility:Post-consumer bale prices swing with oil-indexed virgin PET spreads, compressing blending margins for rigid container producers.
- REACH migration testing bottlenecks:ECHA's evolving contaminant threshold protocols delay food-contact certification timelines by 8-14 months.
Strategic Opportunities
- Underpenetrated flexible packaging:Films and pouches in Italy and Spain remain below 5% recycled content as optical sorting advances unlock multilayer decontamination.
- Chemical recycling convergence:Pyrolysis and glycolysis units are pairing with mechanical lines to produce FDA-compliant rPET for thermoformed trays.
- IRA clean manufacturing tax credits:US converters can offset 30% of recycling equipment capex through federal incentives tied to domestic content sourcing.
Industry Challenges
- Decontamination engineering talent scarcity:Food-contact migration modeling and super-clean process design require specialized chemists in short supply across European converter networks.
- Certification timeline compression:Brand-owner 2025-2027 recycled content deadlines outpace EFSA and FDA no-objection letter issuance, forcing speculative inventory builds.
- Legacy sorting infrastructure retrofit costs:Municipal MRFs require near-infrared and robotics upgrades to supply contaminant-free bales suitable for super-clean mechanical recycling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR Plastic Packaging Market |
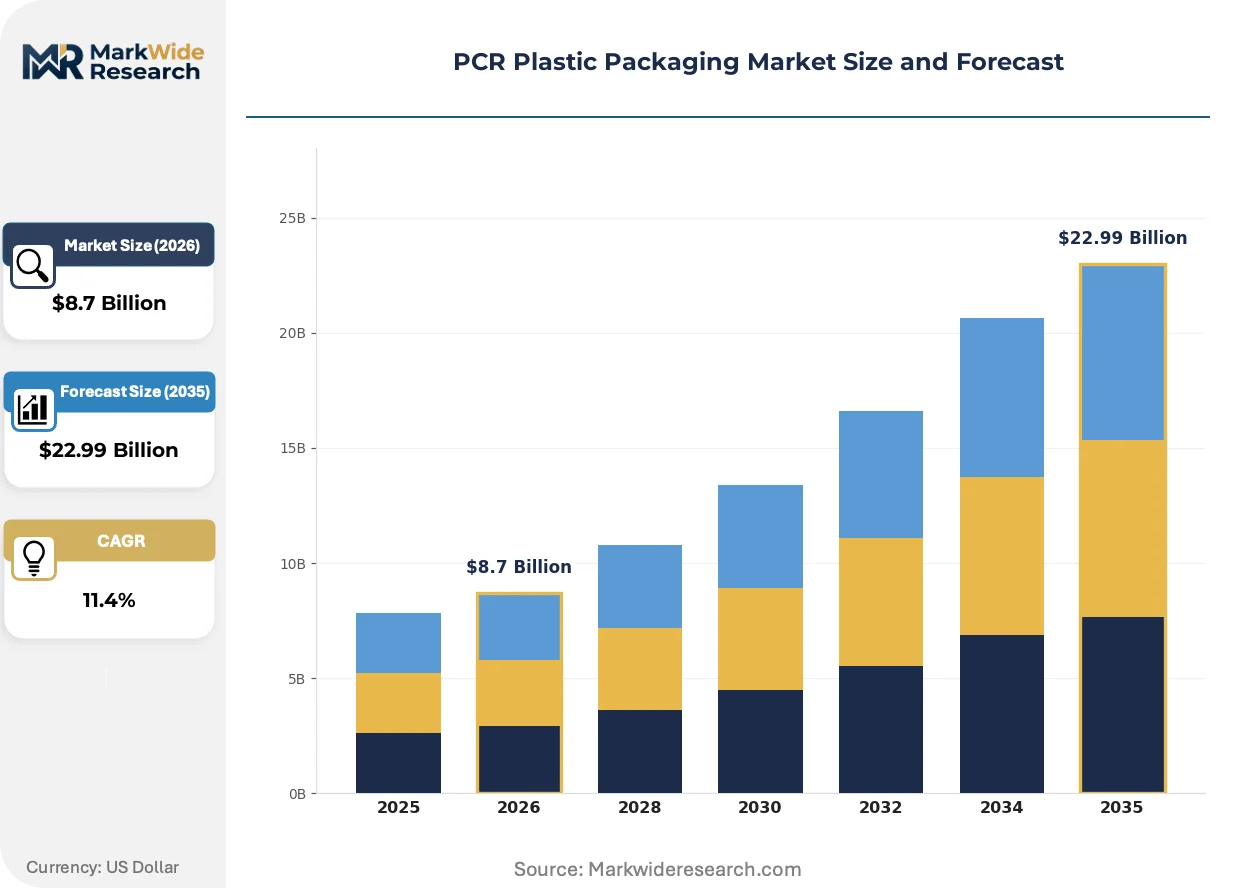
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Bags, Films Application: Food Packaging, Beverage Packaging, Pharmaceutical Packaging, Personal Care Material: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride End User: Food Industry, Healthcare, Cosmetics, Consumer Goods |
| Companies Covered | Amcor plc, Mondi plc, ALPLA Group, Sonoco Products Co., Berry Global, Sealed Air Corporation, Plastipak, BASF SE, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Plastic Packaging Market Strategic Shifts
Advanced decontamination technologies and traceability systems are redrawing competitive boundaries in PCR packaging, shifting advantage from scale players to certified-grade specialists with verified supply chain documentation.
Super-clean mechanical recycling with solid-state polymerization is integrating into European rigid container production, enabling food-contact rPET with sub-0.1 ppm contaminant levels. Dairy and ready-meal brands in Germany and the Netherlands are adopting these resins for thermoformed trays and bottles. The technology is integrating closed-loop supply contracts that lock converters to specific collection zones, compressing spot market participation.
REACH Annex XVII updates and the EU Packaging and Packaging Waste Regulation are mandating harmonized migration testing across member states, eliminating mutual recognition of national certifications. Converters face redundant testing costs when supplying multiple EU markets. Small and mid-sized packaging firms in Poland and Hungary are consolidating testing spend through third-party laboratories to maintain cross-border qualification.
Brand-owner procurement teams are embedding blockchain traceability requirements into resin specifications, replacing annual sustainability reports with real-time mass-balance verification. Major retailers in France and the UK now require QR-linked chain-of-custody documentation for private-label packaging. This behavioral shift concentrates contract awards among recyclers with integrated collection partnerships, sidelining traders of uncertified post-consumer flake.
PCR Plastic Packaging Market Segmentation
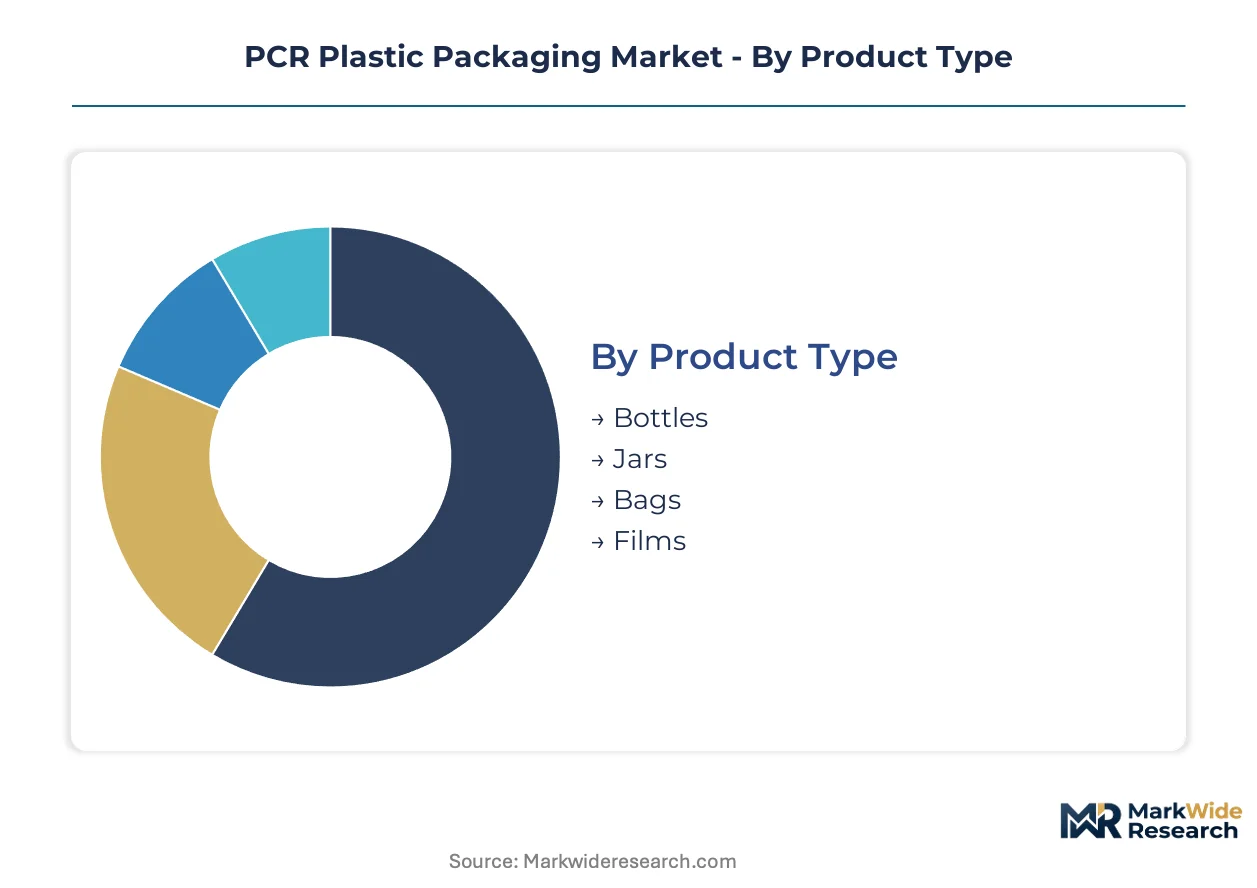
PCR plastic packaging markets fragment across resin chemistry, container geometry, and regulatory compliance tiers. Each segmentation axis determines decontamination intensity, certification pathways, and margin capture differently.
Product Type:
Container geometry dictates mechanical recycling compatibility and super-clean processing requirements.
- Bottles:PET bottle-to-bottle loops dominate volume through established collection infrastructure and EFSA-qualified decontamination. German retailers and Dutch dairy brands anchor demand for food-contact rPET bottles with sub-0.1 ppm contaminant thresholds.
- Films:Multilayer flexibles require advanced optical sorting and delamination before mechanical recycling. Italian pasta brands and Spanish fresh-produce distributors are adopting mono-material PE films with 30% post-consumer content as sorting technology matures.
- Jars:Wide-mouth PP containers serve spreads and condiments with lower migration risk than bottles. French retail private-label programs specify 25% rPP content for sauce jars.
- Bags:LDPE carry bags and pouches rely on post-commercial film streams with limited food-grade qualification. German discount retailers drive specification tightening for recycled content claims.
Mature deployment sits with bottles. Newer deployment is concentrated in films.
Application:
End-use compliance tiers separate premium-certified streams from industrial-grade alternatives.
- Food Packaging:Thermoformed trays and rigid containers demand EFSA no-objection letters and REACH migration testing below specific contaminant thresholds. Ready-meal producers in the Netherlands and dairy processors in Germany command the deepest margin pools due to limited qualified supplier bases.
- Beverage Packaging:Carbonated soft drink bottles and water containers require FDA and EFSA dual certification for export flexibility. Coca-Cola and PepsiCo system suppliers in Austria and Germany control captive recycling assets.
- Pharmaceutical Packaging:Blister packs and prescription bottles face USP Class VI and EP 3.1 migration protocols that exclude most mechanical recycling streams. Swiss and German contract manufacturers specify virgin-equivalent purity.
- Personal Care:Shampoo bottles and cosmetic jars tolerate broader odor and color variation than food contact. Unilever and L'Oréal procurement teams in France and the UK are embedding 50% recycled content targets without food-grade certification burdens.
Food packaging commands the steepest expansion trajectory. Personal care offers the lowest barrier entry.
Material:
Resin polarity and thermal stability determine super-clean processing feasibility and food-contact eligibility.
- Polyethylene:HDPE milk bottles and LDPE films recycle through established mechanical streams with solid-state polymerization for odor removal. German and Austrian converters supply food-grade rHDPE to dairy brands with EFSA-qualified output.
- Polypropylene:Thermoformed trays and caps require advanced decontamination for food contact due to higher migration risk from additives. Italian automotive battery casing recyclers are pivoting to food-grade rPP as collection infrastructure expands.
- Polystyrene:Expanded PS food trays and cups face limited mechanical recycling economics due to density and contamination. German EPS packaging associations are funding chemical recycling pilots for closed-loop food service applications.
- Polyvinyl Chloride:Pharmaceutical blister packs and medical tubing rely on post-industrial scrap with strict traceability. REACH Annex XVII restrictions on plasticizers limit post-consumer PVC streams for sensitive applications.
Polyethylene captures the highest food-contact certification rates. Polypropylene is climbing fastest as super-clean capacity expands.
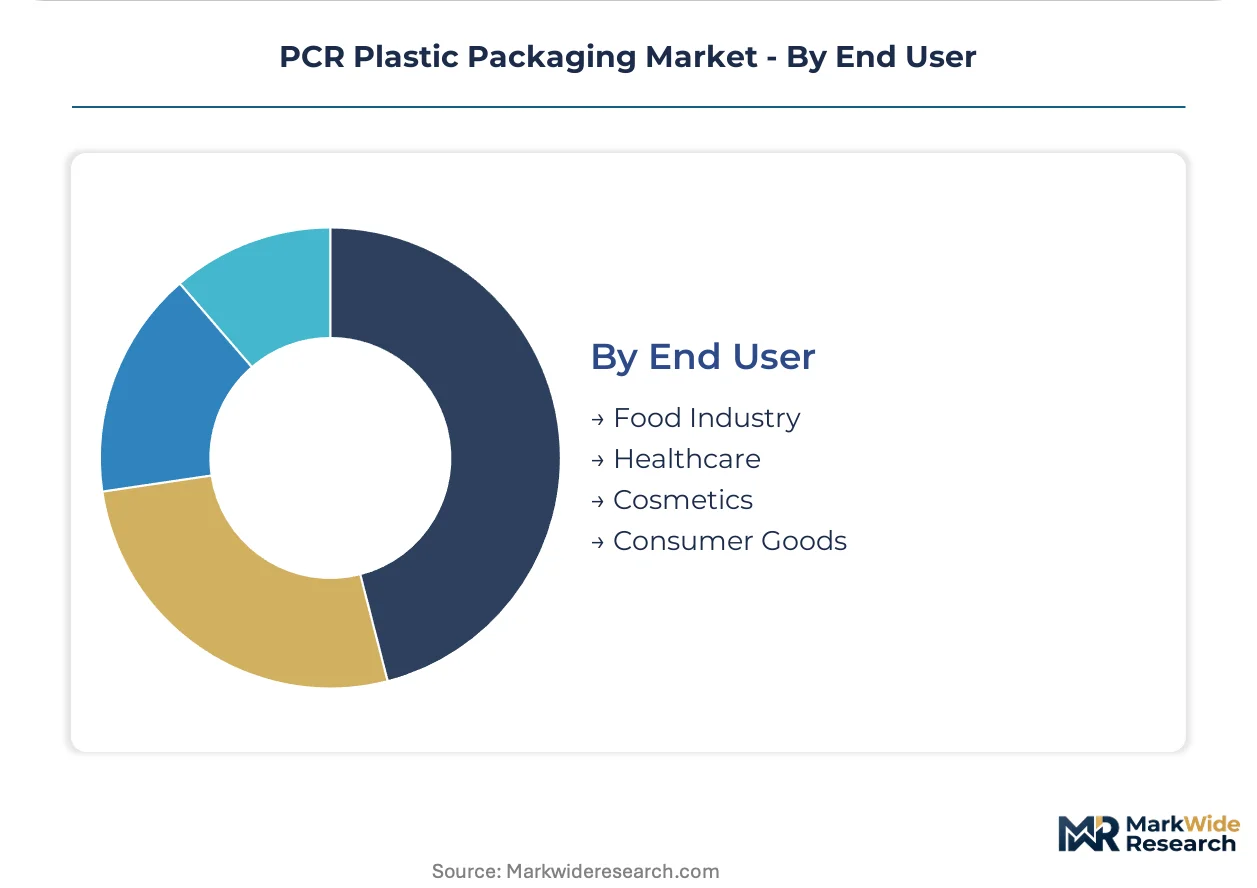
End User:
Procurement sophistication and compliance tolerance vary sharply across buyer categories.
- Food Industry:Retailer private-label specifications and EU Green Deal mandates drive 25-30% recycled content floors. German discounters and French supermarket chains audit mass-balance documentation through blockchain traceability systems.
- Healthcare:Hospital sterilization wrap and pharmaceutical primary packaging require USP and EP compliance that excludes most PCR streams. Swiss medical device manufacturers specify virgin resins with carbon offset certificates instead.
- Cosmetics:Premium brand sustainability marketing tolerates aesthetic variation in PCR content. L'Oréal and Estée Lauder European operations are sourcing 30% rPET for serum bottles without food-grade certification.
- Consumer Goods:Detergent bottles and cleaning product containers face lower migration scrutiny than food contact. Procter & Gamble European plants blend 50% rHDPE for laundry packaging with relaxed odor specifications.
Food industry procurement sets the strictest qualification standards. Consumer goods offers the broadest PCR adoption flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cologne-Düsseldorf corridor anchors European PCR plastic packaging activity through its dense clustering of mechanical recycling parks and EFSA-qualified decontamination facilities. This industrial concentration shapes procurement patterns across adjacent markets.
Germany
German dairy processors and discount retailers drive food-grade rPET demand through private-label specifications requiring 25-30% post-consumer content. The EU Green Deal mandates tighten compliance timelines for converters operating near Cologne and Hamburg. Super-clean mechanical recycling facilities in North Rhine-Westphalia supply bottle-to-bottle closed loops with sub-0.1 ppm contaminant thresholds.
United States
California's SB 54 extended producer responsibility statute obligates brand owners to fund collection infrastructure, expanding post-consumer feedstock availability for West Coast converters. EPA guidelines shape migration testing protocols that determine food-contact eligibility. Mechanical recycling clusters in the Great Lakes region supply rigid container producers with decontaminated flake for beverage applications.
France
French supermarket chains audit mass-balance documentation through blockchain traceability systems, concentrating contract awards among recyclers with integrated collection partnerships. REACH Annex XVII updates mandate harmonized migration testing across EU member states. Packaging converters near Lyon and Paris face redundant certification costs when supplying multiple European markets.
Netherlands
Dutch ready-meal producers command premium pricing for thermoformed trays due to limited qualified supplier bases meeting EFSA no-objection requirements. The Port of Rotterdam serves as a hub for imported post-consumer bale sorting and preprocessing. Recycling infrastructure near the Belgian border supplies mono-material PE films with 30% recycled content to fresh-produce distributors.
Italy
Italian pasta brands and food processors are adopting mono-material PE films as optical sorting advances unlock multilayer decontamination capabilities. National packaging waste regulations align with EU Packaging and Packaging Waste Regulation thresholds. Converters in the Emilia-Romagna region are consolidating testing spend through third-party laboratories to maintain cross-border qualification.
PCR Plastic Packaging Market Competitive Environment
Capital-heavy producers with captive recycling assets compete with asset-light converters dependent on spot resin markets, creating a bifurcated structure around certification grade rather than scale alone. The market concentrates around three strategic archetypes: integrated recyclers controlling collection-to-resin verticals, hybrid packaging firms blending mechanical and chemical recycling streams, and specialty converters focused on single-resin formats. Dominant competitive moves include backward integration into collection infrastructure and strategic partnerships with brand owners for long-term offtake agreements.
Within the integrated recycler tier, Amcor plc and ALPLA Group exemplify asset-heavy positioning through controlled recycling partnerships and bottle-to-bottle closed-loop systems. Mondi plc occupies a distinct position anchoring European operations around hybrid material structures. These three entities represent contrasting approaches to securing food-grade resin streams amid tightening regulatory thresholds.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi plc |
| ALPLA Group |
| Sonoco Products Co. |
| Berry Global |
| Sealed Air Corporation |
| Plastipak |
| BASF SE |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
Decontamination engineering talent scarcity in North Rhine-Westphalia and Upper Austria widens pricing spreads between EFSA-certified food-grade rPET and industrial-grade recycled streams. Labor-cost differentials for super-clean process chemists compress blending margins for converters dependent on spot resin markets versus those with captive technical teams.
Pricing Analysis
Value-based pricing anchored to EFSA no-objection letter throughput dominates food-contact rPET contracts. Three-tier pricing structure across premium food-grade, standard industrial-grade, and economy non-certified levels separates converters by migration testing compliance. Cost compression in standard-grade rHDPE intensifies because oil-indexed virgin PET spreads compress blending economics. Brand-owner procurement teams show lowest price sensitivity for dairy and ready-meal applications where qualified supplier bases remain thin.
Supply Chain Analysis
EFSA and FDA food-contact qualification gating concentrates supply among German, Austrian, and Dutch converters with verified decontamination assets. Post-consumer bale supply draws from municipal MRFs in Belgium, France, and Italy with divergent near-infrared sorting capabilities. Single-source vulnerability runs through ECHA-qualified super-clean mechanical recycling facilities near Cologne and Rotterdam. Distribution runs through long-term offtake contracts locking converters to specific collection zones rather than spot flake markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA-qualified decontamination capacity expansion lags EU Green Deal recycled content mandates, propping pricing power for certified-grade resin holders. Supply constraints favor asset-heavy positioning over spot-market dependency.
For Market Incumbents: Acquire captive mechanical recycling assets with solid-state polymerization capabilities to secure food-grade rPET streams against chemical recycling entrants. Backward integration into collection infrastructure near Rotterdam and Hamburg defends margin position against bale price volatility from extended producer responsibility fund flows. For New Entrants and Emerging Players: Begin with mono-material PE films for Italian pasta and Spanish fresh-produce distributors where optical sorting advances unlock sub-5% recycled content penetration. Target personal care applications for Unilever and L'Oréal procurement teams with relaxed odor specifications versus food-contact certification barriers. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid packaging firms blending mechanical and chemical recycling streams given pyrolysis-glycolysis convergence for FDA-compliant rPET. Long-term viability favors converters with blockchain traceability systems embedded in retailer private-label contracts. Watch ECHA contaminant threshold protocol updates as inflection indicators for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Secures post-consumer bale supply for German dairy processors facing EU Green Deal mandates. |
| Super-Clean Mechanical Recycling Capacity Expansion | Enables EFSA-qualified rPET output for Dutch ready-meal producers with sub-0.1 ppm thresholds. |
| Chemical Recycling Convergence Partnership | Pairs pyrolysis units with mechanical lines for FDA-compliant thermoformed tray production. |
| Blockchain Traceability System Deployment | Satisfies French supermarket chain mass-balance documentation requirements for private-label awards. |
| Third-Party Laboratory Testing Consolidation | Maintains cross-border REACH qualification for Polish and Hungarian packaging converters. |
Study Parameters
Independent corroboration across packaging converter executives, recycling plant managers, brand-owner procurement leads, and EFSA regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from EU Packaging and Packaging Waste Regulation filings, ECHA migration testing protocols, SEC 10-K disclosures by listed packaging firms, and extended producer responsibility statute texts from California and New York. Bottom-up resin volume estimates triangulate with top-down market sizing across certification-grade tiers.
Comparable-period anchoring to historical recycled content adoption curves shapes the projection horizon across the analysis window. Segmentation dimensions modeled include container geometry, resin chemistry, regulatory compliance tier, and end-use application intensity. CAGRs derive from decontamination capacity buildout trajectories and brand-owner recycled content deadline clustering. Forecast inputs incorporate EFSA no-objection letter issuance rates and municipal MRF retrofit investment pipelines.
Underlying measurement precision varies by segment; food-contact rPET carries tighter precision than pharmaceutical packaging where USP Class VI exclusions limit mechanical recycling participation. Forecasts reflect assumptions about ECHA protocol evolution and IRA clean manufacturing tax credit utilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
Vietnam Plastic Bottles Market