
 Global Air Bubble Film Machines Market | 2026-2036
Global Air Bubble Film Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Bubble Film Machines Market Analysis
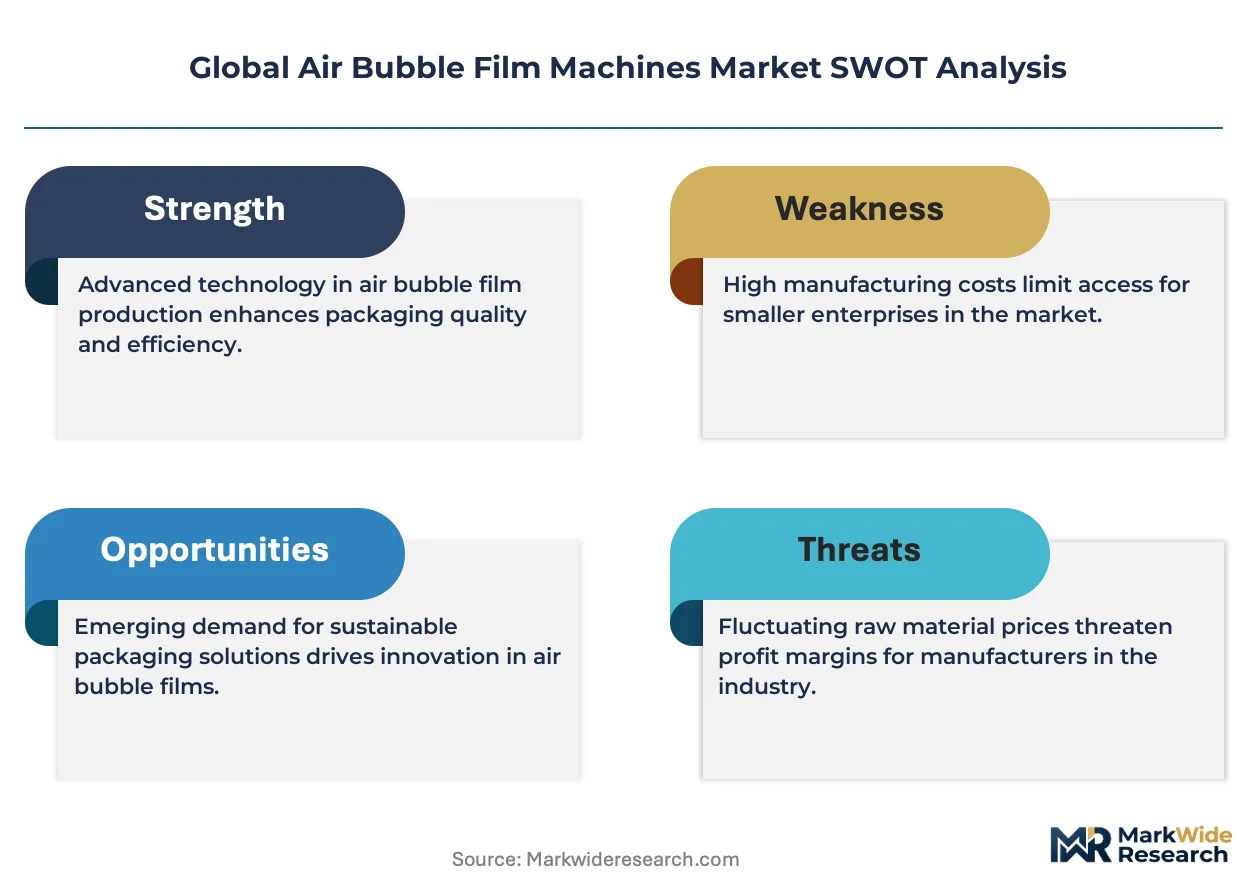
Multi-layer co-extrusion specification is rotating toward the center of buyer specifications as converters seek downgauging without performance loss. Sealed Air Corporation leverages its polymer science heritage to sustain premium positioning in high-barrier bubble configurations. Rui'an Hualiang Machinery Co., Ltd. anchors the mid-market segment with standardized single-layer lines priced for regional Asian converters. Pregis LLC differentiates through in-house resin formulation and captive testing protocols that validate drop-performance claims for e-commerce shippers.
Air bubble film machines extrude polyethylene resin through circular dies to form sealed air-cell structures used for impact protection and surface cushioning during transit; blown film extrusion remains the dominant process architecture, though co-extrusion lines now integrate EVOH or nylon sub-layers for gas-barrier applications in sensitive electronics packaging. Multi-layer equipment commands the widest margin pool as converters trade up from single-layer configurations to meet brand-owner sustainability pledges. E-commerce end users represent the fastest-growing demand channel, with logistics operators specifying machines capable of on-demand bubble production at fulfillment nodes rather than centralized film procurement.
FDA indirect food-contact rules govern bubble film destined for agricultural and fresh-produce applications in the United States, while REACH and RoHS constrain phthalate-based additives across European supply chains. China's SAMR enforces GB standards for mechanical safety and electromagnetic compatibility on imported extrusion equipment, creating a compliance threshold that filters out uncertified machinery vendors. Stakeholders must monitor how extended producer responsibility frameworks in Germany and France reshape resin specifications and machine retrofit requirements before committing to platform investments.
Market Dynamics
Multi-layer co-extrusion technology is compressing equipment replacement cycles as converters abandon single-layer lines to meet downgauging mandates from brand owners and EPR frameworks.
Growth Catalysts
- E-commerce logistics automation:Fulfillment operators are installing on-demand bubble production lines at regional distribution nodes to eliminate inbound film freight costs and packaging waste.
- REACH compliance deadlines:European converters face mandatory phase-outs of phthalate-based additives, forcing equipment upgrades to lines compatible with bio-based and recycled-content resins.
- China's dual carbon goals:Provincial energy intensity targets are accelerating scrappage of legacy extruders in favor of servo-driven, energy-recovery machines in Zhejiang and Guangdong manufacturing clusters.
Market Restraints
- Polyethylene resin price volatility:Naphtha-linked feedstock costs swing unpredictably, compressing converter margins and deferring capex commitments for new extrusion lines.
- Supply concentration in German precision components:Gearbox and die-head suppliers cluster in Baden-Württemberg, creating single-source vulnerability for Asian machine builders.
- Mechanical limitations of recycled-content extrusion:Post-consumer PE streams exhibit inconsistent melt-flow indices, causing bubble-cell rupture rates that degrade protective performance below e-commerce shipper tolerance thresholds.
Strategic Opportunities
- India's packaging automation lag:Domestic e-commerce penetration remains below China and US levels, creating first-mover advantage for equipment vendors establishing localized service networks.
- Agricultural fresh-produce packaging:FDA-compliant bubble films for berry and grape transit protection represent an underserved application with premium pricing power.
- EU Green Deal capital subsidies:Member-state recovery funds are covering 30-50% of equipment costs for recyclate-compatible extrusion lines, lowering payback periods for converter investments.
Industry Challenges
- Multi-layer die engineering expertise:Co-extrusion head design requires polymer rheology specialists that machine builders struggle to recruit and retain against chemical industry compensation benchmarks.
- SAMR certification timelines:China's GB standard testing protocols for imported extrusion equipment extend lead times by 4-6 months, freezing capital deployment for non-domestic vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Bubble Film Machines Market |
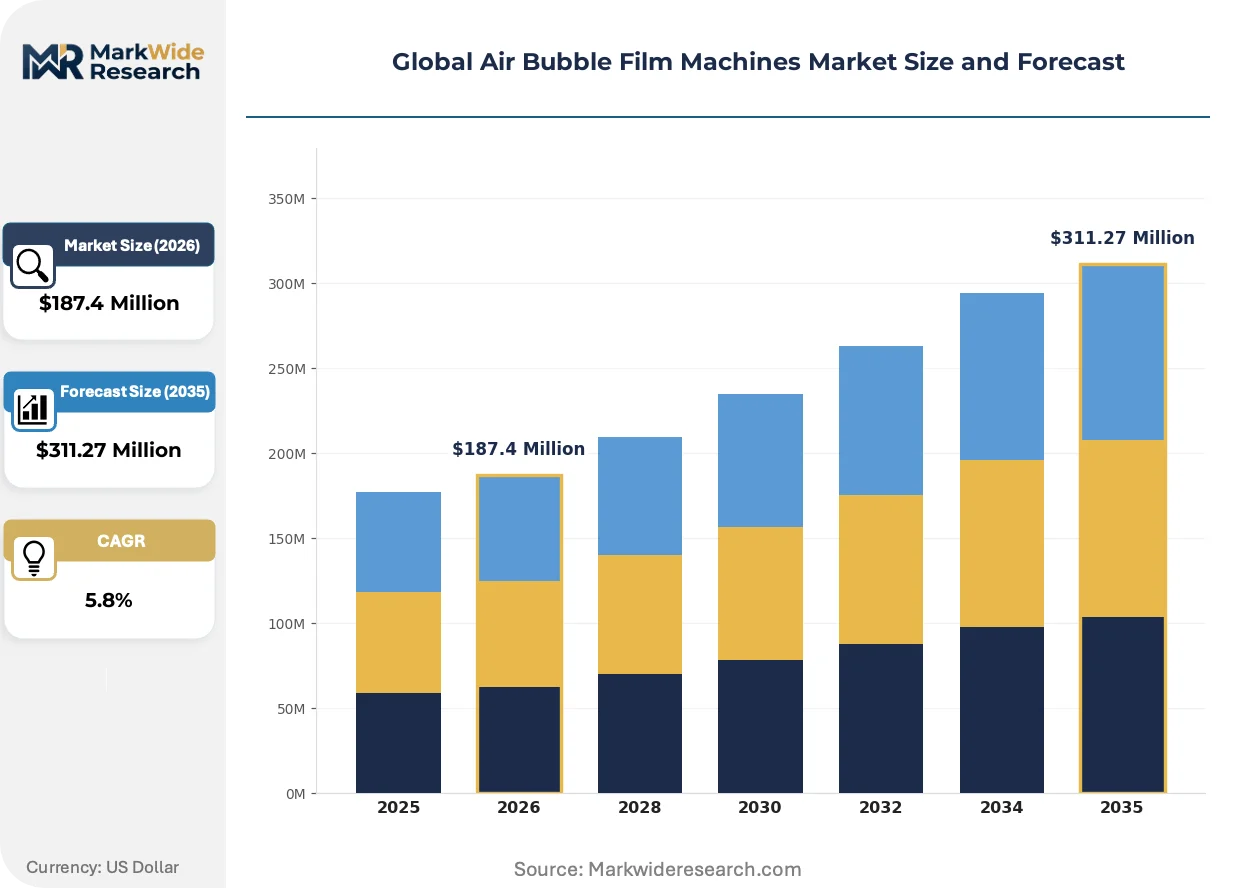
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Layer, Multi-Layer, Customizable, Heavy-Duty Application: Packaging, Protective Wrapping, Shipping, Void Fill End User: Manufacturing, E-Commerce, Retail, Logistics Technology: Blown Film Extrusion, Casting, Recycling, Co-Extrusion |
| Companies Covered | Sealed Air Corporation, Pregis LLC, Storopack Hans Reichenecker GmbH, Automated Packaging Systems, Inc., Smurfit Kappa Group, Rui'an Hualiang Machinery Co., Ltd., Dongguan Tepai Machinery Co., Ltd., Guangdong Zhongrui Plastic Machinery Technology Co.,Ltd., Zhejiang Dingye Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Bubble Film Machines Market Emerging Trajectories
Equipment architecture is pivoting from centralized film production toward distributed, on-demand manufacturing at logistics nodes, enabled by compact extrusion footprints and resin-feed automation.
Co-extrusion technology is fragmenting the installed base of bubble film machines as converters trade up from single-layer configurations. E-commerce fulfillment operators are adopting these lines fastest, driven by shipper sustainability scorecards that penalize virgin resin content. The technology is fragmenting vendor market positions by creating separate margin pools for barrier-film specialists versus commodity single-layer suppliers.
REACH Article 33 disclosure requirements are tightening supply chain traceability for substances of very high concern in packaging films. Converter customers now demand batch-level resin certificates, forcing machine builders to integrate barcode tracking and automated documentation modules. European electronics packaging segments are responding fastest, specifying EVOH sub-layer configurations that satisfy both barrier and compliance requirements.
Shippers are consolidating bubble film procurement from multiple regional converters toward single-source, long-term equipment lease arrangements. Third-party logistics providers are displacing traditional film distributors by offering packaging-as-a-service models that bundle machine installation, resin supply, and maintenance. This concentration is most visible in Germany and the United States, where DHL and FedEx ground operations have piloted captive extrusion at sortation hubs.
Global Air Bubble Film Machines Market Segmentation
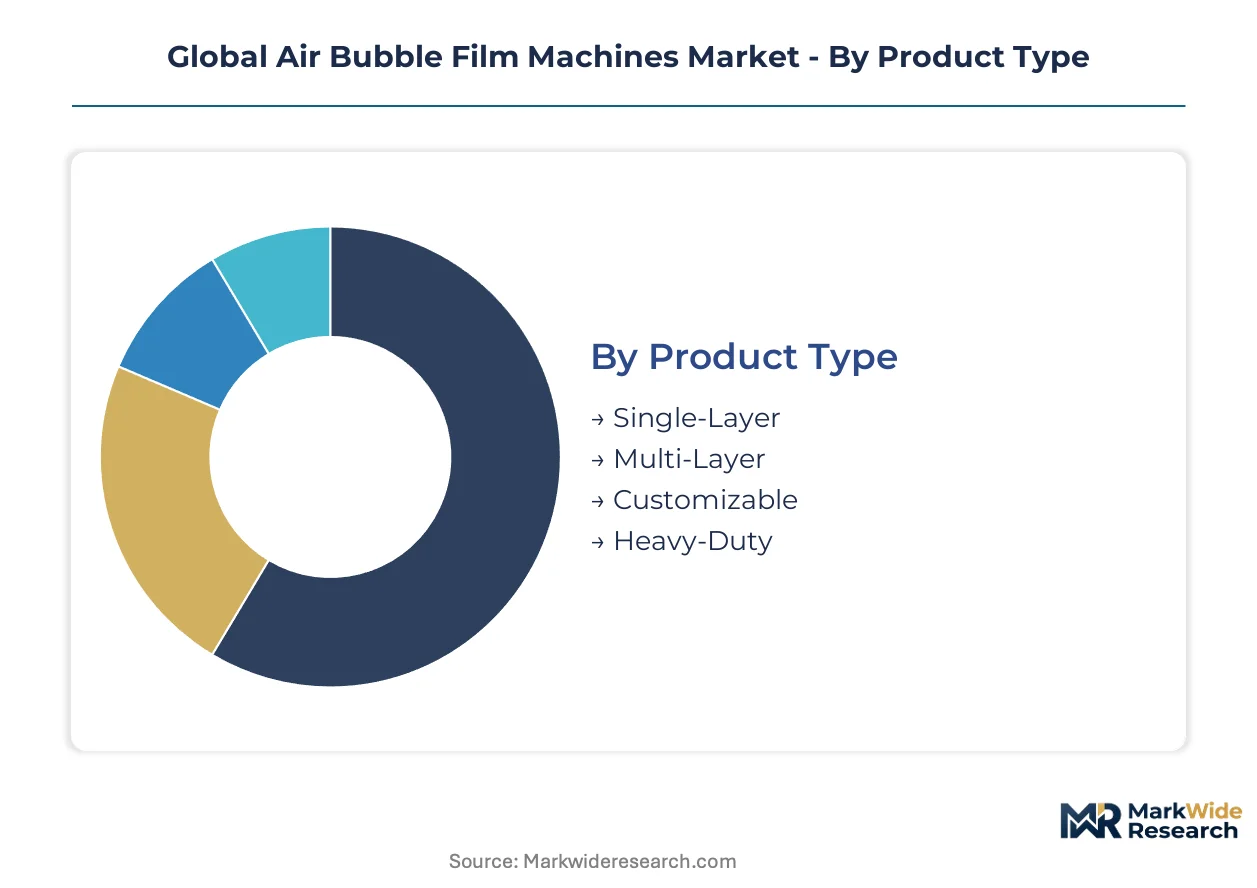
Air bubble film machine segmentation reveals how margin pools concentrate around co-extrusion capabilities and e-commerce fulfillment specifications. Equipment buyers now prioritize lines that reconcile downgauging mandates with protective performance validation.
Product Type:
Margin pools concentrate in multi-layer configurations where barrier-film premiums offset higher capital intensity and polymer science integration costs.
- Multi-Layer:Co-extrusion architectures integrate EVOH or nylon sub-layers for gas-barrier applications in sensitive electronics packaging. Demand clusters with German and Chinese converters serving brand-owner sustainability pledges that mandate recyclate compatibility without performance degradation.
- Single-Layer:Standardized blown-film lines dominate entry-level procurement for regional Asian packaging converters. Price compression is most severe here as Rui'an Hualiang Machinery and comparable vendors compete on standardized specifications for commodity void-fill applications.
- Customizable:Modular die-head configurations allow rapid specification changes between barrier and non-barrier film production.
- Heavy-Duty:Reinforced extruder screws and cooling systems handle high-melt-strength resins for industrial cushioning applications.
The dominant share belongs to Single-Layer equipment, while Multi-Layer configurations are gaining share fastest as REACH compliance deadlines force resin formulation upgrades.
Application:
Application segmentation tracks how fulfillment automation is redistributing equipment placement from centralized film mills toward distributed logistics nodes.
- Void Fill:On-demand bubble production at e-commerce sortation hubs eliminates inbound film freight costs and packaging waste accumulation. DHL and FedEx ground operations in Germany and the United States have piloted captive extrusion installations that displace traditional distributor relationships.
- Packaging:Primary protective film for consumer goods transit commands volume leadership but faces margin erosion from virgin resin content penalties in shipper sustainability scorecards.
- Protective Wrapping:Surface cushioning for furniture and electronics requires controlled cell geometry validated through drop-testing protocols.
- Shipping:Bulk film procurement for third-party logistics providers concentrates in long-term equipment lease arrangements with resin supply bundling.
Packaging retains the largest installed base, though Void Fill applications are climbing the fastest as logistics operators internalize bubble production.
End User:
End-user segmentation exposes how procurement authority is shifting from converters toward logistics operators with captive sustainability mandates.
- E-Commerce:Fulfillment operators specify machines capable of on-demand bubble production at regional distribution nodes rather than centralized film procurement. China's JD.com and Alibaba logistics arms are driving servo-driven, energy-recovery machine upgrades in Zhejiang manufacturing clusters to meet provincial dual carbon targets.
- Logistics:Third-party packaging-as-a-service providers displace traditional film distributors by bundling machine installation, resin supply, and maintenance under long-term contracts.
- Manufacturing:Industrial captive film production for component transit protection favors heavy-duty extrusion lines with high uptime requirements.
- Retail:In-store fulfillment operations for omnichannel retailers generate demand for compact extrusion footprints with resin-feed automation.
Manufacturing holds the deepest historical penetration, yet E-Commerce logistics operators are expanding most quickly as procurement authority consolidates.
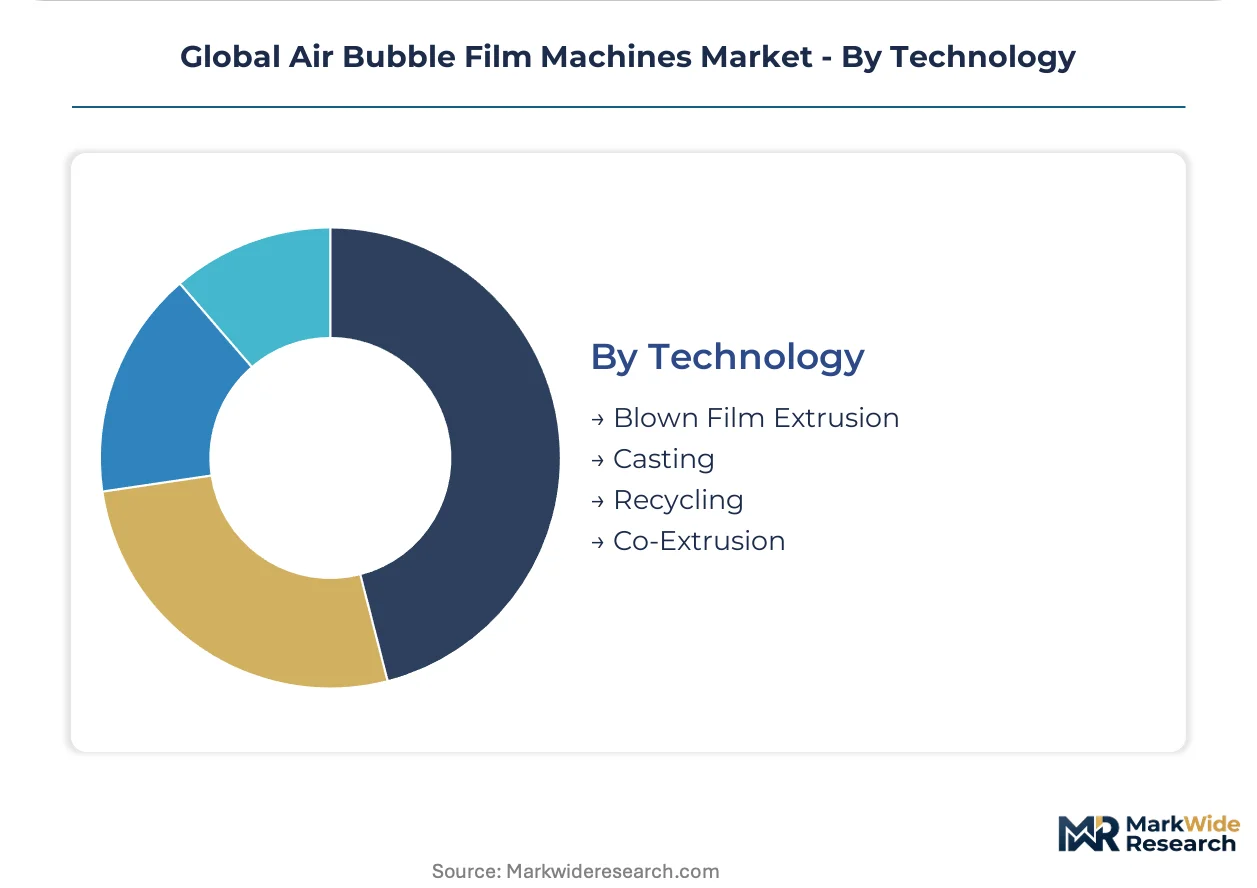
Technology:
Technology segmentation maps how process architecture determines compliance eligibility for regulated resin streams and barrier specifications.
- Co-Extrusion:Multi-layer die heads enable EVOH sub-layer integration for electronics packaging segments responding to REACH Article 33 disclosure requirements. European converters now demand batch-level resin certificates with barcode tracking integration.
- Recycling:Post-consumer PE stream processing requires specialized screw designs and melt-filtration systems to manage inconsistent melt-flow indices that cause bubble-cell rupture.
- Blown Film Extrusion:Circular die configurations remain the dominant process architecture for commodity air-cell formation.
- Casting:Flat-die extrusion produces uniform film gauges for optical-grade protective applications with minimal haze requirements.
Blown Film Extrusion maintains the broadest installed base, while Co-Extrusion lines show the steepest expansion trajectory as barrier specifications proliferate across electronics and fresh-produce segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in Germany's precision engineering belt and China's coastal manufacturing provinces, with demand intensity scaling alongside e-commerce fulfillment infrastructure investments in each geography.
United States
FDA indirect food-contact rules govern bubble film for agricultural applications, while logistics operators pilot captive extrusion at sortation hubs. DHL and FedEx ground operations in the Midwest and Southeast have installed on-demand production lines to eliminate inbound freight costs. The FDA compliance threshold filters out uncertified machinery vendors serving fresh-produce packaging segments.
Germany
REACH Article 33 disclosure requirements tighten supply chain traceability for substances of very high concern in packaging films. Extended producer responsibility frameworks in Germany reshape resin specifications and machine retrofit requirements. Baden-Württemberg hosts gearbox and die-head suppliers that create single-source vulnerability for Asian machine builders seeking precision components.
China
Provincial energy intensity targets accelerate scrappage of legacy extruders in favor of servo-driven machines. SAMR enforces GB standards for mechanical safety and electromagnetic compatibility on imported extrusion equipment, extending lead times by 4-6 months. Zhejiang and Guangdong manufacturing clusters drive equipment upgrades as JD.com and Alibaba logistics arms expand fulfillment networks.
India
Domestic e-commerce penetration remains below China and US levels, creating first-mover advantage for equipment vendors establishing localized service networks. The country's packaging automation lag attracts vendors targeting mid-market converters with standardized single-layer lines. Maharashtra and Gujarat industrial corridors generate demand for entry-level extrusion equipment as regional logistics infrastructure matures.
Japan
METI industrial policy prioritizes energy efficiency in manufacturing equipment, aligning with global converter sustainability mandates. Electronics packaging segments specify EVOH sub-layer configurations that satisfy both barrier performance and compliance requirements. The Kanto region maintains precision machinery expertise that supports high-barrier film equipment development for sensitive component protection.
Global Air Bubble Film Machines Market Vendor Landscape
Concentration sits with diversified packaging conglomerates and specialized machinery fabricators competing across distinct technology tiers. The vendor base spans polymer science heritage players, standardized equipment manufacturers, and regional Asian fabricators. Three archetypes dominate: barrier-film specialists leveraging co-extrusion expertise, mid-market suppliers competing on standardized specifications, and logistics-integrated packaging-as-a-service providers. Competitive moves center on strategic partnerships for resin supply security and geographic expansion into underpenetrated fulfillment markets.
Among US-based packaging technology providers, Sealed Air Corporation and Pregis LLC occupy positions at the premium tier where polymer science integration commands pricing power. Storopack Hans Reichenecker GmbH represents German precision engineering heritage in protective packaging systems. Chinese fabricators including Rui'an Hualiang Machinery Co., Ltd. and Zhejiang Dingye Machinery Co., Ltd. anchor the mid-market segment with standardized equipment configurations. These named entities exemplify how geographic origin and corporate structure map to distinct competitive positioning archetypes rather than convergent strategies.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| Storopack Hans Reichenecker GmbH |
| Automated Packaging Systems, Inc. |
| Smurfit Kappa Group |
| Rui'an Hualiang Machinery Co., Ltd. |
| Dongguan Tepai Machinery Co., Ltd. |
| Guangdong Zhongrui Plastic Machinery Technology Co.,Ltd. |
| Zhejiang Dingye Machinery Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term equipment lease arrangements with bundled resin supply lock in both supply access and price visibility for e-commerce logistics operators, insulating converters from polyethylene resin volatility while binding them to single-source dependencies. These contracts concentrate procurement authority with DHL and FedEx ground operations in Germany and the United States, compressing margin flexibility for mid-market Asian fabricators.
Pricing Analysis
REACH Article 33 disclosure requirements dictate the pricing tier structure across European supply chains, forcing converters to absorb certification costs for batch-level resin traceability. Three-tier pricing structure across premium, standard, and economy levels separates EVOH-integrated barrier lines from commodity single-layer equipment, with customization premiums widening as polymer rheology expertise scarcity intensifies. Cost compression in the standardized single-layer segment runs through Rui'an Hualiang Machinery and comparable Chinese vendors competing on identical specifications. E-commerce fulfillment operators demonstrate lowest price sensitivity due to sustainability scorecard mandates, while regional Asian converters exhibit highest sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Inventory buffers for precision die-head components stretch lead times by 4-6 months as gearbox suppliers cluster in Baden-Württemberg, Germany. Manufacturing concentration centers on Germany's precision engineering belt and China's Zhejiang and Guangdong provinces, with servo-drive systems and melt-filtration hardware drawing from Japanese and South Korean component specialists. Single-source vulnerability for precision extrusion screws creates structural risk as SAMR certification timelines freeze capital deployment for non-domestic vendors. Distribution runs through third-party logistics providers offering packaging-as-a-service models that displace traditional film distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against paper-based cushioning alternatives and molded pulp formats that threaten bubble film's e-commerce void-fill dominance. Incumbents must navigate sustainability scorecards that penalize virgin resin content while defending equipment placement at captive logistics nodes.
For Market Incumbents: Compound barrier-film expertise through co-extrusion R&D investments that validate drop-performance claims for electronics packaging segments. Secure resin supply through backward integration into bio-based feedstock partnerships, insulating margins from naphtha-linked volatility that compresses converter capex cycles. Defend installed base positions at DHL and FedEx sortation hubs by retrofitting lines for on-demand production footprints that eliminate inbound freight costs. For New Entrants and Emerging Players: CE marking fast-track programs unlock European electronics packaging segments where REACH Article 33 disclosure requirements filter out uncertified machinery vendors. Target India's packaging automation lag, where domestic e-commerce penetration trails China and US levels, establishing localized service networks in Maharashtra and Gujarat industrial corridors. Pursue agricultural fresh-produce packaging as a white-space application, leveraging FDA indirect food-contact compliance as a differentiation anchor against commodity void-fill competitors. For Investors and Strategic Acquirers: Polymer science-integrated equipment specialists with captive testing protocols represent the most defensible acquisition archetype, commanding pricing power in high-barrier bubble configurations. Monitor extended producer responsibility framework implementations in Germany and France as an inflection signal, as these reshape resin specifications and machine retrofit requirements across European converter bases. Long-term viability hinges on exposure to co-extrusion technology migration rather than stranded single-layer installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resin Supply | Insulates margin pools from naphtha volatility that compresses converter capex cycles. |
| Co-Extrusion Technology Licensing | Captures barrier-film premiums as electronics packaging segments adopt EVOH sub-layer configurations. |
| Localized Service Network Expansion | Secures first-mover positioning in India's underpenetrated packaging automation corridor. |
| On-Demand Production Footprint Retrofit | Aligns equipment architecture with DHL and FedEx captive extrusion pilots at regional sortation hubs. |
| REACH Compliance Certification Program | Filters uncertified competitors from European supply chains bound by Article 33 disclosure mandates. |
Methodological Framework
Desk research of customs and trade databases, machinery shipment records, and regulatory filing repositories preceded structured interviews with extrusion plant managers, OEM procurement teams at packaging converters, aftermarket service heads, and polymer science R&D directors. Primary fieldwork validated secondary data from SAMR GB standard documentation, REACH Article 33 disclosure registries, and FDA indirect food-contact guidance materials. Bottom-up equipment shipment tallies triangulated against top-down converter capex surveys across the analysis window.
Variance decomposition across product type, application, end-user, and technology segmentation dimensions informed value and volume projections throughout the forecast period. Co-extrusion penetration rates, e-commerce logistics automation indices, and provincial energy intensity targets in China served as industry-specific forecast inputs. CAGRs derived from equipment replacement cycle compression and resin formulation upgrade timelines.
Decision-makers should treat outputs as directional under assumptions of sustained e-commerce logistics automation and stable REACH enforcement intensity; material deviation in polyethylene resin pricing regimes or extended producer responsibility scope would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Nano Sealers Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
Saudi Arabia Plastic Packaging Films Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
Global Silicone Release Liner Market