
 Static-Free Packaging Films Market | 2026-2036
Static-Free Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Static-Free Packaging Films Market Analytics
Direct-to-fab film supply is reshaping how static-free packaging reaches semiconductor cleanrooms. 3M leverages its materials science depth to sustain premium positioning in wafer-shipping formats. Achilles Corporation anchors Asian supply through specialized PVC and polypropylene lines for electronics OEMs. Kolon Industries competes on geographic proximity to Korean display panel fabs.
Static-free packaging films are polymer-based materials engineered with surface resistivity between 10^4 and 10^11 ohms per square, typically achieved through carbon loading, surfactant coatings, or inherently dissipative polymer alloys. These films neutralize electrostatic discharge to protect sensitive components during handling, transport, and storage. Polyethylene formulations dominate volume due to cost scalability, while PET commands margin pools in precision electronics where optical clarity and dimensional stability matter. Barrier packaging applications lead value contribution from pharmaceutical cold-chain requirements, and ultra-thin gauges represent the fastest-expanding thickness segment as device miniaturization accelerates.
FDA regulates static-free films in pharmaceutical contact applications through USP Class VI and biocompatibility testing protocols. EPA oversees volatile organic compound emissions from solvent-based coating processes used in film manufacturing. Semiconductor fabs now require ESD compliance to ANSI/ESD S20.20 and IEC 61340-5-1 standards as a condition of vendor qualification. Stakeholders must monitor how evolving cleanroom particulate specifications and halogen-free mandates in Europe and Asia redefine formulation roadmaps.
Market Dynamics
Semiconductor fabs are consolidating their supplier base around film converters capable of meeting simultaneous ANSI/ESD S20.20 and IEC 61340-5-1 certifications, compressing qualification timelines from 18 months to under 9 months and reshaping how specialty polymer formulations reach cleanroom environments.
Growth Catalysts
- REACH halogen-free mandates:European electronics OEMs are accelerating substitution of brominated flame retardants in static-dissipative formulations, opening formulation contracts for compliant polymer alloys.
- Wafer-level packaging expansion:Taiwan and South Korean semiconductor foundries are expanding procurement of ultra-clean anti-static films for 300mm wafer transport cassettes.
- Carbon nanotube loading:Film extruders are adopting multi-wall carbon nanotube masterbatches to achieve surface resistivity below 10^6 ohms per square without optical haze.
Market Restraints
- Ethylene feedstock volatility:Polyethylene-based static-dissipative films face margin compression from naphtha-cracker output fluctuations tied to regional energy markets.
- Carbon black supply concentration:Conductive carbon black for anti-static loading concentrates among three global producers, creating single-source vulnerability for mid-tier converters.
- Optical clarity trade-offs:High-loading conductive formulations in PET substrates degrade light transmission below 85%, disqualifying them from display panel applications.
Strategic Opportunities
- Indian electronics manufacturing clusters:PLI scheme incentives for semiconductor assembly and mobile device production are creating first-mover advantage for qualified film suppliers near Chennai and Bengaluru.
- Cold-chain pharmaceutical logistics:Temperature-stable static-dissipative barrier films for biologics transport remain underpenetrated versus standard pharmaceutical packaging.
- Direct-to-fab digital platforms:Specialized film distributors are bypassing regional converter networks to serve semiconductor cleanrooms through vendor-managed inventory portals.
Industry Challenges
- Cleanroom particulate certification timelines:Achieving ISO 14644 Class 3 compliance for film slitting operations requires 12-18 month facility qualification cycles that delay market entry.
- ESD auditor talent scarcity:Qualified technicians capable of certifying surface resistivity per ANSI/ESD STM11.11 protocols command premium wages and constrain converter expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Static-Free Packaging Films Market |
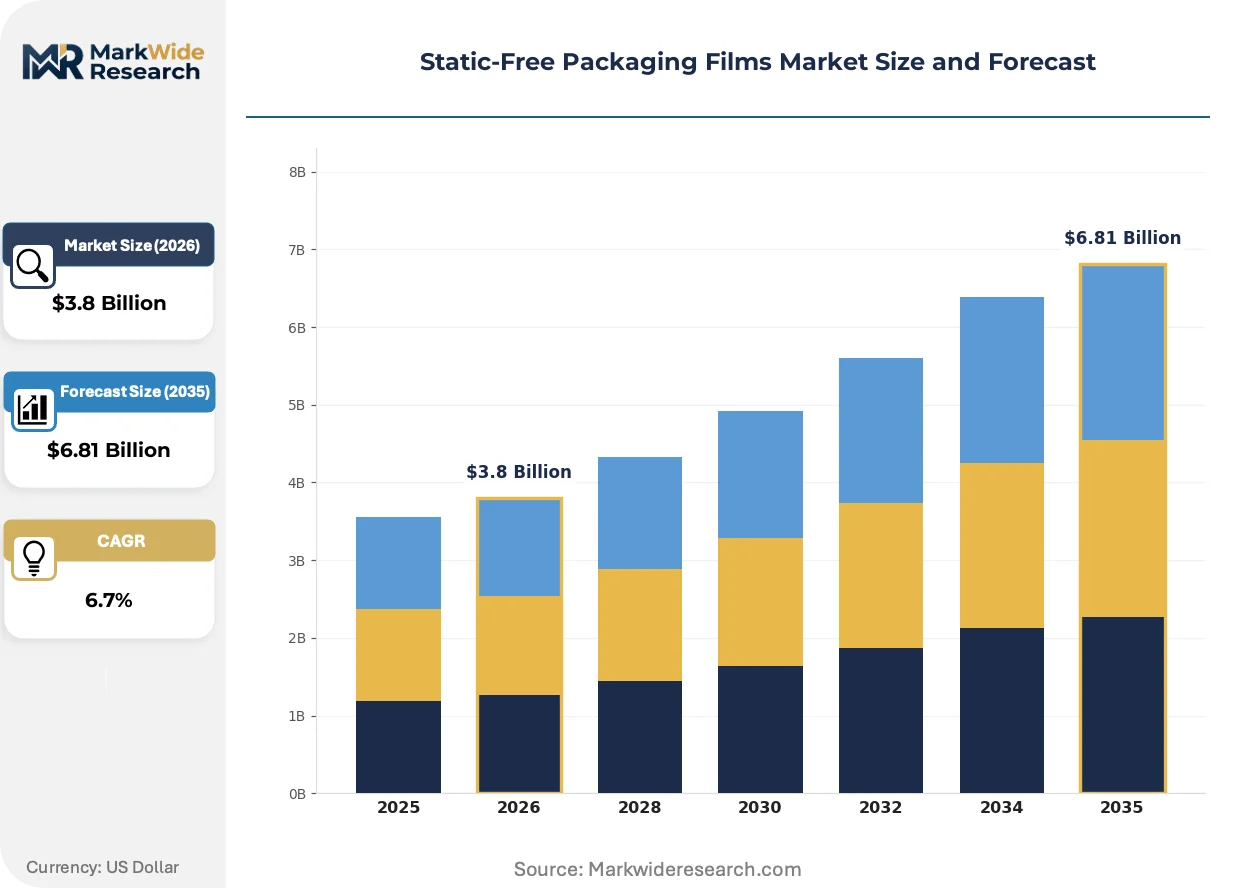
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET End User: Electronics, Pharmaceuticals, Food & Beverage, Automotive Thickness: Thin, Medium, Heavy, Ultra-Thin Application: Protective Packaging, Barrier Packaging, Retail Bags, Mailers |
| Companies Covered | 3M, Achilles Corporation, Toyobo Co. Ltd., Kolon Industries Inc., Berry Global Inc., Sealed Air Corporation, Amcor plc, Toray Industries Inc., Klöckner Pentaplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Static-Free Packaging Films Market Evolving Landscape
Formulation chemistry and procurement architecture are simultaneously evolving as semiconductor fabs demand tighter static control and faster qualification pathways. Three developments are restructuring how value flows through the supply chain.
Permanent anti-static surfactant coatings are migrating from migratory amine-based systems to non-migratory ionomer complexes that maintain surface resistivity across multiple sterilization cycles. Medical device manufacturers in Germany and Switzerland are specifying these formulations for implantable electronics packaging. The shift is compressing demand for traditional topical coatings that require reapplication after gamma irradiation.
ECHA enforcement of REACH SVHC candidate list updates is forcing reformulation of halogenated static-dissipative additives across European converter operations. Electronics OEMs serving EU markets now require full material disclosure to 0.1% threshold for substances of very high concern. Film suppliers are responding with phosphorus-based flame retardant alternatives in polyethylene and polypropylene substrates, though these carry 15-20% raw material cost premiums.
Consolidated procurement desks at major semiconductor foundries are unbundling film supply from legacy packaging distributors and negotiating directly with extrusion specialists. This pattern concentrates volume with converters maintaining captive slitting and cleanroom bagging capabilities. Korean display panel manufacturers have moved fastest on this model, with Taiwan foundries now following suit.
Static-Free Packaging Films Market Segmentation
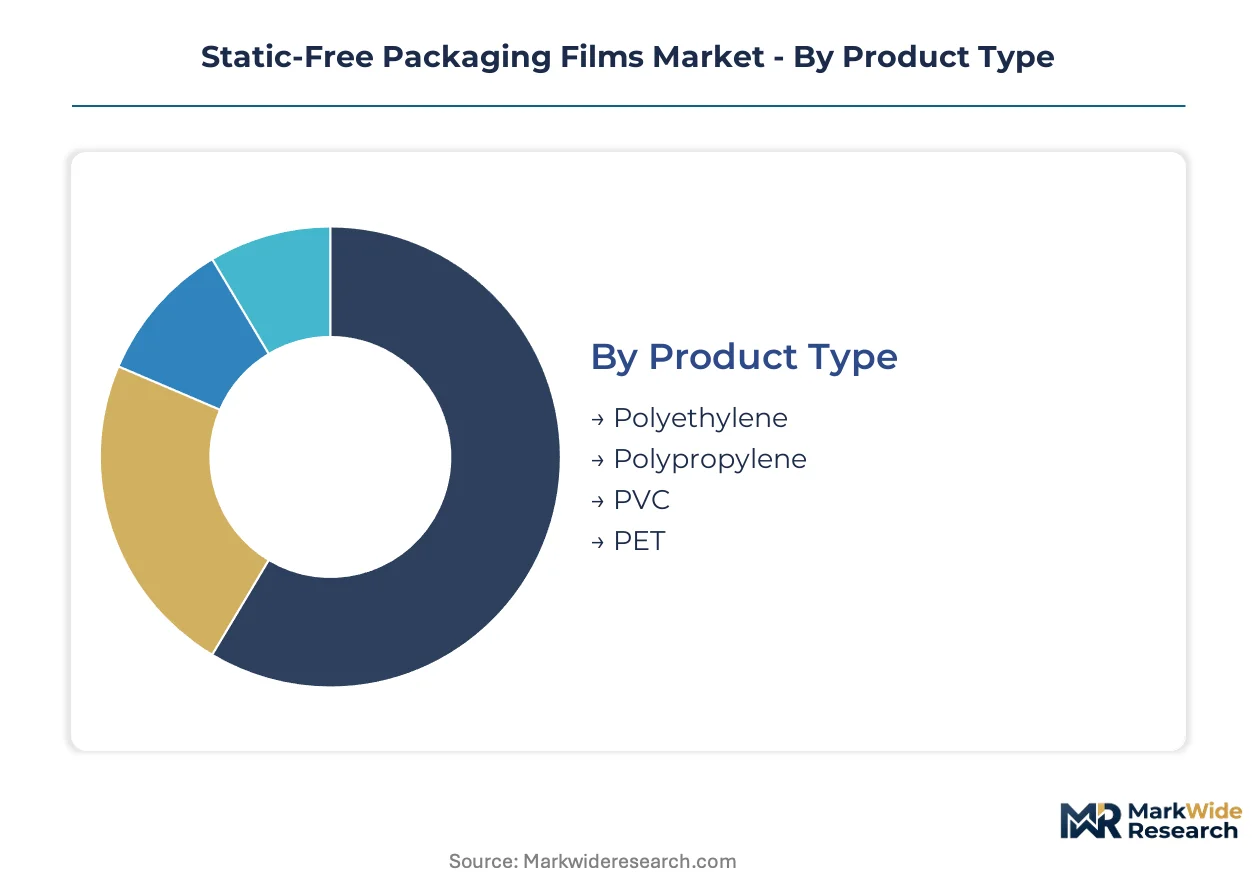
Static-free packaging films serve divergent performance requirements across semiconductor cleanrooms, pharmaceutical cold chains, and consumer electronics logistics. Segmentation reveals how formulation chemistry, gauge precision, and regulatory compliance create distinct margin pools and qualification barriers for converters.
Product Type:
After-sales service intensity varies sharply across polymer platforms, with semiconductor-grade PET demanding on-site ESD auditor support while commodity polyethylene operates through distributor self-service.
- Polyethylene:Carbon-loaded LDPE and LLDPE formulations dominate volume through cost-scalable extrusion. Taiwanese wafer foundries specify ultra-clean grades for 300mm transport cassettes, though optical haze limits deployment in display panel applications.
- PET:Biaxially oriented polyester with inherently dissipative copolymer layers achieves surface resistivity below 10^9 ohms per square without conductivity additives. Korean display panel manufacturers require 87%+ light transmission for OLED shipping trays, compressing demand for carbon-black alternatives.
- Polypropylene:Cast PP films with migratory amine coatings serve general electronics cushioning where humidity-dependent performance is acceptable.
- PVC:Plasticized formulations with permanent anti-static plasticizers anchor medical device blister packs in German and Swiss markets.
Polyethylene holds the largest share; momentum sits with PET as wafer-level packaging precision tightens.
End User:
Customer concentration patterns split the market between fab-direct procurement desks and fragmented pharmaceutical converter networks.
- Electronics:Semiconductor and display panel manufacturers now require simultaneous ANSI/ESD S20.20 and IEC 61340-5-1 certification as a non-negotiable vendor qualification condition.
- Pharmaceuticals:Cold-chain biologics transport drives demand for temperature-stable static-dissipative barrier films with USP Class VI validation.
- Food & Beverage:Powdered ingredient handling in European dairy processing plants employs medium-resistivity films to prevent dust explosions.
- Automotive:EV battery cell manufacturers specify heavy-gauge static-free dunnage for lithium-ion module transport.
Electronics commands the premium tier; pharmaceuticals represent the steepest expansion trajectory as biologics logistics requirements multiply.
Thickness:
Volume scale concentrates in commodity gauges while precision segments capture formulation margin.
- Ultra-Thin:Sub-25 micron PET and PEN films enable miniaturized component pocket tape for surface-mount device feeding systems.
- Thin:25-50 micron polyethylene dominates disposable cleanroom garment bags where single-use protocols prevail.
- Medium:50-100 micron formulations balance puncture resistance with flexibility for general electronics cushioning.
- Heavy:Above-100 micron gauges serve reusable dunnage and automotive battery module containment.
Thin gauges anchor volume; ultra-thin films are gaining share fastest as device miniaturization accelerates.
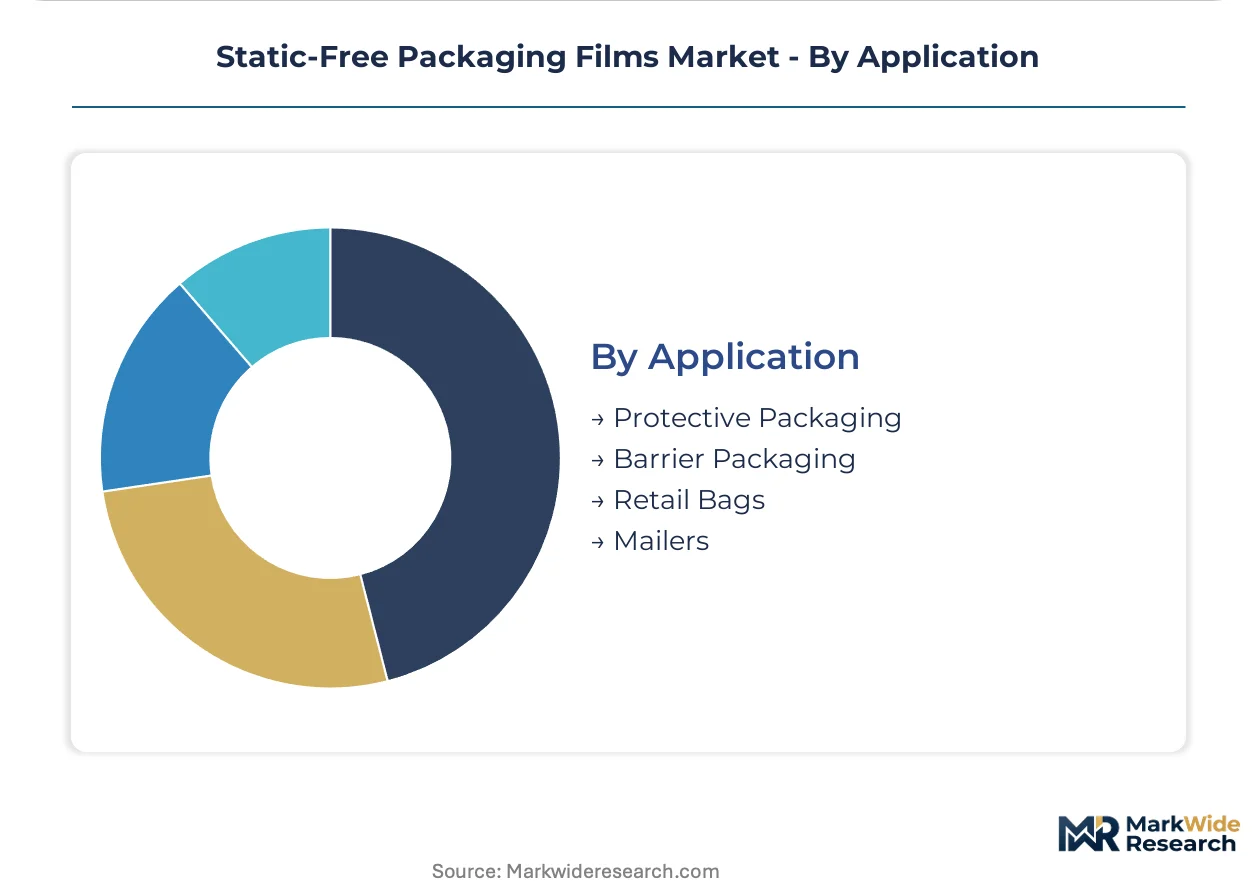
Application:
Functional performance requirements determine whether films compete on optical clarity, moisture barrier, or surface resistivity precision.
- Barrier Packaging:Multi-layer coextrusions with EVOH or aluminum oxide coatings protect moisture-sensitive pharmaceuticals through tropical distribution.
- Protective Packaging:Bubble and foam laminates with embedded conductive layers serve semiconductor wafer shipping cassettes.
- Retail Bags:Standard anti-static polyethylene competes on converter throughput for consumer electronics accessories.
- Mailers:E-commerce fulfillment of sensitive components drives demand for puncture-resistant static-dissipative poly mailers.
Barrier packaging captures the highest value per square meter; protective packaging maintains the deepest fab-direct relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH enforcement is compressing formulation timelines for static-dissipative film converters serving European electronics OEMs. Taiwan and South Korea semiconductor fabs are driving premium demand for ultra-clean wafer transport films.
United States
FDA's USP Class VI protocols govern pharmaceutical-grade static-free films for biologics cold-chain packaging. EPA oversight of VOC emissions from solvent-based coating processes is pushing converters toward aqueous formulation systems. The Boston-Cambridge biotech corridor and Austin semiconductor cluster anchor demand for certified barrier and protective film formats.
Germany
EMA's medical device packaging regulations intersect with ECHA's SVHC disclosure mandates for implantable electronics films. The country's automotive OEMs specify heavy-gauge static-dissipative dunnage for EV battery module logistics. Bavaria's precision manufacturing belt and Baden-Württemberg's automotive supply chain concentrate converter qualification activity.
China
MIIT's GB standards for electrostatic discharge control are tightening qualification requirements for domestic semiconductor packaging suppliers. NMPA oversight of pharmaceutical contact materials is expanding USP-aligned testing protocols for barrier film imports. The Yangtze River Delta and Pearl River Delta electronics manufacturing clusters are scaling procurement of locally extruded anti-static films.
South Korea
MFDS pharmaceutical packaging regulations and METI-aligned ESD standards are converging on multi-certification requirements for film vendors. Display panel manufacturers in the Gyeonggi-Seoul corridor are specifying PET-based static-dissipative trays with 87%+ optical clarity. Samsung and LG supply chain consolidation is compressing vendor qualification timelines below nine months.
India
BIS certification for electrostatic control materials is becoming mandatory for semiconductor assembly imports under the PLI scheme. CDSCO's pharmaceutical packaging standards are driving USP Class VI adoption for biologics logistics. The Chennai-Bengaluru electronics manufacturing corridor and Gujarat pharmaceutical belt are attracting first-mover film converters.
Static-Free Packaging Films Market Competitive Landscape
Materials-science conglomerates and specialized polymer converters split the market between premium certified supply and cost-scalable commodity formats. The vendor base concentrates around three strategic archetypes: integrated materials conglomerates with captive film extrusion, regional converter specialists with cleanroom slitting capabilities, and diversified packaging multinationals with static-dissipative product lines. Competitive moves center on direct-to-fab procurement desk relationships and halogen-free formulation licensing.
Within the materials-conglomerate tier, 3M and Toray Industries exemplify positioning anchored in precision polymer science and semiconductor-grade certification depth. Kolon Industries occupies a geographic-proximity position serving Korean display panel supply chains. Specialized converters including Achilles Corporation and Klöckner Pentaplast sit within the regional-expertise archetype, while packaging multinationals Amcor and Berry Global represent diversified-portfolio positioning across pharmaceutical and electronics end-uses.
| Leading Market Players |
|---|
| 3M |
| Achilles Corporation |
| Toyobo Co. Ltd. |
| Kolon Industries Inc. |
| Berry Global Inc. |
| Sealed Air Corporation |
| Amcor plc |
| Toray Industries Inc. |
| Klöckner Pentaplast |
| Others |
Value Network & Pricing Analysis
Taiwanese wafer foundry clusters in Hsinchu and Tainan anchor global capacity for semiconductor-grade PET films, concentrating formulation expertise and cleanroom slitting infrastructure that translates directly into pricing power over downstream electronics OEMs. Their dominance in ultra-clean anti-static substrates allows premium capture from Korean display panel manufacturers while compressing margins for commodity polyethylene converters in Southeast Asia.
Pricing Analysis
East Asian foundry hubs command 25-40% premiums over European and North American converters for identical ANSI/ESD S20.20 certified grades. Pricing stratifies across premium, standard, and economy tiers based on certification depth and optical clarity thresholds. Cost compression in commodity polyethylene runs through ethylene feedstock volatility tied to naphtha-cracker output fluctuations. Pharmaceutical cold-chain buyers exhibit lowest price sensitivity due to USP Class VI validation requirements, while consumer electronics accessory distributors face relentless throughput pressure.
Supply Chain Analysis
Export control regimes targeting carbon nanotube masterbatch technologies constrain technology transfer to non-aligned manufacturing jurisdictions, fragmenting supply architectures. Taiwan, South Korea, and Japan concentrate high-purity PET resin and conductive additive production. Raw material flows draw from Saudi ethylene crackers, Chinese carbon black processors, and German specialty chemical houses. Single-source vulnerability concentrates in conductive carbon black where three global producers dominate. Distribution runs through direct-to-fab vendor-managed inventory portals that bypass regional converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halogen-free REACH mandates and wafer-level packaging precision requirements are reshaping competitive positioning, creating acceleration windows for qualified converters. The market sits at a technological inflection where carbon nanotube loading displaces legacy surfactant systems.
For Market Incumbents: Entrench through captive cleanroom slitting capacity additions in Gyeonggi and Hsinchu corridors, securing sub-nine-month qualification timelines that emerging competitors cannot match. Deepen backward integration into carbon nanotube masterbatch production to offset conductive additive supply concentration. ANSI/ESD auditor talent scarcity threatens expansion velocity; lock qualified technicians through long-term employment structures. For New Entrants and Emerging Players: Indian electronics manufacturing clusters under PLI scheme incentives represent the most penetrable entry point, with Chennai-Bengaluru corridor demand outpacing qualified local supply. Cold-chain pharmaceutical logistics for biologics transport remains underpenetrated versus standard pharmaceutical packaging, offering margin refuge from fab-direct procurement desk consolidation. Pursue joint qualification pathways with European REACH compliance consultants to accelerate ECHA-aligned formulation approval. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because semiconductor fab vendor base compression concentrates volume with converters maintaining simultaneous certification depth and geographic proximity. Target acquisition archetypes: regional specialists with ISO 14644 Class 3 slitting operations and existing foundry relationships. Monitor ECHA SVHC candidate list expansion velocity as signal for halogen-free formulation contract inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Formulation Licensing | ECHA REACH enforcement opens substitution contracts for phosphorus-based flame retardant alternatives. |
| Direct-to-Fab Digital Platform Launch | Vendor-managed inventory portals bypass regional distributors to capture semiconductor procurement desk relationships. |
| Carbon Nanotube Masterbatch Integration | Multi-wall carbon nanotube loading achieves sub-10^6 ohm surface resistivity without optical degradation. |
| Indian Manufacturing Footprint Establishment | PLI scheme incentives for semiconductor assembly create first-mover advantage in qualified film supply. |
| Cleanroom Slitting Capacity Expansion | ISO 14644 Class 3 certification compresses foundry qualification timelines below nine months. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade databases, and semiconductor industry association reports. Primary interviews engaged film extrusion plant managers, foundry procurement officers at Taiwanese and Korean fabs, ESD auditor certification bodies, and pharmaceutical packaging converters. Secondary validation drew from ECHA SVHC candidate list updates, ANSI/ESD S20.20 certification registries, and EPA VOC emission disclosures. Bottom-up demand modeling triangulated against top-down polymer consumption estimates across electronics manufacturing clusters.
Forecast inputs considered polymer platform mix shifts, thickness gauge miniaturization trajectories, and regional regulatory enforcement intensity across the analysis window. Segmentation dimensions modeled include polymer chemistry, end-use industry vertical, certification tier, and geographic manufacturing hub. CAGRs derived from weighted average of demand elasticity coefficients and input cost pass-through assumptions. Carbon nanotube adoption curves and REACH halogen-free substitution timelines served as industry-specific forecast modifiers.
Practitioners should monitor ECHA SVHC list expansion, semiconductor fab capital expenditure cycles, and carbon black supply allocation decisions for early signals of forecast deviation. Material shifts in export control regime stringency or cleanroom particulate specification tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
North America Barrier Films Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Tray Liners Market
Packaging Barrier Films
Bonding Films Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Cling Films Market