
 Europe Barrier Films Market | 2026-2036
Europe Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Barrier Films Market Insights
Pharmaceutical packaging is decoupling from traditional food-sector dominance as the fastest-expanding end-use vertical in Europe. Amcor PLC leverages its continental manufacturing network to serve both healthcare and food clients with specialized multilayer structures. Mondi PLC anchors Central European supply through integrated kraft paper and film operations. Constantia Flexibles specializes in pharmaceutical-grade barrier solutions that meet stringent EU safety protocols.
Europe barrier films are multilayer polymer laminates engineered to block oxygen, moisture, and light transmission, typically incorporating ethylene vinyl alcohol or metallized substrates through coextrusion or vacuum deposition processes. These films preserve shelf stability for sensitive goods ranging from retort pouches to blister packs. Polyethylene formulations lead volume production due to cost efficiency and heat-seal compatibility across food packaging lines. Ethylene vinyl alcohol commands premium positioning in pharmaceutical and electronics applications where oxygen transmission rates below 1 cc/m²/day are mandatory. Nylon-reinforced structures occupy niche agricultural and industrial segments requiring puncture resistance and dimensional stability under load.
EMA pharmaceutical packaging guidelines, REACH chemical registration requirements, and the EU Green Deal circular economy framework collectively reshape material selection and recyclability mandates across European supply chains. ECHA restrictions on per- and polyfluoroalkyl substances are forcing substitution toward fluorine-free barrier chemistries in food-contact applications. Stakeholders must monitor regulatory timelines for recycled content quotas and assess whether existing coextrusion assets can process post-consumer feedstocks without sacrificing barrier performance.
Market Dynamics
REACH chemical restrictions and the EU Green Deal are forcing material substitutions across European barrier film supply chains, compressing development timelines while elevating compliance costs for multilayer structures containing legacy chemistries.
Growth Catalysts
- EMA pharmaceutical packaging guidelines:Stringent stability requirements for blister packs and sachets are pulling high-barrier EVOH and metallized films into healthcare applications at accelerated rates.
- Central European industrial corridor:Germany's concentration of food processing and pharmaceutical manufacturing creates dense demand clusters for coextruded barrier solutions within short logistics radii.
- Ethylene vinyl alcohol coextrusion:Advances in five- and seven-layer line configurations are extending oxygen barrier performance below 0.5 cc/m²/day without metallization steps.
Market Restraints
- Ethylene feedstock volatility:Naphtha-derived ethylene price swings directly compress polyethylene film margins, forcing producers to absorb costs or risk volume loss to Asian imports.
- Per- and polyfluoroalkyl substance bans:ECHA restrictions on fluorinated barrier chemistries are eliminating proven high-performance options before fluorine-free alternatives achieve equivalent moisture barrier rates.
- Mechanical recycling incompatibility:Current coextrusion assets cannot process post-consumer multilayer feedstocks without cross-contamination, stranding circular economy investments.
Strategic Opportunities
- Polish packaging manufacturing expansion:Lower conversion costs and EU structural funds are attracting barrier film slitting and converting operations eastward from German sites.
- Pharmaceutical cold-chain formats:Temperature-sensitive biologics are creating demand for barrier films with integrated phase-change materials and thermal insulation layers.
- Digital watermarking integration:Combined printed electronics and barrier substrates enable unit-level traceability for compliance with EU packaging waste tracking mandates.
Industry Challenges
- Multilayer extrusion technician scarcity:European technical institutes produce insufficient operators capable of calibrating seven-layer die heads for EVOH distribution uniformity.
- Recyclability certification timelines:Obtaining Interseroh or Der Grüne Punkt approval for novel barrier structures requires 18-24 month validation cycles that outpace product refresh rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Barrier Films Market |
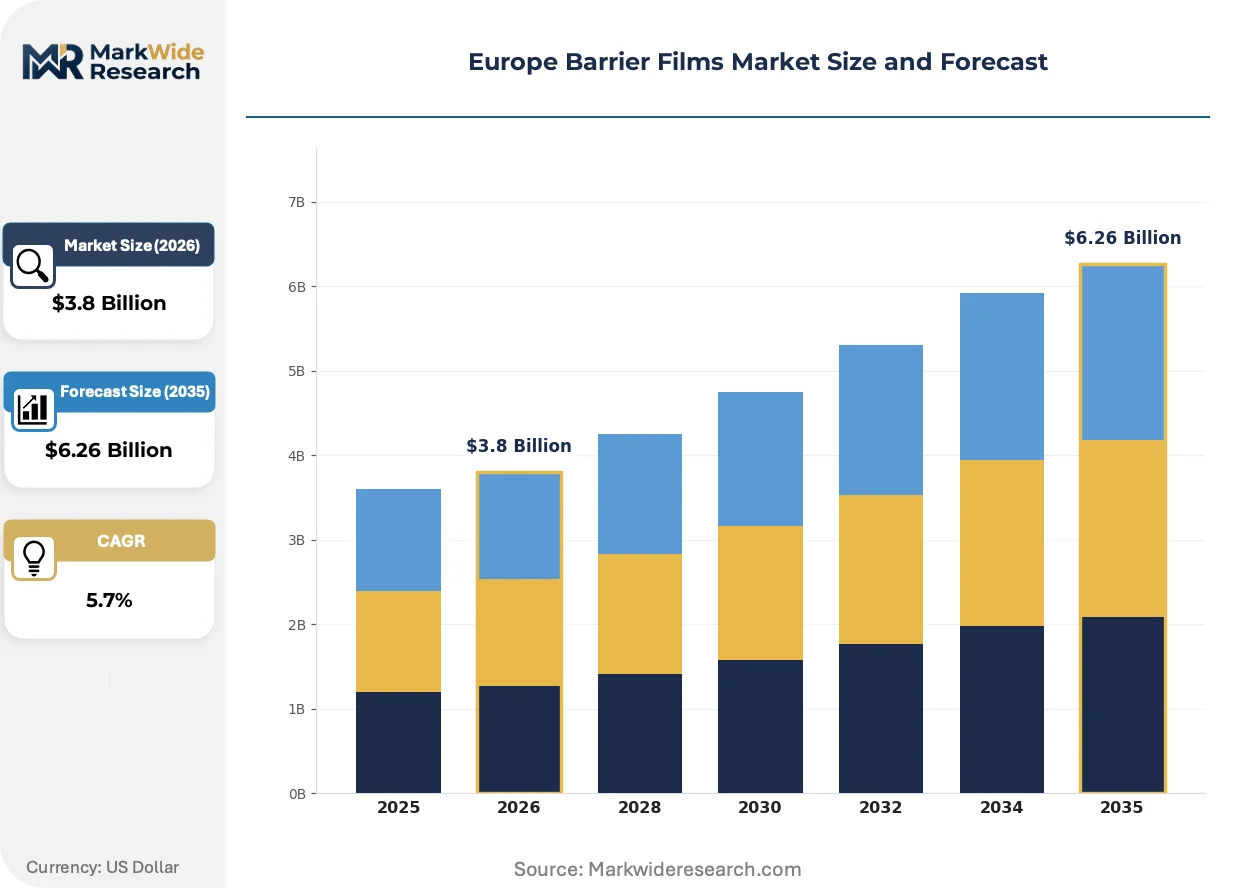
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Ethylene Vinyl Alcohol, Nylon Application: Food Packaging, Pharmaceuticals, Electronics, Agriculture End User: Food Industry, Healthcare, Consumer Goods, Automotive Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Amcor PLC, Mondi PLC, Berry Global Group, Huhtamaki Oyj, Sealed Air Corporation, Coveris Holdings, Constantia Flexibles, Wipak Oy, Sudpack Verpackungen, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Barrier Films Market Trends and Innovations
Active substitution of metallized substrates with transparent high-barrier polymers is compressing the traditional performance gap between premium and standard film tiers across European packaging lines.
Polyethylene-based oxygen scavenger films are consolidating position in modified-atmosphere meat packaging as retailers demand microwaveable formats that eliminate delamination risks of metallized alternatives. German discount grocery chains are specifying these structures for private-label fresh protein lines. The shift is consolidating volume toward transparent barrier solutions and eroding metallized film share in segments where oxygen transmission below 1 cc/m²/day remains sufficient.
REACH registration requirements for polymer additives are tightening disclosure thresholds for substances of very high concern, compelling reformulation of slip agents and anti-fog coatings used in food-contact barrier films. The ECHA candidate list expansion is accelerating substitution of conventional amide-based slip agents with bio-derived alternatives. Pharmaceutical packaging converters in Italy and Spain are prioritizing suppliers with completed SVHC dossiers to avoid supply interruption.
Consolidated buying by pan-European food groups is compressing supplier bases and elevating technical service expectations beyond commodity film transactions. Nestlé and Unilever procurement teams are reducing qualified supplier lists to three-to-five strategic partners per film category. This concentration is most visible in the Benelux dairy packaging segment, where annual tender cycles now require dedicated R&D collaboration commitments alongside volume pricing.
Europe Barrier Films Market Segmentation
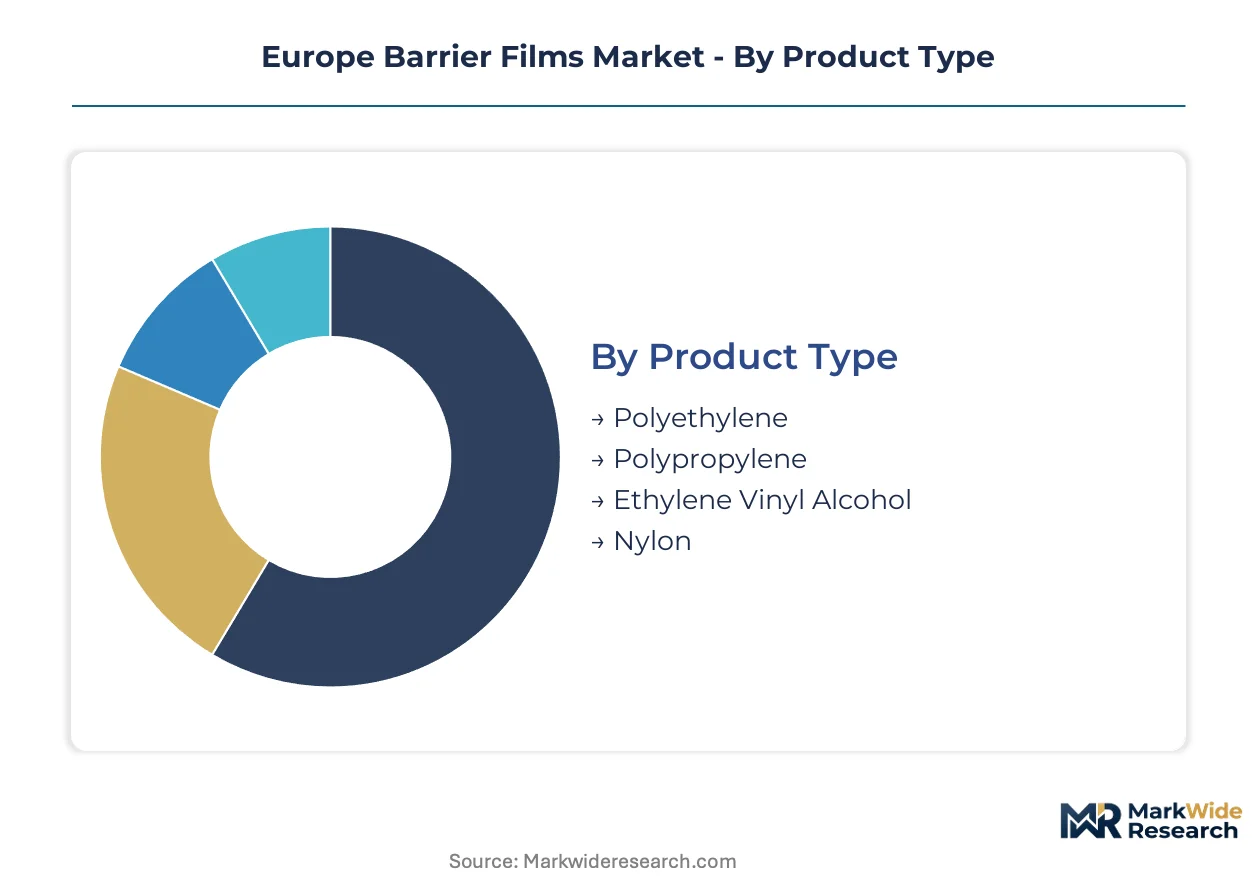
Barrier film specifications diverge sharply across European end-uses, with pharmaceutical and food-contact applications demanding incompatible certification pathways. Material selection directly determines REACH compliance burden and recyclability credentials under EU Green Deal timelines.
Product Type:
REACH registration thresholds and EFSA food-contact approvals segment European producers by polymer chemistry burden, with EVOH and metallized substrates facing stricter SVHC scrutiny than commodity polyolefins.
- Polyethylene:Dominant volume polymer in five-layer coextrusion lines serving modified-atmosphere meat packaging. German discount retailers specify PE-based structures for private-label fresh protein lines, prioritizing heat-seal consistency and microwave compatibility over ultra-low oxygen barriers.
- Ethylene Vinyl Alcohol:High-barrier copolymer achieving oxygen transmission below 0.5 cc/m²/day in pharmaceutical blister packs. Italian and Spanish converters prioritize suppliers with completed ECHA dossiers to avoid supply interruption under expanding SVHC candidate lists.
- Polypropylene:Clarity-optimized grades for retort pouches and sterilizable medical packaging. Lower moisture sensitivity than EVOH suits tropical distribution climates.
- Nylon:Puncture-resistant structures for agricultural silage wrap and industrial dunnage. Belgian and Dutch compounders blend PA6 with impact modifiers for dimensional stability under mechanical load.
Polyethylene sits at the top of the volume ranking, with Ethylene Vinyl Alcohol climbing the fastest.
Application:
Application segments stratify by barrier performance tier and regulatory intensity, from commodity oxygen scavenger films to validated pharmaceutical cold-chain formats.
- Food Packaging:Modified-atmosphere structures for fresh protein and dairy dominate tonnage. Benelux dairy processors specify transparent high-barrier polymers to eliminate metallized film delamination risks in microwaveable formats.
- Pharmaceuticals:Blister packs and sachets for temperature-sensitive biologics pull EVOH and metallized films at accelerated rates. EMA stability guidelines mandate oxygen barriers below 1 cc/m²/day for moisture-sensitive APIs.
- Electronics:Static-dissipative films for semiconductor wafer shipping. Cleanroom packaging requirements in German and Czech fabrication clusters favor ionomer-modified structures.
- Agriculture:Silage stretch films and greenhouse covers. Nylon-reinforced grades withstand puncture from crop debris and UV exposure across Central European growing seasons.
Food Packaging captures the largest volume share, though Pharmaceuticals expands most quickly on biologics cold-chain investments.
End User:
End-user concentration patterns mirror Europe's industrial corridor geography, with food processing and pharmaceutical manufacturing clustering within short logistics radii of film extrusion assets.
- Food Industry:Pan-European retail groups consolidate supplier bases to three-to-five strategic partners per film category. Nestlé and Unilever procurement teams now require dedicated R&D collaboration commitments alongside annual tender pricing.
- Healthcare:Hospital and pharmacy distribution networks demand validated cold-chain formats with integrated phase-change materials. German logistics providers specify thermal insulation layers for biologics transport.
- Consumer Goods:Personal care and household product flexible packaging. French and Italian brand owners prioritize aesthetic clarity and shelf appeal in premium positioning.
- Automotive:Protective films for interior trim and exterior components during assembly and transit. Just-in-time delivery requirements from German OEMs favor regional slitting operations.
The Food Industry anchors volume demand, while Healthcare gains share fastest on EMA packaging guideline expansion.
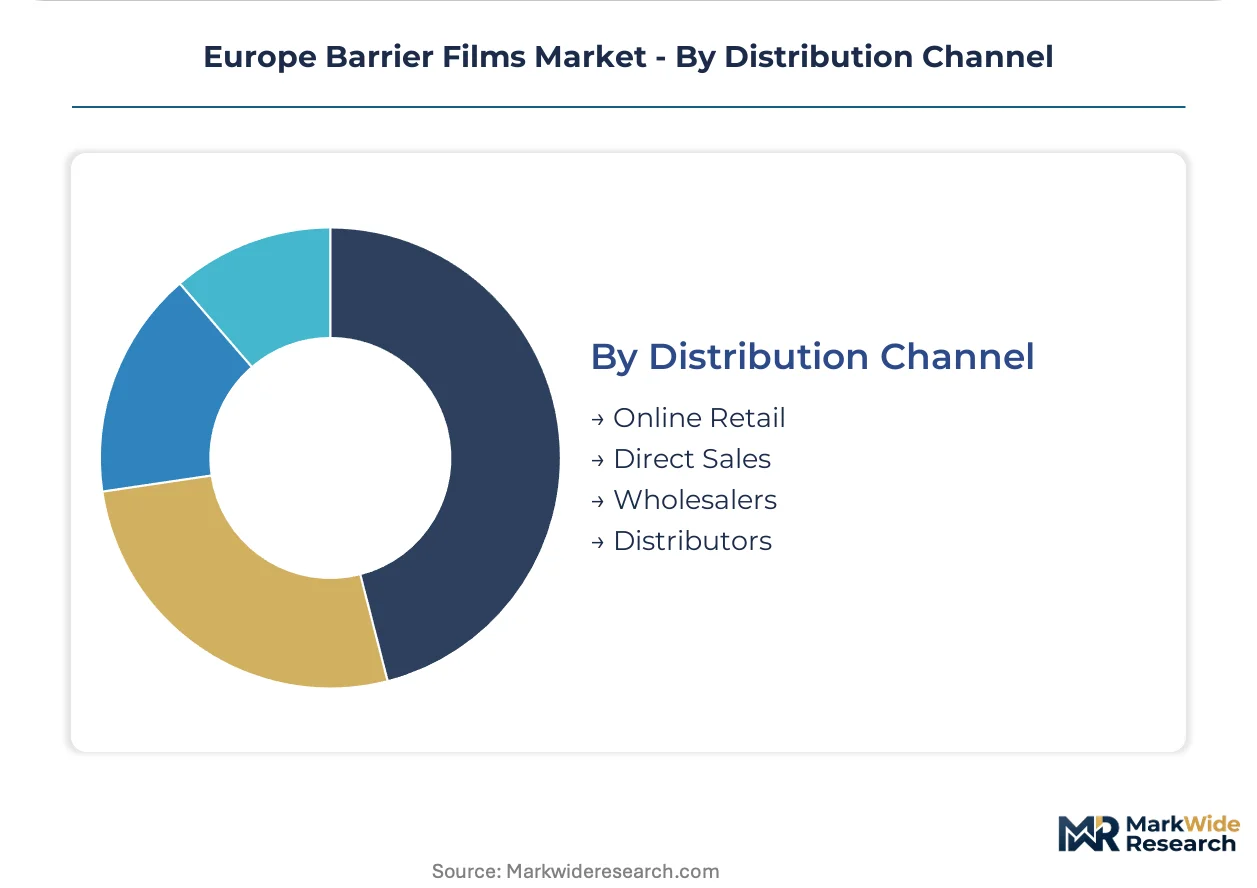
Distribution Channel:
Channel selection reflects order scale and technical service intensity, with direct relationships dominating pharmaceutical qualification cycles and distributors serving fragmented food converter bases.
- Direct Sales:Strategic accounts with co-development requirements and 18-24 month recyclability certification timelines. Major pharmaceutical converters in Germany and Italy maintain dedicated technical service agreements.
- Distributors:Inventory buffering for small-to-mid food packaging converters across Poland and Czech Republic. Regional warehouses reduce lead times for just-in-time production schedules.
- Online Retail:Sample ordering and technical documentation access for specification engineers. Limited to standard grades with established datasheets.
- Wholesalers:Commodity polyolefin volumes for non-critical applications with flexible specifications. Price-sensitive segments in Southern European markets.
Direct Sales leads the value ranking, with Distributors expanding most quickly on Polish manufacturing migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting barrier film production eastward within Europe as REACH compliance costs and EU Green Deal timelines compress margins in established Western manufacturing hubs. Polish and Czech conversion operations capture volume migrating from German sites seeking lower labor and environmental compliance burdens.
Germany
Pharmaceutical blister pack demand from Merck and Bayer operations pulls high-barrier EVOH films into Baden-Württemberg and Hesse. ECHA's expanding SVHC candidate list forces reformulation of slip agents in food-contact applications. The Rhine-Main industrial corridor anchors multilayer coextrusion capacity serving discount grocery chains with modified-atmosphere meat packaging specifications.
Poland
Lower conversion costs and EU structural fund access attract barrier film slitting and converting operations from German parent companies. The country's national environmental regulator aligns with EU packaging waste directives while offering faster permitting timelines. The Łódź manufacturing zone hosts expanding operations supplying Central European dairy processors with polyethylene-based oxygen scavenger structures.
Italy
Pharmaceutical packaging converters in Lombardy and Emilia-Romagna prioritize suppliers with completed REACH dossiers to avoid supply interruption. EMA stability guidelines for temperature-sensitive biologics drive adoption of metallized barrier films. The Milan-Turin pharmaceutical cluster demands oxygen transmission rates below 0.5 cc/m²/day for moisture-sensitive API protection.
Netherlands
Benelux dairy processors specify transparent high-barrier polymers to eliminate metallized film delamination risks in microwaveable formats. The EU Green Deal circular economy framework mandates recyclability certification through Der Grüne Punkt or Interseroh. The Rotterdam-Antwerp port corridor facilitates raw material import for five-layer coextrusion lines serving pan-European food groups.
Spain
Pharmaceutical converters in Catalonia and Madrid source EVOH films meeting EMA guidelines for blister pack stability validation. The country's national pharmaceutical regulator enforces packaging integrity standards aligned with EU MDR requirements. The Barcelona chemical corridor hosts compounding operations developing bio-derived slip agents to replace conventional amide-based additives under REACH pressure.
Europe Barrier Films Market Competitive Landscape
Strategic partnerships dominate the current landscape as producers seek to share the capital burden of seven-layer coextrusion line upgrades and recyclability certification cycles. The vendor base clusters around three tiers: integrated multinationals with continental manufacturing networks, regional specialists with pharmaceutical-grade validation capabilities, and commodity converters competing on throughput in standard polyolefin structures. Two archetypes define positioning: full-service healthcare packaging partners offering dedicated R&D collaboration, and scale-driven food packaging suppliers optimizing asset utilization across annual retail tender cycles. M&A activity and capacity expansion in Central European satellite operations represent the primary competitive vectors.
Within the integrated multinational tier, Amcor PLC and Mondi PLC exemplify divergent strategic postures. Amcor anchors healthcare and food service capabilities through continental manufacturing networks spanning multiple polymer chemistries. Mondi occupies a position emphasizing integrated kraft paper and film operations with Central European supply chain density. Constantia Flexibles represents the pharmaceutical-specialist archetype, with positioning centered on EU safety protocol compliance and EMA guideline alignment for barrier validation.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi PLC |
| Berry Global Group |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Coveris Holdings |
| Constantia Flexibles |
| Wipak Oy |
| Sudpack Verpackungen |
| Others |
Pricing and Supply Chain Analysis
Five- and seven-layer coextrusion line upgrades across Central Europe simultaneously compress per-unit conversion costs and consolidate production volume toward German and Polish manufacturing clusters. This capital-intensity threshold reshapes pricing power by favoring producers with installed multilayer capacity over commodity converters dependent on simpler extrusion assets.
Pricing Analysis
Distributor margins for specialty EVOH and metallized films run 12-18 points above direct-to-pharmaceutical-OEM channels. Pricing stratifies across pharmaceutical-grade certification, food-contact compliance tiers, and standard industrial specifications. Cost compression in commodity polyethylene structures is intensifying because naphtha-derived ethylene volatility forces margin absorption. Food packaging converters in Poland and Czech Republic exhibit highest price sensitivity, while German pharmaceutical blister pack manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Post-consumer multilayer film collection and mechanical recycling flows remain underdeveloped across Europe, stranding circular economy investments and forcing reliance on virgin feedstocks. Raw material supply concentrates in Germany, Belgium, and Netherlands, with ethylene and EVOH resin production anchored in the Antwerp-Rotterdam chemical corridor. The network draws from naphtha crackers, metallization equipment, and specialty polymer additives. Single-source vulnerability in EVOH copolymer supply creates concentration risk. Distribution runs through direct technical service agreements for pharmaceutical accounts and regional distributors for fragmented food converter bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe barrier films market functions as a regulatory compounder where ECHA SVHC candidate list expansions and EU Green Deal recyclability mandates continuously elevate compliance burdens and reshape material specifications.
For Market Incumbents: To counter fluorine-free barrier chemistry substitution timelines, prioritize backward integration into bio-derived slip agent compounding and accelerate seven-layer line upgrades in Polish satellite operations. Lock in 18-24 month recyclability certification cycles with Der Grüne Punkt and Interseroh before competitor structures reach market.
For New Entrants and Emerging Players: Capture volume in Polish slitting and converting operations serving Central European dairy processors, where lower labor costs and EU structural fund access offset German manufacturing overhead. Target pharmaceutical cold-chain formats with integrated phase-change materials as the most penetrable segment. Lead with digital watermarking integration for EU packaging waste tracking compliance.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with pharmaceutical-grade validation capabilities but limited seven-layer coextrusion scale. Five-to-ten year viability hinges on installed capacity for EVOH distribution uniformity and completed REACH dossiers. Monitor EMA stability guideline expansions for temperature-sensitive biologics as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Seven-Layer Coextrusion Capacity Expansion | Enables oxygen transmission below 0.5 cc/m²/day for EMA-compliant pharmaceutical blister packs. |
| Backward Integration into Bio-Derived Slip Agents | Replaces conventional amide-based additives facing ECHA SVHC scrutiny under REACH pressure. |
| Polish Manufacturing Footprint Establishment | Captures EU structural funds and lower conversion costs serving Central European dairy processors. |
| Recyclability Certification Acceleration | Secures Der Grüne Punkt approval ahead of EU Green Deal recycled content quota enforcement. |
| Digital Watermarking Integration | Enables unit-level traceability for compliance with EU packaging waste tracking mandates. |
Research Methodology
Multiple input streams — extrusion line operator interviews, pharmaceutical packaging converter procurement data, and polymer resin trade flows — were reconciled against secondary validation from ECHA registration databases and EU customs records. Primary discussions with multilayer coextrusion technicians, food packaging R&D directors, and pharmaceutical regulatory affairs leads informed operational constraints and compliance timelines. Secondary sources included Cefic chemical industry reports, SEC filings of listed packaging groups, and Der Grüne Punkt recyclability certification registries. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Data-stream reconciliation across product type, application, and end-user dimensions anchored the analytical framework throughout the projection horizon. Segmentation modeling incorporated polymer chemistry tier, barrier performance specification, and regional manufacturing hub clustering. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion pipelines. Forecast inputs included EMA pharmaceutical packaging guideline revision schedules and EU Green Deal circular economy timeline enforcement.
Feedstock price volatility, ECHA regulatory acceleration, and mechanical recycling technology breakthroughs are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on polymer substitution rates and certification timeline durations. Practitioners should monitor EVOH resin supply concentration and fluorine-free barrier performance parity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
Global Stretch and Shrink Film Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Heat Insulating Films Market