
 Global Sound Insulation PVB Film Market | 2026-2036
Global Sound Insulation PVB Film Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sound Insulation PVB Film Market Analysis
Ethylene-vinyl acetate is repositioning conventional PVB in cost-sensitive glazing tiers, pressuring interlayer suppliers to defend acoustic performance premiums. Sekisui Chemical Co., Ltd. leverages its Japan-based resin synthesis to sustain vertical control over acoustic-grade formulations. Eastman Chemical Company anchors North American supply through Tennessee manufacturing scale. Kuraray Co., Ltd. differentiates via specialized butyral resin architecture for rail transit specifications.
Sound insulation PVB film consists of plasticized polyvinyl butyral resin extruded into 0.38 mm to 1.52 mm sheets, engineered with controlled viscoelastic damping to attenuate airborne noise transmission across 100 Hz to 5,000 Hz frequencies. The material bonds glass laminates under heat and pressure, serving primarily as an acoustic barrier in safety glazing where human comfort and regulatory noise limits apply. Acoustic PVB Film commands the fastest expansion trajectory as rail transit operators and luxury vehicle manufacturers specify dedicated damping grades. Architectural Glazing retains the deepest margin pool due to project-scale volumes and performance-certification requirements. OEM Integration dominates deployment value as vehicle and building original equipment manufacturers lock in multi-year interlayer supply agreements.
The U.S. Department of Transportation's Federal Railroad Administration enforces exterior noise limits for passenger equipment, directly mandating laminated window upgrades. The European Union's F-Gas Regulation and Construction Products Regulation jointly shape material eligibility and environmental compliance for building-integrated glazing systems. China's MIIT publishes GB standards for railway vehicle noise control that specify laminated glass performance thresholds. Stakeholders must monitor evolving acoustic test protocols across these jurisdictions to align R&D roadmaps with certification requirements.
Market Dynamics
Acoustic-grade PVB film supply chains are tightening around specialized resin synthesis capabilities, with automotive and rail OEMs locking in multi-year interlayer agreements to secure damping performance certification for next-generation glazing systems.
Growth Catalysts
- EU Green Deal exterior noise mandates:Stringent decibel limits for vehicle and building envelopes are forcing laminated glass upgrades across German automotive production and French residential construction.
- China's high-speed rail corridor expansion:MIIT GB standards for railway vehicle noise control specify laminated glass performance thresholds, driving dedicated procurement of acoustic interlayers for window systems.
- Viscoelastic damping engineering advances:Controlled polymer architecture now attenuates airborne transmission across 100 Hz to 5,000 Hz frequencies, opening specification in luxury vehicle segments previously served by heavier glass assemblies.
Market Restraints
- Butyral resin supply concentration:Captive production of acoustic-grade formulations concentrates among Japanese and Korean chemical conglomerates, limiting second-source options for European laminators.
- Ethylene-vinyl acetate substitution pressure:Cost-sensitive architectural tiers are downgrading to EVA interlayers where acoustic performance requirements permit, compressing addressable volume for dedicated PVB damping grades.
- F-Gas Regulation compliance friction:EU restrictions on fluorinated greenhouse gases complicate manufacturing process choices for interlayer suppliers serving building-integrated glazing markets.
Strategic Opportunities
- India's premium residential tower pipeline:Mumbai and Bangalore developers are specifying acoustic laminated glass for luxury high-rises, creating first-mover advantage for certified interlayer suppliers.
- Automotive HUD integration requirements:Windshield-mounted augmented reality displays demand specialized interlayer optical clarity combined with noise attenuation, converging two previously separate specification tracks.
- US Federal Railroad Administration rulemaking:Proposed exterior noise limits for passenger equipment would mandate retrofitted laminated windows across Amtrak's existing fleet, opening aftermarket volume.
Industry Challenges
- Acoustic test protocol fragmentation:Jurisdictional divergence between ISO 140, ASTM E90, and GB/T 19889 certification requirements forces redundant testing cycles and delays product launches.
- Plasticizer migration control:Long-term viscoelastic stability demands precise formulation discipline, with performance degradation risks in extreme climate zones requiring extended validation timelines.
- Laminate autoclave capacity constraints:Glass processors face capex-intensive expansion to handle thicker acoustic-grade interlayer stacks, particularly for rail transit specification volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sound Insulation PVB Film Market |
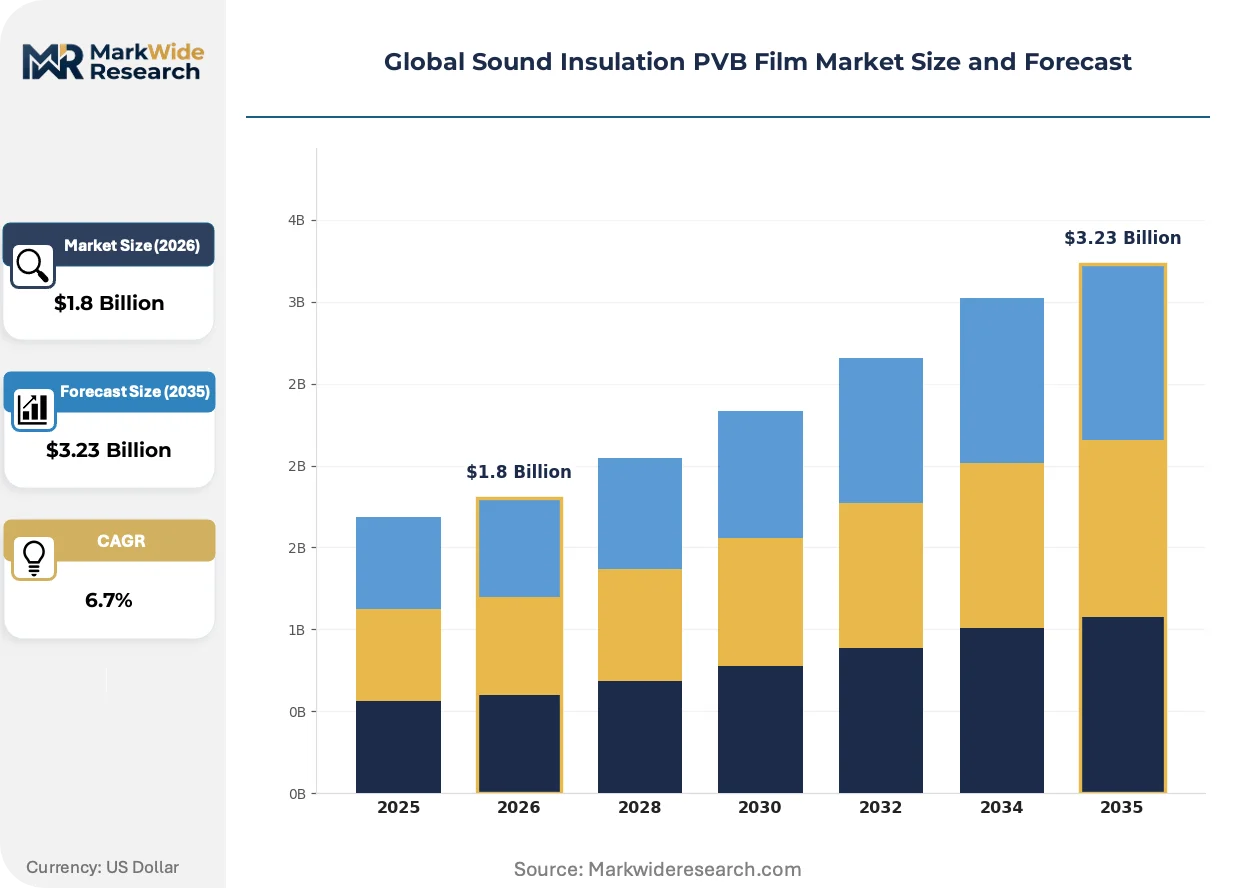
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear PVB Film, Colored PVB Film, Acoustic PVB Film, Ultra-Clear PVB Film, Structured PVB Film Application: Automotive Windshields, Architectural Glazing, Rail Transit Windows, Marine Windows, Aviation Windows End User Industry: Vehicle Manufacturers, Building Contractors, Public Transit Operators, Shipbuilders, Aircraft Assemblers Deployment Type: OEM Integration, Aftermarket Replacement, Retrofit Installations, Commercial Projects, Residential Projects |
| Companies Covered | Sekisui Chemical Co., Ltd., Everlam GmbH, Eastman Chemical Company, Chang Chun Petrochemical Co., Ltd., Zhejiang Decent Plastic Co., Ltd., Kuraray Co., Ltd., Trosifol, Huakai Plastic (Chongqing) Co., Ltd., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sound Insulation PVB Film Market Emerging Trajectories
Multilayer interlayer architectures are redefining acoustic performance benchmarks, with engineered damping profiles now custom-tuned to specific frequency bands rather than broadband attenuation. Material scientists and glazing engineers are co-developing application-specific formulations that trade off optical, structural, and acoustic properties in novel combinations.
Functionalized PVB resins are converging with embedded sensor integration for smart glass applications. Automotive OEMs in Germany and Japan are specifying interlayers capable of supporting transparent conductive coatings for defogging and antenna functions without degrading acoustic damping. This convergence is compressing the traditional separation between safety glazing and electronic subsystem supply chains, forcing interlayer suppliers to coordinate with tier-two electronics integrators earlier in vehicle development cycles.
REACH authorization requirements for plasticizer chemistries are tightening formulation flexibility for suppliers serving European architectural markets. The ECHA sunset date process for certain phthalate-based plasticizers is accelerating R&D into bio-based alternatives that maintain viscoelastic damping performance across temperature extremes. German window manufacturers are responding by qualifying alternative interlayer grades ahead of regulatory deadlines, creating temporary dual-sourcing complexity during transition periods.
Specification authority is migrating from glass processors to OEM engineering teams as acoustic performance becomes a branded vehicle attribute. Rail transit operators in China and Japan now issue dedicated interlayer performance specifications rather than delegating to laminate suppliers, compressing the value capture available to intermediate processors. This shift is most visible in high-speed rail procurement, where operators like CRRC and JR Group contract directly with resin manufacturers for volume supply agreements.
Global Sound Insulation PVB Film Market Segmentation
Segmentation in sound insulation PVB film reveals how procurement authority migrates across value chains. Material specifications diver sharply between safety-critical automotive applications and project-scale architectural contracts.
Product Type:
Buyers select film grades based on optical clarity requirements versus acoustic damping targets, with premium tiers commanding dedicated resin formulations.
- Acoustic PVB Film:Engineered with controlled viscoelastic damping to attenuate airborne noise transmission across 100 Hz to 5,000 Hz frequencies. Rail transit operators in China and luxury vehicle manufacturers in Germany specify dedicated damping grades, driving the steepest expansion trajectory in the category.
- Clear PVB Film:Standard optical-grade interlayer extruded from plasticized polyvinral butyral resin without specialized acoustic engineering. Volume concentrates in cost-sensitive architectural glazing across India's premium residential tower pipeline.
- Colored PVB Film:Pigmented interlayers for aesthetic architectural applications.
- Ultra-Clear PVB Film:Low-iron resin formulations for high-transmission glazing specifications.
- Structured PVB Film:Surface-patterned interlayers for specialized bonding applications.
Volume sits with Clear PVB Film; growth tilts toward Acoustic PVB Film.
Application:
Application selection tracks regulatory noise limits, with EU Green Deal mandates and MIIT GB standards creating divergent specification intensity across end-uses.
- Architectural Glazing:Project-scale laminated glass systems for commercial and residential building envelopes. French residential construction and Mumbai luxury high-rise developments sustain the deepest margin pool due to performance-certification requirements.
- Automotive Windshields:Safety glazing integrating acoustic damping with structural integrity. German automotive production expands procurement of acoustic-grade interlayers under stringent exterior noise limits.
- Rail Transit Windows:High-speed train window systems requiring dedicated damping performance.
- Marine Windows:Vessel glazing with salt corrosion resistance requirements.
- Aviation Windows:Aircraft cabin pressure-rated laminated assemblies.
Margins concentrate in Architectural Glazing; specification intensity climbs fastest in Rail Transit Windows.
End User Industry:
End user procurement patterns reflect the shift from glass processor delegation to direct OEM engineering engagement.
- Vehicle Manufacturers:Automotive OEMs locking in multi-year interlayer agreements for next-generation glazing systems. Windshield-mounted HUD integration requirements now converge acoustic damping with optical clarity specifications.
- Public Transit Operators:Rail agencies issuing dedicated interlayer performance specifications rather than delegating to laminate suppliers. CRRC and JR Group contract directly with resin manufacturers for volume supply agreements.
- Building Contractors:Project-based procurement for commercial and residential glazing.
- Shipbuilders:Marine vessel constructors with corrosion-resistant interlayer requirements.
- Aircraft Assemblers:Aviation OEMs with pressure-rated and weight-optimized specifications.
Contract value pools deepest with Vehicle Manufacturers; direct procurement expands fastest among Public Transit Operators.
Deployment Type:
Deployment mode determines supply chain configuration, with OEM integration locking in multi-year agreements versus project-based spot purchasing.
- OEM Integration:Multi-year interlayer supply agreements secured by vehicle and building original equipment manufacturers. Dominates deployment value through locked-in volume commitments and performance certification requirements.
- Retrofit Installations:Upgraded laminated window systems for existing rail and building infrastructure. US Federal Railroad Administration proposed exterior noise limits would mandate retrofitted laminated windows across Amtrak's existing fleet.
- Aftermarket Replacement:Post-warranty glazing component replacement.
- Commercial Projects:Large-scale architectural glazing contracts.
- Residential Projects:Single-building or small-scale housing applications.
Value capture concentrates in OEM Integration; regulatory-driven volume expands most quickly in Retrofit Installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate acoustic PVB resin synthesis capacity, attracting tier-one automotive and rail OEMs seeking captive interlayer supply. German and Japanese chemical conglomerates anchor premium-grade production through backward-integrated resin architecture.
China
MIIT GB standards for railway vehicle noise control mandate laminated glass performance thresholds across CRRC's high-speed rail corridor projects. The MIIT publishes updated acoustic specifications that interlayer suppliers must certify against before volume procurement. Shanghai and Suzhou industrial clusters host integrated resin-to-film operations serving both domestic rail operators and export automotive programs.
Germany
EU Green Deal exterior noise limits force laminated glass upgrades across automotive windshield production and French-border residential construction. The ECHA REACH authorization timeline for plasticizer chemistries tightens formulation flexibility for architectural glazing suppliers. Bavaria's chemical corridor sustains specialized butyral resin synthesis for acoustic-grade interlayers bound for premium vehicle programs.
Japan
METI industrial standards coordinate with rail operators JR Group and automotive OEMs to specify dedicated damping grades for next-generation glazing systems. The PMDA does not regulate interlayers directly, but METI's quality infrastructure framework shapes certification protocols for export-bound film. Kansai and Chubu industrial regions concentrate captive resin production serving domestic OEM integration contracts.
United States
The Federal Railroad Administration enforces exterior noise limits for passenger equipment that directly mandate laminated window upgrades across Amtrak's operational fleet. Proposed rulemaking would expand retrofit requirements to existing rolling stock, opening aftermarket volume for certified interlayer suppliers. Tennessee manufacturing scale anchors North American supply for automotive OEM integration programs.
India
Mumbai and Bangalore developers specify acoustic laminated glass for luxury high-rise residential towers, creating first-mover advantage for certified interlayer suppliers entering the market. The BIS harmonizes with ISO acoustic test protocols for building-integrated glazing systems, though certification timelines lag European benchmarks. Maharashtra and Karnataka construction corridors concentrate demand for premium architectural glazing specifications.
Global Sound Insulation PVB Film Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with resin-synthesis capabilities determining tier placement. The vendor base concentrates around Japanese and Korean chemical conglomerates with captive butyral resin production, while European and North American players anchor regional supply through manufacturing scale. Three archetypes dominate: backward-integrated resin manufacturers, regional laminate processors, and automotive-dedicated formulation specialists. Competitive moves center on multi-year OEM supply agreements and acoustic performance certification lock-ins.
Among Japan-based chemical conglomerates, Sekisui Chemical Co., Ltd. and Kuraray Co., Ltd. exemplify the backward-integrated archetype through in-house resin synthesis control. Eastman Chemical Company occupies a position among North American scale players anchoring regional supply. These three represent divergent geographic and structural approaches to acoustic-grade interlayer supply.
| Leading Market Players |
|---|
| Sekisui Chemical Co., Ltd. |
| Everlam GmbH |
| Eastman Chemical Company |
| Chang Chun Petrochemical Co., Ltd. |
| Zhejiang Decent Plastic Co., Ltd. |
| Kuraray Co., Ltd. |
| Trosifol |
| Huakai Plastic (Chongqing) Co., Ltd. |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Rail transit operators and automotive OEMs locking in multi-year interlayer agreements dominate procurement volume, anchoring contract-based pricing that rewards volume commitment over spot purchasing. This buyer concentration amplifies pricing power for resin manufacturers with captive synthesis capabilities while squeezing laminate processors caught between fixed resin costs and capped contract rates.
Pricing Analysis
Short lead-time premiums apply to acoustic-grade formulations required for urgent rail certification deadlines, while spot inventory of standard clear grades trades at modest discounts. Three-tier pricing structure across premium, standard, and economy levels separates certified acoustic damping grades from architectural clear film and commodity EVA substitutes. Pricing pressure stems from EVA substitution in cost-sensitive architectural tiers, with Indian residential developers and Chinese commercial contractors driving the sharpest price sensitivity. Luxury vehicle manufacturers and high-speed rail operators exhibit least price sensitivity, prioritizing performance certification over unit cost.
Supply Chain Analysis
Domestic-content mandates under China's MIIT procurement guidelines and India's PLI scheme for advanced materials are reshaping sourcing patterns, forcing non-Asian suppliers to establish local compounding partnerships or forfeit volume. Geographic supply concentrates in Japan, South Korea, and China's Yangtze River Delta, where captive butyral resin synthesis feeds integrated film extrusion. Raw material dependencies center on polyvinyl alcohol feedstock, plasticizer chemistries, and specialized acoustic additive packages. Single-source vulnerability runs through Japanese resin architecture patents held by Sekisui and Kuraray. Distribution runs through direct OEM supply agreements for automotive and rail tiers, with architectural channels served by regional laminate processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into resin synthesis has become the defining competitive race, with acoustic-grade formulation control separating margin leaders from price-takers. Players lacking captive butyral production face structural disadvantage as OEMs consolidate supply agreements around vertically integrated suppliers.
For Market Incumbents: To counter EVA substitution pressure in architectural glazing, Sekisui Chemical and Kuraray should accelerate certification of next-generation bio-based plasticizer formulations ahead of ECHA REACH sunset deadlines. Eastman Chemical must defend Tennessee manufacturing scale by locking extended supply agreements with Detroit automotive OEMs integrating HUD-compatible acoustic interlayers. Certification investment in India's BIS harmonization process offers first-mover protection against emerging Chinese competitors.
For New Entrants and Emerging Players: Enter via India's premium residential tower pipeline, where Mumbai and Bangalore developers specify acoustic laminated glass without entrenched supplier relationships. Target rail transit retrofit opportunities under proposed US Federal Railroad Administration noise limits, where incumbent relationships with Amtrak remain unformed. Pursue white-label supply to European laminate processors seeking second-source options beyond Japanese resin dependence.
For Investors and Strategic Acquirers: The window for entry favors mid-cap resin compounders with acoustic formulation capability but lacking film extrusion scale. Acquisition targets should demonstrate validated damping performance across 100 Hz to 5,000 Hz frequencies and existing qualification with at least one tier-one rail or automotive OEM. Watch for inflection when Chinese MIIT publishes revised GB standards tightening noise control thresholds, triggering replacement demand across CRRC's installed base.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive butyral production secures margin control against feedstock volatility for acoustic-grade formulations. |
| Long-term Supply Agreement | Multi-year OEM contracts with German automotive manufacturers lock in volume commitments through EU Green Deal compliance cycles. |
| Joint Venture | Local compounding partnerships in India satisfy BIS certification requirements and PLI domestic-content thresholds. |
| Capacity Expansion | Additional laminate autoclave capacity addresses rail transit specification volumes for China's high-speed rail corridor projects. |
| Green Manufacturing Transition | Bio-based plasticizer R&D maintains ECHA REACH authorization ahead of phthalate sunset deadlines for European architectural markets. |
Methodological Framework
Trade databases, chemical industry association filings, and regulatory submission records formed the secondary backbone, cross-referenced against primary interviews with resin synthesis plant managers, automotive OEM procurement leads, rail transit specification engineers, and architectural glazing distributors. Bottom-up volume estimates triangulated against top-down market sizing derived from customs data and downstream laminate processor capacity disclosures. Primary fieldwork concentrated on supply chain mapping across Japan's Kansai industrial region, Germany's Bavaria chemical corridor, and China's Yangtze River Delta special economic zones.
Bottom-up modeling aggregated segment-level demand across acoustic PVB film, clear PVB film, and alternative interlayer technologies, with top-down validation against macro drivers including EU Green Deal implementation timelines, MIIT GB standard revision cycles, and Federal Railroad Administration rulemaking progress. Segmentation dimensions included product grade tier, end-use application intensity, deployment mode, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution effects from EVA interlayers and projected rail fleet expansion schedules. Industry-specific inputs captured plasticizer chemistry transition costs and laminate autoclave capacity utilization rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EVA substitution in cost-sensitive architectural tiers or delayed ECHA authorization timelines for alternative plasticizer chemistries. Forecasts reflect documented assumptions regarding regulatory implementation schedules, OEM platform transition timing, and resin synthesis capacity expansion plans. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
PVC Films Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Canada Plastic Packaging Films Market
Poly film
Polylaminate Capsules Market
Poly film
Tube Laminating Films Market
Poly film
Global BOPET Packaging Films Market
Poly film
In-Mould Label Film Market
Poly film
PVC Cling Film Market
Poly film
Light Reflective Film Market
Poly film
Colourless Polyimide Films Market
Poly film
Twist Wrap Film Market
Poly film
North America Plastic Film Packaging Market
Poly film
Cellulose Film Packaging Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
Global Fluoropolymer Films Market
Poly film
Starch-Based Plastic Films Market