

Barrier Coated Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Coated Carton Market Insights
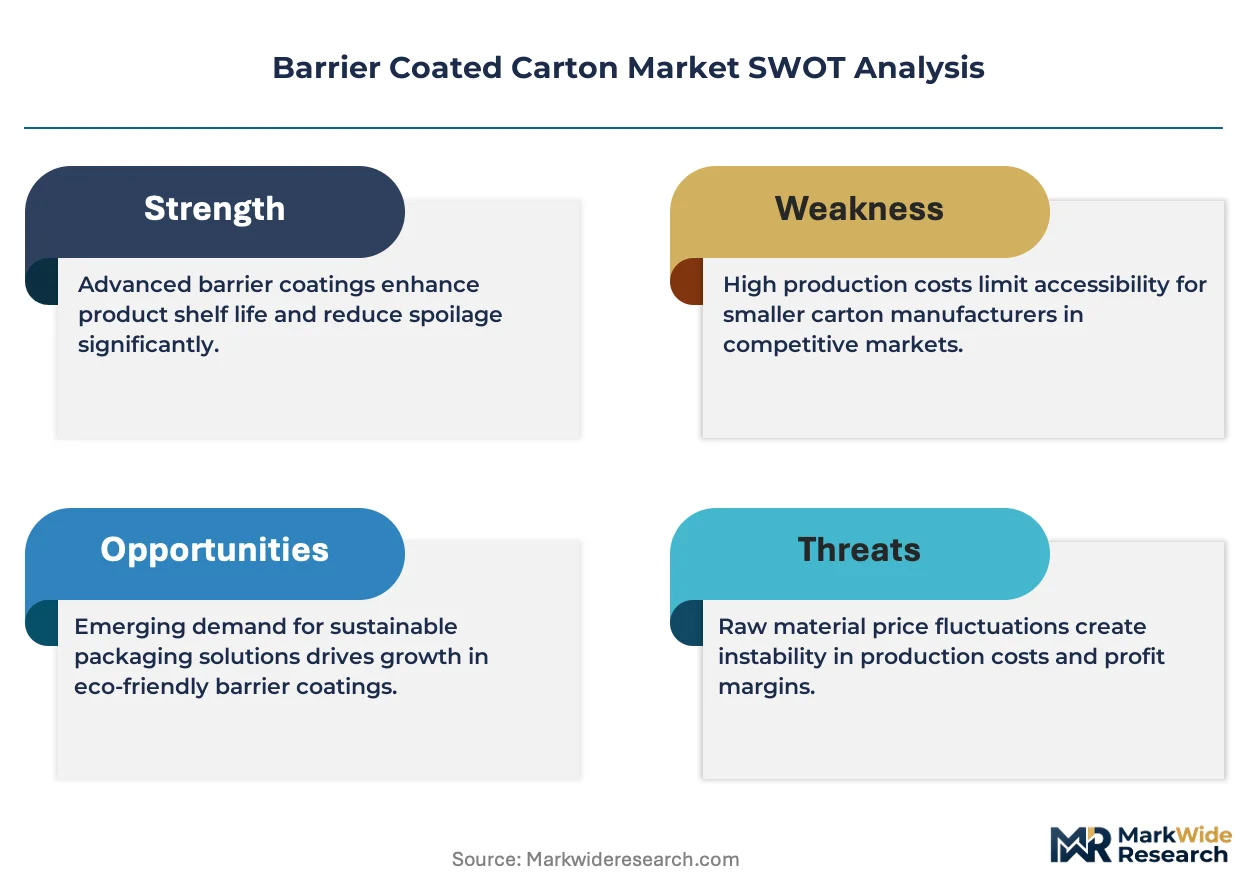
Polyethylene is decoupling from virgin fossil feedstocks as bio-based and recycled-content barrier layers reshape carton economics. Mondi leverages its integrated pulp-to-packaging model to control substrate quality and barrier consistency across European operations. Huhtamaki anchors its position through specialized extrusion coating capabilities that serve quick-service food chains globally. Stora Enso competes via its renewable materials platform, linking forest certification to downstream carton sustainability claims.
A barrier coated carton consists of paperboard substrate laminated with functional polymer, wax, or metallic layers that block moisture, oxygen, grease, or light transmission, typically achieving water vapor transmission rates below 10 g/m²/day depending on coating chemistry and caliper. The primary commercial purpose is extending shelf life while enabling direct food contact and post-consumer recyclability within existing paper streams. Polyethylene coated cartons still dominate installed capacity, though acrylic coated variants are gaining fastest as converters target repulpability thresholds set by European paper mills. Food packaging absorbs the largest share of barrier carton volume, while pharmaceutical applications command the highest margin pools due to child-resistance and moisture-barrier validation requirements.
The EU Green Deal and REACH frameworks restrict per- and polyfluoroalkyl substances in food contact materials, forcing coating reformulation toward mineral oil-free and fluorine-free barriers. FDA food contact notification rules govern U.S. import acceptance, creating dual-compliance burdens for multinational converters. China's GB standards and SAMR oversight add a third regulatory layer for brands sourcing packaging domestically. Stakeholders must monitor evolving extended producer responsibility schemes that shift recycling cost allocation from municipalities to packaging producers.
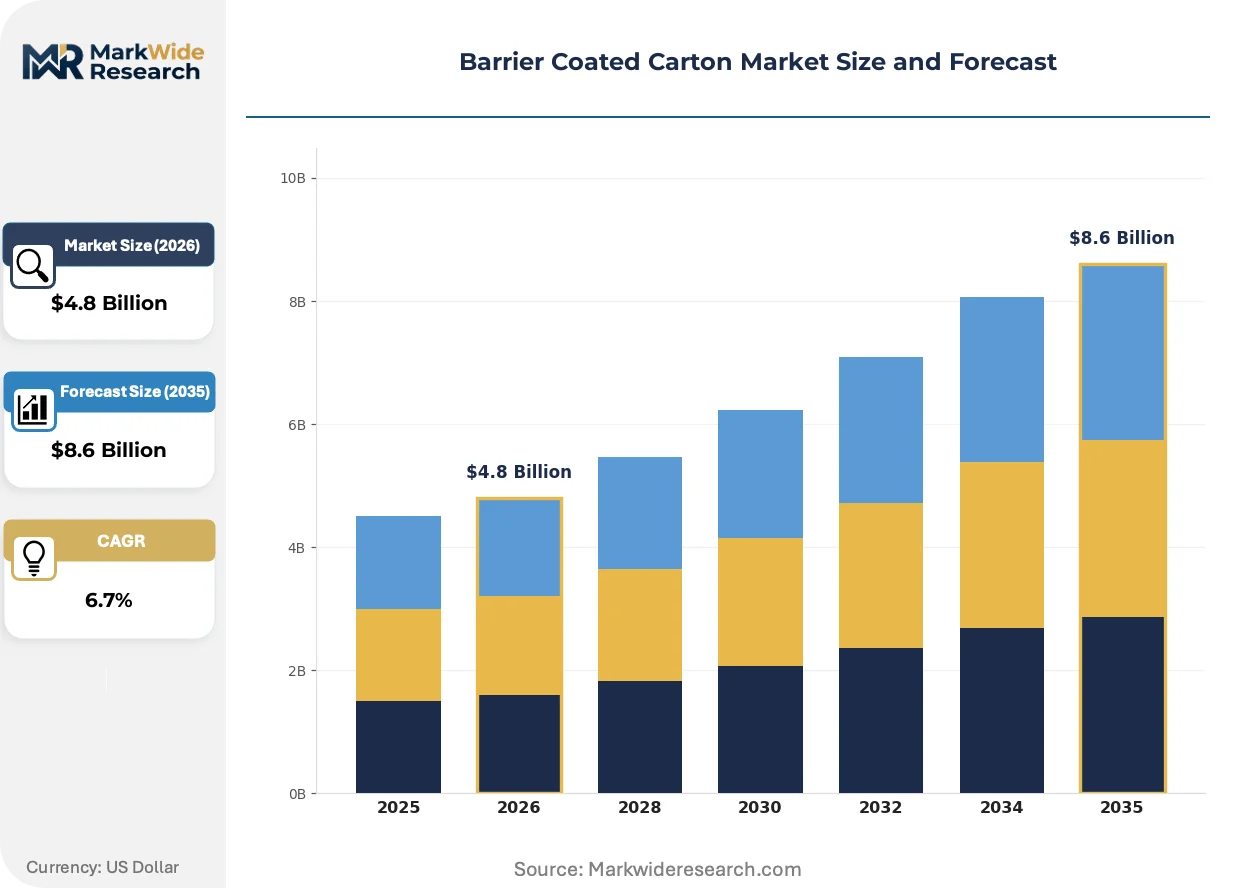
Market Dynamics
The EU Green Deal's fluorine-free mandates are forcing coating reformulation across European converter operations, while bio-based polyethylene feedstocks reshape raw material procurement economics for barrier carton producers.
Growth Catalysts
- REACH Phase-Down of PFAS:Per- and polyfluoroalkyl substance restrictions under ECHA oversight are accelerating mineral oil-free barrier adoption among German food brands seeking compliant packaging substrates.
- Quick-Service Restaurant Chains:Global QSR operators are replacing plastic clamshells with grease-resistant paperboard cartons to meet corporate plastic-reduction commitments and consumer-facing sustainability targets.
- Acrylic Barrier Chemistry:Water-based acrylic coatings are achieving sub-10 g/m²/day moisture vapor transmission rates while maintaining repulpability thresholds demanded by European paper mills.
Market Restraints
- Recycled Polyethylene Feedstock Volatility:Post-consumer rPE supply concentrates in Nordic mechanical recycling clusters, creating price instability for converters dependent on circular content claims.
- Aluminum Oxide Deposition Limits:Vacuum metallization barriers face caliper constraints above 400 gsm board weights, restricting application in heavy-duty frozen food segments.
- Dual FDA-EU Compliance Burden:U.S. food contact notification rules and EFSA migration limit testing create redundant certification costs for multinational brand suppliers.
Strategic Opportunities
- Pharmaceutical Cold Chain Expansion:Moisture-barrier cartons with child-resistance features are penetrating temperature-sensitive drug distribution as glass and plastic vial secondary packaging.
- Extended Producer Responsibility Schemes:French and Italian EPR fee structures now favor fiber-based packaging with demonstrated recyclability, creating cost advantages over multi-material flexible alternatives.
- Digital Printing Convergence:Inkjet and toner-based decoration technologies enable short-run SKU proliferation for regional food brands without plate-changeover delays.
Industry Challenges
- Extrusion Coating Technician Scarcity:Specialized operators capable of maintaining melt-index consistency across bio-based and fossil PE blends command premium wages in Central European labor markets.
- Migration Testing Timeline Compression:EFSA and FDA dual notification protocols extend new barrier formulation commercialization cycles by 18-24 months versus legacy polyethylene standards.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Coated Carton Market Trends and Innovations
Barrier coating technologies are bifurcating between high-performance multilayer structures for shelf-stable foods and simplified mono-material designs optimized for paper-stream recyclability.
Water-based acrylic barrier coatings are absorbing investment from European converters seeking to eliminate polyethylene lamination layers entirely. Mid-size dairy and dry goods brands in the Netherlands and Belgium are piloting these substrates for 12-month shelf-life applications. The technology is absorbing market share previously held by extrusion-coated boards in segments where moderate moisture protection suffices.
EU Green Deal implementation through national transposition laws is mandating fluorine-free grease barriers in fast-food packaging by 2026. ECHA restriction proposals on PFAS in food contact materials are forcing reformulation of legacy popcorn and french fry cartons. German packaging converters are responding with silica-based and clay-modified barrier coatings that sacrifice some oil resistance for regulatory compliance.
Brand procurement teams are consolidating carton specifications across regional manufacturing footprints to reduce SKU complexity. Pan-European food manufacturers are pushing converters toward unified board grades with modular barrier add-ons rather than country-specific formulations. This concentration is most visible in Benelux and Nordics, where sustainability procurement mandates have standardized on FSC-certified substrates with identical barrier performance tiers.
Barrier Coated Carton Market Segmentation
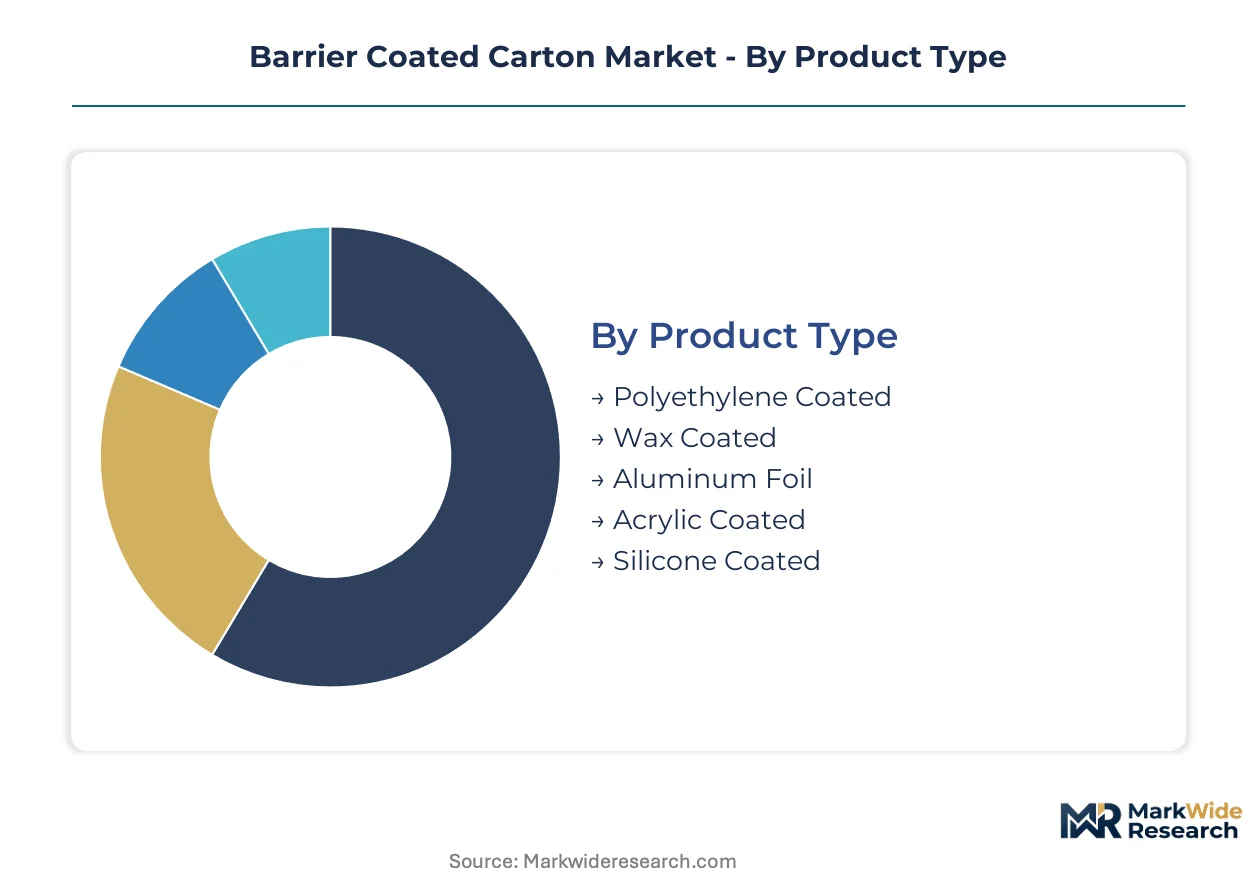
Barrier coated carton segmentation reveals how capital deployment, regulatory compliance, and end-use performance requirements fragment production economics across converter operations. Technical specifications diverge sharply between commodity food service boards and pharmaceutical-grade moisture barriers, creating distinct margin pools and equipment utilization patterns.
Product Type:
Extrusion coating lines demand the heaviest capital outlays, with melt-index control systems and multi-layer die configurations driving upfront investment differentiation across substrate categories.
- Polyethylene Coated:Extrusion-coated polyethylene layers achieve sub-10 g/m²/day water vapor transmission rates through controlled melt-index consistency. German dairy and frozen food brands in Bavaria and North Rhine-Westphalia anchor demand as EFSA migration limits tighten compliance requirements for direct food contact.
- Acrylic Coated:Water-based acrylic dispersions eliminate polyethylene lamination entirely while maintaining repulpability thresholds demanded by European paper mills. Dutch and Belgian mid-size brands pilot these substrates for 12-month shelf-life dry goods, absorbing share from extrusion-coated alternatives where moderate moisture protection suffices.
- Wax Coated:Paraffin and microcrystalline wax barriers serve short-cycle produce and poultry applications with limited recyclability credentials.
- Aluminum Foil:Metallized or laminated aluminum layers deliver near-zero oxygen transmission for oxygen-sensitive pharmaceuticals and premium coffee.
- Silicone Coated:Release-coated variants enable adhesive label applications and baking paper conversions with specialized release force specifications.
Most installed capacity flows through Polyethylene Coated. Expansion is steepest in Acrylic Coated.
Barrier Technology:
Performance tiering separates commodity converters from specialists capable of validating multi-barrier combinations under dual FDA-EU notification protocols.
- Water Vapor Barrier:Polyethylene and acrylic chemistries dominate moisture protection specifications, with transmission rate validation required for dairy, frozen food, and pharmaceutical secondary packaging. Nordic mechanical recycling clusters supply post-consumer rPE feedstock for circular content claims, though price volatility constrains converter margins.
- Grease Resistance:Silica-based and clay-modified coatings replace legacy PFAS-treated boards under EU Green Deal fluorine-free mandates. German quick-service restaurant chains drive specification changes as ECHA restriction proposals force reformulation of popcorn and french fry cartons by 2026.
- Oxygen Barrier:EVOH coextrusions and aluminum oxide deposition preserve shelf life in oxygen-sensitive coffee, nuts, and pharmaceutical applications.
- Aroma Barrier:Specialized coatings prevent flavor scalping in tea, spices, and flavored beverage cartons.
- UV Protection:Light-blocking barriers extend vitamin stability in fortified beverages and light-sensitive nutraceuticals.
Water Vapor Barrier commands the largest equipment base. Grease Resistance is climbing the fastest as regulatory deadlines approach.
Application:
Volume concentration and margin structure diverge between high-throughput food service boards and low-volume, high-specification pharmaceutical formats.
- Food Packaging:Dairy, frozen meals, and dry goods absorb the majority of barrier carton volume, with quick-service restaurant chains replacing plastic clamshells for corporate plastic-reduction commitments. Pan-European manufacturers consolidate specifications toward unified board grades with modular barrier add-ons.
- Pharmaceuticals:Child-resistant closures and moisture-barrier validation requirements command premium pricing as glass and plastic vial secondary packaging. Temperature-sensitive drug distribution expansion drives cold chain carton adoption.
- Beverage Packaging:Aseptic brick cartons and chilled distribution formats require multi-layer oxygen and light barriers.
- Personal Care Products:Cosmetic and hygiene applications demand grease and aroma barriers for oil-based formulations.
- Industrial Goods:Corrosion-inhibiting barriers protect metal components and chemicals during transit and storage.
Food Packaging dominates throughput. Pharmaceuticals deliver the steepest margin expansion trajectory.
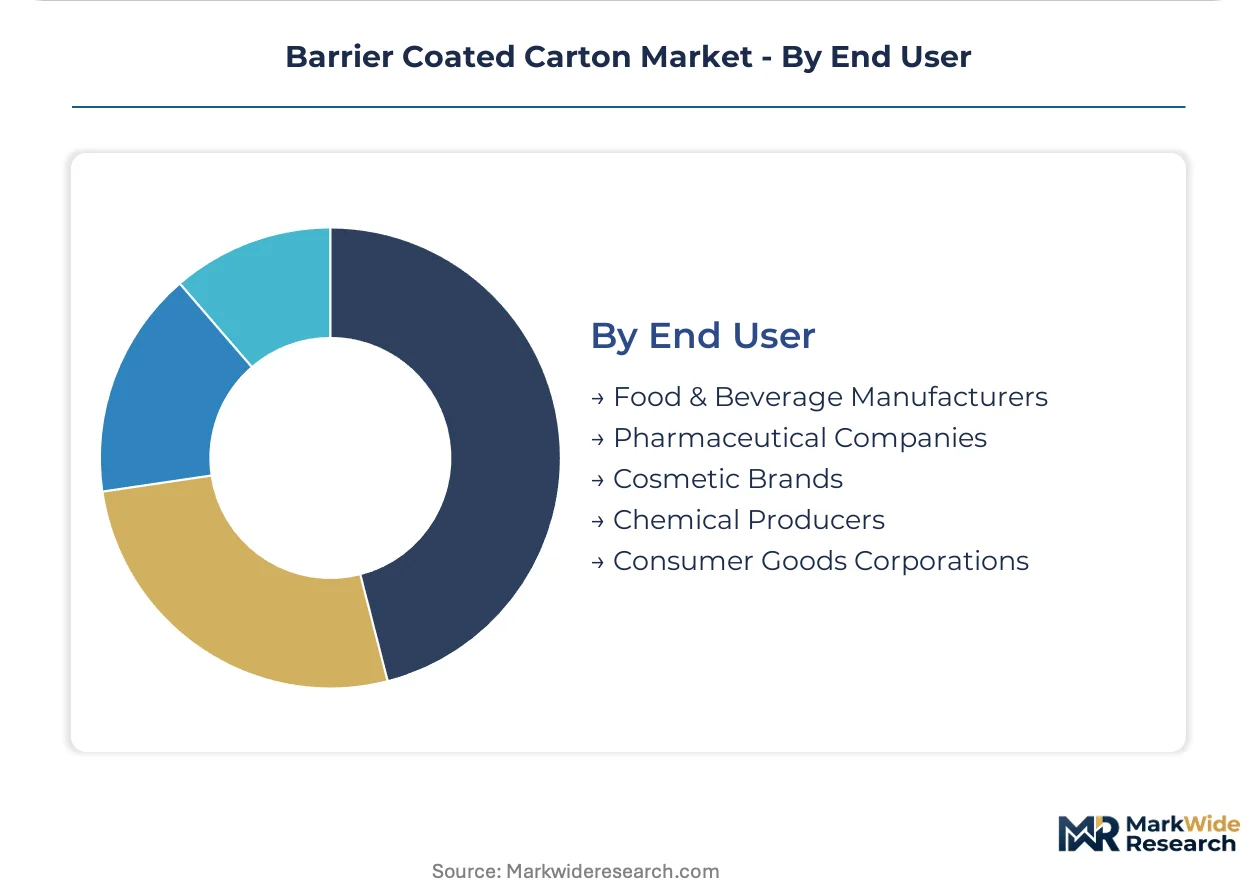
End User:
Procurement consolidation patterns and sustainability mandate intensity reshape converter customer portfolios across end-use categories.
- Food & Beverage Manufacturers:Pan-European dairy and frozen food producers standardize on FSC-certified substrates with identical barrier performance tiers, reducing SKU complexity across Benelux and Nordic manufacturing footprints. Extended producer responsibility fee structures in France and Italy favor demonstrated recyclability.
- Pharmaceutical Companies:Validation timelines and dual FDA-EU compliance burdens extend new barrier formulation commercialization cycles, concentrating supplier relationships on established converters with regulatory affairs capabilities.
- Cosmetic Brands:Premium positioning drives specification of high-barrier boards with distinctive haptic and print surfaces.
- Chemical Producers:Industrial barrier requirements prioritize chemical resistance and UN-certified dangerous goods compatibility.
- Consumer Goods Corporations:Corporate plastic-reduction targets cascade through packaging procurement decisions across household product portfolios.
Food & Beverage Manufacturers anchor volume commitments. Pharmaceutical Companies are gaining share fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German packaging converters anchor European barrier carton production, serving Central European food brands with integrated pulp-to-packaging operations that control substrate quality and barrier consistency.
Germany
Bavarian dairy processors and North Rhine-Westphalia frozen food brands drive specification tightening as EFSA migration limits reshape direct food contact requirements. EU Green Deal fluorine-free mandates force silica-based barrier reformulation by 2026. Stuttgart-area coating specialists pilot acrylic alternatives for 12-month shelf-life applications.
Netherlands
Mid-size dry goods brands in Amsterdam-Rotterdam corridor absorb water-based acrylic barriers that eliminate polyethylene lamination entirely. Extended producer responsibility fee structures favor demonstrated fiber recyclability. Eindhoven-region converters consolidate SKU complexity toward modular barrier add-ons.
France
Paris-based quick-service restaurant chains cascade corporate plastic-reduction targets through procurement decisions. EPR schemes shift recycling cost allocation from municipalities to packaging producers. Lyon-area pharmaceutical cold chain expansion drives moisture-barrier carton adoption for temperature-sensitive distribution.
Belgium
Benelux sustainability procurement mandates standardize on FSC-certified substrates with identical barrier performance tiers. Pan-European manufacturers push unified board grades across regional footprints. Antwerp coating operations serve as technical validation hubs for repulpability thresholds demanded by Nordic paper mills.
United Kingdom
London-headquartered consumer goods corporations enforce corporate plastic-reduction commitments across household product portfolios. Post-Brexit regulatory divergence creates dual UK-EU compliance burdens for barrier formulation notification. Manchester-area converters specialize in short-run digital printing convergence for regional food brand SKU proliferation.
Barrier Coated Carton Market Competitive Landscape
Capacity expansion dominates the current landscape as converters retrofit extrusion coating lines for bio-based polyethylene feedstocks and fluorine-free barrier chemistries. The vendor base clusters around three strategic archetypes: integrated forest products groups with captive pulp supply, specialized flexible packaging converters with extrusion coating expertise, and diversified materials science conglomerates with multi-regional regulatory affairs capabilities. M&A activity concentrates on acrylic coating technology acquisitions and Nordic mechanical recycling cluster partnerships. Geographic expansion into Central European QSR supply chains represents the second dominant competitive vector.
Within the integrated forest products tier, Mondi and Stora Enso exemplify upstream control strategies that link forest certification to downstream sustainability claims. Huhtamaki occupies a specialist position among extrusion coating operators serving quick-service food chains with grease-resistant formats. These three anchors represent divergent responses to EU Green Deal compliance: Mondi emphasizes substrate quality control through pulp-to-packaging integration, Stora Enso leverages renewable materials platforms for circular content positioning, and Huhtamaki targets quick-service restaurant volume commitments through specialized barrier performance tiers.
| Leading Market Players |
|---|
| Amcor |
| Mondi |
| Huhtamaki |
| Graphic Packaging International |
| Stora Enso |
| Sonoco Products |
| Sealed Air |
| DS Smith |
| Coveris |
| Others |
Pricing and Supply Chain Analysis
Backward integration into pulp supply anchors pricing power for integrated forest products groups, allowing substrate quality control to translate into premium barrier consistency claims that command higher contract values from European food brands.
Pricing Analysis
Input-cost pass-through from bio-based polyethylene feedstock volatility shapes contract structures across converter operations. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade moisture barriers with dual FDA-EU validation from commodity food service boards. Cost compression in mid-tier acrylic-coated variants is intensifying because Nordic mechanical recycling clusters concentrate rPE supply. Quick-service restaurant chains exhibit the highest price sensitivity due to volume procurement consolidation, while pharmaceutical companies accept premium positioning for child-resistant validation requirements.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale demand from pan-European food manufacturers seeking unified board grades across manufacturing footprints. Raw material supply concentrates in Germany, Finland, and Sweden where integrated pulp-to-packaging operations control substrate quality. Production draws from Nordic mechanical recycling clusters for post-consumer rPE feedstock and Central European extrusion coating equipment bases. Single-source vulnerability in specialized extrusion coating technician labor pools creates operational risk for bio-based PE blend consistency. Distribution runs through converter-direct relationships with brand procurement teams and packaging specification consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPR fee differentials between France and Italy favor fiber-based packaging with demonstrated recyclability over multi-material flexible alternatives sourced from lower-compliance jurisdictions.
For Market Incumbents: Hedge against acrylic barrier displacement by securing Nordic mechanical recycling cluster partnerships for circular content claims. Defend margin position through EFSA pre-notification dossier investments that compress competitor commercialization timelines. Prioritize extrusion coating line retrofits for fluorine-free grease barrier chemistries ahead of ECHA restriction enforcement.
For New Entrants and Emerging Players: Begin with pharmaceutical cold chain moisture-barrier cartons where validation timelines concentrate supplier relationships on regulatory affairs capabilities. Target Benelux and Nordic sustainability procurement mandates that have standardized on FSC-certified substrates with modular barrier add-ons. Pursue digital printing convergence partnerships for short-run SKU proliferation without plate-changeover delays.
For Investors and Strategic Acquirers: Roll-up economics work for mid-size acrylic coating technology specialists because EPR fee structures in France and Italy create cost advantages over incumbent polyethylene lamination players. Five-to-ten year viability hinges on fluorine-free barrier patent positions. Monitor ECHA restriction proposal implementation timelines as inflection indicators for coating chemistry switching costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Reformulation | ECHA restriction proposals force silica-based coating adoption ahead of 2026 regulatory deadlines. |
| Acrylic Coating Capacity Expansion | Water-based dispersions eliminate polyethylene lamination while meeting European paper mill repulpability thresholds. |
| Nordic Recycling Cluster Partnership | Post-consumer rPE supply agreements secure circular content claims for bio-based feedstock positioning. |
| Pharmaceutical Cold Chain Validation | Moisture-barrier cartons with child-resistance features penetrate temperature-sensitive drug distribution networks. |
| Digital Printing Convergence | Inkjet decoration enables short-run SKU proliferation for regional food brands without plate-changeover delays. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging converter operations managers, brand sustainability procurement leads, ECHA regulatory affairs specialists, and European paper mill technical directors with secondary validation from EU Green Deal implementation documents, EFSA migration limit databases, FSC certification registries, and extended producer responsibility fee structure filings. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segment-weighting approaches distributed value across product type, barrier technology, application, and end user dimensions throughout the forecast period. CAGRs derived from installed extrusion coating line capacity expansion trajectories, bio-based polyethylene feedstock penetration curves, and regulatory deadline acceleration effects. Industry-specific inputs included ECHA restriction proposal implementation timelines and Nordic mechanical recycling cluster output projections.
Several conditions sit outside the modeled scope, including unforeseen polymer chemistry breakthroughs, abrupt EPR fee structure revisions, and trade policy disruptions affecting pulp substrate flows. Forecasts reflect assumptions about regulatory implementation pacing and brand procurement consolidation continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.