
 Breathable Lidding Film Packaging Market | 2026-2036
Breathable Lidding Film Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Breathable Lidding Film Packaging Market Analysis
Polyethylene terephthalate (PET) is repositioning polyvinylidene chloride (PVDC) in high-barrier lidding applications due to cost volatility and recyclability pressures. Sealed Air Corp. leverages its Cryovac heritage in modified-atmosphere expertise to anchor North American protein packaging. Huhtamäki sustains European leadership through fiber-based lidding R&D aligned with single-use plastic directives. Mondi Group specializes in kraft-paper breathable solutions, competing directly against conventional plastic films in fresh produce trays.
Breathable lidding film packaging consists of micro-perforated or inherently permeable membrane structures, typically 20-150 micrometers thick, engineered to balance oxygen and carbon dioxide transmission rates for respiring products. These films prevent anaerobic fermentation while limiting moisture accumulation, extending shelf stability of packaged proteins, produce, and ready meals. Plastic films dominate current volume owing to cost efficiency and seal integrity, though composite structures capture margin pools in pharmaceutical blister applications where barrier gradation matters. Food packaging leads application demand, while pre-cut lid formats grow fastest as tray-sealing automation penetrates mid-tier processors.
FDA food-contact substance notifications govern US market entry for new breathable film chemistries, while EFSA evaluates migration limits for additives in European laminated structures. REACH compliance burdens non-EU exporters with extensive substance registration, effectively filtering supplier bases. Stakeholders must monitor evolving extended producer responsibility schemes, as these frameworks will determine whether mono-material or compostable breathable films become the default compliance pathway.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing multi-layer film structures toward mono-material PE and PP formats, forcing converters to rebuild extrusion capabilities around recyclability rather than barrier performance alone.
Growth Catalysts
- Modified-atmosphere packaging protocols:Retailers in Germany and France are specifying oxygen transmission rate windows of 5,000-15,000 cc/m²/day for fresh produce trays, creating certified supplier tiers.
- Centralized protein distribution:North American meat processors are adopting laser-microperforated lidding films to extend case-ready beef shelf life without retail-level repackaging.
- REACH substance registration:Compliance requirements for laminated adhesive chemistries are filtering European supplier bases toward established compounders with full dossier submissions.
Market Restraints
- Ethylene feedstock volatility:PE resin price swings compress converter margins on fixed-price annual contracts with tray manufacturers.
- Barrier-grade PVDC supply concentration:Two Asian producers control high-clarity PVDC resin for pharmaceutical blister lidding, creating single-source vulnerability.
- Recyclability-versus-barrier tradeoff:Mono-material structures sacrifice moisture vapor transmission rates that multi-layer films achieve, limiting adoption in high-humidity climates.
Strategic Opportunities
- Compostable film substrates:PLA-PHA blends certified under EN 13432 open premium positioning in French and Italian organic produce channels where conventional plastics face restrictions.
- Pre-cut lid automation:Mid-tier US poultry processors are retrofitting tray-sealing lines with vision-guided lid placement, expanding addressable market for roll-stock converters.
- EU extended producer responsibility schemes:Fee modulation favoring recyclable packaging creates margin pools for certified mono-material suppliers over non-compliant imports.
Industry Challenges
- Migration testing capacity:EFSA food-contact evaluations for new additive chemistries face 18-24 month backlogs, delaying product launches.
- Perforation precision engineering:Laser drilling consistency at 50-200 micron diameters requires capital investment in galvo-scanning systems that smaller converters cannot justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breathable Lidding Film Packaging Market |
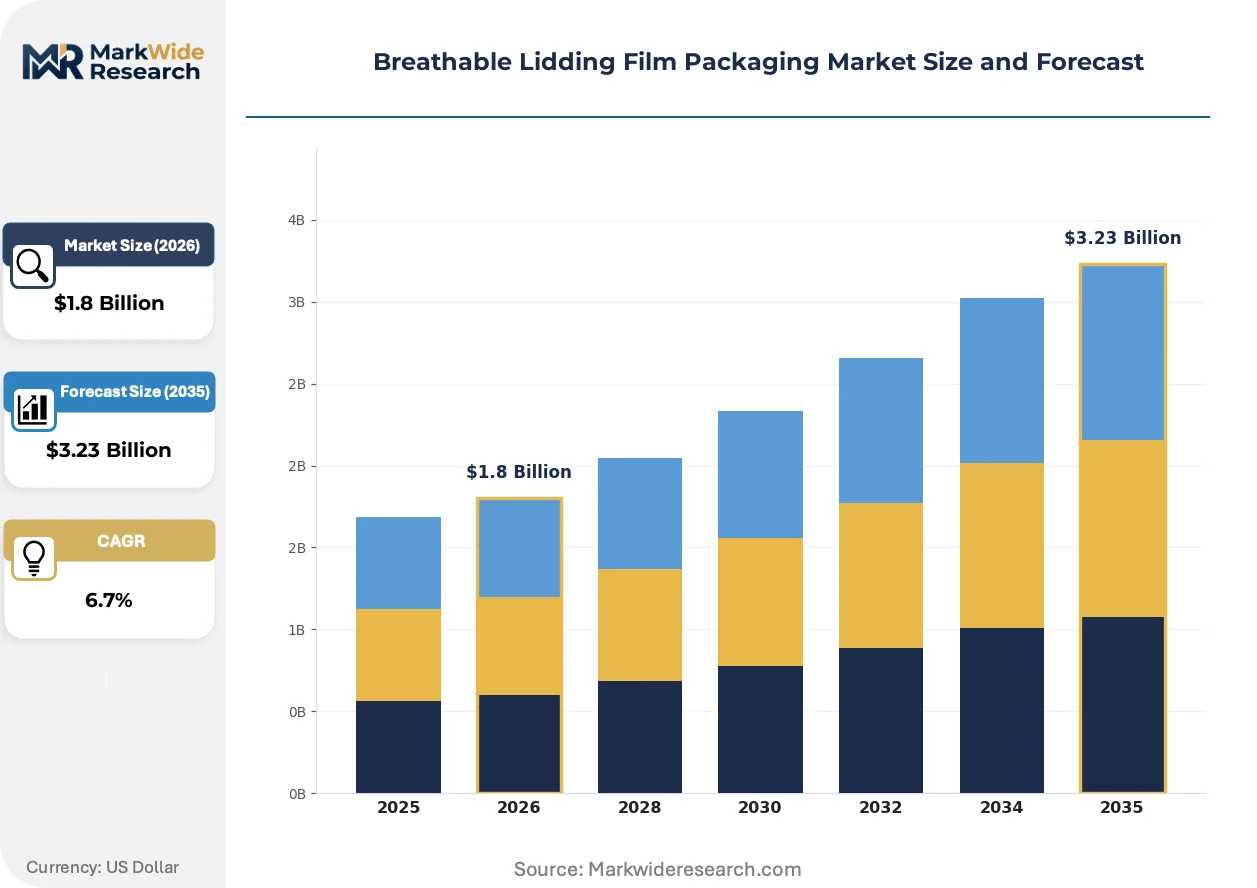
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Paper, Aluminum, Composite Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Electronics Packaging Form: Roll Stock, Pre-Cut Lids, Pouches, Bags End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Electronics Manufacturers |
| Companies Covered | Sealed Air Corp., Huhtamäki, Amcor Plc, Plastopil Hazorea Company Ltd., Sonoco Products Company, Mondi Group, Coveris Holdings, Toray Plastics (America) Inc., Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breathable Lidding Film Packaging Market Emerging Trajectories
Active coating technologies and substrate engineering are converging to redefine breathability as a tunable property rather than fixed film characteristic, enabling segment-specific product architectures.
Laser-microperforation systems are consolidating control over breathable film functionality in high-volume produce applications. Major European salad packagers are retrofitting existing lamination lines with CO₂ laser stations to replace mechanical needle perforation. This shift is consolidating specification power with converters who own in-house perforation capability rather than relying on film suppliers.
REACH authorization requirements for phthalate plasticizers in food-contact laminates are forcing reformulation of legacy adhesive systems. Industrial consequence includes accelerated qualification of bio-based polyurethane alternatives. Fresh protein tray applications in Germany and the Netherlands are most affected, with leading retailers now requiring full substance disclosure to 0.1% threshold.
Consolidation among European retail buying groups is compressing supplier negotiation cycles from annual to quarterly terms. Tray-sealing equipment manufacturers are responding with modular lidding film systems that allow rapid format changeover. This pattern is most visible in Benelux and Scandinavia where three buying groups control 60% of fresh produce shelf space.
Breathable Lidding Film Packaging Market Segmentation
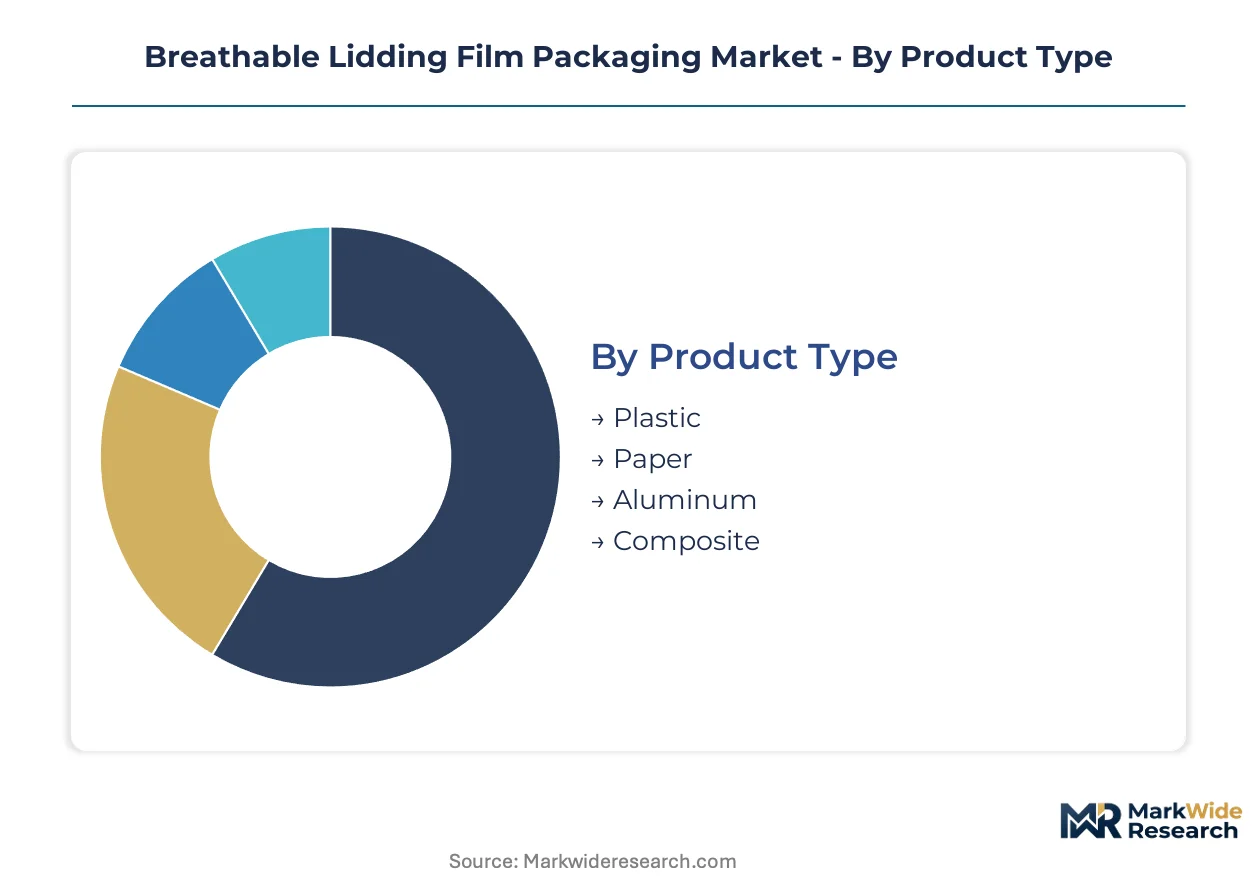
Breathable lidding film packaging exhibits distinct performance requirements across material substrates and end-use applications. Segmentation reveals where regulatory certification burdens concentrate and which product architectures command premium positioning.
Product Type:
EFSA food-contact notifications and FDA substance clearances fall unevenly across material categories, with plastic films carrying the heaviest additive disclosure requirements while paper substrates navigate fiber-sourcing certifications.
- Plastic:Mono-material PE and PP structures dominate volume as converters rebuild extrusion lines around recyclability mandates. German retailers specify oxygen transmission rate windows of 5,000-15,000 cc/m²/day, creating certified supplier tiers for respiring produce trays.
- Paper:Kraft-paper breathable solutions compete directly against plastic films in fresh produce applications. Mondi Group specializes in this segment, aligning with EU single-use plastic directives through fiber-based lidding R&D.
- Aluminum:High-barrier lidding for pharmaceutical blister packs where complete moisture exclusion is required.
- Composite:Multi-layer structures capture margin pools where barrier gradation matters, though EU Packaging and Packaging Waste Regulation compresses adoption toward recyclable alternatives.
Plastic sits at the top of the volume ranking, with Paper climbing the fastest.
Application:
Cost tier differentiation separates commodity tray sealing from premium modified-atmosphere protocols, with protein and produce applications absorbing disproportionate technology investment.
- Food Packaging:Laser-microperforated films extend case-ready beef shelf life in North American protein distribution. Fresh produce drives adoption as retailers seek condensation-free shelf-life extension.
- Pharmaceutical Packaging:Barrier-grade requirements for blister lidding face supply concentration risk with Asian resin producers controlling high-clarity PVDC. Migration testing capacity at EFSA creates 18-24 month qualification backlogs.
- Cosmetic Packaging:Premium positioning for breathable membranes in active-ingredient preservation.
- Electronics Packaging:Moisture vapor transmission control for sensitive component protection during transit.
Food Packaging holds the largest revenue share, with Pharmaceutical Packaging facing the steepest regulatory qualification barriers.
Form:
Automation penetration in mid-tier processing operations is redistributing volume between roll-fed and pre-cut formats.
- Roll Stock:Standard format for high-volume tray-sealing operations with in-house cutting capability.
- Pre-Cut Lids:Vision-guided placement systems are retrofitting poultry processing lines across the US, expanding addressable market for converters. This format gains share fastest as equipment manufacturers deliver modular changeover systems.
- Pouches:Flexible format for irregular produce geometries and portion-controlled protein packs.
- Bags:Bulk breathable packaging for agricultural distribution channels.
Roll Stock maintains volume leadership, with Pre-Cut Lids expanding most quickly through automation adoption.
End User:
Procurement consolidation among retail buying groups is compressing supplier negotiation cycles and favoring converters with multi-format production flexibility.
- Food Manufacturers:Centralized retail distribution in Germany and France creates premium positioning for certified breathable films. Three Benelux and Scandinavian buying groups control 60% of fresh produce shelf space.
- Pharmaceutical Companies:REACH authorization requirements for phthalate plasticizers force adhesive system reformulation, with German and Dutch protein tray applications most affected.
- Cosmetic Brands:Premium channel demand for sustainable packaging substrates.
- Electronics Manufacturers:Industrial procurement emphasizing moisture protection specifications.
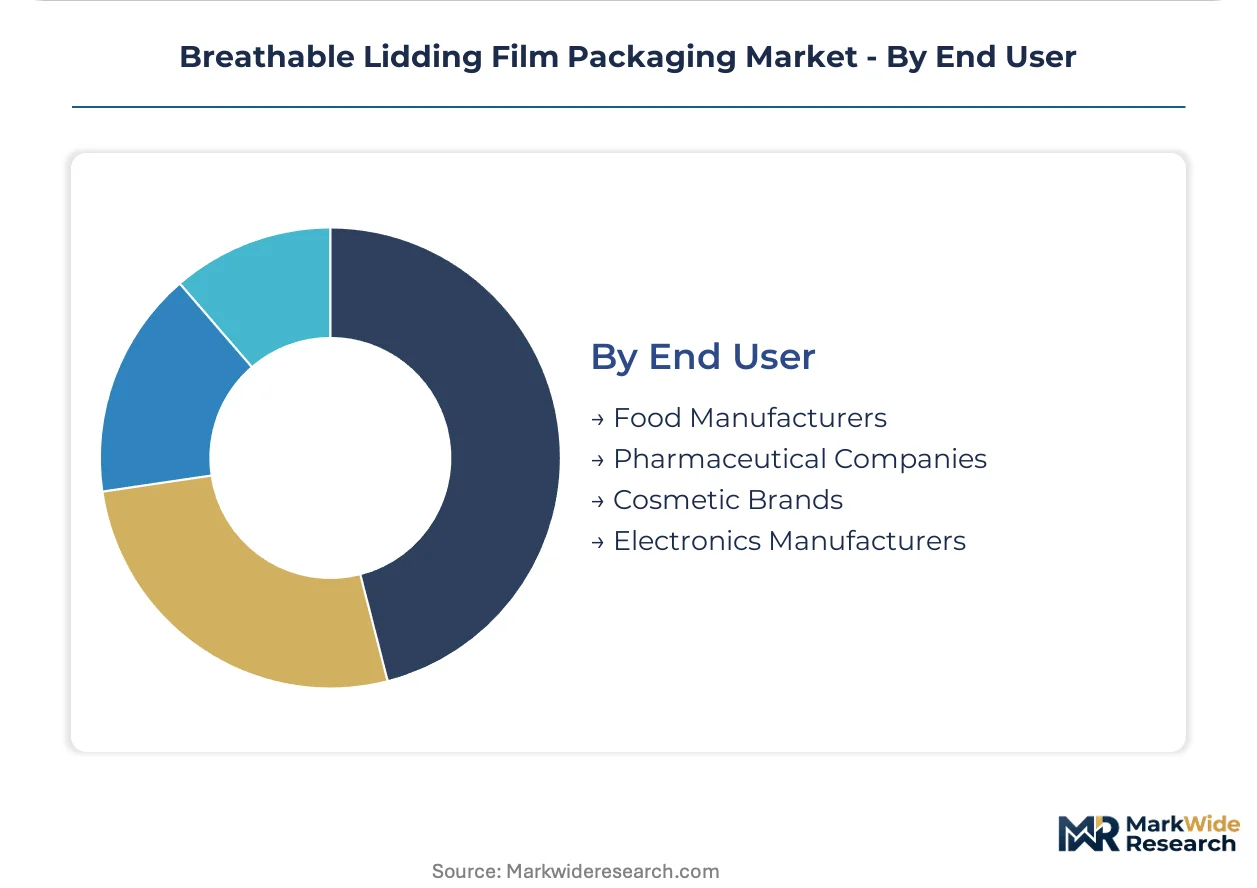
Food Manufacturers represent the dominant demand source, with Pharmaceutical Companies imposing the most stringent substance disclosure thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's centralized retail distribution and strict food-contact compliance create premium positioning for certified breathable films across European fresh produce channels. Retail buying groups in Benelux and Scandinavia compress supplier negotiation cycles from annual to quarterly terms. German converters rebuild extrusion capabilities around mono-material PE and PP formats to meet EU Packaging and Packaging Waste Regulation mandates.
Germany
Modified-atmosphere packaging protocols dominate fresh produce retail, with oxygen transmission rate windows of 5,000-15,000 cc/m²/day creating certified supplier tiers. EFSA evaluates migration limits for additives in laminated structures, filtering supplier bases toward established compounders. The Rhine-Ruhr industrial corridor hosts tray-sealing equipment manufacturers delivering modular lidding film systems for rapid format changeover.
United States
Centralized protein distribution drives laser-microperforated lidding film adoption for case-ready beef shelf-life extension. FDA food-contact substance notifications govern market entry for new breathable film chemistries. Midwest poultry processors retrofit tray-sealing lines with vision-guided lid placement systems, expanding addressable market for roll-stock converters.
France
Compostable film substrates certified under EN 13432 open premium positioning in organic produce channels where conventional plastics face restrictions. REACH authorization requirements for phthalate plasticizers force adhesive system reformulation in fresh protein tray applications. The Lyon-Grenoble corridor concentrates active coating technology development for tunable breathability properties.
China
Barrier-grade PVDC supply concentration creates single-source vulnerability for pharmaceutical blister lidding applications. GB standards and SAMR oversight shape food-contact compliance pathways for imported film structures. The Yangtze River Delta hosts converters serving export-oriented fresh produce packaging demand.
Netherlands
Three buying groups control sixty percent of fresh produce shelf space, consolidating procurement power and favoring multi-format production flexibility. Extended producer responsibility schemes modulate fees toward recyclable packaging, creating margin pools for certified mono-material suppliers. The Rotterdam-Antwerp port cluster facilitates resin import and film export logistics for Benelux converters.
Breathable Lidding Film Packaging Market Vendor Landscape
Capacity expansion dominates the current landscape as converters rebuild extrusion lines around recyclability mandates. The supplier base separates into three tiers: multinational film producers with full regulatory dossiers, regional specialists in laser-microperforation equipment integration, and commodity roll-stock converters serving price-sensitive poultry processors. Strategic archetypes include mono-material PE/PP specialists, fiber-based lidding innovators, and modified-atmosphere technology integrators. M&A activity and geographic expansion into certified supplier tiers represent the dominant competitive moves.
Among diversified packaging conglomerates, Sealed Air Corp., Huhtamäki, and Mondi Group occupy distinct positioning vectors. Sealed Air Corp. represents modified-atmosphere expertise anchored in North American protein packaging heritage. Huhtamäki exemplifies European leadership through fiber-based lidding research aligned with single-use plastic directives. Mondi Group sits within the paper-based breathable solutions archetype, competing directly against conventional plastic films in fresh produce tray applications. These three entities illustrate how regulatory geography and substrate specialization stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Sealed Air Corp. |
| Huhtamäki |
| Amcor Plc |
| Plastopil Hazorea Company Ltd. |
| Sonoco Products Company |
| Mondi Group |
| Coveris Holdings |
| Toray Plastics (America) Inc. |
| Berry Global Inc. |
| Others |
Supply Flow & Price Mechanics
Three Benelux and Scandinavian retail buying groups control sixty percent of fresh produce shelf space, compressing supplier negotiation cycles from annual to quarterly terms and forcing converters toward contract-based long-term offtake pricing with volume-tier discounts.
Pricing Analysis
Ethylene feedstock pass-through clauses dominate converter-processor contracts, with PE resin price swings compressing margins on fixed-price annual agreements. Pricing stratifies across certified mono-material suppliers, established multi-layer converters, and commodity roll-stock producers. Cost compression in the commodity tier intensifies as poultry processors demand ever-tighter unit economics. Pharmaceutical blister applications show least price sensitivity due to barrier-grade PVDC supply concentration and EFSA qualification backlogs.
Supply Chain Analysis
Post-consumer film collection and mechanical recycling flows are rebuilding around mono-material PE and PP streams, with German converters investing in extrusion line retrofits to process recycled content. Resin supply concentrates in Germany, the Netherlands, and Belgium, with the Rotterdam-Antwerp cluster anchoring import-export logistics. Raw material sourcing draws from naphtha crackers, bio-based feedstock pilots, and post-industrial regrind streams. Single-source vulnerability runs through Asian PVDC resin producers for pharmaceutical applications. Distribution runs through centralized retail distribution centers in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on laser-microperforation automation reducing unit costs and certified mono-material structures capturing premium positioning under EU extended producer responsibility fee modulation.
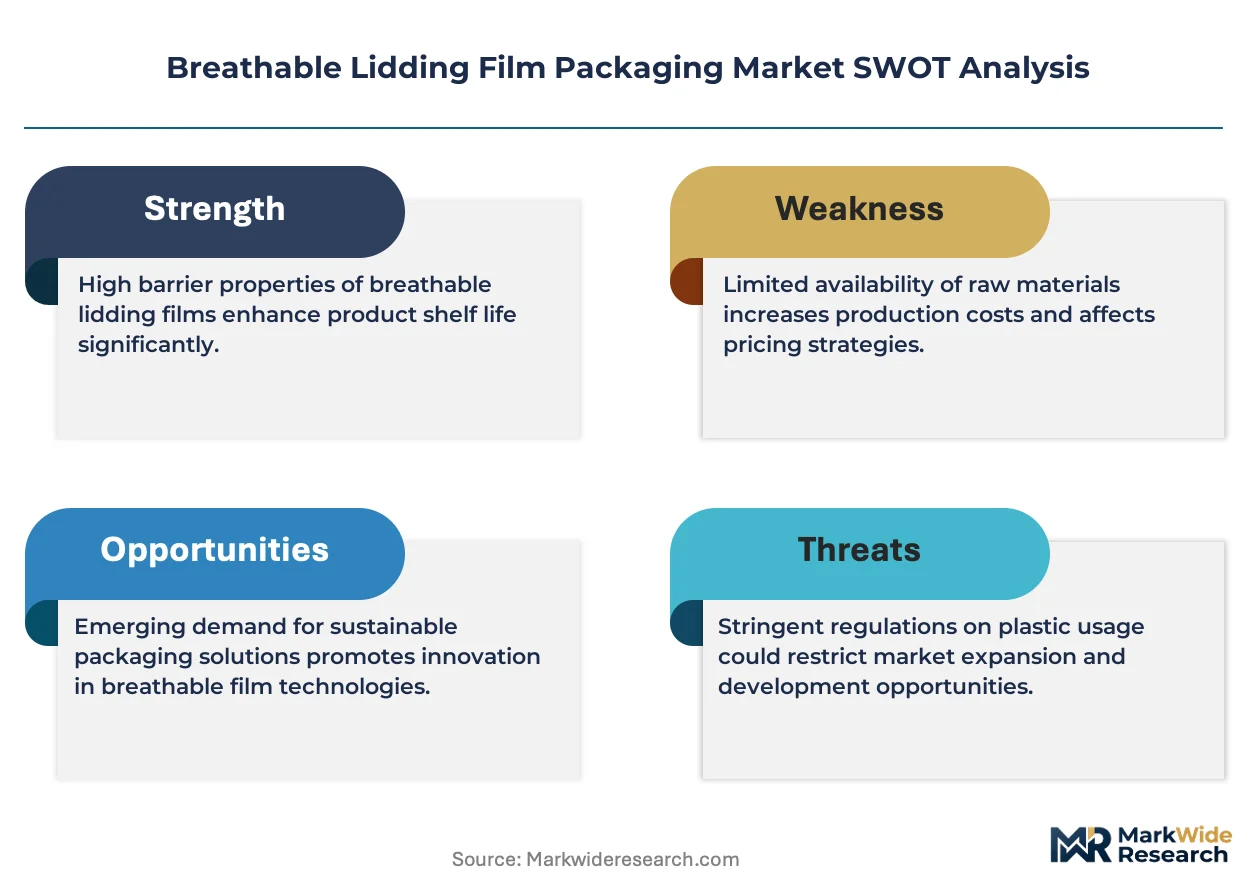
For Market Incumbents: Deepen in-house perforation capability through galvo-scanning system investment, defending against converters who rely on external film suppliers. Secure REACH dossier completeness for adhesive chemistries before EFSA backlogs lengthen further. Capacity addition in the Rhine-Ruhr corridor positions for rapid format changeover demand from retail buying groups. For New Entrants and Emerging Players: E-commerce direct sourcing platforms offer route-to-market bypassing consolidated retail procurement. Target mid-tier US poultry processors retrofitting tray-sealing lines with vision-guided lid placement, the most penetrable automation upgrade cycle. Compostable PLA-PHA substrates certified under EN 13432 open white-space in French and Italian organic produce channels. For Investors and Strategic Acquirers: Packaging conglomerates with full regulatory dossiers are the most active acquirers in this space, consolidating regional specialists in laser-microperforation equipment integration. Long-term viability hinges on mono-material extrusion capability and certified supplier tier access. The signal to watch is EFSA migration testing queue length, as backlogs beyond twenty-four months would trigger qualification-driven M&A.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Line Retrofit | Converters rebuild capabilities around EU Packaging and Packaging Waste Regulation recyclability mandates, securing certified supplier tier access. |
| Laser-Microperforation System Integration | In-house CO₂ laser stations replace mechanical needle perforation, consolidating specification power with converters owning perforation capability. |
| REACH Dossier Completion for Adhesive Chemistries | Full substance registration filters European supplier bases toward established compounders, creating competitive moats. |
| Compostable Substrate Certification | PLA-PHA blends certified under EN 13432 open premium positioning in organic produce channels facing plastic restrictions. |
| Pre-Cut Lid Format Expansion | Vision-guided placement systems retrofitting poultry processing lines expand addressable market for automation-ready converters. |
Methodological Framework
Bottom-up fresh produce and protein packaging modeling reconciled against top-down resin supply and converter capacity tracking forms the analytical core. Primary interviews with tray-sealing equipment manufacturers, film converter procurement leads, retail category buyers, and EFSA regulatory consultants combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, REACH registration databases, and customs trade data. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrices map oxygen transmission rate specifications to resin grade demand, extrusion capacity utilization, and end-use application growth across the projection horizon. Segmentation dimensions include material substrate, application vertical, format type, and end-user procurement tier. CAGRs derive from rolling substitution analysis of mono-material for multi-layer structures and automation penetration curves in mid-tier processing. Industry-specific forecast inputs incorporate EFSA evaluation timelines and laser-microperforation equipment installation rates.
The model assumes a particular technology adoption path; alternative pathways for mechanical recycling versus chemical recycling of mono-material films would alter the outlook. Forecasts reflect documented assumptions about regulatory enforcement timing and retailer specification windows. Practitioners should monitor EFSA backlog length, ethylene feedstock volatility, and retail buying group consolidation velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Barrier Foil Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
Heat Seal Coating Market
Packaging Barrier Films
Nano Sealers Market