
 Flatbed Die Cutters Market | 2026-2036
Flatbed Die Cutters Market Size, Share, and Industry Trends Forecast 2026-2036
Flatbed Die Cutters Market Foresight
E-commerce packaging is restructuring demand across the flatbed die cutters landscape as converters replace legacy equipment with automated lines. BOBST leverages its rotary technology leadership to anchor premium packaging accounts across Europe. Heidelberger Druckmaschinen sustains R&D intensity in digital die-cutting modules for short-run label jobs. Masterwork Machinery dominates cost-engineered semi-automatic units for Asian print shops expanding into corrugated finishing.
Flatbed die cutters employ a fixed platen bed where steel-rule dies or laser beams cut sheeted substrates including paperboard, corrugated fiberboard, and flexible films with precision tolerances near 0.1 mm, serving primary purposes in packaging prototyping, display production, and industrial gasket fabrication. Fully automatic die cutters lead value generation due to pallet-to-pallet automation that reduces labor content in high-volume folding carton plants. Digital die cutters represent the fastest-expanding technology segment as print shops eliminate tooling costs for personalized packaging and variable-data label runs. Waterjet and ultrasonic modalities occupy specialized niches in textile and automotive component fabrication where heat-free cutting preserves material integrity.
OSHA machine guarding standards in the United States and CE marking requirements under the EU Machinery Directive enforce interlocked safety systems and emergency stop protocols that elevate equipment cost but reduce liability exposure for operators. China's SAMR enforces GB standards on electromagnetic compatibility and energy efficiency that filter market access for imported equipment. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal reshape substrate specifications and energy consumption benchmarks for installed equipment fleets.
Market Dynamics
E-commerce packaging volumes are forcing converters to abandon single-purpose die-cutting lines in favor of modular systems that handle variable board grades without tooling changeovers, compressing equipment replacement cycles from seven years toward four.
Growth Catalysts
- REACH substance restrictions:European converters must eliminate certain adhesives and coatings in food-contact packaging, driving replacement of legacy flatbed die cutters that cannot process compliant substrates without contamination risk.
- Automotive lightweighting:OEMs in Germany, Japan, and the United States are expanding captive die-cutting operations for composite gaskets and thermal management materials, pulling high-tonnage equipment demand.
- Laser die-cutting modules:Print shops serving personalized packaging are eliminating steel-rule tooling costs entirely, accelerating adoption in short-run folding carton and label segments.
Market Restraints
- Steel price volatility:Rule die steel and precision platen castings face input cost swings that compress equipment margins and extend quoting cycles for custom configurations.
- Electronics supply concentration:Servo drive systems and motion control components concentrate among Japanese and German suppliers, exposing lead time risks for equipment builders outside those geographies.
- Digital substitution ceiling:Laser and waterjet modalities cannot yet match steel-rule economics above 50,000-unit runs, capping penetration in high-volume corrugated plants.
Strategic Opportunities
- India packaging modernization:Domestic folding carton capacity is expanding faster than finishing equipment installation, creating white space for semi-automatic flatbed systems with localized service networks.
- EU Green Deal energy benchmarks:Equipment retrofits that cut compressed air consumption and enable regenerative braking qualify for member-state efficiency incentives, favoring newer machine generations.
- Digital-physical convergence:Integration of inline inspection and automated die registration is opening premium pricing tiers for quality-critical pharmaceutical and cosmetic packaging runs.
Industry Challenges
- Mechatronics skill scarcity:Servo tuning, vibration analysis, and predictive maintenance diagnostics require technicians that converter workforces rarely possess, forcing equipment vendors to embed remote monitoring or extend field service headcount.
- Legacy system integration:Brownfield plants running 1990s-vintage die cutters face control architecture mismatches when adding automated material handling or quality feedback loops, inflating project complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flatbed Die Cutters Market |
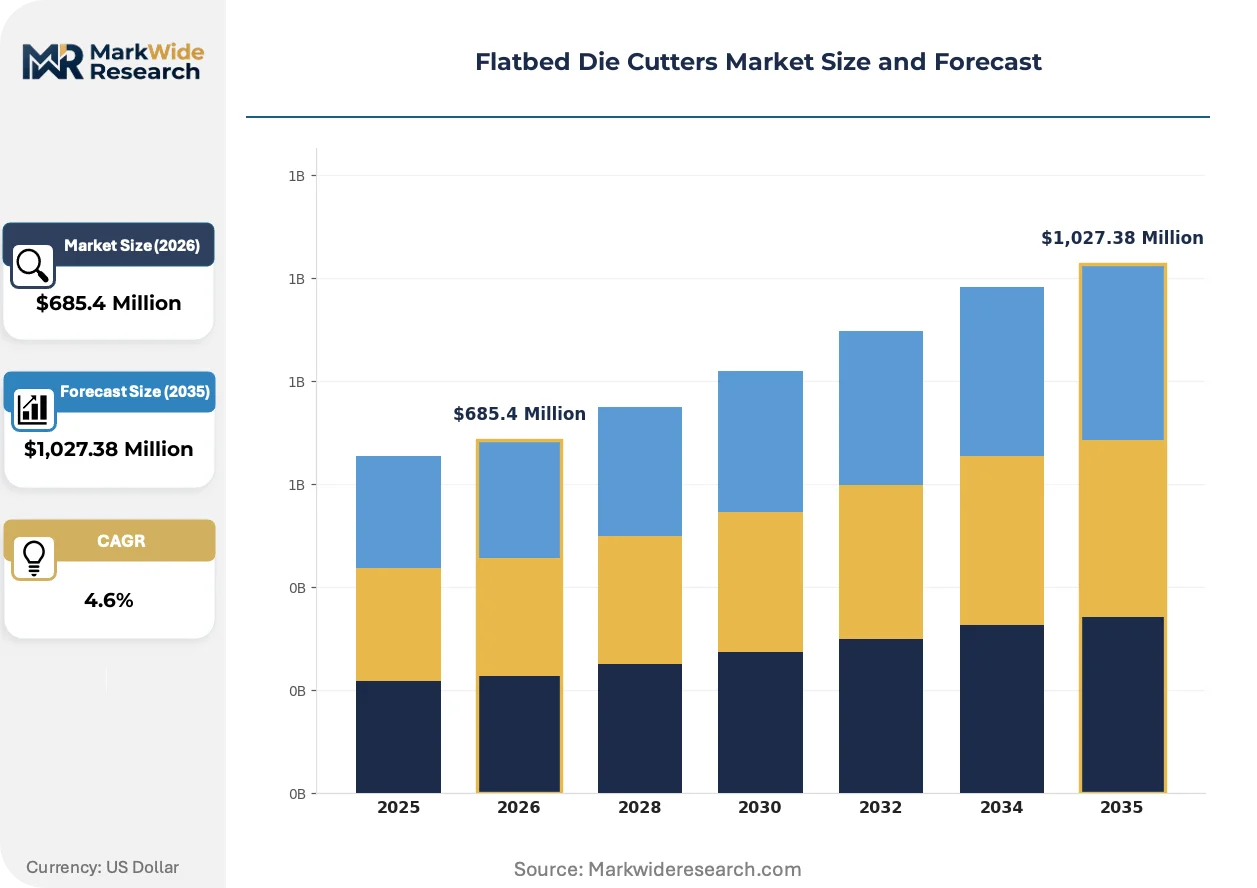
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,027.38 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Die Cutters, Semi-Automatic Die Cutters, Fully Automatic Die Cutters, Digital Die Cutters Technology: Rotary, Laser, Punch, Waterjet, Ultrasonic Application: Packaging, Labeling, Automotive Components, Electronics, Textiles End User: Manufacturers, Print Shops, Custom Fabricators, Advertising Agencies |
| Companies Covered | Heidelberger Druckmaschinen, BOBST, Komori, Koenig & Bauer, Masterwork Machinery, SANWA, Asahi Machinery, Duplo International, Young Shin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flatbed Die Cutters Market Shifts & Advancements
Automation architectures and substrate versatility are converging to redefine equipment specifications, with three developments commanding converter attention through 2035.
Digital die-cutting technology is decentralizing production geography by eliminating tooling lead times that previously forced brands to centralize packaging procurement near die manufacturing clusters. Mid-sized print shops in secondary cities now handle national brand short runs that once required metropolitan converter relationships, compressing the effective service radius of traditional packaging hubs.
China's GB standards on electromagnetic compatibility and energy efficiency are tightening market access for imported flatbed die cutters, forcing non-domestic vendors to redesign control enclosures and motor systems. Equipment builders serving the Chinese market must now certify through SAMR testing protocols that add six to nine months to product launch timelines, advantaging local manufacturers with established compliance pathways.
Converter buying committees are unbundling after-sales service from equipment purchase contracts, treating spare parts and technical support as separately negotiated spend categories. This procurement fragmentation pressures OEM service margins while creating openings for independent technical service providers and third-party spare parts distributors, particularly visible in the United States where maintenance outsourcing rates exceed European norms.
Flatbed Die Cutters Market Segmentation
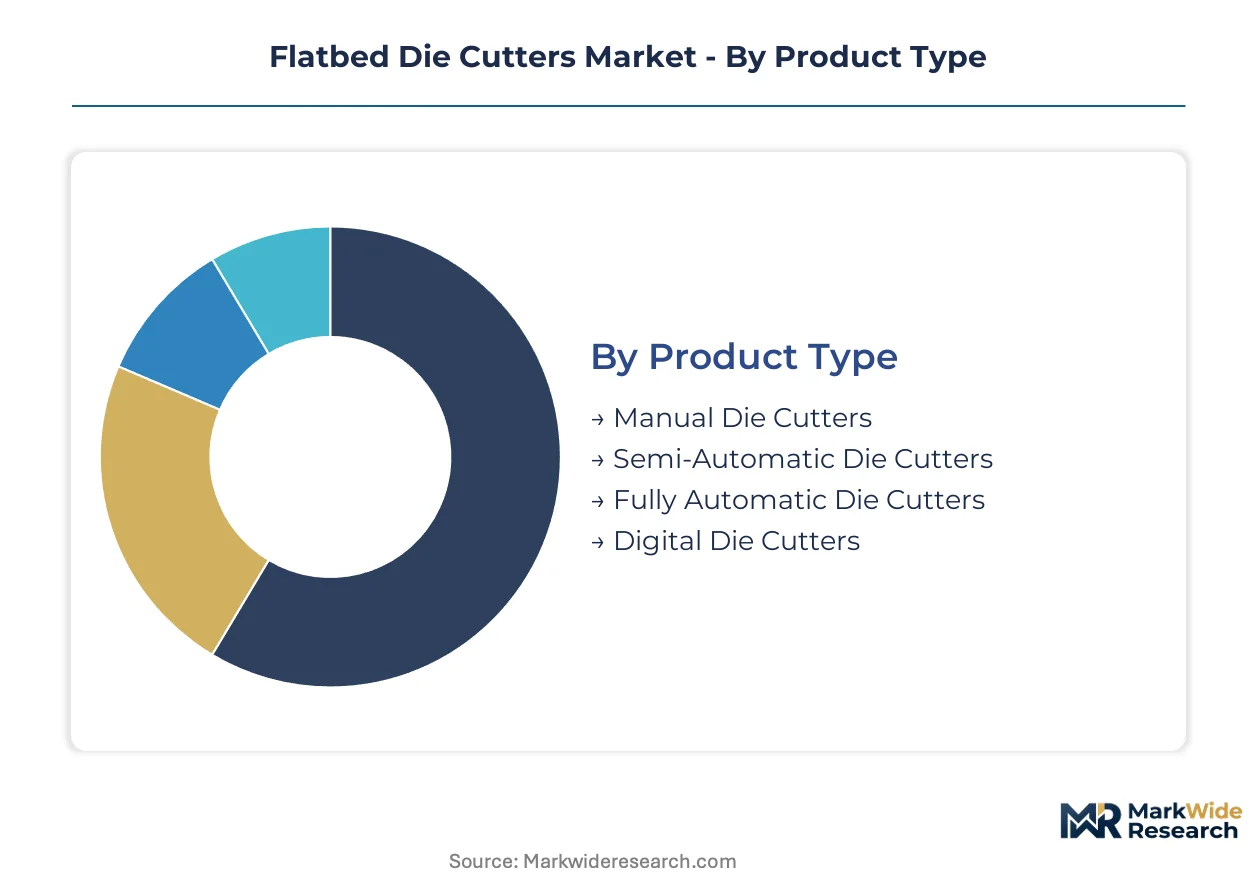
Equipment buyers in the flatbed die cutters market face divergent integration requirements. Some segments operate as standalone finishing lines while others embed directly within broader production workflows. Understanding these structural differences clarifies procurement priorities across converter operations.
Product Type:
Integration depth varies sharply across product types, with standalone manual units at one extreme and fully automated pallet-to-pallet systems at the other.
- Fully Automatic Die Cutters:These systems integrate automatic feeding, die registration, and stacking modules that eliminate manual intervention between pallet loads. German and Japanese automotive OEMs favor these configurations for captive gasket production where throughput consistency outweighs capital intensity.
- Digital Die Cutters:Laser or knife-based systems eliminate steel-rule tooling entirely, enabling same-day turnaround on personalized packaging runs. Print shops in secondary US cities deploy these to capture short-run folding carton work that previously required metropolitan converter relationships.
- Semi-Automatic Die Cutters:Require operator-assisted feeding and stacking while automating the cutting stroke itself.
- Manual Die Cutters:Hand-cranked or foot-pedal operated units for prototyping and very low-volume specialty work.
Fully automatic die cutters lead volumes today; digital die cutters are gaining share fastest.
Technology:
Cost tier separation distinguishes rotary systems as premium infrastructure against emerging modalities competing on specialized material handling.
- Rotary:Cylindrical dies mounted on rotating drums enable continuous web processing at speeds exceeding flatbed platen cycles. European folding carton plants specify rotary configurations for high-volume pharmaceutical and cosmetic packaging where registration tolerances must hold within 0.1 mm.
- Laser:CO2 or fiber laser sources vaporize substrate material without mechanical contact, eliminating die manufacturing lead times and storage costs. Label converters serving variable-data pharmaceutical serialization requirements favor laser systems for lot-specific coding integration.
- Punch:Mechanical stroke systems using steel-rule dies on fixed platens, the conventional technology baseline.
- Waterjet:High-pressure abrasive streams cut heat-sensitive composites without thermal degradation, serving automotive thermal management material fabrication.
- Ultrasonic:High-frequency vibration cutting for synthetic textiles and nonwovens where fused edges prevent fraying.
Rotary technology commands the installed base; laser systems show the steepest expansion trajectory.
Application:
Application focus determines whether equipment operates in continuous production environments or project-based job shop settings.
- Packaging:Folding carton and corrugated finishing represents the dominant volume application, with e-commerce fulfillment driving replacement of legacy single-purpose lines. Converters prioritize modular systems handling variable board grades without tooling changeovers.
- Automotive Components:Composite gasket and thermal barrier fabrication requires high-tonnage equipment with specialized nesting software to minimize expensive material waste. Captive operations at German and Japanese OEMs pull dedicated system configurations.
- Labeling:Pressure-sensitive and shrink-sleeve label production favors narrower web formats with precision die registration.
- Electronics:Flexible circuit and membrane switch fabrication demands cleanroom-compatible configurations with electrostatic control.
- Textiles:Apparel and technical textile cutting employs ultrasonic or waterjet modalities for sealed or heat-free edges.
Packaging dominates current procurement volumes; automotive components are climbing the fastest as lightweighting accelerates.
End User:
Customer type segmentation reveals divergent buying behaviors between capital-intensive manufacturers and service-oriented fabricators.
- Manufacturers:Captive packaging operations at consumer goods and automotive companies specify fully automatic lines with inline quality systems. These buyers negotiate multi-year service contracts and prioritize equipment uptime guarantees over initial purchase price.
- Print Shops:Commercial printing operations expanding into finishing require semi-automatic or digital systems with shorter payback periods. US-based shops increasingly unbundle after-sales service from equipment purchase contracts, treating maintenance as separately negotiated spend.
- Custom Fabricators:Job shops serving advertising displays and industrial gaskets favor flexible configurations handling diverse substrates.
- Advertising Agencies:In-house production units for retail display and promotional materials prioritize compact footprints and rapid setup capabilities.
Manufacturers represent the largest equipment purchaser category today; print shops are expanding share fastest through digital die-cutter adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier corridor stretching from Stuttgart to Munich generates sustained demand for high-tonnage flatbed die cutters serving captive gasket and thermal management material production.
United States
Automotive OEMs in Michigan and Ohio operate captive die-cutting facilities for composite gasket fabrication. OSHA machine guarding standards enforce interlocked safety systems that elevate equipment costs. Detroit-area converter clusters are replacing legacy lines with modular systems handling variable board grades for e-commerce packaging fulfillment.
Germany
REACH substance restrictions are eliminating legacy adhesives in food-contact packaging, forcing equipment replacement among Baden-Württemberg folding carton producers. The EU Machinery Directive mandates CE marking with emergency stop protocols. Bavarian pharmaceutical packaging clusters specify fully automatic lines with registration tolerances within 0.1 mm.
China
Domestic print shops in the Yangtze River Delta are expanding corrugated finishing capacity faster than equipment installation rates. SAMR enforces GB standards on electromagnetic compatibility and energy efficiency that filter market access for imported machines. Shanghai and Suzhou converter clusters favor cost-engineered semi-automatic units from local manufacturers with established compliance pathways.
Japan
Electronics OEMs in the Kanto region maintain captive operations for flexible circuit and membrane switch fabrication. METI oversees industrial machinery standards that influence servo drive specifications. Tokyo-Osaka industrial corridors concentrate demand for cleanroom-compatible configurations with electrostatic control systems.
India
Folding carton capacity in Maharashtra and Gujarat is expanding faster than finishing equipment installation, creating white space for semi-automatic systems. BIS certification requirements shape import equipment specifications. Mumbai-Pune converter clusters prioritize localized service networks over premium automation features for mid-volume pharmaceutical packaging runs.
Flatbed Die Cutters Market Competitive Landscape
Technology licensing dominates the current landscape as equipment builders secure servo drive and motion control partnerships to reduce supply concentration risks. The vendor base organizes around three tiers: premium European manufacturers with rotary technology leadership, Asian specialists in cost-engineered semi-automatic configurations, and emerging digital die-cutting entrants. Strategic archetypes include automation-focused system integrators, substrate versatility specialists, and regional service network builders. M&A activity and geographic expansion through localized assembly operations represent the two dominant competitive vectors reshaping market presence.
Among German-origin precision machinery builders, Heidelberger Druckmaschinen AG and Koenig & Bauer AG occupy positions within the premium automation tier, exemplifying sustained R&D intensity in digital die-cutting modules. BOBST S.A., headquartered in Switzerland, anchors the rotary technology leadership archetype across European pharmaceutical and cosmetic packaging accounts. Japanese specialists Komori Corporation and Asahi Machinery Co., Ltd. sit within the precision registration segment, representing the concentration of servo drive expertise in Nagoya and Tokyo industrial basins. Chinese equipment builders including Masterwork Machinery Co., Ltd. exemplify the cost-engineered semi-automatic archetype serving Asian print shop expansion into corrugated finishing.
| Leading Market Players |
|---|
| Heidelberger Druckmaschinen |
| BOBST |
| Komori |
| Koenig & Bauer |
| Masterwork Machinery |
| SANWA |
| Asahi Machinery |
| Duplo International |
| Young Shin Industries |
| Others |
Supply & Pricing Matrix
Rule die steel price indices cascade through flatbed die cutter manufacturing tiers, compressing margins on semi-automatic configurations while premium rotary systems absorb volatility through long-term automotive contracts. Japanese and German servo drive suppliers transmit component scarcity into extended quoting cycles that favor equipment builders with captive control system production.
Pricing Analysis
Input-cost pass-through from rule die steel and precision platen castings stratifies pricing across three tiers. Premium-mid-economy pricing differentiation separates fully automatic pallet-to-pallet systems with CE certification from semi-automatic units lacking interlocked safety modules. Cost compression in the semi-automatic tier is intensifying because Yangtze River Delta manufacturers compete on localized GB compliance rather than feature depth. Print shops in secondary Indian cities exhibit highest price sensitivity, while German automotive OEMs prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Shanghai coordinate hub-and-spoke patterns for spare parts and retrofit modules. Component manufacturing concentrates in Germany, Japan, and China, with servo drive systems and motion control modules drawing from Nagoya and Tokyo industrial basins. Supply chain risk centers on single-source vulnerability for high-precision linear encoders and specialized cutting rule alloys. Distribution runs through OEM-direct channels for fully automatic systems and independent distributors for semi-automatic units in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flatbed die cutters market functions as a stable compounder anchored by e-commerce packaging volume growth that sustains equipment replacement cycles regardless of macroeconomic softness.
For Market Incumbents: Anchor premium positioning through backward integration into servo drive calibration capabilities, reducing exposure to Japanese supplier concentration. Defend against digital die-cutting entrants by embedding remote diagnostics and predictive maintenance modules that converter workforces cannot replicate internally. CE marking investments and REACH-compliant substrate handling certifications create switching costs among European pharmaceutical packaging accounts. For New Entrants and Emerging Players: Enter via India's Maharashtra and Gujarat folding carton corridors where domestic capacity expansion outpaces finishing equipment installation. Target semi-automatic configurations with localized service networks rather than premium automation features. Partner with Yangtze River Delta component suppliers to accelerate SAMR compliance timelines and undercut established import channels on total cost of ownership. For Investors and Strategic Acquirers: Asymmetric upside sits with digital die-cutting module specialists serving variable-data pharmaceutical serialization requirements. Long-term viability favors equipment builders with installed base scale sufficient to monetize unbundled after-sales service contracts. Watch laser cutting speed benchmarks relative to steel-rule economics above 50,000-unit runs as the inflection signal for technology substitution ceilings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Systems | Reduces lead time exposure from Nagoya and Tokyo component suppliers. |
| GB Standards Certification Investment | Unlocks SAMR market access for imported equipment in Yangtze River Delta clusters. |
| Remote Diagnostics Platform Deployment | Addresses mechatronics skill scarcity in converter maintenance workforces. |
| Localized Assembly Operations in India | Captures Maharashtra and Gujarat folding carton modernization demand. |
| Digital Die-Cutting Module Development | Eliminates tooling costs for short-run pharmaceutical and cosmetic packaging. |
Research Methodology
Bottom-up packaging converter modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads informed operational assumptions. Secondary validation drew from customs trade data, SEC 10-K filings of listed machinery builders, SAMR certification registries, and EU Machinery Directive compliance databases. Triangulation between demand-side converter capacity expansion and supply-side production schedules refined volume estimates.
Historical trendline analysis of replacement cycle compression and technology substitution patterns established baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include automation level, cutting technology, end-use application, and regional regulatory cluster. CAGRs were derived from equipment unit economics and substrate volume elasticities specific to e-commerce packaging fulfillment and automotive lightweighting material demand.
Inputs from primary fieldwork and secondary databases were available through the study window; gaps in real-time converter capital expenditure intentions introduce uncertainty bands around near-term shipment forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Hang Tag Applicators Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
PET Preform Machine Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Labeling Equipment Market
Packaging Equipment
Loose Fill Packaging Systems Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Linear Net Weighing Machines Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Strapping and Banding Equipment Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
France Foam Pumps Market