
 Transparent Barrier Films Market | 2026-2036
Transparent Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Barrier Films Market Analytics
Asian petrochemical producers is hardening the supply base for ethylene-vinyl alcohol copolymers used in high-barrier stacks. Amcor Plc leverages its integrated film-to-package network across Australasia to sustain margin capture. DuPont de Nemours Inc. anchors North American supply through captive resin production and proprietary ionomer know-how.
Transparent barrier films are multilayer polymer structures, typically incorporating polyethylene terephthalate, polyamide, or aluminum oxide vapor-deposited layers, engineered to block oxygen and moisture transmission below specified permeability thresholds for shelf-life extension. Polymer films dominate volume shipments for food packaging where clarity and flex-crack resistance matter most, while metalized films command premium positioning in electronics shielding where electromagnetic interference attenuation drives specification. Vacuum deposition technology is displacing conventional coating for ultra-thin barrier layers in organic photovoltaics and flexible display backplanes.
The FDA enforces stringent extractables and leachables protocols for pharmaceutical contact films, while the EU's REACH framework governs monomer and additive substance authorization across the value chain. Japan's METI maintains voluntary labeling standards for food-contact barrier performance that de facto shape export specifications. Stakeholders must monitor how California's Safer Consumer Products regulations and emerging per- and polyfluoroalkyl substance restrictions in the European Union redefine acceptable barrier chemistries before next-generation material platforms achieve scale.
Market Dynamics
Solvent-free coating technologies are consolidating technical leadership as the EU's F-Gas Regulation eliminates fluorinated gas-based deposition processes, forcing converters to rebuild process lines around water-based and UV-curable alternatives.
Growth Catalysts
- Pharmaceutical stability mandates:FDA extractables and leachables protocols for blister packaging are tightening oxygen permeability thresholds, pulling multilayer EVOH structures into standard formularies.
- REACH substance authorization:The EU's framework is accelerating substitution of legacy barrier chemistries with bio-based polyamides and aluminum oxide vapor-deposited layers.
- Organic photovoltaics manufacturing:Vacuum deposition technology is displacing conventional coating for ultra-thin barrier layers in flexible display backplanes and solar cell encapsulation.
Market Restraints
- Ethylene-vinyl alcohol supply concentration:Asian petrochemical producers control upstream copolymer resin supply, exposing converters to feedstock allocation risk during cracker maintenance cycles.
- Aluminum oxide deposition capex intensity:Roll-to-roll vacuum coating equipment requires significant capital outlay, limiting mid-scale converter participation in premium barrier segments.
- Per- and polyfluoroalkyl substance restrictions:Emerging EU limitations on PFAS chemistries threaten fluoropolymer-based barrier coatings before next-generation platforms achieve commercial scale.
Strategic Opportunities
- Japan's voluntary labeling standards:METI's food-contact barrier performance guidelines are de facto shaping export specifications for converters targeting premium Asian retail chains.
- California Safer Consumer Products regulations:The state's chemical prioritization process is creating first-mover advantage for barrier film suppliers with pre-validated green chemistry portfolios.
- Flexible electronics convergence:Integration of transparent barrier films with printed circuit substrates and quantum dot encapsulation is opening adjacent revenue pools beyond traditional packaging.
Industry Challenges
- Vacuum deposition technician scarcity:Specialized process engineering expertise for thin-film aluminum oxide and silicon oxide deposition remains concentrated among legacy display industry talent pools.
- Multilayer lamination certification timelines:Pharmaceutical contact film validation under FDA protocols extends commercialization cycles by 18-24 months versus food-grade equivalents.
- Legacy solvent coating line stranding:Converters face asset write-down pressure as environmental compliance costs render conventional coating infrastructure economically unviable.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Barrier Films Market |
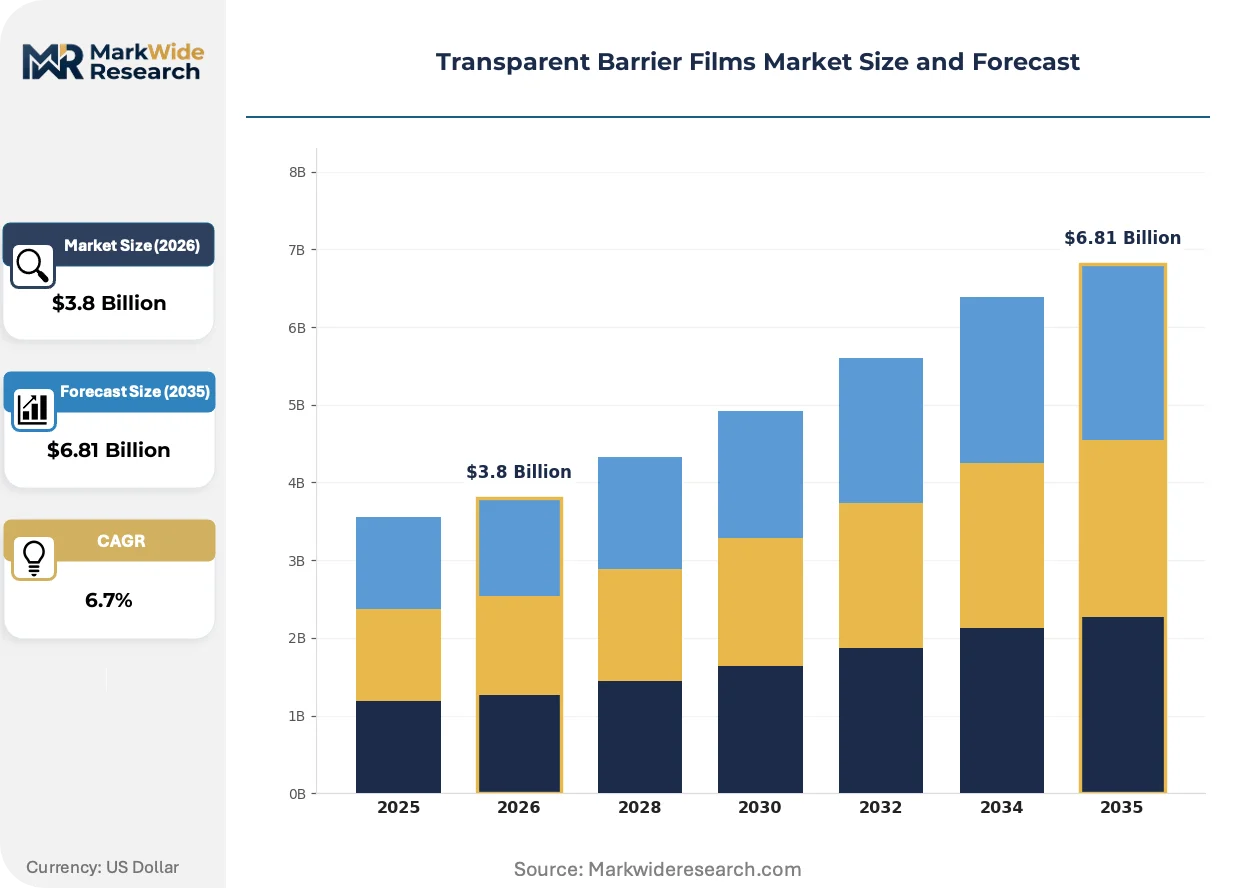
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Films, Metalized Films, Coated Films, Laminated Films Application: Packaging, Electronics, Healthcare, Automotive End User: Food Industry, Pharmaceutical Companies, Consumer Electronics, Personal Care Technology: Extrusion, Co-extrusion, Vacuum Deposition, Printing |
| Companies Covered | Amcor Plc, 3M Co., Sealed Air Corp., Mondi Plc, Berry Global Inc., Cosmo Films Ltd., DuPont de Nemours Inc., Toppan Inc., UFlex Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Barrier Films Market Evolving Landscape
Active materials integration and deposition technology convergence are redefining performance benchmarks, with clarity and barrier function no longer treated as trade-offs but as simultaneously optimizable parameters.
Atomic layer deposition is consolidating process control for sub-100 nanometer barrier layers on temperature-sensitive polymer substrates. Organic photovoltaics manufacturers in Germany and Japan are adopting ALD-equipped roll-to-roll lines to achieve water vapor transmission rates below 10^-4 g/m²/day. This precision is compressing the performance gap between polymer films and glass encapsulation in flexible device applications.
The EU's F-Gas Regulation is banning hydrofluorocarbon-based plasma etching and cleaning processes in barrier film manufacturing from 2030. Converters in Germany's Düsseldorf-Cologne industrial corridor are retrofitting deposition chambers with nitrogen trifluoride alternatives and cryogenic recovery systems. Pharmaceutical packaging specifications are tightening fastest, with EMA guidance now requiring documented fluorinated gas phase-out roadmaps for new product approvals.
Brand-owner sustainability scorecards are reshaping supplier selection criteria for transparent barrier films. Major European food retailers are embedding carbon footprint thresholds into procurement contracts, displacing virgin petrochemical grades with mechanically recycled PET and bio-based polyamide alternatives. This behavioral shift is most visible in Germany, where private-label packaging accounts for concentrated demand volume and sustainability compliance determines shelf access.
Transparent Barrier Films Market Segmentation
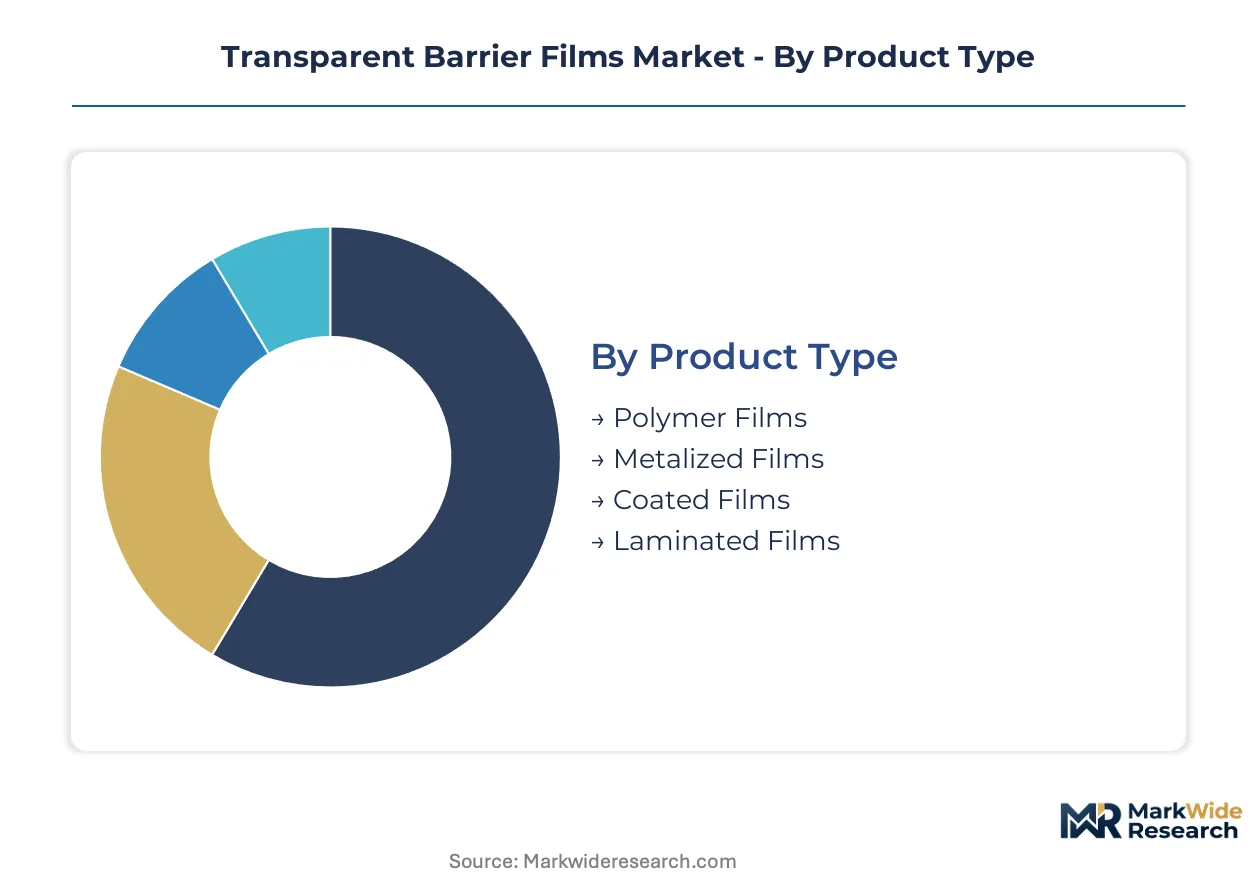
Transparent barrier films serve divergent performance requirements across packaging precision, electronic protection, and medical safety. Segmentation reveals how material architecture and manufacturing method determine addressable end-use economics and regulatory compliance burden.
Product Type:
Technical specification and barrier mechanism define competitive positioning across film architectures.
- Polymer Films:Multilayer structures incorporating EVOH or polyamide cores achieve oxygen transmission rates below 1 cc/m²/day without metallization. Food packaging in Germany's retail chains concentrates demand where clarity and flex-crack resistance override ultra-high barrier requirements.
- Metalized Films:Aluminum vapor-deposited layers deliver electromagnetic interference attenuation exceeding 60 dB for electronics shielding applications. Japanese consumer electronics manufacturers specify these grades for flexible circuit protection where signal integrity is paramount.
- Coated Films:Solvent-free and UV-curable barrier coatings on PET substrates address tightening EU F-Gas Regulation compliance timelines.
- Laminated Films:Adhesive-bonded multilayer stacks combine dissimilar polymers for pharmaceutical blister packaging requiring FDA-validated extractables profiles.
Polymer films lead on scale; metalized films lead on momentum as flexible electronics proliferation accelerates specification migration.
Application:
End-use performance thresholds stratify procurement criteria and certification burden.
- Packaging:Shelf-life extension for oxygen-sensitive foods and pharmaceuticals drives specification of EVOH-based structures with WVTR below 0.5 g/m²/day. German private-label retailers embed carbon footprint thresholds into supplier scorecards.
- Electronics:Flexible display backplanes and organic photovoltaics require water vapor transmission rates below 10^-4 g/m²/day achievable only through atomic layer deposition or advanced vacuum coating.
- Healthcare:FDA extractables and leachables protocols extend validation cycles for pharmaceutical contact films.
- Automotive:Interior lighting encapsulation and sensor protection applications specify barrier clarity under thermal cycling stress.
Packaging dominates volume throughput; electronics commands the steepest expansion trajectory as ALD-equipped roll-to-roll capacity scales.
End User:
Regulatory exposure and sustainability disclosure requirements differentiate customer procurement behavior.
- Food Industry:European retailers' sustainability scorecards prioritize mechanically recycled PET and bio-based polyamide alternatives over virgin petrochemical grades.
- Pharmaceutical Companies:EMA guidance now requires documented fluorinated gas phase-out roadmaps for new barrier film product approvals.
- Consumer Electronics:Japanese manufacturers leverage METI voluntary labeling standards as de facto export specifications for premium Asian retail chains.
- Personal Care:California Safer Consumer Products regulations create first-mover advantage for suppliers with pre-validated green chemistry portfolios.
Food industry absorbs the highest absolute tonnage; pharmaceutical companies impose the most stringent qualification protocols.
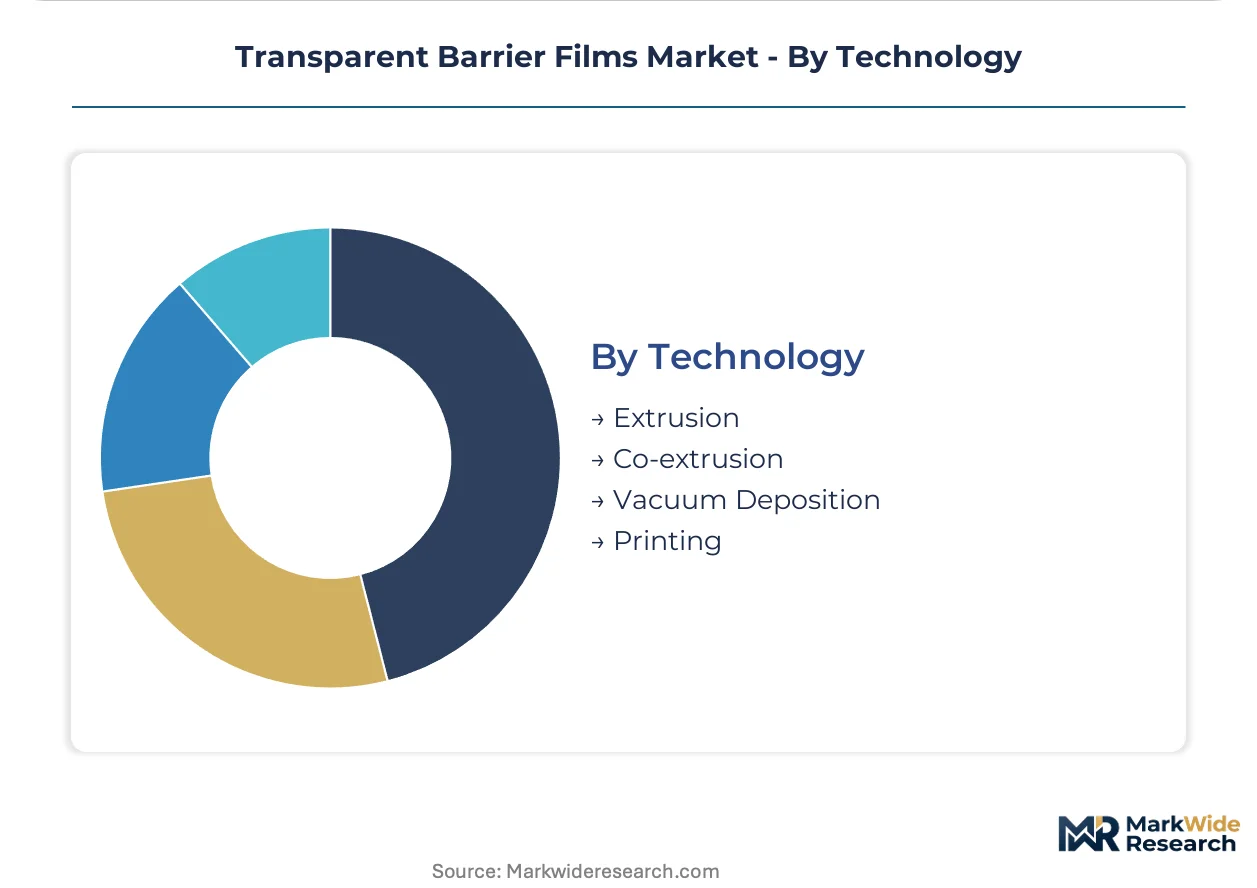
Technology:
Capital intensity and process expertise determine converter participation thresholds across deposition and forming methods.
- Extrusion:Cast and blown film lines produce base substrates for subsequent barrier enhancement, with Asian petrochemical producers controlling upstream EVOH resin supply.
- Co-extrusion:Simultaneous multi-polymer forming creates integral multilayer structures without adhesive lamination, reducing interlayer contamination risk for pharmaceutical applications.
- Vacuum Deposition:Roll-to-roll aluminum oxide and silicon oxide coating requires specialized process engineering expertise concentrated among legacy display industry talent pools.
- Printing:Gravure and flexographic methods apply functional barrier coatings with lower capital barriers than vacuum deposition.
Extrusion anchors baseline capacity; vacuum deposition concentrates margin capture in premium barrier segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing transparent barrier film production toward jurisdictions with lower compliance costs for solvent-free coating transitions, while EU-based converters absorb stranded asset write-downs from fluorinated gas phase-out mandates.
Germany
Pharmaceutical blister packaging specifications from EMA drive EVOH multilayer adoption in the Düsseldorf-Cologne corridor. The EU's F-Gas Regulation forces vacuum deposition retrofits with nitrogen trifluoride alternatives by 2030. Converters around Düsseldorf are rebuilding process lines around water-based coatings ahead of compliance deadlines.
United States
FDA extractables and leachables protocols tighten oxygen permeability thresholds for drug contact films. California's Safer Consumer Products regulations prioritize suppliers with pre-validated green chemistry portfolios. Midwest converters serving pharmaceutical clients extend validation cycles 18-24 months versus food-grade equivalents.
Japan
METI voluntary labeling standards for food-contact barrier performance shape export specifications across premium Asian retail chains. Consumer electronics manufacturers specify metalized films for flexible circuit protection where signal integrity dominates. Kansai-based producers leverage these de facto standards to capture regional premium positioning.
China
Asian petrochemical producers harden EVOH copolymer supply control, exposing converters to feedstock allocation risk during cracker maintenance. The country's national chemical regulator enforces dual carbon goals that accelerate solvent-free coating adoption. Yangtze River Delta converters face margin compression from resin import dependency.
India
Domestic pharmaceutical packaging demand pulls multilayer barrier structures into standard formularies as CDSCO aligns with international stability mandates. The PLI scheme for specialty chemicals incentivizes local coating technology development. Maharashtra-based converters target import substitution for high-barrier pharmaceutical grades.
Transparent Barrier Films Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electronics shielding and flexible display encapsulation where ALD-equipped capacity concentrates margin capture. The market structures around three player archetypes: integrated resin-to-film operators with captive EVOH supply, specialist vacuum deposition houses serving device manufacturers, and regional laminators competing on pharmaceutical validation speed. Dominant competitive moves include backward integration into resin production and technology licensing partnerships for atomic layer deposition scale-up.
Among integrated packaging networks, Amcor Plc and Sealed Air Corp. exemplify the resin-to-package archetype with Australasia and North American manufacturing footprints respectively. DuPont de Nemours Inc. anchors the materials science tier through proprietary ionomer positioning. These three occupy positions across the premium-standard spectrum without overlapping direct competition in identical end-use segments.
| Leading Market Players |
|---|
| Amcor Plc |
| 3M Co. |
| Sealed Air Corp. |
| Mondi Plc |
| Berry Global Inc. |
| Cosmo Films Ltd. |
| DuPont de Nemours Inc. |
| Toppan Inc. |
| UFlex Ltd. |
| Others |
Value Network & Pricing Analysis
EVOH copolymer resin costs cascade from Asian petrochemical producers through converter margins to pharmaceutical blister packaging premiums, with the EU's F-Gas Regulation compressing solvent-based coating profitability and forcing asset write-downs across Germany's Düsseldorf-Cologne corridor.
Pricing Analysis
Distributor margins on vacuum-deposited metalized films widen where Japanese consumer electronics manufacturers specify electromagnetic interference attenuation exceeding 60 dB. Three-tier pricing structure across premium, standard, and economy levels separates ALD-equipped barrier films for flexible displays from conventional EVOH laminates for food packaging. Cost compression in mid-tier coated films intensifies because water-based and UV-curable alternatives require line retrofits. Pharmaceutical companies exhibit lowest price sensitivity due to FDA validation timelines, while private-label food retailers in Germany embed carbon footprint thresholds that squeeze virgin petrochemical grades.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical OEMs mandate qualified backup suppliers for EVOH multilayer structures, with resin allocation risk concentrated among South Korean, Japanese, and Thai petrochemical producers. Feedstock dependencies rest on ethylene-vinyl alcohol copolymers, aluminum oxide deposition precursors, and bio-based polyamide alternatives. Single-source vulnerability runs through atomic layer deposition equipment where specialized process engineering talent concentrates among legacy display industry pools. Distribution runs through regional laminators serving pharmaceutical validation protocols and integrated film-to-package networks across Australasia and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transparent barrier films market functions as a stable compounder where pharmaceutical stability mandates and flexible electronics proliferation sustain durable demand expansion across packaging precision and device protection applications.
For Market Incumbents: Anchor backward integration into captive EVOH resin production to defend against Asian petrochemical supply concentration and feedstock allocation risk during cracker maintenance cycles. Accelerate ALD-equipped roll-to-roll capacity additions in Germany's industrial corridor ahead of EU F-Gas Regulation compliance deadlines. Prioritize pharmaceutical contact film certification investments where FDA extractables protocols extend validation cycles and lock in customer switching costs.
For New Entrants and Emerging Players: Mid-scale converters stranded by aluminum oxide deposition capex intensity represent an underserved buyer archetype for deposition-as-a-service partnerships or technology licensing arrangements. Flexible electronics manufacturers in Japan and Germany seeking water vapor transmission rates below 10^-4 g/m²/day constitute the most penetrable segment. Pursue equipment-leasing go-to-market models that bypass capital barriers to vacuum coating participation.
For Investors and Strategic Acquirers: Consolidation pressure builds where vacuum deposition technician scarcity and multilayer lamination certification timelines fragment mid-tier converter viability. Five-to-ten-year viability favors integrated resin-to-film operators with captive EVOH supply and validated pharmaceutical contact portfolios. Monitor EMA fluorinated gas phase-out roadmap submissions as inflection indicator for regulatory-compliant capacity scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin | Captive supply from Asian petrochemical producers eliminates feedstock allocation risk during cracker maintenance. |
| ALD-Equipped Roll-to-Roll Capacity Expansion | Atomic layer deposition scale-up captures premium positioning in organic photovoltaics and flexible display backplanes. |
| Pharmaceutical Contact Film Certification | FDA extractables validation extends commercialization cycles but locks in switching costs for blister packaging formularies. |
| Solvent-Free Coating Line Retrofit | Water-based and UV-curable alternatives align with EU F-Gas Regulation timelines ahead of 2030 compliance deadlines. |
| Technology Licensing Partnership | Deposition expertise transfer opens mid-scale converter participation without aluminum oxide capex intensity. |
Research Methodology
Bottom-up pharmaceutical and electronics packaging modeling reconciled against top-down EVOH resin and vacuum deposition capacity tracking forms the analytical core of this study. Primary interviews with film converters, pharmaceutical packaging engineers, electronics OEM procurement leads, and deposition equipment specialists combined with secondary validation from FDA 510(k) filings, EMA regulatory guidance documents, METI voluntary labeling standards, and SEC 10-K disclosures from integrated packaging networks. Triangulation across supply-side capacity announcements and demand-side specification trends anchored volume and value estimates.
Historical trendline analysis of EVOH multilayer adoption rates and ALD-equipped capacity installations informed projection frameworks across the analysis window. Segmentation dimensions modeled include barrier mechanism (polymer, metalized, coated, laminated), end-use application (packaging, electronics, healthcare, automotive), and technology (extrusion, co-extrusion, vacuum deposition, printing). CAGRs derived from regression analysis of patent filing velocity, regulatory compliance cost trajectories, and brand-owner sustainability scorecard adoption curves.
Underlying measurement precision varies by segment; pharmaceutical contact films and electronics encapsulation grades carry tighter precision than commodity food packaging laminates due to documented regulatory pathways and equipment vendor disclosures. Forecasts reflect assumptions around F-Gas Regulation enforcement timelines, fluoropolymer substitution rates, and flexible electronics manufacturing scale-up. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
North America Barrier Films Market
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
Saudi Arabia Plastic Packaging Films Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Moisture Barrier Bags Market