
 Industrial Label Printers Market | 2026-2036
Industrial Label Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Label Printers Market Insights
The EU Falsified Medicines Directive is expanding compliance-driven hardware refresh cycles across European pharmaceutical packaging lines. Zebra Technologies leverages its thermal transfer portfolio to dominate high-volume serialization deployments. Honeywell International anchors its position through ruggedized printer lines engineered for chemical production environments. SATO Holdings competes in Asia-Pacific logistics hubs with Bluetooth-enabled mobile units designed for warehouse floor mobility.
Industrial label printers are electromechanical devices that apply durable identification marks onto substrates using thermal, inkjet, or laser imaging methods, typically achieving print resolutions between 203 and 600 dots per inch for barcode and human-readable traceability data. Thermal transfer technology leads product type demand due to its chemical resistance and archival longevity in manufacturing settings. Wi-Fi and Ethernet connectivity segments are expanding fastest as facilities integrate printers into centralized MES and WMS architectures. Dot matrix retains niche share in heavy-industrial zones where impact printing survives harsh temperature cycling.
The US FDA enforces Unique Device Identification rules that mandate label-grade print permanence for medical device supply chains. REACH and RoHS frameworks in Europe restrict hazardous substances in printer components and consumables, pushing OEMs toward reformulated ribbon chemistries. Stakeholders must monitor evolving serialization mandates across multiple regulatory jurisdictions to align hardware procurement cycles with compliance deadlines.
Market Dynamics
Serialization mandates across pharmaceutical and medical device supply chains are forcing hardware replacement cycles that compress printer lifespans from seven years to three. Thermal transfer engine architectures face obsolescence pressure as facilities retool for 600 DPI traceability compliance.
Growth Catalysts
- EU Falsified Medicines Directive:European pharmaceutical packaging lines require barcode-grade hardware refreshes. The directive mandates unit-level serialization that legacy dot matrix systems cannot execute.
- Warehouse automation:E-commerce fulfillment centers deploy Wi-Fi-enabled mobile printers for real-time inventory marking. Bluetooth connectivity eliminates tethering to fixed workstations.
- German automotive supplier density:Component traceability requirements from OEMs drive demand for chemical-resistant thermal transfer labels in Stuttgart and Wolfsburg manufacturing clusters.
Market Restraints
- Ribbon chemistry constraints:REACH and RoHS frameworks restrict solvent-based ribbon formulations. European OEMs face reformulation costs that compress margin structures.
- Printhead supply concentration:Precision thermal printhead manufacturing concentrates in Japanese and South Korean component suppliers. Single-source dependencies create vulnerability to semiconductor allocation disruptions.
- Laser marking substitution:Permanent direct-part marking on metal and polymer substrates bypasses consumable-based labeling entirely in aerospace and precision engineering applications.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO track-and-trace implementation lags European timelines by four to six years. Domestic and multinational firms require serialization infrastructure that mirrors EU compliance architecture.
- Cloud-native printer management:SaaS-based fleet monitoring converges with MES platforms. Predictive maintenance algorithms reduce unplanned downtime in continuous pharmaceutical production.
- Food allergen labeling mandates:FSSAI regulations in India expand beyond pharmaceuticals into processed food traceability. Cold-chain logistics units require mobile printers for secondary packaging compliance.
Industry Challenges
- Field service technician scarcity:Mechatronics expertise for thermal printhead alignment and platen maintenance concentrates with aging workforces in Midwest US manufacturing corridors.
- Legacy PLC integration:Decades-old packaging line controllers lack Ethernet/IP connectivity. Retrofit engineering extends deployment timelines and inflates commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Label Printers Market |
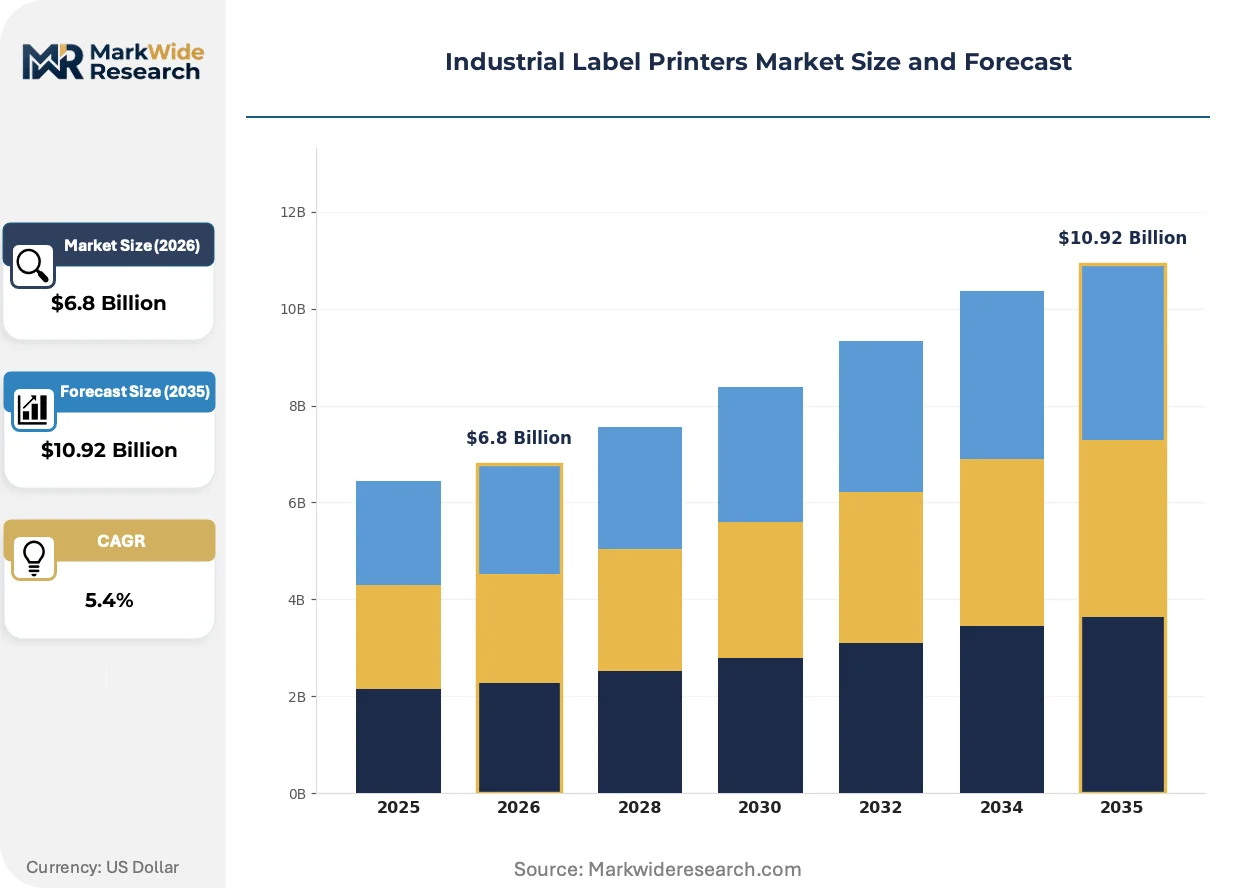
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Transfer, Direct Thermal, Inkjet, Laser, Dot Matrix Technology: Wi-Fi, Bluetooth, Ethernet, USB, Cellular Application: Manufacturing, Logistics & Warehousing, Food Processing, Chemical Production, Electronics Assembly End User Industry: FMCG Companies, Pharmaceutical Firms, Aerospace Suppliers, Textile Manufacturers, Packaging Services |
| Companies Covered | Zebra Technologies Corporation, Honeywell International Inc., SATO Holdings Corporation, TSC Auto ID Technology Co., Ltd., Brother Industries, Ltd., Seiko Epson Corporation, Toshiba Tec Corporation, Brady Corporation, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Label Printers Market Trends and Innovations
Edge computing architectures are redistributing intelligence from centralized MES layers to printer-level processors. This shift enables real-time print verification without network dependency and compresses response latency for high-speed pharmaceutical lines.
AI-powered optical character recognition engines embedded in printheads are decentralizing quality control. Pharmaceutical contract manufacturers in Ireland and Singapore deploy these systems to eliminate downstream rejection costs. The technology removes dependency on separate vision stations and reduces line footprint requirements.
REACH substance restrictions are accelerating water-based ribbon chemistry development. European chemical producers reformulate resin systems to eliminate restricted solvents while maintaining smudge resistance. German automotive suppliers pilot these formulations for under-hood component labeling where thermal cycling extremes persist.
Pharmaceutical buyers are consolidating vendor relationships around full-lifecycle service contracts. Large CMOs in Switzerland and Massachusetts now specify uptime guarantees rather than capital purchase terms. Equipment suppliers absorb maintenance risk and align revenue with production continuity outcomes.
Industrial Label Printers Market Segmentation
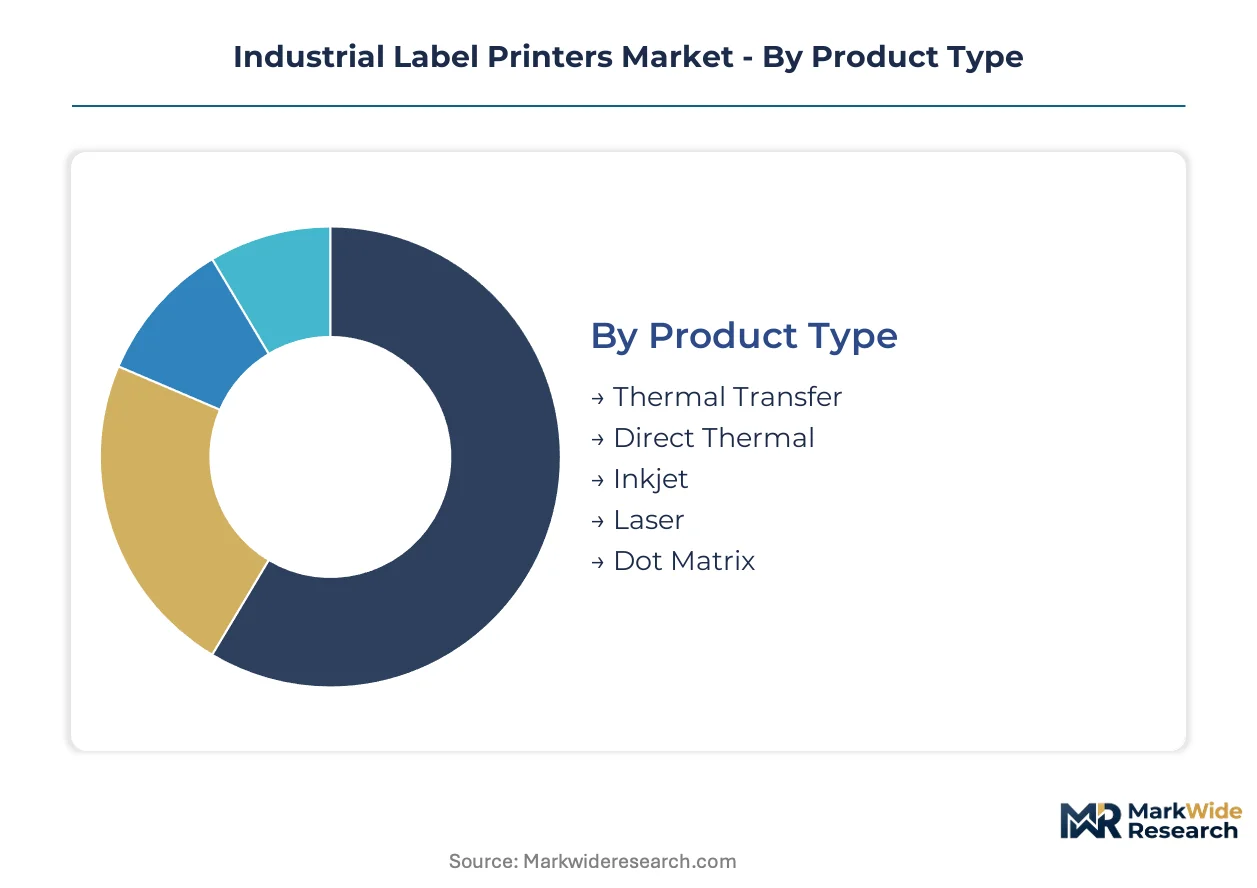
Industrial label printer procurement decisions hinge on substrate durability requirements, connectivity infrastructure, and regulatory compliance intensity. Segmentation reveals where capital deployment concentrates and which technology combinations command premium positioning.
Product Type:
Capital intensity varies sharply across imaging architectures, with laser systems demanding the highest upfront investment and thermal transfer dominating mid-range manufacturing deployments.
- Thermal Transfer:Ribbon-based imaging deposits resin or wax coatings onto synthetic substrates, achieving 300-600 DPI resolution with chemical resistance for pharmaceutical serialization. German automotive suppliers in Stuttgart and Wolfsburg specify these systems for under-hood component traceability where thermal cycling extremes persist.
- Direct Thermal:Heat-sensitive paper imaging eliminates ribbon consumables but limits archival longevity to 6-12 months in ambient conditions. E-commerce fulfillment centers in the United States deploy these for short-lifecycle shipping labels where capital constraints prioritize hardware minimization over durability.
- Inkjet:Piezoelectric drop-on-demand systems apply aqueous or solvent inks to porous and non-porous substrates. Food processing facilities specify these for date coding on corrugated secondary packaging.
- Laser:Electrophotographic imaging fuses toner to substrate surfaces with permanent adhesion. Aerospace suppliers in Toulouse and Hamburg deploy these for certification-grade documentation requiring decades-long legibility.
- Dot Matrix:Impact printing with inked ribbons survives harsh temperature cycling in heavy-industrial zones. Chemical production environments in the US Gulf Coast retain these for legacy PLC integration where digital connectivity remains unavailable.
Most installed capacity flows through Thermal Transfer. Expansion is steepest in Laser systems for permanent marking applications.
Technology:
Connectivity selection tracks facility digital maturity, with Ethernet dominating greenfield installations and Bluetooth capturing mobile warehouse deployments.
- Wi-Fi:IEEE 802.11 protocols enable untethered printer placement within warehouse floor layouts. Pharmaceutical contract manufacturers in Ireland deploy these for line reconfiguration flexibility without cable infrastructure replacement.
- Bluetooth:Short-range wireless pairing eliminates workstation dependency for mobile inventory marking. Logistics operators in Singapore specify handheld units for real-time carton labeling during pick-and-pack operations.
- Ethernet:Wired TCP/IP connectivity delivers deterministic latency for high-speed pharmaceutical lines. Swiss CMOs integrate these directly into centralized MES architectures.
- USB:Direct host connection persists in small-batch electronics assembly where network security policies restrict wireless endpoints.
- Cellular:LTE/5G modules enable remote fleet management for distributed field service operations. Cold-chain logistics providers in India deploy these for secondary packaging compliance at non-wired distribution nodes.
Ethernet carries the majority of industrial traffic. Bluetooth is climbing the fastest as warehouse automation accelerates.
Application:
Application selection correlates with environmental severity, from cleanroom electronics assembly to chemical exposure in process industries.
- Manufacturing:Work-in-progress labeling and finished goods identification dominate discrete production. German automotive supplier density in Baden-Württemberg drives concentration here.
- Logistics & Warehousing:Inbound receiving, put-away, and outbound shipping labels require mobile flexibility. E-commerce fulfillment centers in the United States specify Wi-Fi-enabled units for real-time inventory marking.
- Food Processing:Date coding and allergen declaration mandates require washdown-resistant hardware. FSSAI regulations in India expand traceability requirements into processed food cold chains.
- Chemical Production:GHS hazard communication labels demand solvent-resistant imaging. REACH and RoHS frameworks restrict ribbon formulations in European chemical clusters.
- Electronics Assembly:ESD-safe construction and high-DPI barcoding for component traceability. FDA Unique Device Identification rules govern medical device supply chains in the United States.
Manufacturing holds the largest installed base. Food Processing is expanding most quickly as allergen labeling mandates proliferate.
End User Industry:
End user selection reflects compliance intensity, with pharmaceutical serialization commanding the most stringent hardware specifications.
- Pharmaceutical Firms:Unit-level serialization for EU Falsified Medicines Directive compliance requires 600 DPI thermal transfer systems. CDSCO track-and-trace implementation in India lags European timelines, creating infrastructure replication demand.
- FMCG Companies:High-volume consumer goods labeling prioritizes throughput over resolution. Mass-market beverage bottlers specify these for production line integration.
- Aerospace Suppliers:AS9100 traceability mandates permanent marking with decades-long legibility. Hamburg and Toulouse manufacturing clusters specify laser systems for certification documentation.
- Textile Manufacturers:Care label and composition marking for retail compliance. Water-based ribbon chemistry development targets REACH substance restrictions in European textile hubs.
- Packaging Services:Contract packaging operations require flexible hardware for multi-client specifications. Swiss and Massachusetts CMOs now specify uptime-guaranteed service contracts over capital purchase terms.
Pharmaceutical Firms deploy the most specialized capacity. Packaging Services are gaining share fastest as outsourcing consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial label printer manufacturing traces its commercial origins to post-war precision engineering clusters in Japan and Germany, where thermal transfer mechanisms first achieved industrial reliability. These foundational capabilities now distribute across pharmaceutical serialization hubs and automotive supplier networks spanning multiple continents.
United States
FDA Unique Device Identification mandates drive hardware refresh cycles across medical device supply chains. The agency enforces label-grade print permanence standards that legacy dot matrix systems cannot satisfy. Massachusetts contract manufacturing organizations specify uptime-guaranteed service contracts over capital purchases.
Germany
REACH and RoHS frameworks restrict solvent-based ribbon formulations, forcing OEM reformulation investments. Stuttgart and Wolfsburg automotive clusters demand chemical-resistant thermal transfer labels for under-hood component traceability. Baden-Württemberg supplier density concentrates procurement volume.
India
CDSCO track-and-trace implementation lags European timelines by four to six years, creating infrastructure replication demand. FSSAI regulations expand serialization requirements into processed food cold chains. Domestic pharmaceutical manufacturers in Maharashtra and Gujarat require EU-mirror compliance architecture.
Japan
METI industrial standards govern precision thermal printhead manufacturing that concentrates among component suppliers. PMDA pharmaceutical serialization rules align with EU Falsified Medicines Directive architecture. Nagoya-area electronics assemblers specify ESD-safe construction for high-DPI component traceability.
Switzerland
Swissmedic pharmaceutical oversight mandates unit-level serialization matching EU stringency. Large contract manufacturing organizations specify full-lifecycle service contracts with production continuity guarantees. Basel and Zurich packaging lines drive premium-tier hardware deployment.
Industrial Label Printers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance intensity and service bundling dimensions. The vendor base stratifies between full-stack serialization specialists and component-focused hardware fabricators. Three archetypes dominate: thermal transfer engine specialists, ruggedized industrial systems providers, and mobile connectivity-focused logistics suppliers. Competitive moves concentrate on M&A for software integration capabilities and strategic partnerships for regional service coverage.
Within the premium-tier vector, Zebra Technologies Corporation exemplifies thermal transfer specialization for high-volume pharmaceutical deployments. Honeywell International Inc. anchors the ruggedized systems archetype through industrial-grade hardware engineering. SATO Holdings Corporation occupies the mobile connectivity position with Bluetooth-enabled units designed for warehouse floor mobility.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Honeywell International Inc. |
| SATO Holdings Corporation |
| TSC Auto ID Technology Co., Ltd. |
| Brother Industries, Ltd. |
| Seiko Epson Corporation |
| Toshiba Tec Corporation |
| Brady Corporation |
| Avery Dennison Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive ribbon chemistry production in Germany and Japan anchors premium-tier pricing power for thermal transfer systems, while outsourced printhead sourcing from South Korean component houses compresses margin structures for mid-market OEMs competing on hardware cost alone. This integration divergence separates serialization-grade suppliers who command service-contract premiums from commodity players exposed to REACH reformulation costs and semiconductor allocation volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates uptime-guaranteed pharmaceutical service contracts from capital-purchase hardware and entry-level direct thermal units. Price differentiation rests on DPI certification grade and after-sales bundling intensity. Cost compression in the standard tier is intensifying because REACH-mandated ribbon reformulation transfers compliance expense to OEMs without commensurate price recovery. FMCG bottlers exhibit highest price sensitivity; Swiss CMOs accept premium positioning for production continuity guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical demand, while distribution runs through regional integrators for mid-market manufacturing deployments. Precision thermal printhead manufacturing concentrates in Japan and South Korea; ribbon substrate production clusters in Germany and the United States. The supply chain draws from specialized resin chemistries, ceramic heating elements, and synthetic label substrates. Single-source vulnerability in Japanese printhead suppliers creates exposure to semiconductor allocation disruptions. Channel partners and authorized service networks dominate downstream fulfillment for compliance-intensive deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Pharmaceutical serialization mandates have shifted procurement criteria from capital cost minimization toward uptime-guaranteed service performance and 600 DPI compliance certification.
For Market Incumbents: Acquire cloud-native fleet management software capabilities to capture recurring revenue streams and lock out point-solution competitors. Consolidate position by deepening backward integration into REACH-compliant ribbon chemistry production in European manufacturing clusters. Laser marking substitution in aerospace applications threatens thermal transfer growth; defend by embedding AI-powered OCR verification into printhead architectures to eliminate separate vision station requirements. For New Entrants and Emerging Players: The mid-tier price gap between premium Swiss CMO service contracts and economy direct thermal hardware creates entry space for subscription-model serialization specialists. Target Indian pharmaceutical manufacturers in Maharashtra and Gujarat replicating EU compliance architecture ahead of CDSCO enforcement timelines. Lead with cellular-enabled mobile units for cold-chain logistics nodes lacking wired infrastructure, bypassing established players' Ethernet-centric installed base. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists because pharmaceutical buyers are consolidating vendor relationships around full-lifecycle contracts rather than capital purchases. Platform consolidation targets mid-cap OEMs with captive ribbon chemistry capabilities and established channel presence in German automotive supplier clusters. Watch for inflection in India's CDSCO implementation pace; accelerated enforcement would compress hardware procurement cycles and favor entrants with localized manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ribbon Chemistry | REACH compliance costs in Germany force captive production to defend margin structures against reformulation expense transfer. |
| Cloud-Native Fleet Management Platform | SaaS monitoring converges with MES architectures to capture recurring revenue from Swiss pharmaceutical CMOs. |
| AI-Embedded Printhead Development | Real-time OCR verification eliminates separate vision stations and reduces line footprint for Irish contract manufacturers. |
| Cellular-Enabled Mobile Unit Launch | LTE/5G modules address India's cold-chain distribution nodes lacking wired infrastructure for FSSAI allergen compliance. |
| Regional Service Network Expansion | Authorized technician density in Midwest US corridors defends against field service scarcity threatening uptime guarantees. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, regulatory filing analysis, and customs trade data — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations included maintenance directors at pharmaceutical packaging lines, aftermarket service heads at thermal transfer specialists, and channel sales managers at regional distribution partners. Secondary validation drew from FDA Unique Device Identification guidance documents, EMA Falsified Medicines Directive implementation reports, CDSCO track-and-trace advisories, and SEC filings from disclosed market participants.
Historical shipment data was cross-referenced against panel input from procurement executives to establish baseline penetration rates across the projection horizon. The analytical framework modeled demand by product type, connectivity protocol, application severity, and end-user compliance intensity. CAGR derivation incorporated pharmaceutical serialization mandate timelines, automotive supplier traceability requirements, and warehouse automation adoption curves. Industry-specific inputs included REACH substance restriction phase-in schedules and CDSCO enforcement probability assessments.
The model assumes a particular technology adoption path; alternative pathways for laser marking substitution in aerospace and precision engineering would alter the outlook for thermal transfer demand. Forecasts reflect base-case assumptions regarding regulatory enforcement consistency and semiconductor supply normalization. Periodic stress-testing of base assumptions is recommended given single-source printhead dependencies and evolving serialization mandates across multiple jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Pressure Sensitive Labels Market
Labels
Self-Adhesive Labels Market
Labels
Braille Labels Market
Labels
Primary Packaging Labels Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Warning Labels and Stickers Market
Labels
Extended Text Labels Market
Labels
Tags Market
Labels
BOPP Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Barcode Label Printer Market
Labels
Direct Thermal Linerless Labels Market
Labels
Multi-Part Labels Market
Labels
Non-Adhesive Tags Market
Labels
Self-Laminating Labels Market