
 France Paper Packaging Market | 2026-2036
France Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
France Paper Packaging Market Foresight
France's AGEC anti-waste law is shifting the cost-of-entry calculus for packaging suppliers by imposing strict recyclability quotas and extended producer responsibility fees. Smurfit Kappa Group plc leverages its integrated containerboard network to control recycled fiber supply across French operations. DS Smith Packaging France anchors its position through specialized e-commerce corrugated designs for premium consumer brands. Autajon Group differentiates via high-value folding carton production serving pharmaceutical and cosmetic clients.
France paper packaging encompasses rigid and flexible containers manufactured from wood pulp fibers, typically ranging from 150 to 400 grams per square meter in basis weight, with corrugated medium achieving burst strengths between 150 and 275 pounds per square inch for industrial shipping protection. Folding cartons command the largest value share among product types due to their dominance in food and beverage retail presentation, while corrugated boxes exhibit the fastest structural growth propelled by e-commerce fulfillment expansion. Virgin kraft paper sustains premium positioning in export-oriented food packaging where moisture resistance and print clarity justify higher material grades against recycled alternatives.
ANSM enforces pharmaceutical packaging traceability standards that elevate compliance costs for carton and label suppliers serving drug manufacturers. ECHA's REACH framework and France's AGEC law collectively restrict certain chemical coatings and mandate minimum recycled content thresholds, reshaping material sourcing decisions across the value chain. Stakeholders must monitor evolving extended producer responsibility fee structures and recyclability certification requirements to align capital allocation with regulatory trajectory.
Market Dynamics
France's AGEC anti-waste law is compressing margins for non-compliant packaging converters while rewarding integrated recyclers with lower extended producer responsibility fees. This regulatory pressure is accelerating consolidation among mid-tier suppliers unable to fund circular economy transitions.
Growth Catalysts
- E-commerce fulfillment surge:Third-party logistics operators in the Paris metropolitan area are expanding corrugated box procurement for same-day delivery networks. This demand concentrates in Île-de-France distribution hubs.
- AGEC recyclability mandates:France's anti-waste law requires minimum recycled content thresholds, pulling fiber through domestic sorting infrastructure and stimulating investment in local repulping capacity.
- Barrier-coated kraft innovation:Food processing units are adopting moisture-resistant paper packaging for chilled ready-meals, displacing multi-material laminates in premium retail channels.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container pricing fluctuates with German export demand, squeezing French boxboard producers during Q4 peak seasons.
- Nordic pulp supply concentration:Bleached kraft pulp for pharmaceutical folding cartons routes through limited Baltic port capacity, creating bottlenecks during winter ice conditions.
- Plastic substitution ceiling:High-barrier flexible films retain cost advantages for wet pet food applications, capping paper penetration in moisture-sensitive categories.
Strategic Opportunities
- Rhône-Alpes pharmaceutical corridor:Lyon-based drug manufacturers are expanding serialization-compliant carton demand for export to Swiss and Belgian markets.
- Reuse system integration:AGEC-modified extended producer responsibility frameworks reward packaging designed for looped distribution, creating service revenue for logistics-integrated converters.
- Digital print convergence:Inkjet web presses are enabling short-run personalized corrugated for direct-to-consumer cosmetics brands, collapsing minimum order quantities.
Industry Challenges
- ANSM serialization compliance:Pharmaceutical carton suppliers must integrate track-and-trace codes without compromising line speed, requiring capital upgrades to folding-gluing equipment.
- REACH coating reformulation:ECHA restrictions on fluorinated barriers force R&D timelines that outpace customer specification cycles, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Paper Packaging Market |
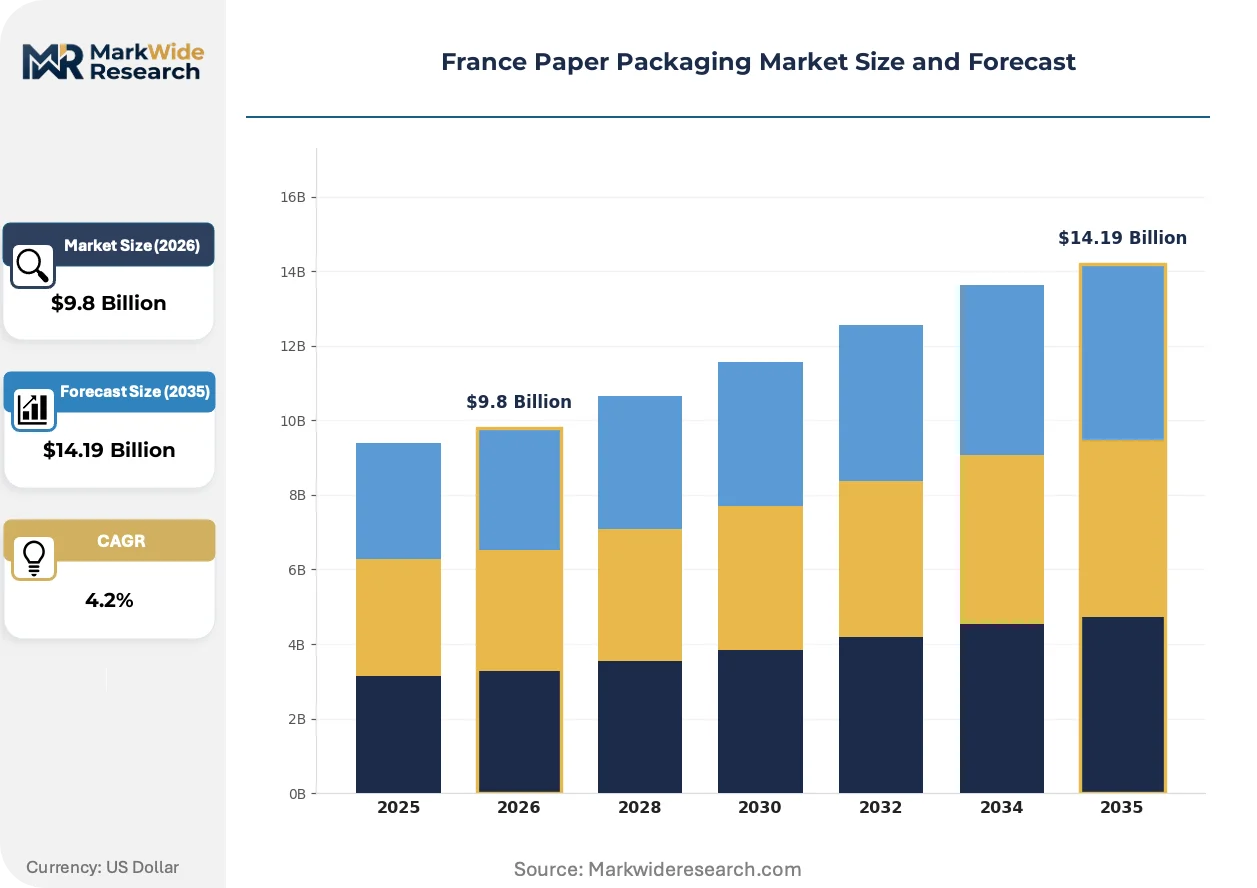
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.19 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Cartons, Corrugated Boxes, Paper Bags, Labels, Tubes & Cores Application: Food & Beverage, Personal Care, Household Products, Pharmaceuticals, Industrial Goods Material Grade: Recycled Paper, Virgin Kraft Paper, Bleached Paperboard, Unbleached Paperboard, Coated Paper End User Industry: Consumer Goods Manufacturers, Pharmaceutical Companies, Food Processing Units, Cosmetic Brands |
| Companies Covered | Graphic Packaging International, Autajon Group, Smurfit Kappa Group plc, LGR Packaging, LACAUX Freres, DS Smith Packaging France, MM PACKAGING GmbH, Saica Paper France, International Paper, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Paper Packaging Market Shifts & Advancements
Digital manufacturing and regulatory chemistry restrictions are reshaping how French converters design, produce, and certify paper packaging for regulated end-uses. These shifts favor capital-rich operators with in-house compliance capabilities.
Water-based barrier coatings are converging with high-speed flexographic printing to enable plastic-free food packaging that maintains heat-seal integrity. Dairy processors in Brittany are piloting these materials for fresh cheese applications. This convergence is compressing the premium gap between fiber-based and conventional multi-layer structures.
France's AGEC law and ECHA's REACH framework are jointly restricting per- and polyfluoroalkyl substances in food contact materials. Folding carton suppliers serving the ready-meal sector are reformulating grease-resistant treatments to maintain regulatory access. The Rhône-Alpes industrial corridor is experiencing the steepest compliance cost escalation due to its concentration of premium food exporters.
Brand-led sustainability scorecards are displacing price-primary supplier selection in cosmetics and luxury goods procurement. Paris-based beauty houses are mandating Forest Stewardship Council chain-of-custody certification for all primary packaging. This behavioral shift is most visible in the Hauts-de-Seine cluster, where packaging decisions flow through centralized corporate sustainability offices rather than regional purchasing teams.
France Paper Packaging Market Segmentation
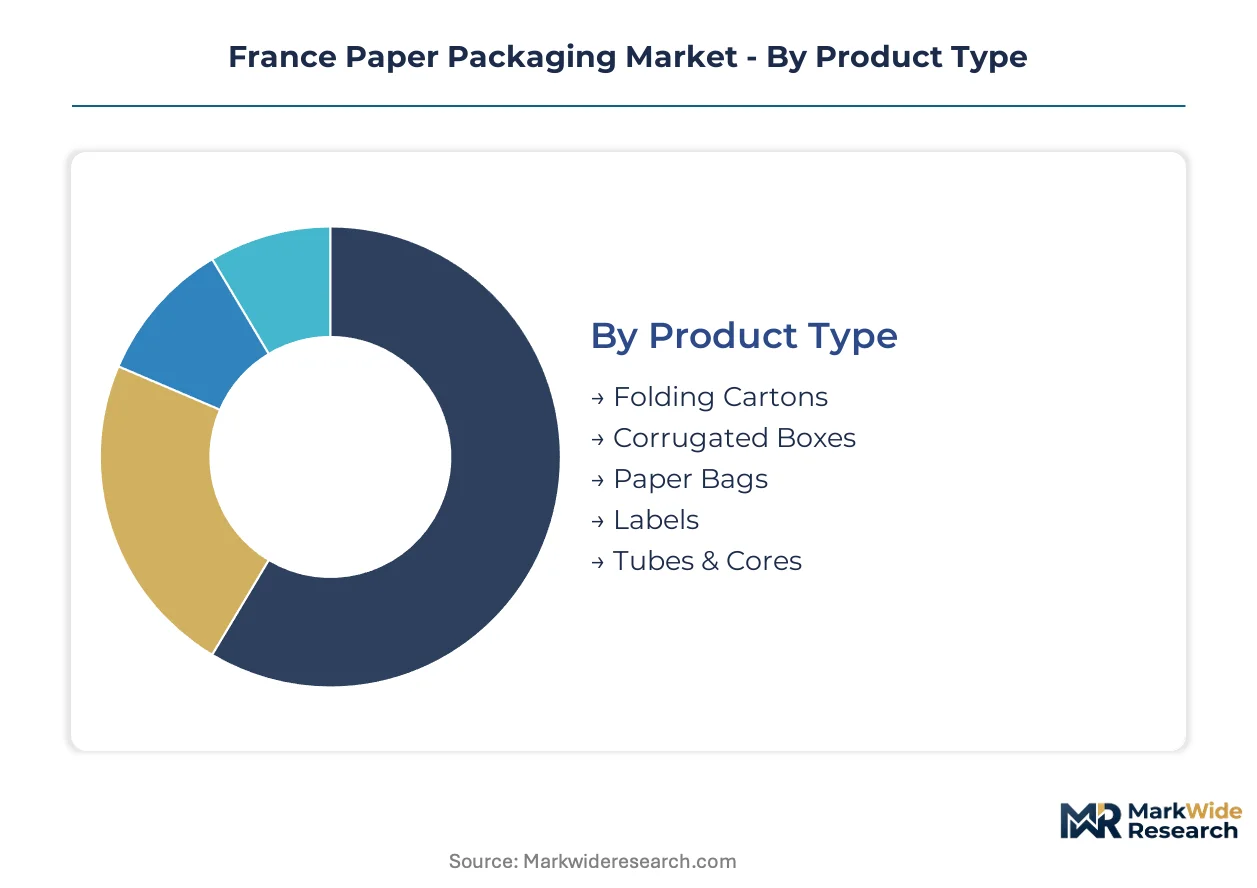
France paper packaging segmentation reveals how material specifications and regulatory thresholds reshape procurement across distinct value chains. Understanding these divisions exposes where AGEC compliance costs concentrate and where barrier-coated innovations unlock substitution opportunities.
Product Type:
Structural specifications and burst strength requirements differentiate performance across transport and retail presentation formats.
- Folding Cartons:These 250-400 gsm paperboard containers serve premium retail presentation with high-resolution offset printing surfaces. Demand concentrates in Paris-based cosmetics headquarters where AGEC recyclability mandates favor mono-material designs over plastic windows.
- Corrugated Boxes:Fluted medium sandwiched between linerboards achieves 150-275 psi burst strength for industrial shipping protection. E-commerce fulfillment networks in Île-de-France distribution hubs are expanding procurement of these containers for same-day delivery operations.
- Paper Bags:Kraft paper constructions range from 80-150 gsm for retail carry applications with twisted or flat handles.
- Labels:Pressure-sensitive and wet-glue formats serve pharmaceutical serialization requirements under ANSM traceability standards.
- Tubes & Cores:Spiral-wound cardboard cylinders support textile winding and film rolling in Rhône-Alpes manufacturing corridors.
Mature deployment sits with folding cartons serving established retail channels. Newer deployment is concentrated in corrugated formats designed for automated fulfillment systems.
Application:
End-use regulatory intensity and moisture sensitivity requirements determine material grade selection and coating chemistry investments.
- Food & Beverage:Chilled ready-meal processors in Brittany pilot barrier-coated kraft to displace multi-material laminates. ECHA REACH restrictions on fluorinated barriers are forcing reformulation timelines for grease-resistant treatments in this segment.
- Pharmaceuticals:ANSM serialization standards require track-and-trace code integration on cartons and labels without compromising line speed. Lyon-based drug manufacturers are expanding demand for these compliant formats targeting Swiss and Belgian export markets.
- Personal Care:Paris beauty houses mandate Forest Stewardship Council chain-of-custody certification for primary packaging through centralized sustainability offices.
- Household Products:Detergent and cleaning supply brands favor corrugated shipping cases with high recycled content to meet AGEC extended producer responsibility thresholds.
- Industrial Goods:Heavy-duty corrugated specifications protect automotive components shipped through Rhône-Alpes logistics corridors.
Established volume flows through food and beverage channels. Steepest specification upgrades are appearing in pharmaceutical applications.
Material Grade:
Fiber sourcing decisions balance cost volatility against regulatory minimums for recycled content and export market access requirements.
- Recycled Paper:Old corrugated container fiber feeds domestic repulping capacity expanded under AGEC pull-through mandates. Pricing fluctuates with German export demand, squeezing French producers during peak seasons.
- Virgin Kraft Paper:Unbleached long-fiber pulp provides moisture resistance and print clarity for premium export-oriented food packaging. Nordic pulp supply routes through limited Baltic port capacity create winter bottlenecks.
- Bleached Paperboard:Pharmaceutical folding cartons require this grade for clinical white backgrounds and precise color matching on serialization codes.
- Unbleached Paperboard:Natural kraft appearance serves organic food brands and sustainability-forward cosmetics positioning.
- Coated Paper:Clay or polymer surface treatments enable high-definition graphics for luxury goods presentation in Hauts-de-Seine corporate procurement.
Cost-sensitive applications favor recycled grades. Premium positioning depends on virgin fiber certification.
End User Industry:
Procurement centralization and technical specification authority vary dramatically across buyer organizational structures.
- Consumer Goods Manufacturers:Mass-market retailers drive standardized corrugated specifications with volume-based pricing and AGEC compliance documentation requirements.
- Pharmaceutical Companies:Serialization investments and ANSM validation protocols elevate supplier switching costs for carton and label providers.
- Food Processing Units:Brittany dairy processors and ready-meal packers are piloting moisture-resistant paper barriers to replace plastic laminates in chilled distribution.
- Cosmetic Brands:Paris-based beauty houses centralize packaging decisions through corporate sustainability offices rather than regional purchasing teams.
Long-term supply relationships dominate pharmaceutical procurement. Agile specification changes characterize cosmetic brand sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's ZFE-m (Zones à Faibles Émissions Mobilité) clean transport zones concentrate packaging demand near urban distribution hubs where AGEC compliance costs shape supplier selection.
Île-de-France
E-commerce fulfillment networks in Paris metropolitan distribution hubs expand corrugated procurement for same-day delivery operations. ANSM pharmaceutical serialization standards elevate compliance investments for carton suppliers serving drug manufacturers headquartered in Hauts-de-Seine. The Roissy-Charles de Gaulle logistics corridor anchors air-freight packaging demand for luxury cosmetics exports.
Auvergne-Rhône-Alpes
Lyon-based pharmaceutical manufacturers drive serialization-compliant folding carton demand targeting Swiss and Belgian export markets. ECHA REACH restrictions on fluorinated barrier coatings force reformulation timelines for food packaging suppliers in the Grenoble industrial basin. The Saint-Étienne packaging cluster specializes in high-value cosmetic and pharmaceutical formats.
Brittany
Dairy processors pilot moisture-resistant kraft barriers for fresh cheese applications displacing plastic laminates. AGEC extended producer responsibility fees pull fiber through domestic sorting infrastructure stimulating repulping investment. Rennes agri-food R&D centers validate heat-seal integrity for chilled ready-meal formats.
Hauts-de-France
Dunkirk port capacity handles Nordic bleached kraft pulp imports for pharmaceutical-grade folding cartons. Old corrugated container pricing volatility with German export demand squeezes regional boxboard producers during peak seasons. Lille distribution hubs serve cross-border e-commerce fulfillment into Benelux markets.
Provence-Alpes-Côte d'Azur
Marseille-Fos port infrastructure receives recycled fiber shipments for regional corrugated medium production. Cosmetic brand sustainability scorecards mandate Forest Stewardship Council chain-of-custody certification through centralized Nice and Aix-en-Provence procurement offices. The Sophia Antipolis technology cluster incubates digital print packaging innovations.
France Paper Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across France's paper packaging value chain. The market exhibits tiered consolidation where integrated containerboard producers command supply security advantages while mid-tier converters face margin compression from AGEC compliance costs. Three archetypes dominate: integrated fiber-to-box operators controlling recycled pulp supply, specialized folding carton manufacturers serving regulated pharmaceutical clients, and regional corrugated specialists anchored to e-commerce logistics networks. Competitive dynamics center on backward integration into repulping capacity and strategic partnerships with brand sustainability offices.
Within the integrated operator tier, Smurfit Kappa Group plc and DS Smith Packaging France exemplify scale-driven positions leveraging containerboard network control. Autajon Group occupies a specialized niche representing high-value folding carton production for pharmaceutical and cosmetic applications. These three anchors illustrate how capital allocation toward AGEC-compliant circular infrastructure separates sustainable competitive position from regulatory-driven exit risk.
| Leading Market Players |
|---|
| Graphic Packaging International |
| Autajon Group |
| Smurfit Kappa Group plc |
| LGR Packaging |
| LACAUX Freres |
| DS Smith Packaging France |
| MM PACKAGING GmbH |
| Saica Paper France |
| International Paper |
| Others |
Supply & Pricing Matrix
Cosmetics procurement offices in Hauts-de-Seine centralize packaging decisions through sustainability scorecards rather than regional purchasing teams, anchoring contract pricing to Forest Stewardship Council certification tiers and volume commitments rather than spot fiber markets.
Pricing Analysis
Short lead-time premiums dominate pricing for pharmaceutical folding cartons serving Lyon-based drug manufacturers with ANSM serialization deadlines. Three-tier pricing structure across certified sustainable, standard recycled, and economy grades reflects AGEC extended producer responsibility fee differentials. Cost compression in economy corrugated runs through German old corrugated container export demand volatility. Mass-market retailers exhibit highest price sensitivity; pharmaceutical exporters show lowest due to regulatory compliance switching costs.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale demand from Paris metropolitan e-commerce fulfillment networks, while specialized distributors serve cosmetic and pharmaceutical clients with technical specification support. Nordic bleached kraft pulp for pharmaceutical grades routes through Baltic port capacity, with recycled fiber sourcing drawing from German and Benelux collection infrastructure. Single-source vulnerability concentrates in winter ice conditions blocking Nordic pulp shipments. Distribution runs through Île-de-France logistics hubs for corrugated, Rhône-Alpes corridors for pharmaceutical formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's paper packaging sector sits in a barrier-coating transition phase, with water-based moisture-resistant treatments displacing fluorinated legacy chemistry under ECHA REACH restrictions.
For Market Incumbents: Anchor competitive position through captive repulping capacity investments in AGEC-compliant circular infrastructure. Smurfit Kappa Group plc and DS Smith Packaging France demonstrate supply security advantages from integrated containerboard networks. Defend against mid-tier consolidation by accelerating digital print capabilities for short-run cosmetic personalization. For New Entrants and Emerging Players: E-commerce corrugated procurement for same-day delivery networks offers the most penetrable entry vector, particularly in underserved Brittany and Provence-Alpes-Côte d'Azur distribution hubs. Target barrier-coated kraft innovation for chilled ready-meal applications where plastic substitution ceilings remain unbreached. Pursue direct relationships with Paris-based beauty house sustainability offices bypassing traditional procurement channels. For Investors and Strategic Acquirers: The window for entry favors specialized folding carton manufacturers with ANSM serialization compliance infrastructure and established pharmaceutical client relationships. Mid-tier converters facing AGEC margin compression represent distressed acquisition opportunities. Monitor ECHA coating reformulation timelines as inflection indicator for R&D-capable target valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Repulping Capacity | AGEC extended producer responsibility fee reductions reward domestic fiber circularity investments. |
| Digital Print Platform Deployment | Inkjet web presses collapse minimum order quantities for direct-to-consumer cosmetic brands. |
| Barrier Coating R&D Partnership | ECHA REACH fluorinated restrictions force collaborative reformulation timelines with food processors. |
| Pharmaceutical Serialization Certification | ANSM track-and-trace compliance elevates supplier switching costs for Lyon drug exporters. |
| Sustainability Scorecard Alignment | Forest Stewardship Council chain-of-custody certification unlocks Paris beauty house procurement access. |
Research Methodology
Document review covered customs trade data, SEC filings from listed packaging conglomerates, and ANSM regulatory guidance, complemented by interviews with plant managers at Rhône-Alpes folding carton facilities, procurement leads at Brittany dairy processors, sustainability directors at Paris-based cosmetic brands, and distribution channel partners serving Île-de-France e-commerce networks. Secondary validation drew from ECHA REACH substance restrictions, AGEC legislative texts, and industry association capacity reports. Bottom-up fiber demand modeling triangulated against top-down end-use consumption estimates.
Segmented outputs across product type, material grade, application, and regional industrial corridor anchored volume projections over the analysis window. CAGRs derived from regression against historical fiber pricing volatility and regulatory compliance cost trajectories. Key inputs included old corrugated container trade flows, Nordic pulp shipment schedules, and pharmaceutical serialization equipment deployment timelines.
The model holds under stable AGEC fee structures and ECHA coating restriction timelines; deviation in Nordic pulp supply disruptions or German export demand spikes would shift corrugated pricing assumptions. Practitioners should monitor Baltic port winter conditions and REACH substance restriction amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraft Paper Mailer Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
North America Corrugated Board Packaging Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Global Folding Boxboards Market