
 Release Coatings Market | 2026-2036
Release Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Release Coatings Market Analysis
China is reconfiguring regional supply dynamics through expanded silicone monomer and emulsion capacity additions. Dow Inc. leverages integrated silicone feedstock positions across North American and Asian manufacturing complexes. Shin-Etsu Chemical Co., Ltd. anchors premium electronics-grade release coating supply through proprietary polymer architecture. Wacker Chemie AG competes on formulation breadth spanning solvent-based, water-based, and UV-curable release systems for pressure-sensitive adhesive converters.
Release coatings comprise thin functional layers applied to substrates to prevent adhesion between surfaces, typically formulated from polydimethylsiloxane (PDMS) or fluorinated polymers at coating weights of 0.5–2.0 g/m² to achieve controlled peel forces of 5–50 g/cm. These coatings enable clean separation of pressure-sensitive adhesives from liners in tape, label, and hygiene product manufacturing. Silicone formulations occupy the dominant value position due to thermal stability across -60°C to 250°C operating ranges, while water-based systems represent the fastest-expanding formulation category as converters phase out volatile organic compound emissions. Electronics applications command premium pricing through ultra-low outgassing specifications for optical display bonding, whereas packaging segments sustain volume leadership across food and consumer goods end users.
EPA VOC emission standards under the Clean Air Act constrain solvent-based formulation production in US manufacturing facilities, while REACH registration requirements govern silicone oligomer classifications across European coating operations. China's GB standards for industrial volatile organic compound limits tighten compliance thresholds for domestic release coating producers. FDA indirect food contact regulations under 21 CFR 177.2260 specify extractable limits for silicone release coatings in direct food packaging applications. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation portfolios and manufacturing location strategies.
Market Dynamics
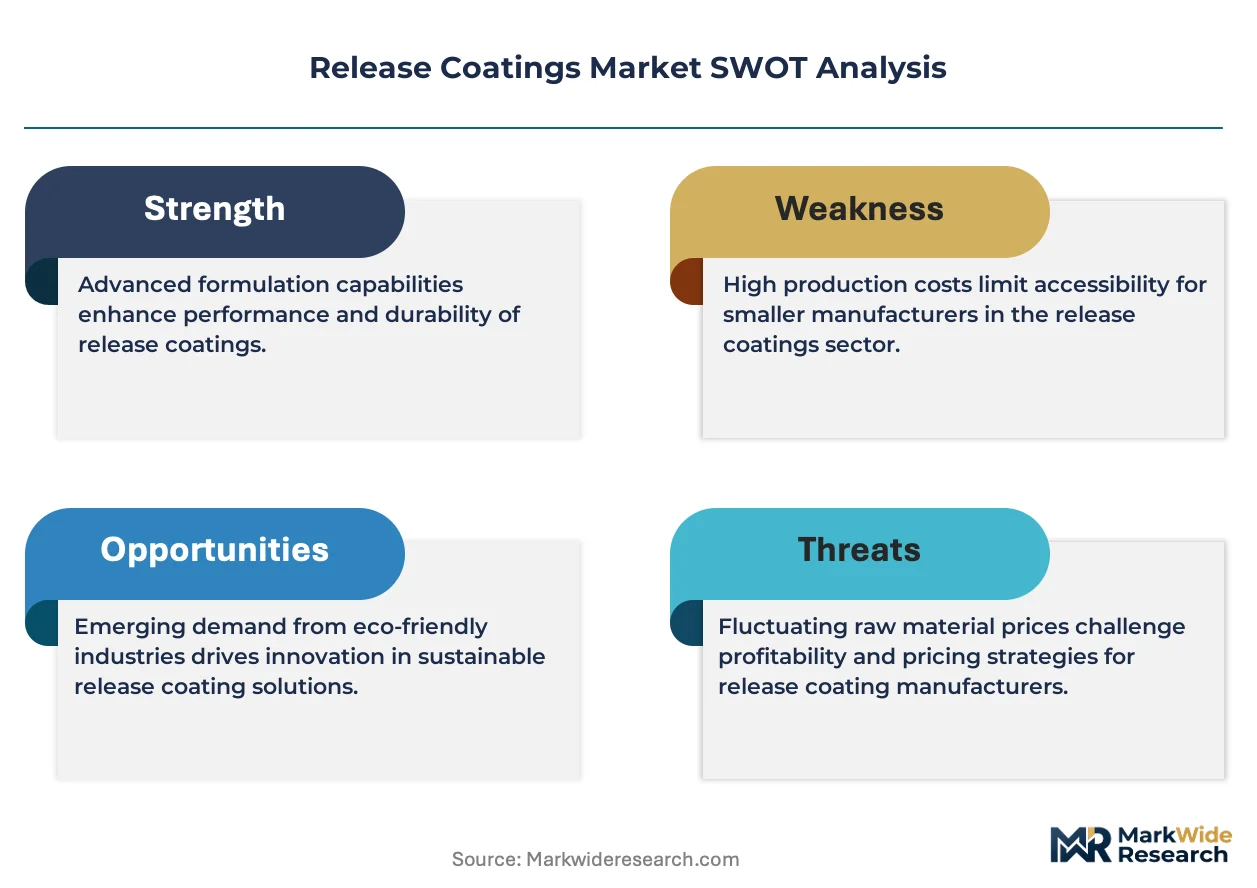
The Release Coatings Market is undergoing fundamental restructuring as water-based silicone emulsions displace solvent systems under tightening volatile organic compound regulations across major manufacturing jurisdictions.
Growth Catalysts
- EU Green Deal packaging directives:The European Commission's packaging waste regulations mandate solvent-to-water formulation transitions, compelling converters to adopt silicone release liners with reduced environmental footprints.
- Extended shelf-life food packaging:Food packaging converters are expanding silicone-based release liner adoption to meet preservation requirements for ready-to-eat and fresh-produce segments.
- Automotive adhesive tape clustering:Germany's concentration of automotive adhesive tape manufacturing anchors regional silicone release coating consumption through integrated supply relationships with tier suppliers.
Market Restraints
- Silicone monomer supply concentration:China controls critical silicone monomer capacity, creating geographic supply risk for Western formulators dependent on imported feedstock.
- Fluoropolymer cost volatility:Perfluorinated raw material prices fluctuate with regulatory phase-out timelines, constraining premium electronics-grade release coating margins.
- REACH oligomer classification friction:ECHA registration requirements for low-molecular-weight silicone oligomers impose compliance costs and reformulation burdens on European coating operations.
Strategic Opportunities
- UV-curable system penetration:Electronics-grade optical display bonding applications command premium positioning through ultra-low outgassing specifications that solvent systems cannot satisfy.
- India packaging conversion:The country's food processing sector expansion creates underpenetrated demand for extended-shelf-life packaging with silicone release functionality.
- Dual carbon policy alignment:China's GB standards for industrial volatile organic compound limits accelerate domestic water-based formulation adoption, opening technology licensing partnerships.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required for silicone polymer architecture and controlled peel-force engineering exceeds current technical education pipeline output.
- Multi-jurisdiction certification timelines:FDA 21 CFR 177.2260 extractable limits for food contact applications require 18-24 month validation cycles that delay product launches.
- Legacy solvent system retrofit complexity:Converters face capital-intensive drying equipment modifications when transitioning coating lines from solvent to water-based chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Release Coatings Market |
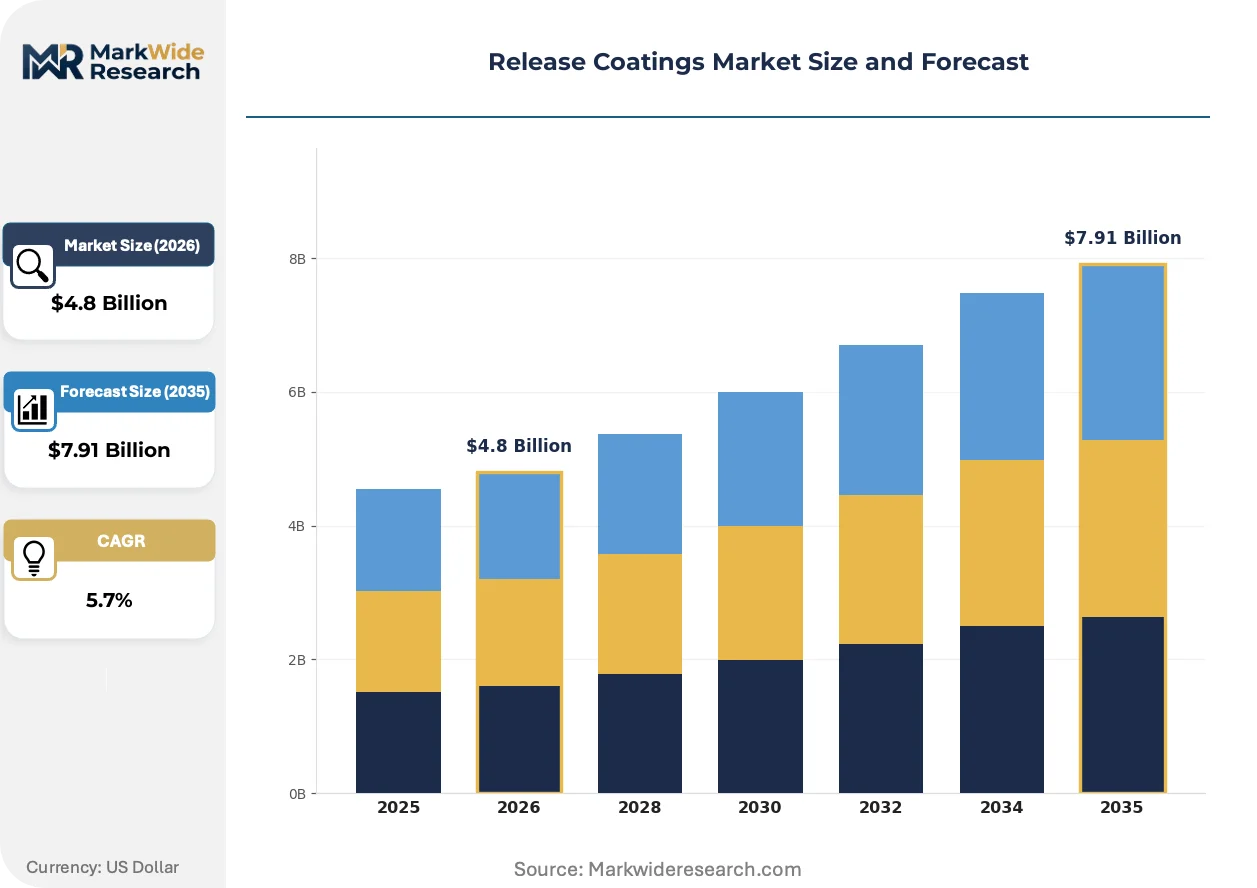
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, PTFE, Polyolefin, Fluoropolymer Application: Packaging, Adhesives, Automotive, Electronics Formulation Type: Water-Based, Solvent-Based, Hot Melt, Powder End User: Food, Healthcare, Consumer Goods, Industrial |
| Companies Covered | Dow Inc., Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials Inc., Wacker Chemie AG, Evonik Industries, Elkem ASA, HITAC Adhesives & Coatings, Mayzo, Inc., Henkel AG & Co. KGAA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Release Coatings Market Emerging Trajectories
Formulation chemistry is pivoting toward sustainable architectures as regulatory thresholds tighten and end-users demand performance without environmental trade-offs.
Water-based silicone emulsion technology is migrating from niche applications to mainstream pressure-sensitive adhesive converter operations. Major tape and label manufacturers in North America and Europe are completing line conversions at accelerated pace. This migration is compressing demand for solvent-based systems and consolidating supplier relationships around integrated emulsion producers with captive monomer supply.
REACH registration requirements for silicone oligomer classifications are reshaping European formulation portfolios. ECHA's substance evaluation protocols now require extensive toxicological data packages for low-molecular-weight species. Electronics-grade release coating producers are responding by engineering higher-molecular-weight polymer architectures that circumvent classification thresholds while maintaining peel-force precision.
Specification-driven procurement now dominates hygiene product manufacturing, where brand owners mandate certified low-outgassing release liners for infant care and adult incontinence applications. Converter qualification programs have replaced spot purchasing with approved-supplier frameworks. This shift is most visible in Germany and Japan, where consumer product safety standards exceed baseline regulatory requirements.
Release Coatings Market Segmentation
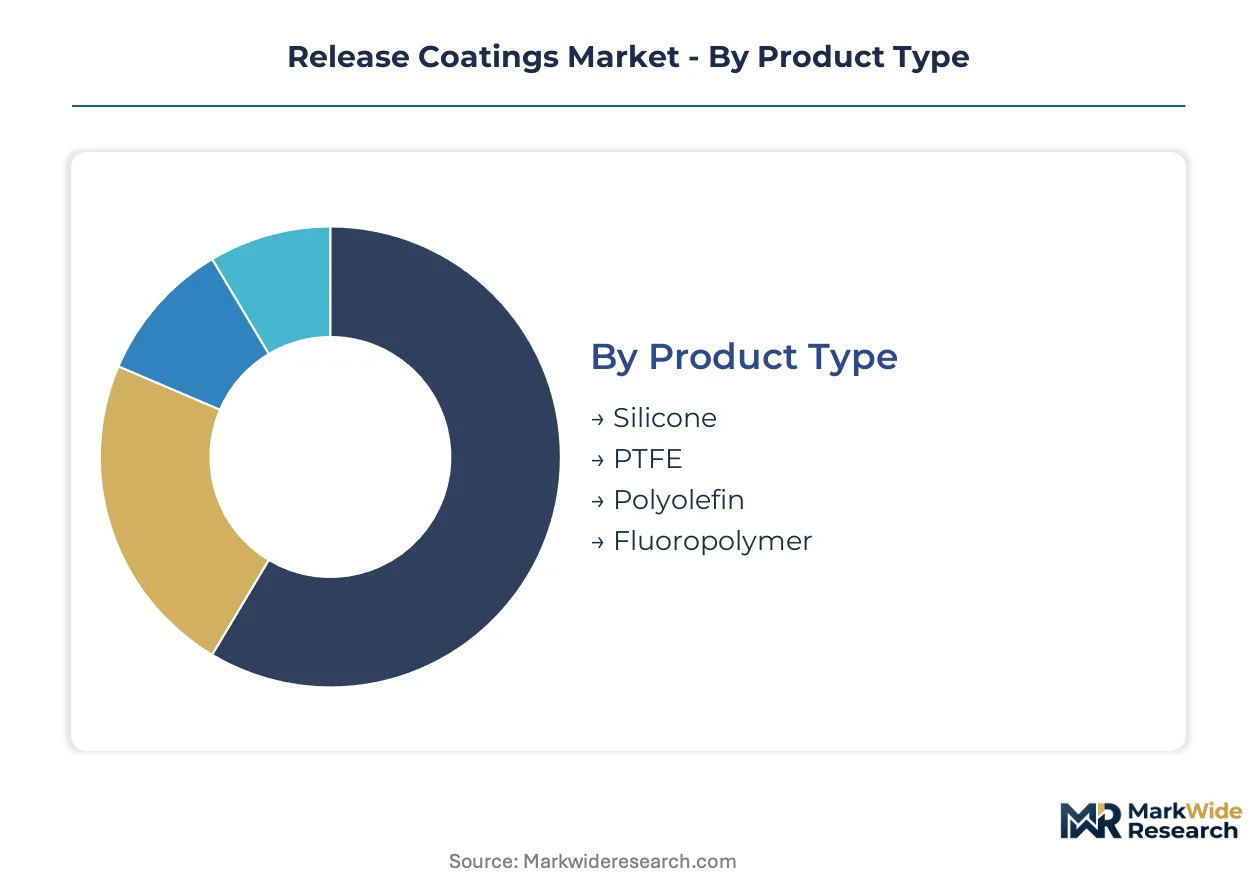
Release coatings serve divergent performance requirements across temperature extremes, peel-force precision, and regulatory compliance. Segmentation reveals how formulation chemistry and end-use specifications reshape supplier priorities and manufacturing investments.
Product Type:
Cost tier differentiation separates commodity silicone formulations from premium fluoropolymer architectures in this category.
- Silicone:Polydimethylsiloxane (PDMS) formulations dominate through thermal stability from -60°C to 250°C and coating weights of 0.5–2.0 g/m². Food packaging converters in Germany anchor demand as EU Green Deal packaging waste directives accelerate solvent-to-water transitions.
- Fluoropolymer:Perfluorinated polymer systems command premium positioning through ultra-low surface energy and chemical inertness. Electronics-grade optical display bonding in Japan and South Korea drives specification intensity as outgassing limits tighten below 50 ppm.
- PTFE:Polytetrafluoroethylene coatings serve high-temperature industrial release applications with friction coefficients below 0.1.
- Polyolefin:Polyethylene and polypropylene-based systems offer cost-competitive alternatives for low-temperature packaging release where silicone transfer must be eliminated.
Silicone commands the established base. The steepest expansion runs through fluoropolymer as electronics specifications harden.
Application:
Application segmentation tracks how peel-force engineering requirements concentrate across manufacturing clusters and regulatory jurisdictions.
- Packaging:Extended shelf-life requirements for ready-to-eat and fresh-produce segments drive silicone release liner adoption. FDA 21 CFR 177.2260 extractable limits govern food contact validation cycles of 18–24 months in US converter operations.
- Electronics:Optical display bonding and semiconductor manufacturing demand ultra-low outgassing specifications below 10 ppm total volatile organic compounds. UV-curable silicone systems penetrate this segment as solvent-based alternatives fail cleanliness thresholds.
- Adhesives:Pressure-sensitive adhesive tape manufacturing requires controlled peel forces of 5–50 g/cm across label and industrial bonding applications.
- Automotive:Adhesive tape clustering in Germany anchors regional consumption through integrated supply relationships with tier suppliers facing lightweighting mandates.
Packaging retains volume leadership. Electronics generates the highest margin capture through specification-driven procurement.
Formulation Type:
Formulation segmentation captures the technology transition from solvent architectures to water-based and energy-curable systems under tightening emissions regulations.
- Water-Based:Silicone emulsion technology migrates from niche to mainstream converter operations as EPA VOC standards under the Clean Air Act constrain solvent production in US facilities. Major tape manufacturers complete line conversions at accelerated pace.
- Solvent-Based:Legacy systems face compressed demand as REACH registration requirements for silicone oligomers impose reformulation burdens on European operations. Capital-intensive drying equipment modifications deter converter transitions.
- Hot Melt:Thermoplastic formulations serve high-speed coating operations with immediate bond strength and no drying energy requirements.
- Powder:Dry silicone powder coatings enable specialized applications where liquid carrier systems contaminate substrates.
Solvent-based formulations hold residual share in legacy electronics applications. Water-based systems climb the fastest as regulatory thresholds tighten across manufacturing jurisdictions.
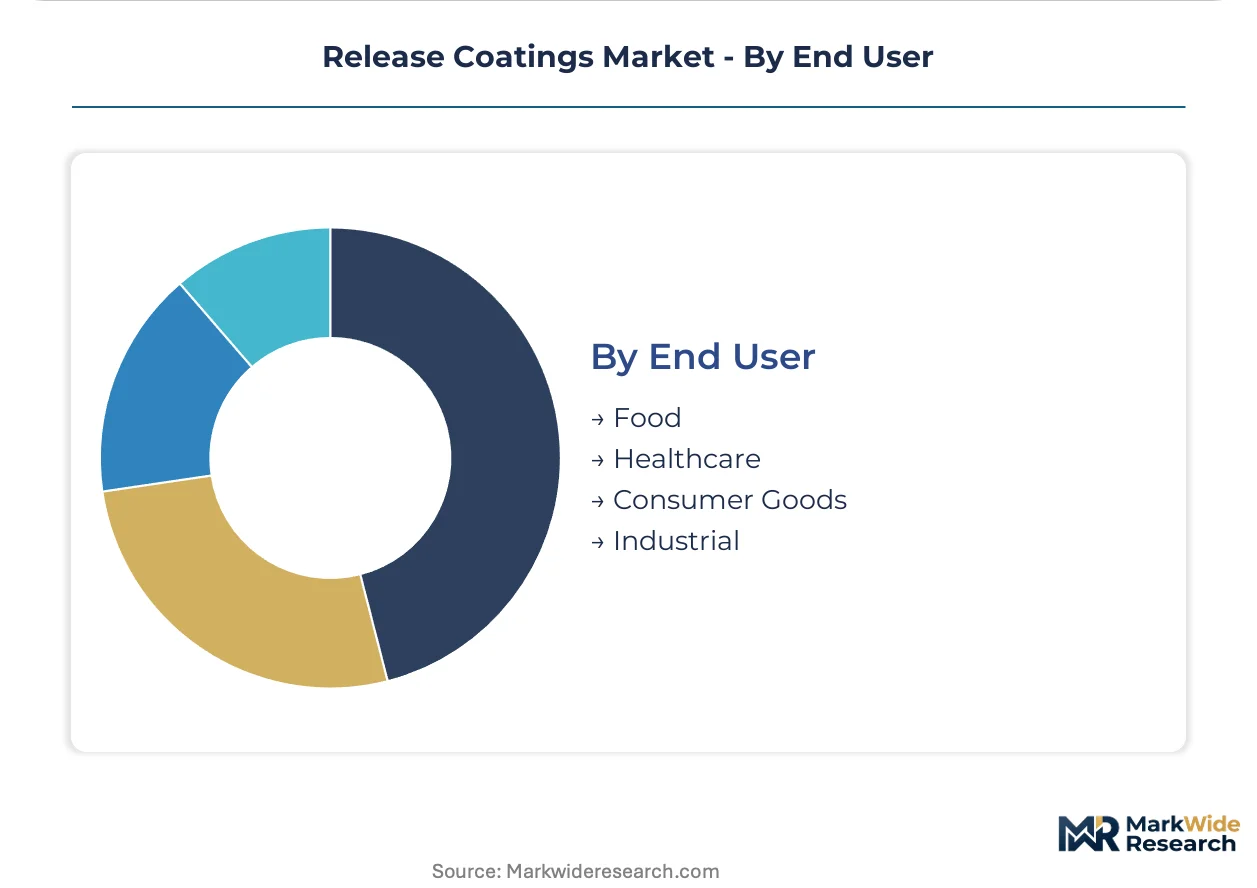
End User:
End user segmentation distinguishes between regulated food contact applications and specification-intensive healthcare markets.
- Food:Indirect food contact regulations under FDA 21 CFR 177.2260 and EU Framework Regulation 1935/2004 specify extractable limits for silicone migration. Brand owners mandate certified low-outgassing release liners as consumer safety standards exceed baseline requirements.
- Healthcare:Infant care and adult incontinence applications drive hygiene product manufacturing specifications. Converter qualification programs in Germany and Japan have replaced spot purchasing with approved-supplier frameworks.
- Consumer Goods:Personal care and household product packaging sustains volume demand through private label and branded manufacturing.
- Industrial:Manufacturing process release applications span composite molding, rubber processing, and metal forming where temperature and chemical resistance priorities vary.
Food contact applications anchor volume throughput. Healthcare commands the steepest expansion trajectory as safety certification requirements intensify procurement selectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA VOC emission standards under the Clean Air Act constrain solvent-based formulation production in US manufacturing facilities, while REACH registration requirements govern silicone oligomer classifications across European coating operations. China's GB standards for industrial volatile organic compound limits tighten compliance thresholds for domestic release coating producers.
United States
Food packaging converters in the Midwest and Southeast are expanding silicone-based release liner adoption to meet extended shelf-life requirements for ready-to-eat segments. FDA 21 CFR 177.2260 extractable limits govern indirect food contact validation cycles of 18–24 months. Tape manufacturing clusters in Ohio and Illinois anchor regional consumption through integrated supply relationships with hygiene product brand owners.
Germany
Automotive adhesive tape manufacturing in Baden-Württemberg and Bavaria anchors regional silicone release coating consumption through tier supplier integration. EU Green Deal packaging waste directives accelerate solvent-to-water formulation transitions across converter operations. Stuttgart's concentration of OEM engineering centers drives specification intensity for lightweighting-compatible bonding solutions.
China
Dual carbon policy alignment through GB standards for industrial volatile organic compound limits accelerates domestic water-based formulation adoption. Expanded silicone monomer and emulsion capacity additions in Jiangsu and Zhejiang provinces reconfigure regional supply dynamics. Yangtze River Delta coating producers are completing line conversions at accelerated pace under tightening emissions enforcement.
Japan
Electronics-grade optical display bonding applications in Osaka and Nagoya command premium positioning through ultra-low outgassing specifications below 10 ppm total volatile organic compounds. METI industrial standards guide formulation chemistry pivots toward sustainable architectures. Kansai region semiconductor manufacturing clusters sustain demand for UV-curable silicone systems that solvent alternatives cannot satisfy.
South Korea
Display panel manufacturing in Gyeonggi Province drives specification-driven procurement for certified low-outgassing release liners. MFDS regulations for hygiene product safety intensify procurement selectivity among infant care brand owners. Seoul Capital Area converter qualification programs have replaced spot purchasing with approved-supplier frameworks across electronics and healthcare segments.
Release Coatings Market Vendor Landscape
Capability concentration sits with integrated silicone feedstock producers; scale advantage sits with diversified chemical conglomerates with coating formulation breadth. The market structure separates into three tiers: captive monomer suppliers with backward integration, independent formulators with specialized emulsion technology, and regional converters with coating line assets. Strategic moves center on water-based emulsion capacity expansion and technology licensing partnerships for UV-curable system penetration.
Within the integrated feedstock tier, Dow Inc. and Shin-Etsu Chemical Co., Ltd. exemplify archetypes of geographic diversification across North American and Asian manufacturing complexes. Wacker Chemie AG occupies a position spanning solvent-based, water-based, and UV-curable release systems for pressure-sensitive adhesive converters. These three anchors represent distinct competitive vectors: Dow through integrated silicone positions, Shin-Etsu through proprietary polymer architecture, and Wacker through formulation breadth across curing chemistries.
| Leading Market Players |
|---|
| Dow Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials Inc. |
| Wacker Chemie AG |
| Evonik Industries |
| Elkem ASA |
| HITAC Adhesives & Coatings |
| Mayzo, Inc. |
| Henkel AG & Co. KGAA |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion cost dynamics compress margins for European formulators importing Chinese silicone monomer feedstock while amplifying price spreads between captive-integrated suppliers and merchant-market buyers across the release coatings value chain.
Pricing Analysis
Geographic price spreads between Asia-origin and Europe-delivered silicone emulsion widened as freight differentials and carbon-border adjustment mechanisms layered onto base chemical costs. Three-tier pricing structure across electronics-grade fluoropolymer, food-contact silicone, and industrial polyolefin separates premium UV-curable systems from commodity water-based formulations. Pricing pressure stems from Chinese domestic capacity expansion flooding regional emulsion markets. Tier suppliers in automotive adhesive tape manufacturing exhibit highest price sensitivity; electronics optical display bonders accept premium positioning for ultra-low outgassing certification.
Supply Chain Analysis
Export-control regimes limiting fluorinated polymer technology transfers constrain Western access to next-generation perfluorinated architectures for semiconductor-grade release applications. China, Germany, and Japan concentrate silicone monomer and formulated coating supply. Raw material dependencies center on methylchlorosilane feedstock, platinum catalyst systems, and UV photoinitiator packages. Single-source vulnerability runs through Jiangsu Province silicone monomer complexes. Distribution runs through pressure-sensitive adhesive converter direct contracts rather than merchant chemical distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemist pipelines fail to replenish retirement-driven attrition, constraining innovation velocity for water-based emulsion architectures and UV-curable system engineering across the industry.
For Market Incumbents: Build captive monomer supply moats through backward integration into silicone feedstock or long-term offtake agreements with Chinese producers. Defend against merchant-market price erosion by securing FDA 21 CFR 177.2260 pre-validated product platforms. Expand water-based emulsion capacity in Germany to serve EU Green Deal packaging converter demand. For New Entrants and Emerging Players: Pursue technology licensing partnerships with Yangtze River Delta producers seeking European market access. Target India's underpenetrated food packaging conversion sector where extended-shelf-life silicone release liner demand outpaces domestic supply. Lead with UV-curable system specialization for electronics-grade optical display bonding applications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated emulsion producers with captive monomer positions over independent formulators exposed to feedstock volatility. Long-term viability hinges on water-based formulation patent estates and regulatory pre-certification libraries. Watch for ECHA oligomer classification enforcement actions as inflection signals for polymer architecture obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Monomer | Captive methylchlorosilane supply secures margin control against Chinese export price volatility. |
| Water-Based Emulsion Capacity Expansion | EU Green Deal packaging directives accelerate solvent-to-water converter line conversions. |
| UV-Curable System Technology Licensing | Electronics-grade optical display bonding specifications exclude legacy solvent formulations. |
| FDA Pre-Validation Program Investment | 18-24 month food contact certification cycles create switching costs for approved suppliers. |
| Joint Venture with India Packaging Converters | Food processing sector expansion outpaces domestic release liner manufacturing capacity. |
Methodological Framework
Cross-validation between primary interviews with silicone polymer chemists, pressure-sensitive adhesive procurement directors, and food packaging converter operations managers and secondary validation through SEC 10-K filings, customs trade data, and ECHA substance registration databases anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down chemical industry capacity assessments.
Calibration against historical silicone monomer price cycles and converter line conversion announcements shapes the analytical framework across the projection horizon. Segmentation dimensions span formulation chemistry, curing mechanism, end-use industry, and regional regulatory cluster. CAGRs derive from elasticity-adjusted volume projections and value-per-unit trend analysis. Forecast inputs incorporate EPA VOC enforcement intensity indices and EU packaging waste directive implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed chemical conglomerates would shift outcomes. Material shifts in REACH oligomer classification thresholds or FDA extractable limit revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
North America Barrier Films Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Special Effects Laminate Films Market