
 Water Resistant Packaging Market | 2026-2036
Water Resistant Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Water Resistant Packaging Market Analytics
ISO 11607 compliance for sterile barrier systems is bifurcating the competitive landscape into certified medical-grade suppliers and general industrial players. Amcor leverages its pharmaceutical certification footprint across European sterile packaging lines. Smurfit Kappa anchors its position through integrated pulp-to-box operations in Iberia and the Nordics. Mondi Group differentiates via proprietary Advantage Barrier papers that replace plastic laminates in food pouches.
Water resistant packaging denotes engineered enclosures incorporating hydrophobic substrates, extrusion-coated barriers, or sealed seam constructions to maintain product integrity under humidity exposure, condensation, or incidental liquid contact. The primary commercial purpose centers on extending shelf stability for moisture-degradable goods during transport, storage, and retail display. Plastic material formats still dominate volume due to polyethylene and polypropylene cost structures, though composite material laminates capture expanding margin pools in pharmaceutical blister applications. Pouch formats represent the fastest-growing packaging type as single-serve and flexible configurations displace rigid containers in personal care and electronics.
FDA 21 CFR Part 211 governs pharmaceutical packaging validation requirements in the United States, while the EU MDR tightens traceability and barrier performance standards for sterile medical devices. ECHA REACH restrictions on per- and polyfluoroalkyl substances are forcing material reformulation across European supply chains. Stakeholders must monitor pending PFAS bans in multiple jurisdictions and pre-qualify alternative barrier chemistries before regulatory deadlines eliminate incumbent formulations.
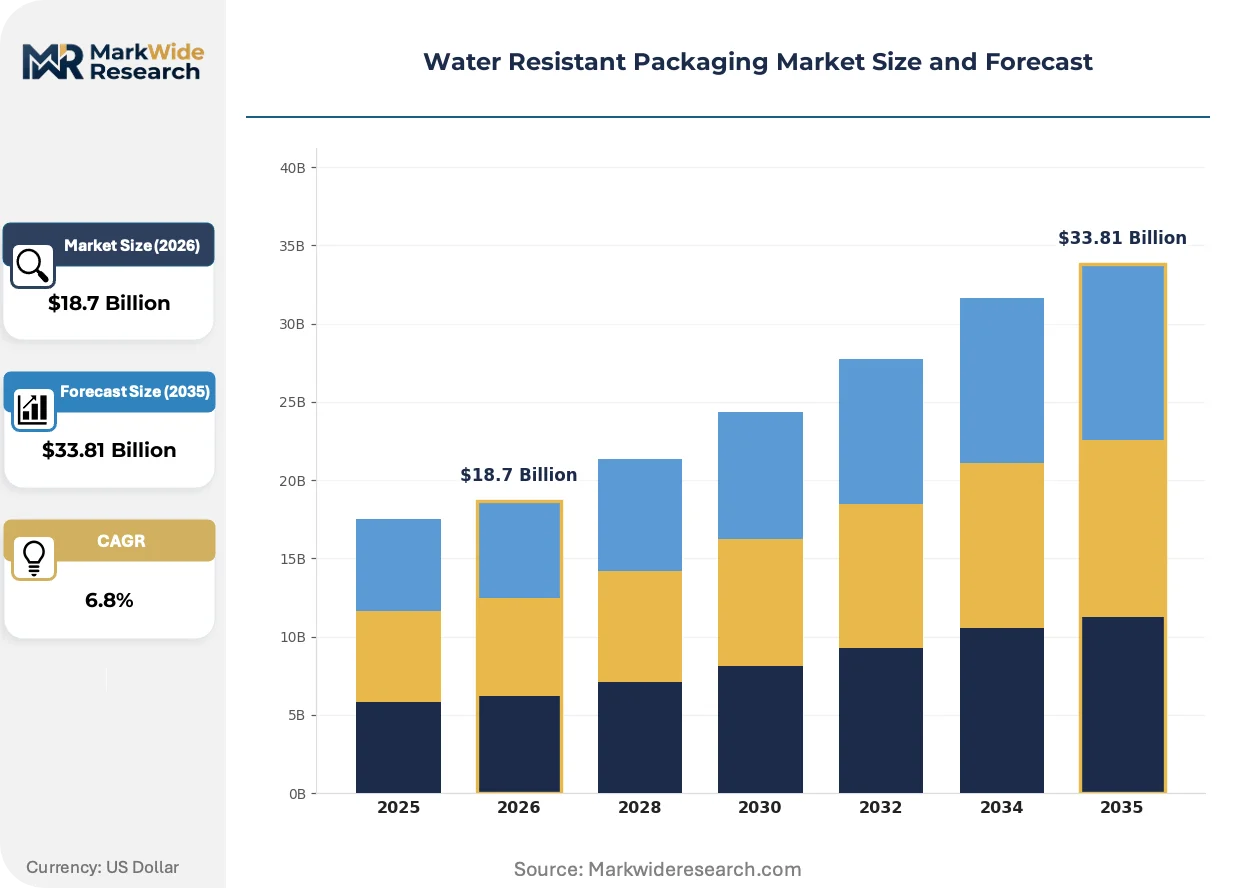
Market Dynamics
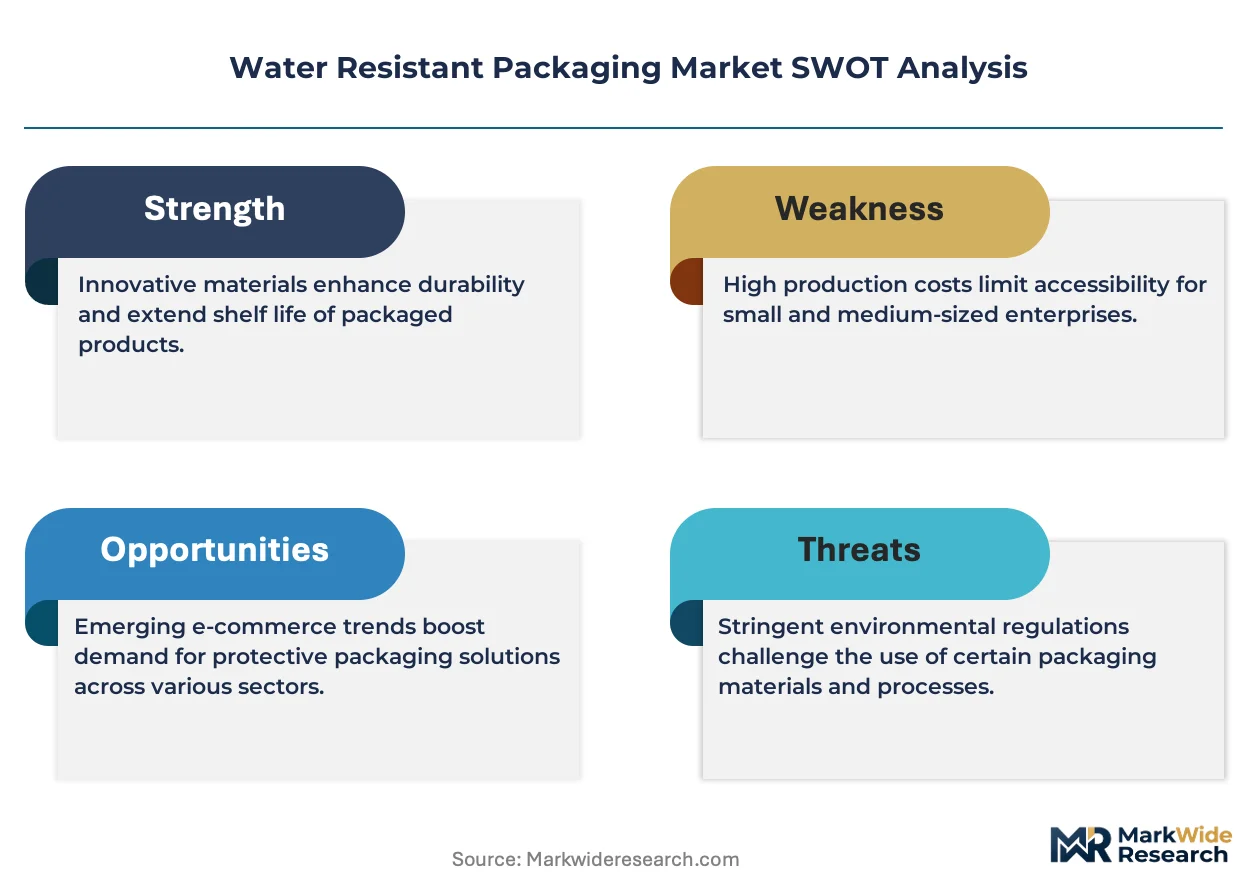
Material substitution pressure from ECHA REACH PFAS restrictions is forcing rapid reformulation across European supply chains, bifurcating the competitive landscape between certified medical-grade suppliers and general industrial players unable to absorb compliance costs.
Growth Catalysts
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics require moisture-barrier protection during transport, driving adoption of ISO 11607-compliant sterile barrier systems across logistics networks.
- EU Packaging and Packaging Waste Regulation:Tightened material recovery targets are accelerating investment in recyclable barrier substrates and closed-loop collection infrastructure.
- Pouch format migration:Single-serve and flexible configurations are capturing share from rigid containers in personal care and electronics end-uses.
Market Restraints
- Petrochemical input volatility:Polyethylene and polypropylene resin costs fluctuate with crude oil indices, compressing margins for commodity-grade producers.
- Certification concentration:FDA 21 CFR Part 211 and EU MDR validation requirements limit sterile packaging supply to a narrow base of qualified converters.
- Per- and polyfluoroalkyl substance dependency:Legacy fluorinated chemistries face pending bans in multiple jurisdictions, stranding existing barrier formulations.
Strategic Opportunities
- German industrial corridor:Demand concentrates in the Rhine-Ruhr and Baden-Württemberg packaging clusters serving automotive and precision electronics exports.
- Composite laminate pharmaceuticals:Blister applications with aluminum-polymer hybrids capture expanding margin pools as biologics penetration deepens.
- Integrated pulp-to-box operations:Nordic and Iberian fiber-based barrier production offers defensible positions against plastic taxation regimes.
Industry Challenges
- Alternative chemistry pre-qualification:Stakeholders must validate non-fluorinated barrier formulations before regulatory deadlines eliminate incumbent options.
- Traceability system integration:EU MDR unique device identification requirements demand serialization infrastructure that smaller converters lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Resistant Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Boxes, Pouches, Containers Material: Plastic, Paper, Metal, Composite End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Sales Channel: Online, Retail, Wholesale, Direct |
| Companies Covered | International Paper Company, Georgia-Pacific LLC, Smurfit Kappa, Mondi Group, Amcor, Berry Global, WestRock Company, Sonoco Products Company, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Resistant Packaging Market Evolving Landscape
Barrier material science is pivoting from petrochemical dependence toward bio-based and fiber-derived alternatives, reshaping R&D priorities and capital allocation across the value chain.
Proprietary Advantage Barrier papers and similar fluorine-free substrates are displacing plastic laminates in food pouch applications. Major food manufacturers in Northern Europe are specifying these materials for ready-meal and snack packaging. The shift is compressing demand for conventional polyethylene terephthalate structures in segments where moisture protection requirements are moderate.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy barrier chemistries from European supply chains. Material suppliers are accelerating investment in silicone-based and bio-wax alternative formulations. Pharmaceutical and medical device segments face the steepest compliance timelines, with sterile barrier suppliers pre-qualifying new substrates under FDA and EMA parallel review pathways.
Brand owners are consolidating supplier relationships around converters with dual pharmaceutical and food-grade certifications. This concentration favors integrated producers with in-house extrusion coating and sterilization validation capabilities. The pattern is most visible in Germany and the Netherlands, where multinational hygiene and nutrition companies are reducing their approved vendor lists by forty to sixty percent.
Water Resistant Packaging Market Segmentation
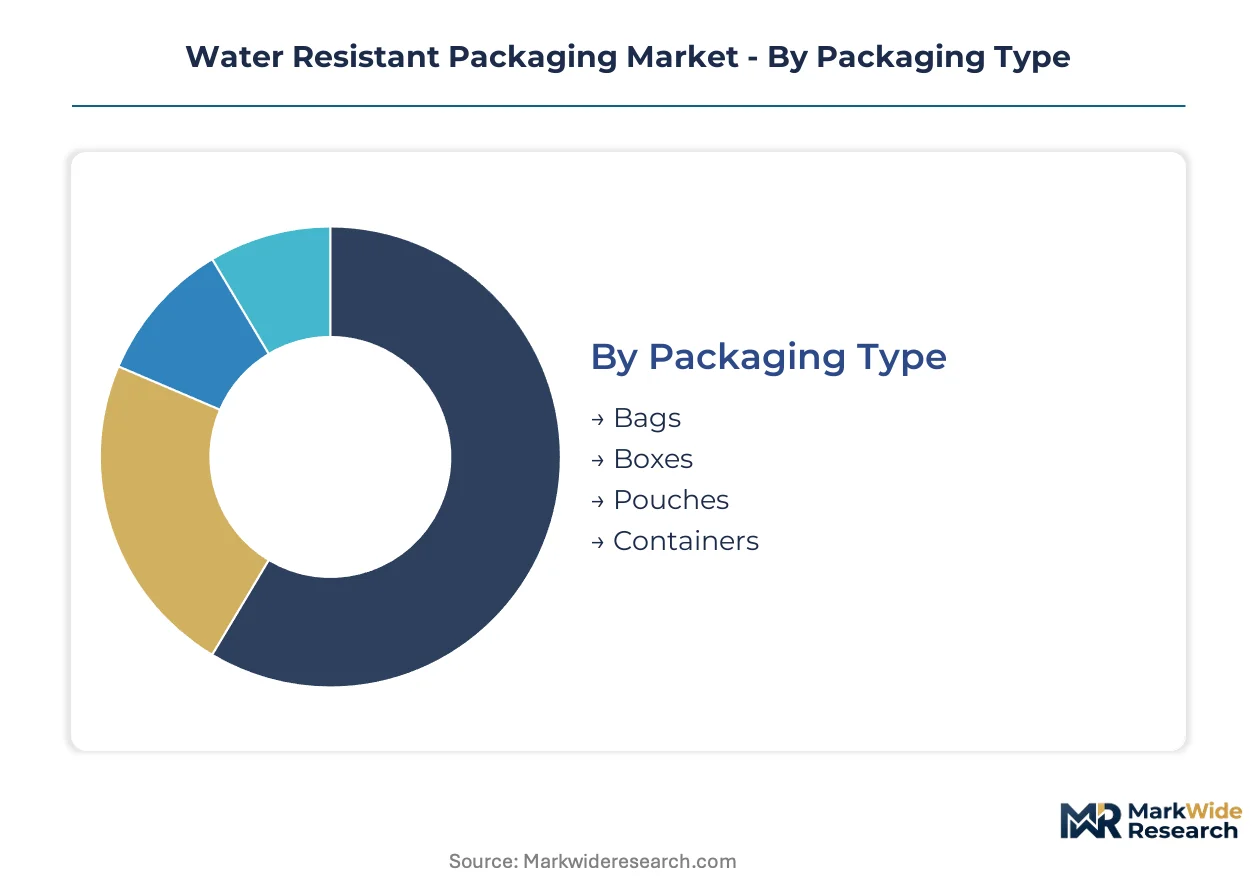
Water resistant packaging segments map to distinct procurement channels and technical specifications. Pharmaceutical and food-grade buyers prioritize ISO 11607 compliance and EFSA migration limits, while industrial purchasers optimize for polyethylene cost structures and palletization efficiency.
Packaging Type:
Pouches flow through retail and e-commerce channels for single-serve applications. Boxes dominate B2B wholesale for industrial components. Bags and containers split between direct procurement by food processors and distributor-mediated electronics supply chains.
- Pouches:Flexible laminates with heat-sealed seams enable portion control and reduced material intensity. Mondi's Advantage Barrier papers and similar fluorine-free substrates are displacing conventional polyethylene terephthalate in Northern European ready-meal packaging, driven by ECHA REACH PFAS restrictions and brand owner sustainability mandates.
- Boxes:Corrugated fiberboard with extrusion-coated polyethylene or wax barriers protects automotive and precision electronics exports from Rhine-Ruhr and Baden-Württemberg clusters. Smurfit Kappa's integrated pulp-to-box operations in Iberia and the Nordics capture volume as plastic taxation regimes expand.
- Bags:Multi-layer polyethylene or polypropylene structures with sealed closures serve bulk food ingredients and chemical intermediates.
- Containers:Rigid polypropylene or high-density polyethylene formats with gasketed lids preserve pharmaceutical tablet stability and laboratory reagent integrity.
Boxes dominate installed base. Pouches are where expansion concentrates.
Material:
Cost tiers separate commodity resin grades from certified pharmaceutical substrates. Plastic commands volume at economy pricing. Composite laminates capture premium margin pools in blister applications.
- Plastic:Polyethylene and polypropylene films with extrusion-coated barriers remain the default for moisture protection at scale. Petrochemical input volatility compresses margins for commodity-grade producers serving food and industrial end-uses, forcing converters toward long-term resin contracts or backward integration into polymer compounding.
- Composite:Aluminum-polymer hybrid laminates meet ISO 11607 sterile barrier requirements for temperature-sensitive biologics. Amcor leverages pharmaceutical certification footprints across European sterile packaging lines to capture expanding margin pools as biologics penetration deepens.
- Paper:Fiber-based barriers with bio-wax or silicone coatings replace plastic laminates in segments with moderate moisture protection requirements.
- Metal:Tinplate and aluminum cans provide hermetic sealing for high-value pharmaceuticals and aggressive chemical formulations.
Plastic holds volume leadership. Composite laminates are climbing the fastest.
End User:
Application requirements dictate barrier performance tiers. Pharmaceuticals demand sterile validation. Food and beverage optimizes for total cost of ownership.
- Pharmaceuticals:FDA 21 CFR Part 211 and EU MDR validation requirements limit sterile packaging supply to qualified converters with serialization infrastructure. Temperature-sensitive biologics require moisture-barrier protection during cold chain transport, driving adoption of ISO 11607-compliant systems.
- Food & Beverage:EFSA migration limits and plastic taxation regimes in multiple European jurisdictions accelerate specification of recyclable barrier substrates. Major manufacturers in Germany and the Netherlands are consolidating supplier relationships around dual-certified converters.
- Electronics:Precision components from Baden-Württemberg automotive clusters require humidity protection during export shipment.
- Personal Care:Single-serve flexible formats displace rigid containers in travel and sampling applications.
Food and beverage anchors volume. Pharmaceuticals is where margin expansion concentrates.
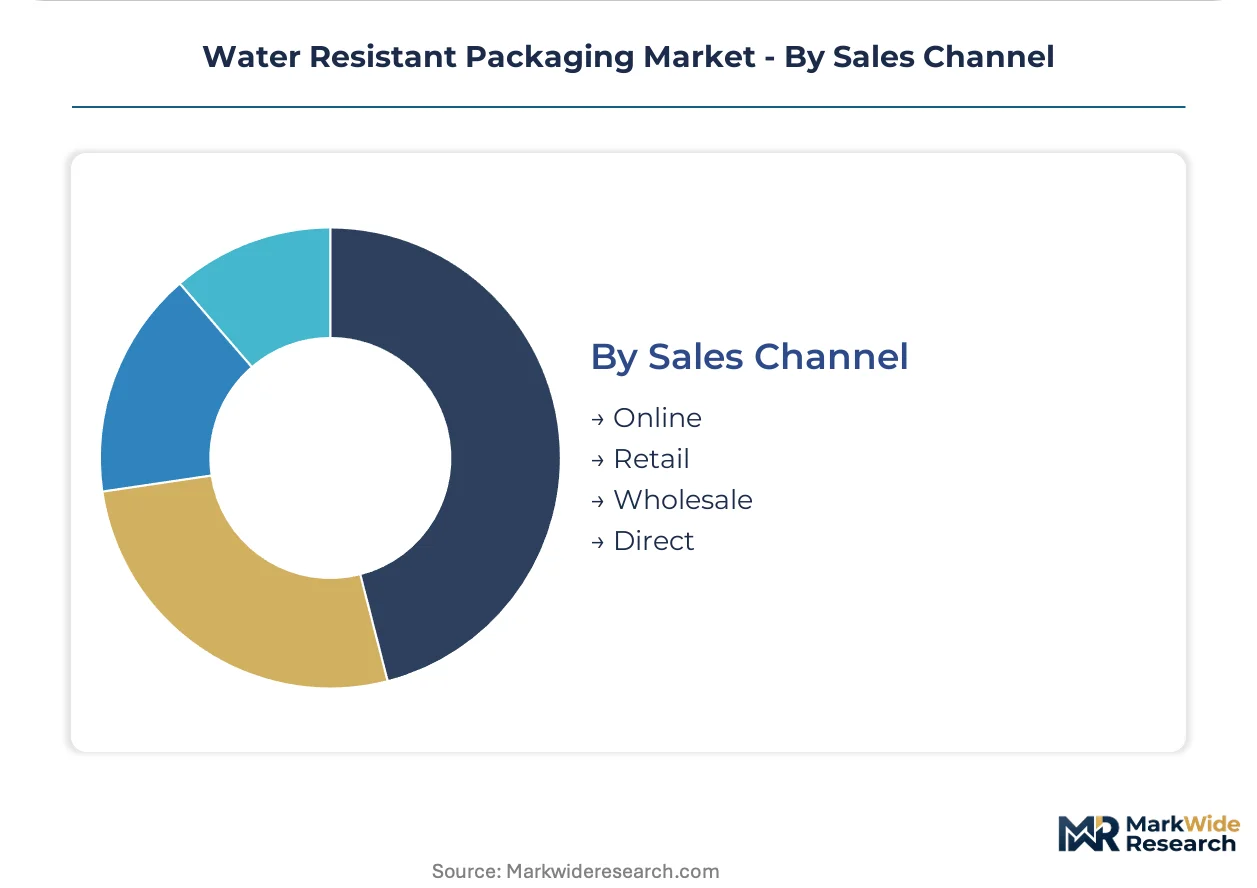
Sales Channel:
Customer scale and certification requirements determine channel selection. Multinationals pursue direct relationships. Smaller manufacturers rely on distributor networks.
- Direct:Long-term supply agreements with pharmaceutical multinationals and food manufacturers specify validated barrier performance, serialization compliance, and audit rights. Brand owners in Germany and the Netherlands have reduced approved vendor lists by forty to sixty percent, concentrating procurement around integrated producers with in-house extrusion coating capabilities.
- Wholesale:Industrial packaging distributors serve mid-tier electronics and automotive suppliers with standardized polyethylene and polypropylene formats.
- Retail:Specialty packaging retailers stock standardized pouch and container formats for small-batch food processors and cosmetic formulators.
- Online:E-commerce platforms enable specification of custom barrier configurations for niche pharmaceutical and diagnostic applications.
Direct channels dominate pharmaceutical procurement. Wholesale captures industrial volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical cold chain buyers cluster in Germany's industrial corridor, while food-grade procurement concentrates in the Netherlands and Nordic fiber-producing regions. Regulatory divergence between ECHA REACH restrictions and FDA validation requirements shapes supplier qualification strategies across export markets.
Germany
ISO 11607-compliant sterile barrier demand from Baden-Württemberg precision electronics and Rhine-Ruhr automotive exporters drives specification of composite laminates. ECHA REACH PFAS restrictions force material reformulation timelines that favor converters with in-house R&D capabilities. The Stuttgart packaging cluster anchors biologics cold chain infrastructure serving EU-wide distribution networks.
United States
FDA 21 CFR Part 211 validation requirements limit sterile packaging supply to qualified converters with serialization infrastructure for pharmaceutical track-and-trace. Temperature-sensitive biologics penetration deepens moisture-barrier adoption across cold chain logistics networks. New Jersey and North Carolina pharmaceutical manufacturing corridors concentrate procurement of high-performance barrier substrates.
Netherlands
EFSA migration limits and plastic taxation regimes accelerate brand owner consolidation around dual-certified converters with pharmaceutical and food-grade qualifications. The Randstad logistics hub serves as a distribution nexus for Northern European ready-meal and snack packaging specifications. Major nutrition companies have reduced approved vendor lists by forty to sixty percent, favoring integrated producers.
Sweden
Nordic pulp-to-box operations capture volume as EU Packaging and Packaging Waste Regulation recovery targets expand across member states. Integrated fiber-based barrier production offers defensible positioning against escalating plastic resin taxation. The Gothenburg industrial packaging corridor supplies automotive and precision electronics exporters with extrusion-coated corrugated formats.
China
SAMR packaging standards and dual carbon goals reshape material specifications for export-oriented electronics manufacturers in the Yangtze River Delta. NMPA pharmaceutical packaging regulations tighten traceability requirements for sterile medical device exports. The Shanghai-Pudong logistics cluster anchors moisture-barrier procurement for temperature-sensitive biologics distribution across Asia-Pacific markets.
Water Resistant Packaging Market Competitive Landscape
Player mix skews toward integrated paper-based converters with captive fiber supply and multinational film specialists with pharmaceutical certification footprints. The competitive structure bifurcates between certified medical-grade suppliers absorbing ECHA REACH compliance costs and general industrial players facing margin compression from petrochemical volatility. Three archetypes dominate: integrated pulp-to-box operators, pharmaceutical-grade laminators, and commodity resin converters. Capacity expansion in Nordic fiber barriers and strategic partnerships for PFAS-free chemistry pre-qualification represent the primary competitive vectors.
Among integrated European operators, Smurfit Kappa and Mondi Group exemplify the pulp-to-box archetype with fiber-based barrier production positioned against plastic taxation regimes. Amcor anchors the pharmaceutical-grade laminator tier with sterile packaging lines validated under FDA and EMA parallel review pathways. These three companies occupy positions that concentrate procurement relationships as brand owners reduce approved vendor lists and consolidate around dual-certified converters with in-house extrusion coating capabilities.
| Leading Market Players |
|---|
| International Paper Company |
| Georgia-Pacific LLC |
| Smurfit Kappa |
| Mondi Group |
| Amcor |
| Berry Global |
| WestRock Company |
| Sonoco Products Company |
| DS Smith |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR Part 211 and EU MDR validation requirements simultaneously gate sterile packaging supply and stratify pricing tiers, concentrating procurement power among dual-certified converters while compressing margins for commodity-grade producers unable to absorb compliance infrastructure costs.
Pricing Analysis
Cost-plus contracts with polyethylene and polypropylene resin indexation dominate pharmaceutical and food-grade procurement, insulating qualified converters from petrochemical volatility while exposing commodity producers to margin compression. Three-tier pricing structure across ISO 11607-certified premium, food-grade standard, and industrial economy levels reflects certification investment amortization and serialization infrastructure requirements. Pricing pressure stems from ECHA REACH PFAS reformulation timelines forcing rapid alternative chemistry pre-qualification. Industrial buyers exhibit highest price sensitivity, while pharmaceutical multinationals prioritize barrier performance assurance over unit cost.
Supply Chain Analysis
Strategic stockpiling of aluminum-polymer hybrid substrates and bio-wax coated fiberboard prevails among pharmaceutical converters facing EU MDR compliance deadlines, while just-in-time resin procurement characterizes commodity polyethylene operations. Supply concentrates in Germany, Sweden, and the Netherlands, with Nordic pulp-to-box operations and Rhine-Ruhr extrusion coating clusters anchoring regional capacity. Raw material dependencies encompass kraft pulp, polyethylene terephthalate resin, and silicone-based barrier chemistries. Single-source vulnerability runs through legacy fluorinated coating suppliers facing regulatory elimination. Distribution runs through direct long-term agreements for pharmaceutical grades and wholesale distributor networks for industrial formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water resistant packaging fragmentation creates acquisition opportunities as brand owner consolidation around dual-certified suppliers eliminates mid-tier converters, while PFAS substitution timelines open niche positions for alternative chemistry specialists.
For Market Incumbents: Secure ISO 11607 certification extensions into adjacent food-grade applications before ECHA REACH deadlines eliminate single-certified competitors. Anchor capacity expansion in Nordic fiber corridors to capture plastic taxation-driven specification shifts. Prioritize backward integration into bio-wax coating compounding to defend margin position against petrochemical input volatility and fluorinated chemistry obsolescence. For New Entrants and Emerging Players: FDA-EMA parallel review pathway fast-track offers entry wedge into sterile barrier supply constrained by incumbent concentration. Target underpenetrated personal care pouch segments in German e-commerce channels where flexible format migration outpaces qualified converter capacity. Pursue private-label partnerships with Northern European ready-meal manufacturers specifying Mondi-type fluorine-free substrates. For Investors and Strategic Acquirers: ECHA REACH PFAS ban implementation reshapes the acquisition landscape toward converters with pre-qualified alternative barrier formulations and existing pharmaceutical certification footprints. Five-to-ten-year viability favors integrated pulp-to-box operators with captive fiber supply and in-house extrusion coating capabilities over resin-dependent commodity converters. Monitor EU MDR unique device identification deployment rates as inflection indicator for serialization infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Chemistry Pre-Qualification | EMA parallel review pathways accelerate sterile barrier substrate validation before regulatory deadlines eliminate incumbent formulations. |
| Nordic Pulp-to-Box Capacity Expansion | Integrated fiber-based barrier production captures volume as EU Packaging and Packaging Waste Regulation recovery targets expand. |
| Pharmaceutical-Food Dual Certification | ISO 11607 and EFSA migration limit compliance opens procurement relationships with consolidating brand owners in Germany and Netherlands. |
| Serialization Infrastructure Deployment | EU MDR unique device identification requirements create defensible positioning among qualified sterile packaging converters. |
| Long-Term Resin Contracting | Polyethylene and polypropylene indexation agreements insulate margins from petrochemical volatility affecting commodity producers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with sterile packaging procurement managers, regulatory affairs directors at pharmaceutical multinationals, extrusion coating plant engineers, and food manufacturer supply chain leads; and secondary validation against EMA submission databases, FDA 21 CFR Part 211 guidance documents, ECHA REACH restriction proposals, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across material, format, and end-use dimensions.
Across the analysis window, the forecasting framework modeled packaging type, material substrate, end-use industry, and geographic regulatory cluster segmentation. CAGRs derived from elasticity-adjusted demand projections incorporating biologics cold chain expansion rates, PFAS substitution timelines, and plastic taxation regime diffusion patterns. Industry-specific inputs included pharmaceutical serialization infrastructure deployment curves and Nordic pulp capacity utilization rates.
Decision-makers should treat outputs as directional under assumptions of ECHA REACH PFAS ban implementation timelines and EU MDR compliance adherence; material deviation in regulatory enforcement intensity or alternative chemistry validation success rates would warrant model refresh. Revision becomes warranted when sterile barrier supplier consolidation accelerates beyond projected vendor list reduction thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market