
 Release Liners Market | 2026-2036
Release Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Release Liners Market Intelligence
Medical device end-use demand is consolidating as a primary demand pillar for high-purity release liners. 3M Company leverages its polymer science capabilities to dominate medical-grade silicone-coated substrates. Avery Dennison Corporation sustains leadership in pressure-sensitive adhesive laminates through controlled coating consistency. LINTEC Corporation anchors Asian supply chains with precision-manufactured polyester film liners for electronics fabricators.
Release liners are thin, flexible substrates—typically paper, film, or glassine—bearing a controlled-release coating that enables clean separation from aggressive adhesives without residue transfer or surface damage. Silicone-coated paper dominates volume production due to its cost-efficiency and broad compatibility with acrylic and rubber-based adhesives, while polyester film variants command premium positioning in electronics assembly where dimensional stability under thermal stress is non-negotiable. Fluoropolymer coatings represent the fastest-expanding coating material segment, driven by extreme-release requirements in medical dressings and advanced composite manufacturing where standard silicone chemistries fail.
FDA medical device substrate regulations and EU MDR biocompatibility frameworks restrict unqualified materials from patient-contact applications, elevating certification costs but creating defensible margin pools for approved suppliers. REACH chemical restrictions and EPA emissions standards further constrain solvent-based coating processes, pressuring converters toward UV-curable and waterborne alternatives. Stakeholders must monitor evolving substrate qualification timelines and coating chemistry transitions as regulatory divergence between jurisdictions reshapes sourcing strategies.
Market Dynamics
Medical-grade substrate qualification timelines are compressing as FDA and EU MDR biocompatibility frameworks tighten patient-contact material standards, forcing converters to accelerate coating chemistry transitions toward UV-curable and waterborne alternatives.
Growth Catalysts
- EU MDR biocompatibility mandates:Patient-contact material standards are elevating certified substrate demand across wound care and transdermal patch manufacturing in Germany and France.
- Electronics fabricators:South Korean and Taiwanese semiconductor assemblers are expanding precision polyester film liner consumption for thermal-stress dimensional stability requirements.
- Fluoropolymer coating chemistry:Extreme-release medical dressings and advanced composite manufacturing are driving fastest-expanding coating material adoption where silicone fails.
Market Restraints
- Petrochemical feedstock volatility:Silicone polymer and polyester resin input costs fluctuate with crude oil derivatives, squeezing converter margins unpredictably.
- East Asian supply concentration:Precision-coated film substrate production clusters heavily in South Korea and Japan, creating single-source vulnerability for Western converters.
- Solvent-based coating regulatory friction:REACH chemical restrictions and EPA emissions standards are forcing costly process retooling before waterborne alternatives achieve performance parity.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO medical device regulations are maturing, creating first-mover advantage for qualified substrate suppliers in domestic transdermal and diagnostic strip production.
- Carbon fiber prepreg manufacturing:Aerospace and wind energy composite fabricators need extreme-release fluoropolymer liners for epoxy resin systems.
- UV-curable coating convergence:Energy-curable silicone hybrid chemistries eliminate solvent recovery infrastructure while meeting FDA extraction test requirements.
Industry Challenges
- Coating technician skill scarcity:Precision thickness control and release force calibration require specialized expertise that vocational pipelines are not replenishing.
- ISO 10993 certification timelines:Biocompatibility testing protocols for new substrate-coating combinations extend qualification cycles 18-24 months.
- Legacy solvent coating asset stranding:Converters face write-down pressure on depreciated thermal drying lines that cannot retrofit to electron beam or UV curing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Release Liners Market |
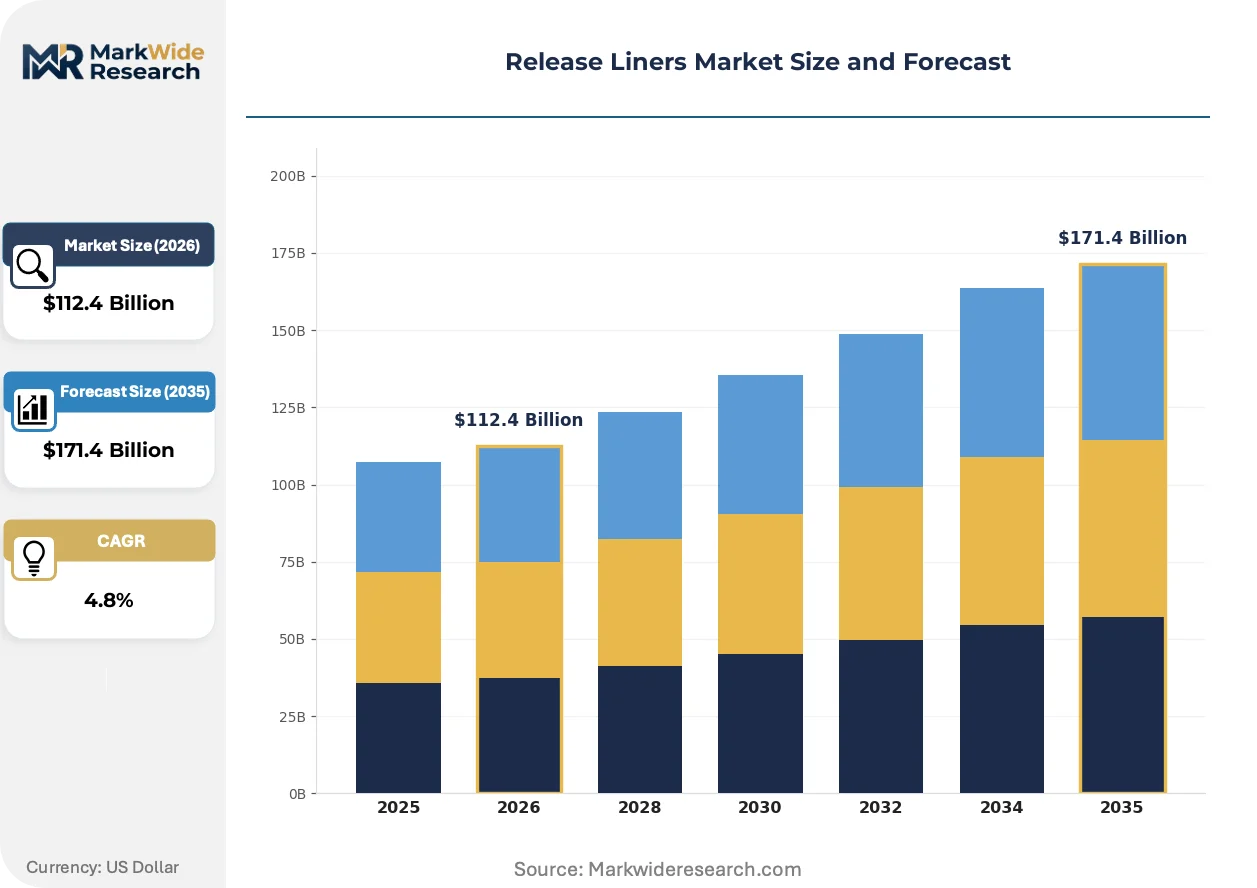
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $171.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Coated, Polyethylene Coated, Polypropylene Coated, Glassine, Polyester Film Coating Material: Silicone, Acrylic, Fluoropolymer, Rubber, UV Curable Application: Pressure Sensitive Adhesives, Medical Dressings, Labeling, Electronics Assembly, Construction Tapes End User Industry: Consumer Goods Manufacturers, Medical Device Producers, Electronics Fabricators, Construction Firms, Printing Entities |
| Companies Covered | 3M Company, Avery Dennison Corporation, Sappi Limited, LINTEC Corporation, Mondi Group, Loparex, Ahlstrom, UPM Raflatac, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Release Liners Market Strategic Shifts & Innovations
Coating chemistry electrification and substrate precision requirements are restructuring competitive capabilities across medical, electronics, and industrial adhesive applications.
Fluorosilicone hybrid release coatings are electrifying extreme-release application segments. Medical dressing manufacturers in Switzerland and Germany are adopting these chemistries for silicone gel adhesive interfaces where standard polydimethylsiloxane coatings exhibit excessive release force. The technology is electrifying premium substrate positioning by enabling clean separation from aggressively tacky medical-grade adhesives without surface contamination.
EU MDR Annex I general safety and performance requirements are reclassifying release liner risk profiles. Substrate suppliers must now demonstrate biological evaluation per ISO 10993 series standards for any material contacting patient skin, even indirectly. German and French wound care converters are responding by consolidating qualified supplier bases and demanding batch-level extractables documentation.
Direct mill procurement is displacing distributor intermediaries in high-volume electronics segments. South Korean display panel manufacturers now specify polyester film liner release force tolerances in supply agreements with coating mills rather than trading houses. This pattern is most visible in Gyeonggi-do manufacturing clusters where just-in-time adhesive lamination lines demand substrate consistency that distributor blending cannot guarantee.
Release Liners Market Segmentation
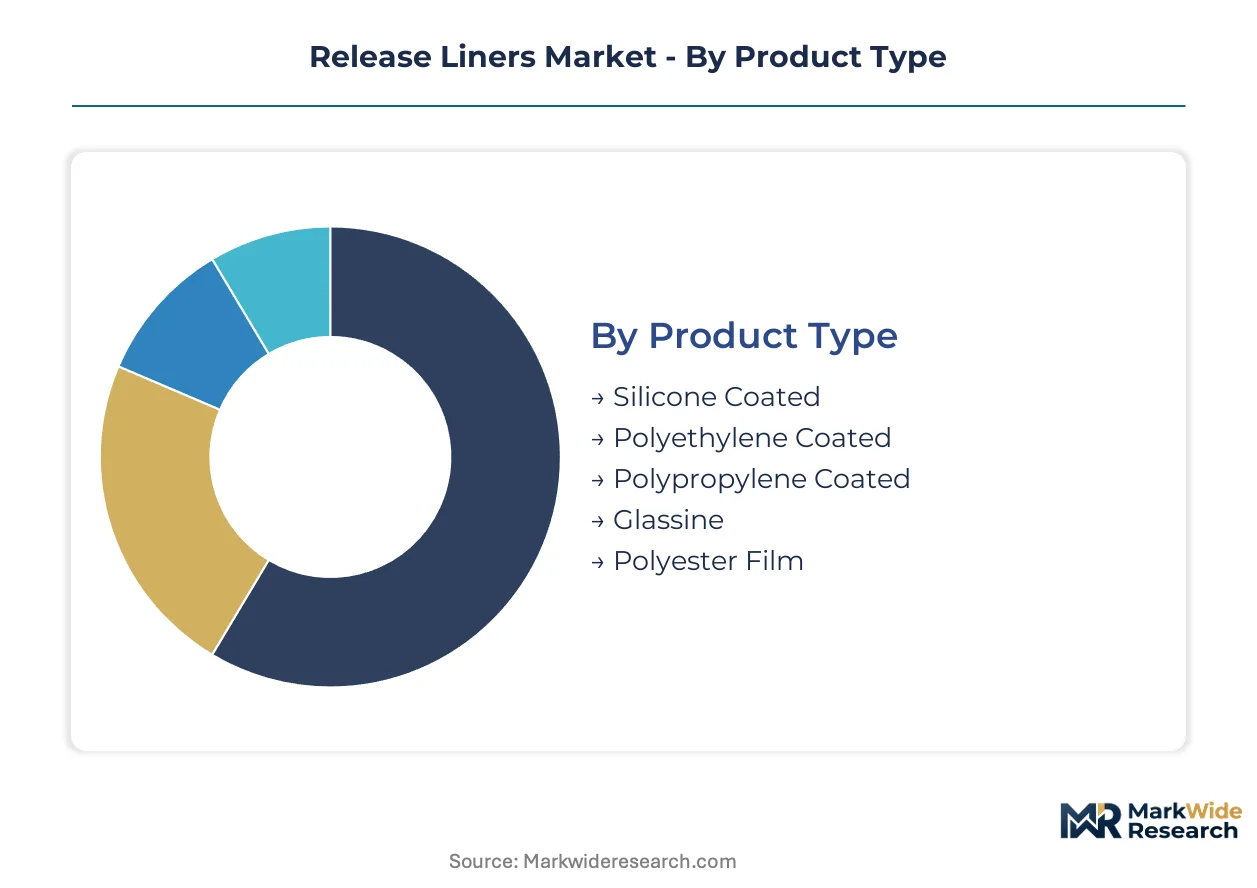
Release liner segmentation reflects divergent performance requirements across adhesive interfaces. Substrate selection determines release force precision, thermal stability, and regulatory compliance for end-use applications ranging from sterile medical devices to semiconductor assembly.
Product Type:
Customization intensity varies sharply across this category, from commodity paper substrates to engineered film constructions demanding sub-micron coating control.
- Silicone Coated:Paper or film substrates carrying polydimethylsiloxane formulations enable controlled release from acrylic and rubber-based adhesives. Demand concentrates in German and US labeling converters serving food packaging and logistics sectors where cost-efficiency and broad compatibility dominate procurement criteria.
- Polyester Film:Dimensionally stable polyethylene terephthalate constructions withstand thermal cycling in electronics lamination processes. South Korean display panel manufacturers in Gyeonggi-do clusters specify tight release force tolerances for just-in-time adhesive bonding lines where substrate consistency eliminates production stoppages.
- Polyethylene Coated:Moisture-resistant substrates serve construction tape applications requiring outdoor durability.
- Polypropylene Coated:Lightweight films target high-volume consumer goods labeling with moderate release requirements.
- Glassine:Smooth, dense paper grades provide economical release surfaces for general industrial adhesives.
Leading the category by volume: Silicone Coated. Growing fastest: Polyester Film.
Coating Material:
Margin structures across this category track regulatory compliance burden and chemistry sophistication, from commodity silicone to certified fluoropolymer systems.
- Silicone:Polydimethylsiloxane and modified silicone polymers dominate volume production through proven performance and formulation flexibility. REACH chemical restrictions and EPA emissions standards are pressuring European and US converters toward solvent-free curing technologies while maintaining release force specifications.
- Fluoropolymer:Perfluorinated chemistries deliver extreme-release performance for silicone gel adhesives and epoxy resin systems. Medical dressing manufacturers in Switzerland and Germany adopt these substrates for aggressively tacky interfaces where standard coatings exhibit excessive release force or surface contamination.
- Acrylic:Waterborne formulations serve environmentally regulated markets with moderate release requirements.
- Rubber:Natural and synthetic rubber coatings target specific adhesive compatibility niches in industrial tapes.
- UV Curable:Energy-curable silicone hybrids eliminate solvent recovery infrastructure while meeting FDA extraction test protocols for medical-grade substrates.
Highest volume position: Silicone. Steepest expansion trajectory: Fluoropolymer.
Application:
Application segmentation maps directly onto certification intensity, with medical and electronics segments demanding qualified supplier bases that commodity labeling cannot access.
- Pressure Sensitive Adhesives:The foundational application spanning tapes, labels, and graphics products requires substrates matching diverse adhesive chemistries. US and German converters specify release force ranges by end-use, from permanent labels to removable repositionable products.
- Medical Dressings:Wound care, transdermal patches, and diagnostic strips demand ISO 10993-certified substrates with documented extractables. EU MDR biocompatibility frameworks and FDA device regulations restrict unqualified materials, creating defensible margin pools for approved suppliers in France, Germany, and the United States.
- Labeling:Food, beverage, and logistics applications drive high-volume consumption of cost-optimized paper liners.
- Electronics Assembly:Flexible circuit lamination and display bonding require dimensional stability under thermal stress.
- Construction Tapes:Weather-resistant substrates serve building envelope and infrastructure applications.
Dominant by volume: Pressure Sensitive Adhesives. Climbing the fastest: Medical Dressings.
End User Industry:
Customer concentration patterns in this category separate high-specification medical and electronics buyers from price-sensitive consumer goods and construction purchasers.
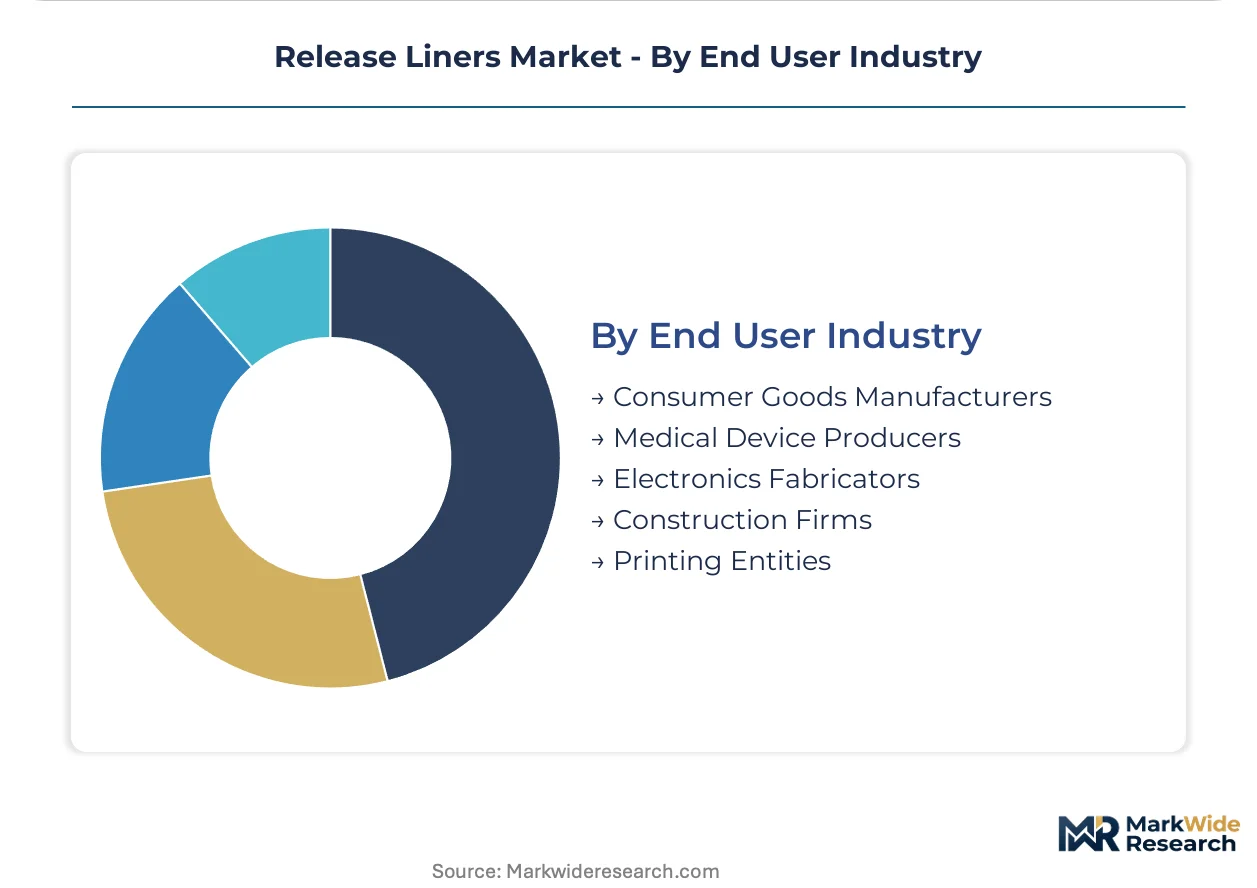
- Medical Device Producers:Sterilizable liner substrates for wound care, surgical drapes, and diagnostic components command premium positioning. FDA and EU MDR compliance requirements tighten substrate qualification protocols, compressing approval timelines while elevating certified supplier dependence.
- Electronics Fabricators:Semiconductor assemblers and display panel manufacturers in South Korea and Taiwan specify precision-coated polyester film liners. Thermal-stress dimensional stability requirements and just-in-time delivery schedules favor direct mill procurement over distributor intermediaries.
- Consumer Goods Manufacturers:High-volume labeling and packaging applications prioritize cost efficiency and supply security.
- Construction Firms:Weatherproofing and bonding tape users demand moisture-resistant substrate performance.
- Printing Entities:Commercial print and converting operations source release liners for adhesive-backed graphic products.
Largest volume segment: Consumer Goods Manufacturers. Gaining share fastest: Medical Device Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of precision-coated film substrates concentrates in East Asian manufacturing clusters, while consumption spreads across German medical device corridors and US industrial adhesive markets. This geographic split shapes qualification timelines and sourcing strategies for converters worldwide.
United States
Medical device producers in Minnesota and Massachusetts drive sterilizable liner substrate demand for wound care and diagnostic applications. FDA device regulations and EPA emissions standards tighten coating chemistry requirements, pushing converters toward UV-curable alternatives. The Twin Cities corridor hosts major adhesive laminators demanding batch-level consistency for transdermal patch manufacturing.
Germany
Wound care converters in Baden-Württemberg and North Rhine-Westphalia anchor EU medical-grade liner consumption. EU MDR biocompatibility frameworks and REACH chemical restrictions elevate certified substrate costs while creating margin pools for approved suppliers. The Stuttgart manufacturing cluster specializes in silicone-coated polyester films for automotive and electronics bonding applications.
South Korea
Display panel manufacturers in Gyeonggi-do and semiconductor assemblers in Suwon specify precision polyester film liners with sub-micron coating control. MFDS medical device regulations and national green chemistry initiatives accelerate waterborne coating adoption. The Pangyo tech corridor drives direct mill procurement patterns that bypass traditional distributor channels.
Japan
Electronics fabricators in Kansai and Chubu regions consume dimensionally stable film substrates for flexible circuit lamination. METI industrial standards and PMDA medical device frameworks enforce rigorous extractables documentation for patient-contact materials. The Nagoya manufacturing belt specializes in fluoropolymer-coated liners for extreme-release composite applications.
India
Pharmaceutical packaging converters in Maharashtra and Gujarat expand transdermal patch and diagnostic strip production. CDSCO medical device regulations are maturing substrate qualification protocols, creating first-mover opportunities for certified suppliers. The Mumbai-Pune industrial corridor attracts coating technology investments serving domestic and export markets.
Release Liners Market Key Industry Players
Top-tier vendors anchor premium medical-grade and electronics specifications, while mid-scale converters compete on coating flexibility and regional logistics. The vendor base stratifies across integrated polymer science capabilities, precision film manufacturing, and commodity paper coating operations. Three archetypes dominate: diversified materials conglomerates with captive silicone supply, specialized film coaters serving electronics just-in-time requirements, and regional paper converters leveraging cost-positioned substrates. Competitive moves center on coating chemistry licensing agreements and backward integration into polymer resin production.
Among diversified materials conglomerates, 3M Company and Dow Inc. exemplify integrated polymer science capabilities spanning substrate formulation to adhesive interface engineering. Avery Dennison Corporation occupies a position within the precision coating tier, representing controlled-release laminate expertise for pressure-sensitive applications. LINTEC Corporation anchors the Asian precision film segment, exemplifying dimensional stability specialization for electronics fabricators in South Korea and Japan. These named entities represent archetype positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Sappi Limited |
| LINTEC Corporation |
| Mondi Group |
| Loparex |
| Ahlstrom |
| UPM Raflatac |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between ISO 10993-qualified medical substrates and commodity paper liners manifests in both pricing power concentration and supply chain tiering. Premium fluoropolymer-coated films command substantial markups through restricted supplier bases, while commodity silicone-coated paper faces margin compression from oversupplied converting capacity.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency procurement premiums from contract-scheduled discounts. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and coating chemistry sophistication. Price differentiation hinges on FDA biocompatibility tier and volume scale commitments. Pricing pressure stems from REACH solvent restrictions forcing costly coating line conversions. Consumer goods labeling converters exhibit highest price sensitivity, while medical device producers accept premium positioning for qualified supply security.
Supply Chain Analysis
Single-source vulnerability sits with precision-coated polyester film production concentrated in South Korea and Japan. Raw material dependencies draw from silicone polymer feedstocks, PET resin, and fluoropolymer precursors. Supply chain risk centers on East Asian logistics chokepoints affecting just-in-time electronics fabrication schedules. Distribution runs through direct mill procurement displacing distributor intermediaries in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as regulatory qualification timelines and coating chemistry transitions force sub-scale converters into exit or acquisition. EU MDR biocompatibility mandates and EPA emissions standards are accelerating this consolidation pressure.
For Market Incumbents: Anchor defensive positioning through backward integration into silicone polymer production and captive fluoropolymer coating capacity. Expand certified substrate inventory in Germany and the United States to compress competitor qualification windows. Threat substitution from UV-curable coating specialists demands accelerated R&D in energy-curable silicone hybrids. Certification investment in ISO 10993 testing infrastructure is the critical lever for margin defense.
For New Entrants and Emerging Players: E-commerce-enabled technical substrate sourcing offers route-to-market bypass of entrenched distributor relationships. Target Indian pharmaceutical packaging corridors where CDSCO regulations are maturing and qualified supplier bases remain thin. Carbon fiber prepreg manufacturing for aerospace composites represents penetrable white-space with extreme-release fluoropolymer demand. Direct technical sales to electronics fabricators in Gyeonggi-do clusters provides go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale coaters possessing ISO 10993 certification infrastructure given EU MDR enforcement timeline compression. Long-term viability over the next decade favors suppliers with demonstrated patient-contact material approvals and waterborne coating process capabilities. Acquisition target archetype: regional paper converters with retrofit-capable assets and existing medical converter relationships. Signal to watch is FDA warning letter volume against unqualified substrate suppliers as proxy for enforcement intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| UV-Curable Coating Conversion | Eliminates solvent recovery infrastructure while satisfying EPA emissions standards and FDA extraction protocols. |
| Backward Integration into Silicone Resin | Captive polymer supply secures margin control against petrochemical feedstock volatility from crude derivatives. |
| ISO 10993 Certification Investment | Biocompatibility testing infrastructure creates defensible positioning for EU MDR and FDA patient-contact applications. |
| Direct Mill Procurement Expansion | Bypasses distributor intermediaries to capture electronics fabricator relationships in South Korean display clusters. |
| Fluoropolymer Coating Capacity Addition | Extreme-release chemistry serves medical dressing and carbon fiber prepreg manufacturing where silicone fails. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with coating mill technical directors, medical device procurement managers, and electronics fabrication supply chain leads combined with secondary validation from FDA 510(k) databases, EU MDR notified body submissions, and REACH registration dossiers. Bottom-up substrate consumption modeling triangulated against top-down adhesive market sizing.
Data-stream reconciliation across coating chemistry volumes, end-use application demand, and regional production capacity informed the analytical framework. Segmentation dimensions modeled include substrate material type, coating chemistry tier, application certification intensity, and end-user industry regulatory burden. CAGRs were derived from installed coating capacity expansion schedules and adhesive market growth elasticities. Forecast inputs incorporated MFDS medical device registration trends and green chemistry initiative adoption curves.
The model holds under stable regulatory enforcement intensity and continued electronics fabrication geographic concentration; deviation in tariff regimes or coating chemistry technology breakthroughs would shift trajectory. Forecasts reflect documented assumptions regarding qualification timeline compression and solvent-to-UV curing transition rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Cap Liner Films Market