
 High Performance Barrier Films Market | 2026-2036
High Performance Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Barrier Films Market Foresight
Modular multi-layer configurations is pivoting buyer choice away from single-material films toward stackable barrier systems that processors can customize by oxygen transmission rate and moisture vapor transmission rate requirements. Amcor plc leverages its global manufacturing footprint to supply these configurable platforms across food and healthcare accounts. DuPont anchors its position through specialty resin and coating technologies that enable thinner gauge constructions without sacrificing barrier performance.
High performance barrier films are engineered polymer structures, typically incorporating ethylene vinyl alcohol or polyamide layers, manufactured through coextrusion or lamination processes to achieve oxygen transmission rates below 0.1 cc/m²/day. Their primary purpose is to protect oxygen-sensitive and moisture-critical contents across extended distribution cycles. Polyester and polyamide product types dominate current volume owing to established supply chains and proven performance in retort and vacuum applications. Transparent films within the material dimension are gaining traction as brand owners eliminate metallization to satisfy optical scanning requirements for recycling streams.
The FDA governs indirect food contact substances through 21 CFR compliance pathways, while the EPA regulates per- and polyfluoroalkyl substance phasedowns that are eliminating legacy fluorinated barrier chemistries from US food packaging. REACH restrictions in Europe further constrain certain halogenated additives, redirecting formulation investment toward silicon oxide and aluminum oxide vapor-deposited alternatives. Stakeholders must track how evolving extended producer responsibility frameworks in multiple jurisdictions redefine acceptable end-of-life pathways for multi-layer constructions.
Market Dynamics
Mono-material compatibility requirements are forcing converters to dismantle multi-layer barrier architectures and rebuild them from single-polymer foundations without sacrificing oxygen and moisture protection. This structural pressure cascades through resin selection, coating chemistry, and equipment configuration decisions.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are compelling brand owners to specify transparent barrier films that optical sorters can detect, accelerating demand for silicon oxide-coated polyester alternatives to metallized structures.
- Food waste reduction mandates:Extended shelf life specifications from retail chains are driving processors toward ethylene vinyl alcohol copolymer layers with sub-0.1 cc/m²/day oxygen transmission rates for meat and dairy applications.
- Bavaria packaging cluster:Concentrated converter capacity around Munich and Nuremberg creates localized demand density that justifies dedicated high-barrier film production lines with rapid technical service response.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Supply dependency on Japanese and Korean polymer producers creates exposure to shipping disruptions and currency volatility for European converters.
- Per- and polyfluoroalkyl substance phaseout:EPA restrictions on fluorinated barrier chemistries are eliminating proven ultra-high barrier solutions before vapor-deposited oxide coatings achieve equivalent performance at commercial scale.
- Multi-layer incompatibility with mechanical recycling:Current sorting infrastructure cannot separate coextruded barrier films, forcing reliance on emerging chemical recycling pathways with limited capacity.
Strategic Opportunities
- Healthcare pharmaceutical blister packs:Moisture-sensitive drug formulations are creating specification pull for tropical-grade barrier films with aluminum oxide vapor deposition and child-resistant functionality.
- Digital printing convergence:Integration of inkjet decoration with barrier film production enables short-run customized packaging for regional food brands without separate lamination steps.
- Germany extended producer responsibility expansion:Upcoming modulation of packaging license fees based on recyclability scores creates financial incentive for mono-material barrier adoption.
Industry Challenges
- Vapor deposition technician scarcity:Operation of roll-to-roll plasma-enhanced chemical vapor deposition equipment requires specialized training that outpaces current vocational program output in key manufacturing regions.
- Migration testing protocol complexity:Demonstrating compliance with EFSA and FDA indirect food contact requirements for novel barrier coatings extends product qualification timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Barrier Films Market |
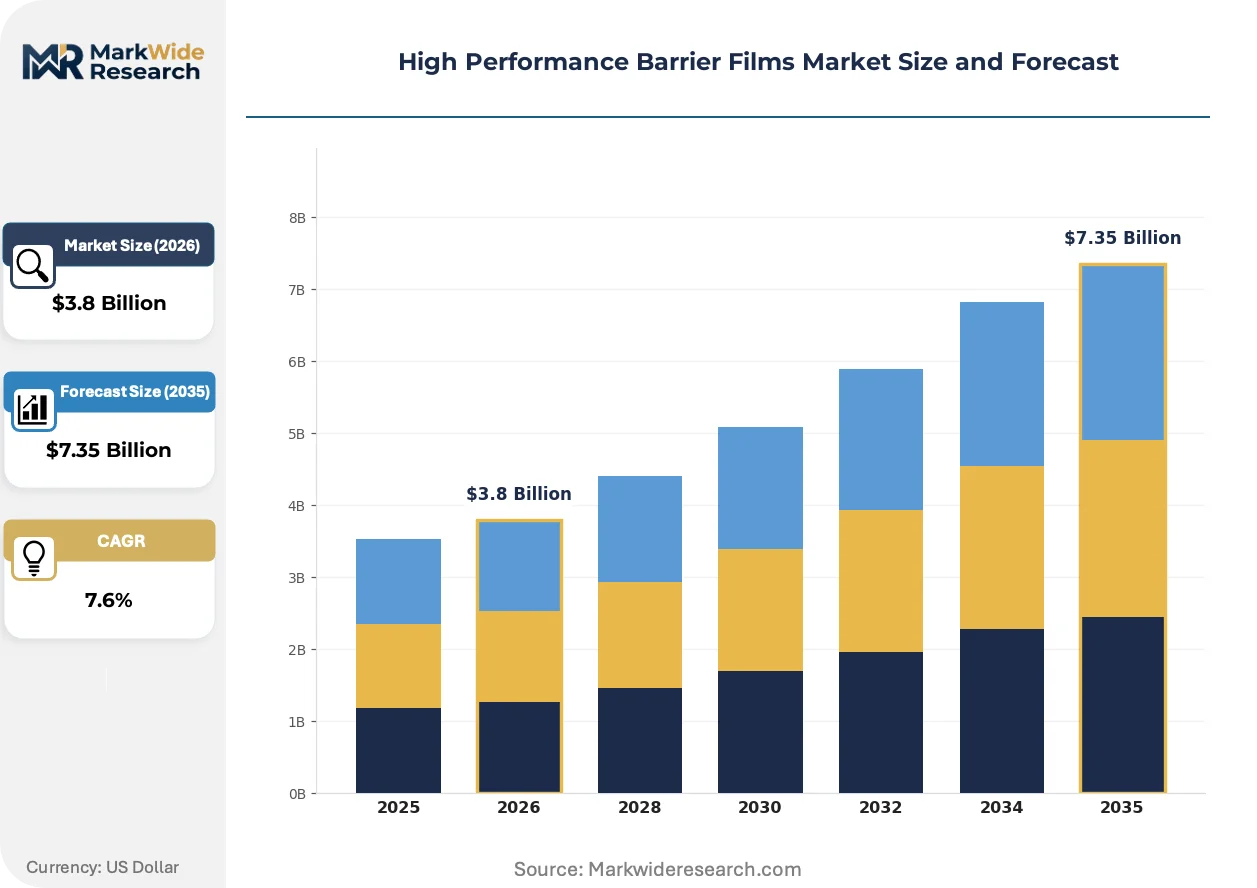
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polyamide, Polyethylene, Coated Films Application: Food Packaging, Electronics, Medical Devices, Industrial Material: Metallized Films, Transparent Films, Biodegradable Films, Barrier Coatings End User: Food Industry, Healthcare, Consumer Electronics, Automotive |
| Companies Covered | Amcor plc, Berry Global Inc., Sealed Air Corporation, Mondi Group, Huhtamaki, 3M, DuPont, Jindal Poly Films, Cosmo Films Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Barrier Films Market Shifts & Advancements
Digital process control systems are penetrating coextrusion lines and metallization chambers, enabling real-time thickness and barrier property adjustment that reduces material over-engineering and scrap generation.
Plasma-enhanced chemical vapor deposition of silicon oxide is automating quality assurance on high-speed barrier film production lines. Food packaging converters in Germany and France are retrofitting existing metallizers with plasma sources at accelerating pace. This technology is automating the elimination of manual inspection stations while compressing defect response times from hours to seconds.
REACH restrictions on persistent organic pollutants are eliminating halogenated flame retardants and certain plasticizers from barrier film formulations. Compounders are redirecting R&D investment toward bio-based polyamide intermediates and non-halogenated barrier additives. Flexible packaging converters in the Netherlands and Belgium are experiencing the most acute formulation disruption as they serve multinational brand owners with pan-European compliance requirements.
Consolidated procurement by pan-European retail alliances is compressing supplier qualification cycles and demanding standardized sustainability documentation across film categories. Mid-sized converters in North Rhine-Westphalia are losing direct relationships with brand technical teams as purchasing decisions centralize to Brussels and London headquarters. This concentration is most visible in the fresh produce segment, where three buying cooperatives now control barrier film specifications for over sixty percent of German supermarket shelf space.
High Performance Barrier Films Market Segmentation
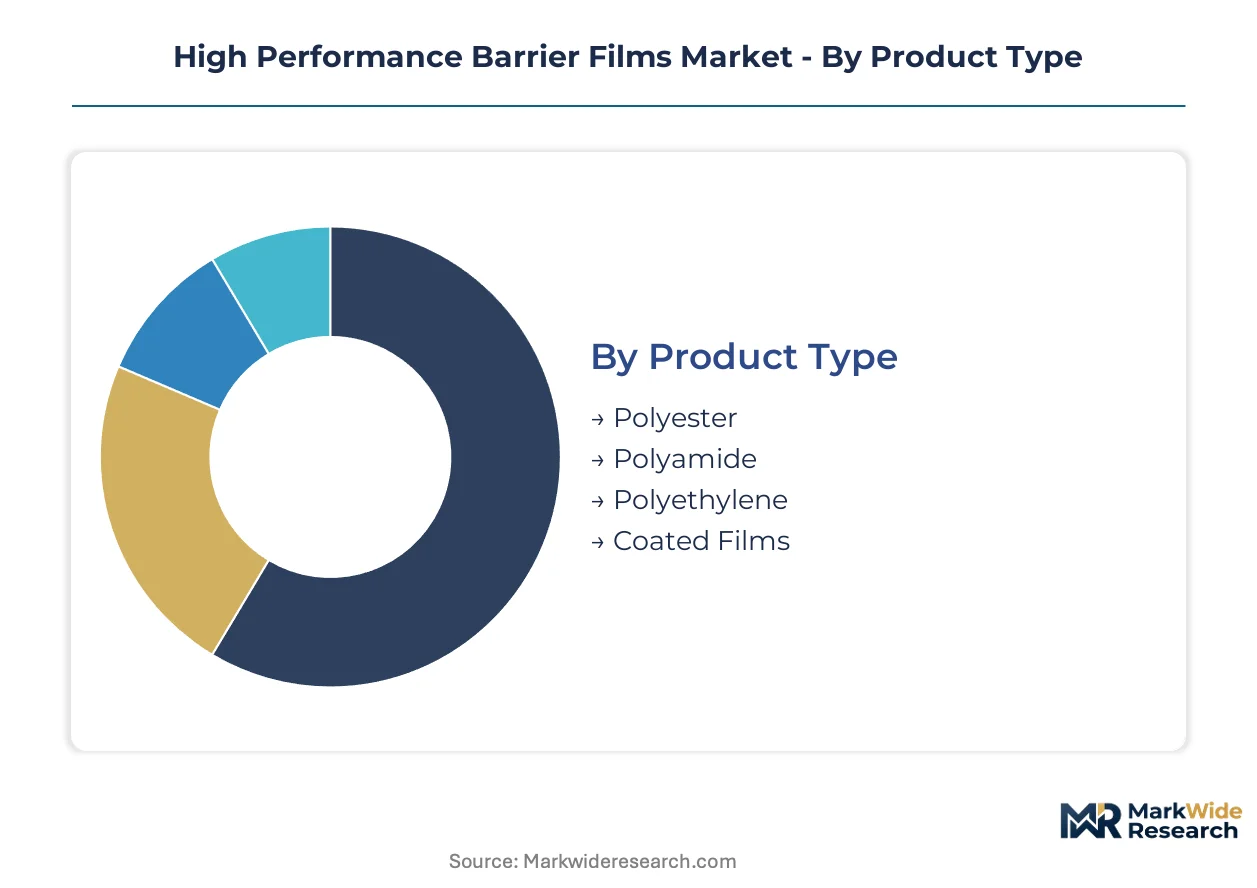
Barrier film specifications diverge sharply across end-use requirements, with oxygen transmission rates and optical clarity demands forcing converters into specialized material stacks. Segmentation in this market reflects tension between proven multi-layer architectures and emerging mono-material alternatives.
Product Type:
Volume concentrates in established polymer platforms, while premium tiers shift toward coated and functionalized surfaces.
- Polyester:Biaxially oriented polyethylene terephthalate structures deliver thermal stability and optical clarity for retort pouches and pharmaceutical blister packs. Bavarian food processors specify PET base layers for high-temperature sterilization cycles in ready-meal applications.
- Polyamide:Aliphatic polyamide 6 and 6,6 grades provide puncture resistance and thermoformability for vacuum skin packaging of fresh meat. North Rhine-Westphalia converter clusters source PA domestically from integrated polymer producers to minimize resin freight exposure.
- Polyethylene:Linear low-density formulations serve cost-sensitive bulk packaging with moderate barrier requirements.
- Coated Films:Silicon oxide and aluminum oxide vapor-deposited layers enable transparent high-barrier performance for recyclable streams.
Today's leader: Polyester. Tomorrow's challenger: Coated Films.
Application:
End-use pull determines barrier specification intensity, with oxygen-sensitive categories commanding premium material stacks.
- Food Packaging:Modified atmosphere packaging for red meat and cheese drives ethylene vinyl alcohol copolymer specifications below 0.1 cc/m²/day oxygen transmission. German retail chains mandate extended shelf life to reduce waste compliance with EU targets.
- Electronics:Flexible circuit substrates and display encapsulation require moisture vapor transmission rates below 0.1 g/m²/day.
- Medical Devices:Sterile barrier systems for implantable devices combine Tyvek lids with foil laminates.
- Industrial:Chemical drum liners and agricultural fumigation films utilize medium-barrier polyethylene constructions.
Food Packaging absorbs the majority of converter capacity, though Electronics specifications are climbing fastest as flexible display manufacturing scales.
Material:
Optical detectability requirements are displacing metallized legacy structures in favor of transparent alternatives.
- Metallized Films:Vacuum-deposited aluminum layers achieve ultra-low oxygen and moisture transmission for coffee and snack packaging. REACH compliance pressures and recycling incompatibility are constraining specification growth across EU markets.
- Transparent Films:Silicon oxide-coated polyester satisfies optical sorting requirements for mechanical recycling streams. French and Dutch converters retrofit metallization chambers with plasma-enhanced chemical vapor deposition sources to supply transparent alternatives.
- Biodegradable Films:Polylactic acid and polyhydroxyalkanoate base layers with barrier coatings serve compostable packaging mandates.
- Barrier Coatings:Aqueous and solvent-based coatings applied via gravure or flexo enable mono-material recyclability.
Material selection now hinges on end-of-life pathway certification as extended producer responsibility fees modulate based on recyclability scores.
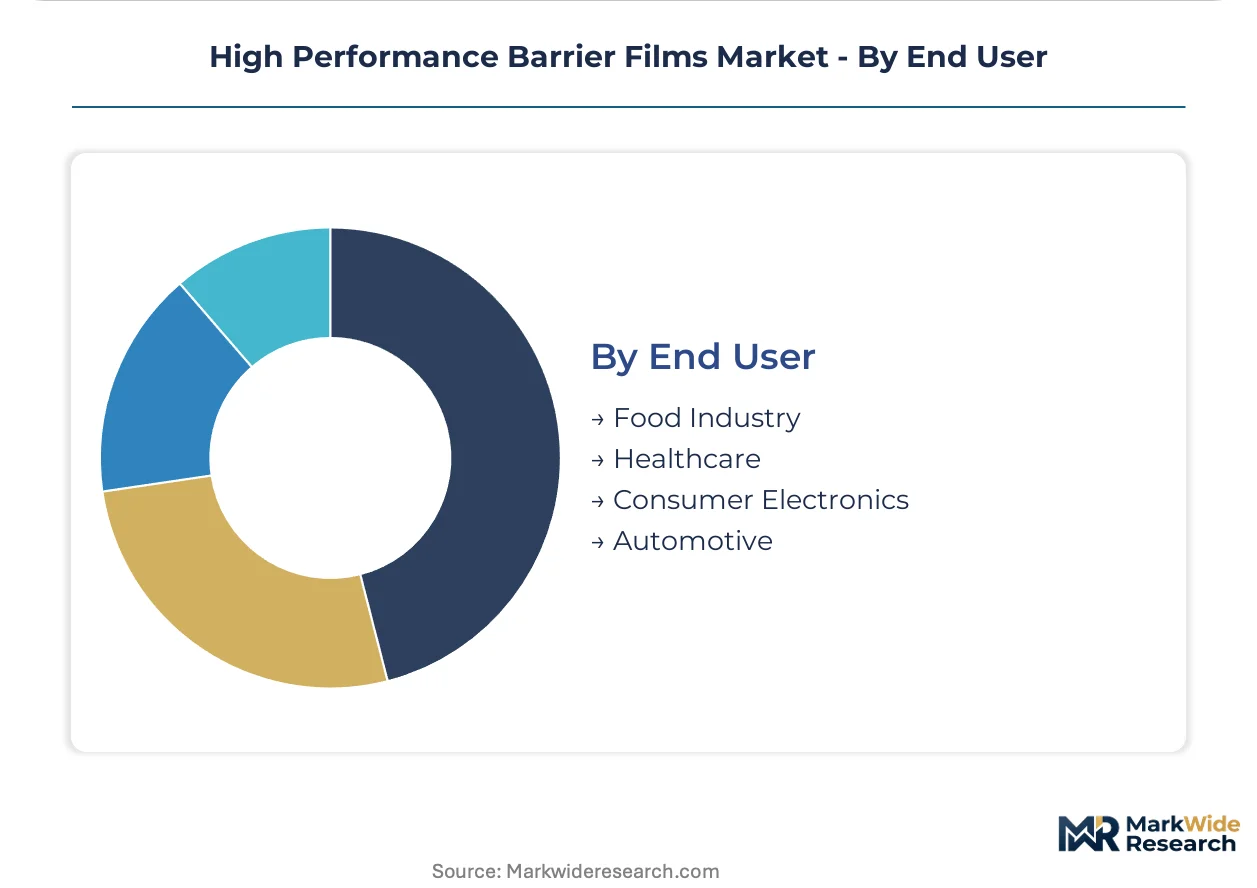
End User:
Procurement sophistication varies dramatically, with healthcare and automotive buyers imposing qualification protocols that exclude commodity suppliers.
- Food Industry:Pan-European retail alliances centralize barrier film specifications to Brussels procurement teams, compressing supplier relationships for mid-sized German converters.
- Healthcare:Pharmaceutical blister packs demand tropical-grade moisture barriers with aluminum oxide vapor deposition and child-resistant functionality. FDA 21 CFR compliance pathways extend qualification timelines.
- Consumer Electronics:Flexible display manufacturers specify ultra-high barrier films for organic light-emitting diode encapsulation.
- Automotive:Battery pouch films for electric vehicle cell encapsulation require biaxial orientation and ionic purity control.
Healthcare qualification barriers protect incumbent suppliers, while Automotive volume is scaling fastest as cell manufacturing localizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier film technology originated in post-war Germany and Japan, where coextrusion processes first achieved industrial scale for food preservation. These engineering foundations spread through licensing agreements to North American converters during the 1970s, establishing the geographic pattern of expertise concentration visible today.
Germany
Modified atmosphere packaging specifications from Aldi and Lidl central procurement teams drive ethylene vinyl alcohol copolymer demand for meat and cheese applications. The Verpackungsgesetz packaging law mandates minimum recycled content thresholds that accelerate mono-material barrier adoption. Converter clusters around Munich and Nuremberg maintain dedicated high-barrier production lines with rapid technical service response to Bavarian food processors.
United States
Pharmaceutical blister pack demand from tropical-grade moisture barriers anchors specialty film consumption on the East Coast. FDA 21 CFR compliance pathways for indirect food contact substances extend qualification timelines for novel barrier coatings. Flexible packaging converters in the Chicago and Milwaukee industrial corridor source ethylene vinyl alcohol resins through Great Lakes distribution hubs serving Midwest meat processors.
Japan
Organic light-emitting diode encapsulation requirements from display manufacturers in the Kansai region pull ultra-high barrier specifications below 0.1 g/m²/day moisture vapor transmission. METI carbon neutrality roadmaps pressure converters toward vapor-deposited oxide coatings as alternatives to metallized structures. Osaka-based film producers coordinate with polymer suppliers in the Chubu region to secure specialized resin grades for electronics applications.
France
Retail chain sustainability mandates from Carrefour and Intermarché specify transparent barrier films compatible with optical sorting infrastructure. REACH restrictions on persistent organic pollutants eliminate halogenated additives from formulations serving pan-European brand owners. Converters in the Lyon industrial basin retrofit metallization chambers with plasma-enhanced chemical vapor deposition sources to supply silicon oxide-coated alternatives.
India
Pharmaceutical export growth to regulated markets drives tropical-grade barrier demand from Mumbai and Ahmedabad formulation facilities. BIS certification requirements for food contact materials create compliance barriers for imported film specifications. Jindal Poly Films and Cosmo Films anchor domestic supply from integrated manufacturing complexes in Maharashtra and Gujarat serving South Asian packaging converters.
High Performance Barrier Films Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating technology sophistication, with vapor-deposited oxide specialists commanding pricing power over conventional metallized film producers. The vendor base stratifies into three tiers: integrated multinationals with captive resin supply, regional converters with coextrusion expertise, and emerging specialists in digital-enabled barrier customization. Consolidation pressure concentrates among mid-scale European converters as pan-European retail procurement centralizes. Dominant competitive moves include retrofitting existing metallization assets with plasma deposition capability and securing long-term ethylene vinyl alcohol resin offtake agreements with Korean and Japanese polymer producers.
Within the integrated multinational tier, Amcor plc and Berry Global Inc. represent scale-driven archetypes with global manufacturing footprints spanning food and healthcare accounts. DuPont occupies a position as a specialty resin and coating technology anchor, enabling thinner gauge constructions without sacrificing barrier performance. These three exemplify divergent strategic postures: Amcor plc emphasizes configurable platform supply across diversified end-uses, Berry Global Inc. concentrates on healthcare and food packaging integration, and DuPont maintains upstream control over material science rather than downstream converter operations.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Sealed Air Corporation |
| Mondi Group |
| Huhtamaki |
| 3M |
| DuPont |
| Jindal Poly Films |
| Cosmo Films Ltd. |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation recyclability mandates gate qualified supply to converters demonstrating transparent barrier film compatibility with optical sorting infrastructure, while simultaneously commanding premium-tier pricing for silicon oxide-coated alternatives to legacy metallized structures. Mono-material certification requirements compress supplier pools and elevate pricing power for qualified producers serving German retail procurement teams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates vapor-deposited oxide specialists from conventional metallized film producers and commodity polyethylene converters. Price differentiation centers on certification grade for EU recyclability compliance and volume scale in ethylene vinyl alcohol resin offtake agreements. Pricing pressure stems from centralized procurement by pan-European retail alliances compressing margins for mid-scale converters. Food industry buyers exhibit highest price sensitivity due to specification standardization, while healthcare pharmaceutical accounts tolerate premium pricing for tropical-grade moisture barriers.
Supply Chain Analysis
Freight cost exposure from Asian ethylene vinyl alcohol resin producers to European converters elevates landed cost volatility for specialty barrier formulations. Supply concentrates in Germany, Japan, and South Korea, with raw material dependencies spanning ethylene vinyl alcohol copolymers, biaxially oriented polyethylene terephthalate base films, and vapor-deposition equipment components. Single-source vulnerability to Korean and Japanese polymer producers creates disruption risk from shipping route constraints. Distribution runs through converter clusters in Bavaria and North Rhine-Westphalia serving proximate food processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between German extended producer responsibility fee modulation and US FDA qualification timeline premiums, with cost differentials favoring early mono-material adoption in EU markets versus legacy multi-layer retention in North America.
For Market Incumbents: Anticipate resin supply disruption by securing long-term ethylene vinyl alcohol offtake agreements with Korean and Japanese polymer producers before competitor lock-in. Retrofit existing metallization assets with plasma-enhanced chemical vapor deposition capability to defend position against transparent film specialists. Prioritize certification investment for EU recyclability scoring to capture extended producer responsibility fee advantages. For New Entrants and Emerging Players: Regional food brands seeking short-run customized packaging represent an underserved buyer archetype requiring digital printing convergence with barrier film production. White-space targets include pharmaceutical blister pack converters lacking tropical-grade moisture barrier capability and automotive battery pouch film specifications scaling with electric vehicle cell manufacturing localization. Pursue equipment partnerships with plasma deposition technology licensors as primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European converters losing direct brand relationships to centralized retail procurement, creating distressed acquisition opportunities with turnaround potential. Long-term viability favors specialists controlling vapor-deposited oxide coating technology or captive ethylene vinyl alcohol resin supply. Watch for inflection signals in chemical recycling capacity buildout resolving multi-layer film end-of-life constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Deposition Retrofit | Enables transparent barrier production for EU optical sorting compliance at German converter facilities. |
| Long-term Resin Offtake Agreement | Secures ethylene vinyl alcohol supply from Korean producers against currency and shipping volatility. |
| Digital Printing Integration | Captures regional food brand demand for short-run customized packaging without separate lamination. |
| Healthcare Certification Pathway | Extends qualification timelines for FDA 21 CFR compliance but protects incumbent supplier margins. |
| Mono-material Platform Development | Aligns with Verpackungsgesetz recycled content thresholds and upcoming fee modulation structures. |
Research Methodology
Coverage spans Germany, United States, Japan, France, and India, with primary inputs from each market combining converter plant managers, food industry procurement leads, pharmaceutical packaging engineers, and resin supplier technical directors. Secondary validation draws from FDA 21 CFR filings, ECHA REACH restriction updates, EU Packaging and Packaging Waste Regulation documentation, and customs trade data for ethylene vinyl alcohol resin flows. Bottom-up volume modeling triangulates against top-down value estimates from identified industry participants.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window, with segmentation modeling spanning product type, application intensity, material detectability, and end-user procurement sophistication. CAGRs derive from fitted growth curves incorporating ethylene vinyl alcohol resin supply constraints, plasma deposition equipment installation rates, and regulatory phase-in schedules for extended producer responsibility frameworks. Forecast inputs include Bayerische Landesamt für Umwelt packaging license fee projections and METI carbon neutrality roadmap implementation pacing.
Underlying measurement precision varies by segment; transparent film and coated film categories carry tighter precision than emerging biodegradable alternatives given established production tracking. Forecasts reflect assumptions about chemical recycling capacity scaling and fluorinated chemistry phaseout pacing that could revise trajectory if deployment lags or accelerates. Stakeholders should weight assumptions against their own operating context and resin supply security.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Sealant Web Films Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Insulation Film Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Meat Packaging Films Market