
 Meat Packaging Films Market | 2026-2036
Meat Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Packaging Films Market Foresight
Aftermarket technical service revenue for packaging line optimization is reshaping how film suppliers capture value beyond commodity resin sales. Amcor plc leverages its global technical service network to embed film specifications directly into processor equipment protocols. Sealed Air Corporation sustains premium positioning through controlled atmosphere system integration with its shrink bag and rollstock portfolios. Mondi Group anchors European supply security through backward integration into kraft paper and recycled resin streams.
Meat packaging films are multilayer coextruded or laminated structures, typically 30-50 microns thick, combining polyethylene sealant layers with polyamide or ethylene vinyl alcohol oxygen barriers to extend chilled meat shelf life from days to weeks. Polyethylene dominates film type volumes due to cost efficiency in form-fill-seal overwrap applications, while polypropylene is gaining ground in high-clarity retail display trays where optical properties command price premiums. The barrier properties segment concentrates margin pools in oxygen barrier and antimicrobial coatings, where EVOH and active additive formulations differentiate suppliers from commodity resin converters.
The European Commission's Packaging and Packaging Waste Regulation and the U.S. FDA's food contact substance notification requirements are tightening compositional transparency and recyclability standards for multi-layer meat films, forcing reformulation toward mono-material or chemically recyclable structures. BIS standards in India and China's GB standards for food contact plastics are expanding testing protocols for heavy metal migration and overall migration limits into meat matrices. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory from non-compliant multi-layer constructions.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing meat film suppliers to dismantle multi-layer barrier structures and reconstruct them as mono-material or chemically recyclable alternatives, compressing formulation margins while demanding fresh R&D investment cycles.
Growth Catalysts
- Modified atmosphere packaging adoption:Fresh and processed meat retail chains are embedding high-barrier films into automated packaging lines to extend chilled shelf life from days to weeks, concentrating demand in centralized processing hubs.
- REACH compliance innovation:ECHA substance restrictions on phthalates and heavy metal stabilizers are accelerating migration toward bio-based sealant layers and mineral oil-free inks across European converter operations.
- Ethylene vinyl alcohol barrier advancement:EVOH coextrusion with polyethylene sealants is displacing conventional nylon barriers in vacuum skin packaging for premium cuts, capturing margin pools in oxygen-sensitive applications.
Market Restraints
- Polyamide resin supply concentration:Caprolactam feedstock and polyamide 6 production clusters in Germany and China expose film converters to input cost volatility and force majeure disruptions in barrier layer supply.
- Multi-layer recyclability technical limitation:Current mechanical recycling infrastructure cannot separate EVOH, PA, and PE layers in post-industrial and post-consumer waste streams, stranding circular economy commitments.
- EU Green Deal carbon border friction:CBAM phase-in on imported plastics is elevating landed costs for Asian film substrates and pressuring margin structures on commodity overwrap grades.
Strategic Opportunities
- India cold chain underpenetration:FSSAI enforcement of mandatory cold storage for packaged meat is creating virgin demand for high-barrier films in poultry and mutton retail modernization across tier-2 cities.
- Chemical recycling infrastructure convergence:Pyrolysis and depolymerization partnerships with petrochemical majors are enabling closed-loop feedstock recovery for multi-layer film waste streams currently landfilled or incinerated.
- Active antimicrobial coating emergence:Nisin and chitosan additive formulations are opening premium pricing tiers in ready-to-cook marinated meat segments where pathogen control extends shelf life beyond passive barrier functions.
Industry Challenges
- Mono-material revalidation timelines:FDA and EFSA food contact substance notification cycles for reformulated sealant layers extend 18-24 months, delaying revenue recognition on sustainable film launches.
- Barrier-performance trade-off execution:Replacing EVOH with polyethylene-based oxygen scavengers demands precision in coextrusion die design and line speed calibration that exceeds legacy technician skill bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Packaging Films Market |
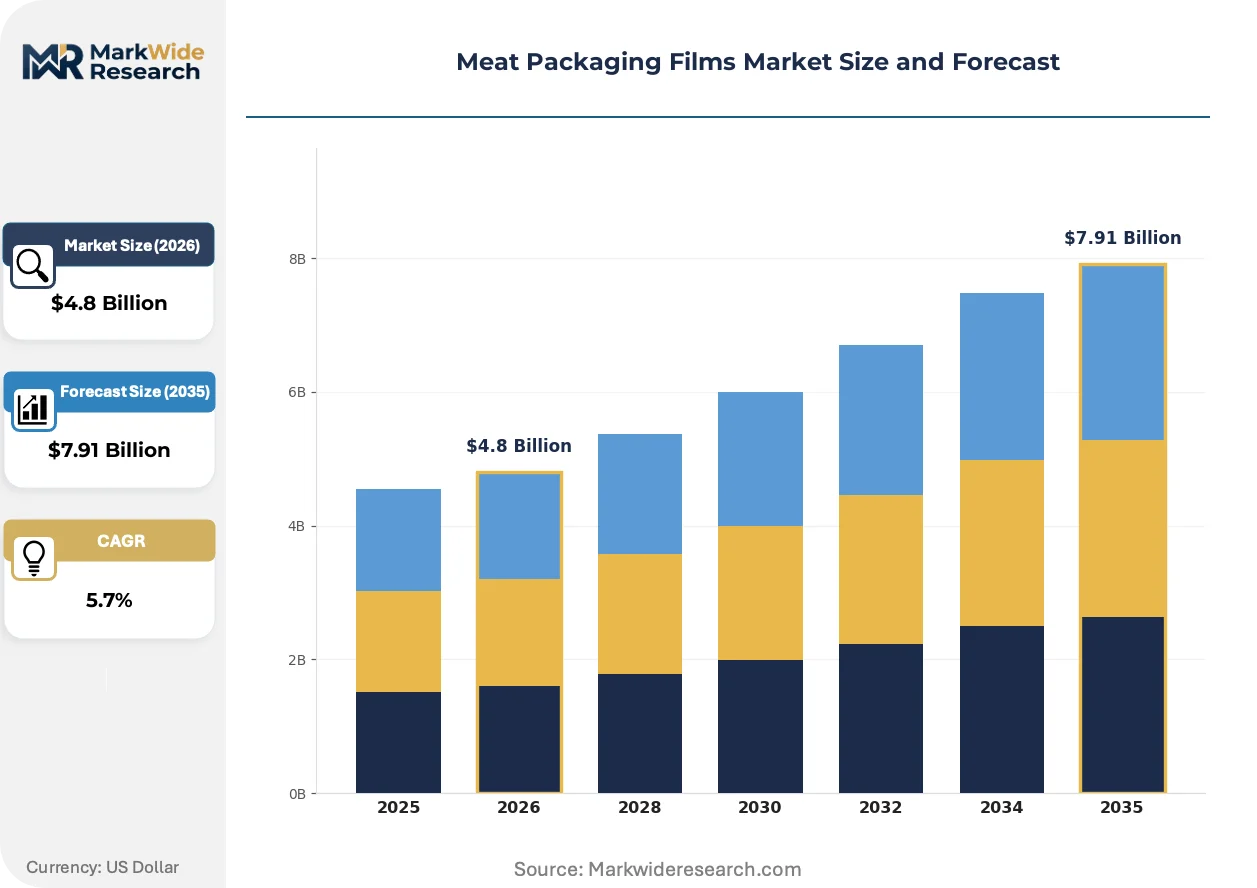
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Polyethylene, Polypropylene, PVDC, Nylon End User Segment: Retail Chains, Meat Processors, Food Service, Wholesalers Thickness: Below 30 Microns, 30-50 Microns, Above 50 Microns, Customized Thickness Barrier Properties: Oxygen Barrier, Moisture Barrier, UV Resistance, Antimicrobial Properties |
| Companies Covered | Amcor plc, Berry Global Inc., Sealed Air Corporation, Coveris Holdings SA, Winpak Ltd., RKW Group, Mondi Group, Sonoco Products Company, Charter Next Generation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Packaging Films Market Shifts & Advancements
Film suppliers are racing to embed digital traceability and intelligent barrier functions into commodity packaging substrates, transforming passive containment into active supply chain infrastructure.
Mono-material polyethylene barrier films is hybridizing with plasma-deposited silicon oxide coatings to replicate EVOH oxygen transmission rates without multi-layer lamination complexity. German meat processors are piloting these structures in high-volume form-fill-seal lines, compressing the technical advantage window for conventional barrier film specialists who rely on incompatible polymer combinations.
REACH authorization requirements for intentional microplastics are compelling reformulation of anti-fog and slip additives in meat contact films. The industrial consequence is a sourcing scramble for bio-based alternatives that maintain optical clarity and coefficient of friction specifications. High-clarity retail display tray segments in France and the Netherlands are most affected, with converters accelerating validation of plant-derived glycerol ester replacements.
Processor procurement patterns are compressing supplier rosters from multi-source commodity bidding to single-source technical partnerships with embedded line optimization services. This consolidation displaces spot-market resin trading in favor of contracted film specifications tied to equipment protocols. The shift is most visible in German centralized meat processing and export logistics hubs, where packaging line uptime guarantees now outweigh unit cost minimization in vendor selection criteria.
Meat Packaging Films Market Segmentation
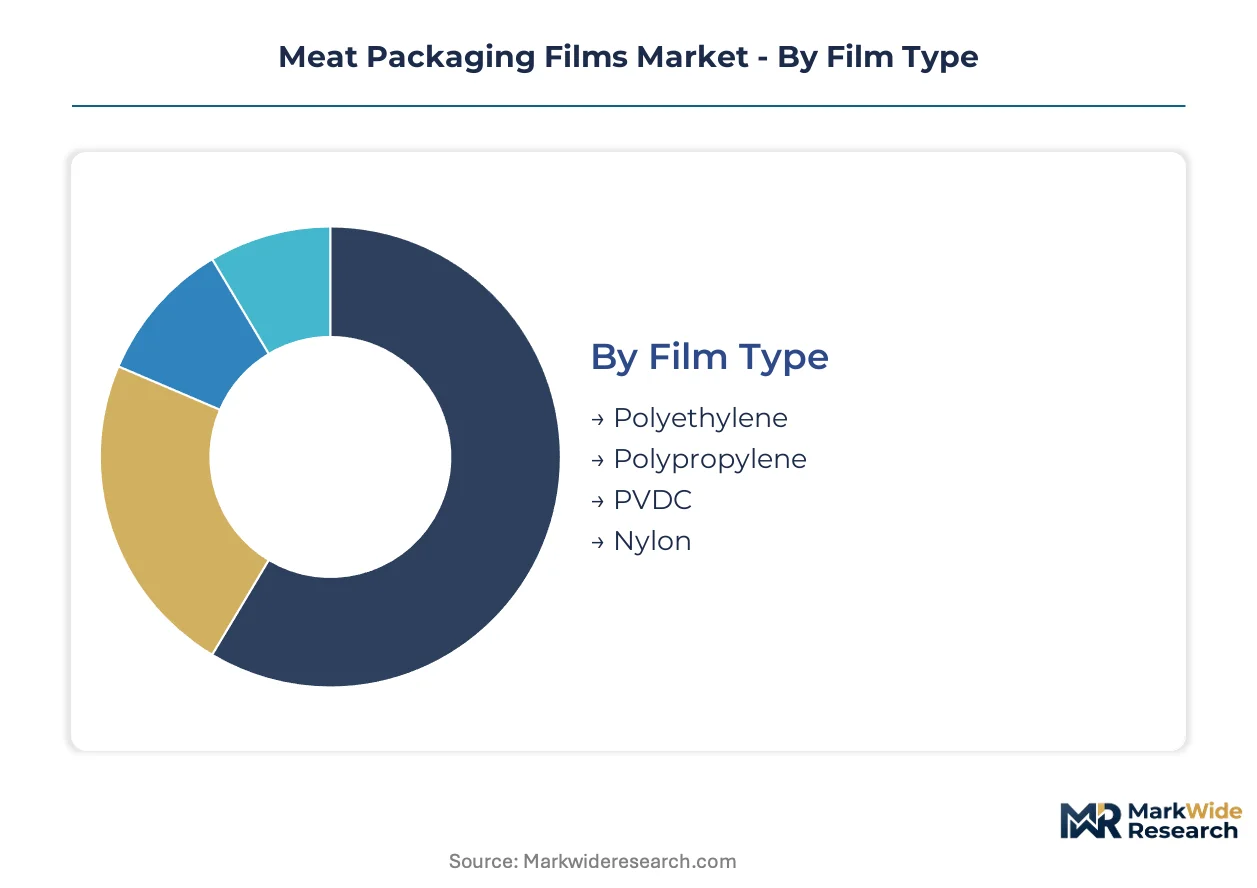
Meat packaging films segment across material chemistry, supply chain position, and functional performance. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier priorities and processor procurement criteria.
Film Type:
Mature commodity resins dominate volume throughput while emerging barrier polymers capture premium positioning in oxygen-sensitive applications.
- Polyethylene:Linear low-density formulations serve as the primary sealant layer in multilayer coextrusions, typically 30-50 microns thick. Form-fill-seal overwrap applications in German retail chains concentrate demand for cost-efficient PE structures, though recyclability mandates are pressuring converters toward mono-material constructions.
- Polypropylene:Cast and oriented PP films deliver high-clarity optical properties for retail display trays where visual meat presentation commands price premiums. French and Dutch supermarkets specify biaxially oriented PP for fresh cut visibility, with REACH microplastic restrictions now forcing additive reformulation.
- PVDC:Polyvinylidene chloride copolymers provide exceptional oxygen and moisture barrier in shrink bag applications for premium cuts.
- Nylon:Polyamide 6 and 6/6 layers deliver puncture resistance and thermoformability in vacuum skin packaging structures.
Polyethylene handles the majority of throughput; Polypropylene is climbing the fastest on share as clarity specifications tighten in European retail.
End User Segment:
Customer type determines specification complexity, with centralized processors demanding embedded technical services while fragmented food service trades on spot resin pricing.
- Retail Chains:Discounters and premium supermarkets mandate standardized film specifications across automated packaging lines, with shelf-life extension driving high-barrier EVOH adoption. German retail concentration creates volume consolidation that favors contracted supplier relationships over commodity bidding.
- Meat Processors:Centralized slaughter and cutting operations in export logistics hubs require 30-50 micron multilayer structures with guaranteed line uptime. Technical service integration now outweighs unit cost in vendor selection at these facilities.
- Food Service:Restaurants, catering, and institutional buyers prioritize cost minimization in portion-control overwrap applications with shorter shelf-life requirements.
- Wholesalers:Cash-and-carry and distribution intermediaries specification flexibility varies by customer mix between retail and food service endpoints.
Meat Processors anchor volume commitment through technical partnerships; Retail Chains are expanding specifications fastest as private-label meat portfolios multiply.
Thickness:
Thickness selection maps directly to barrier duty and equipment compatibility, with standard gauges capturing efficiency gains while custom calipers serve niche performance requirements.
- Below 30 Microns:Ultra-thin structures serve lightweight overwrap for immediate-consumption portions where mechanical protection requirements are minimal.
- 30-50 Microns:Standard coextruded and laminated constructions balance oxygen barrier, puncture resistance, and thermoformability for chilled meat distribution. This gauge range dominates European modified atmosphere packaging lines.
- Above 50 Microns:Heavy-duty shrink bags and deep-draw thermoforming films accommodate bone-in cuts and extended distribution cycles.
- Customized Thickness:Processor-specific calipers tailored to proprietary equipment die designs and line speed parameters.
30-50 Microns carries the volume base; Customized Thickness is gaining traction as line optimization services embed film specifications directly into equipment protocols.
Barrier Properties:
Functional differentiation separates commodity resin converters from specialty suppliers, with passive barriers commoditizing while active and intelligent functions capture expanding margin pools.
- Oxygen Barrier:EVOH coextrusion and metallized films extend chilled beef and pork shelf life from days to weeks. ECHA substance restrictions on conventional additives are accelerating validation of bio-based sealant layer compatibility with high-barrier structures.
- Moisture Barrier:Polyethylene sealant layers and polyolefin coatings prevent weight loss and surface drying in frozen and refrigerated distribution. Poultry processors in India specify elevated moisture retention as cold chain infrastructure expands.
- UV Resistance:Light-stabilized formulations protect packaged meat from photo-oxidation and discoloration in retail display cases with fluorescent or LED lighting.
- Antimicrobial Properties:Nisin and chitosan active additive formulations deliver pathogen control beyond passive barrier functions in ready-to-cook marinated segments.
Oxygen Barrier commands the specification priority in premium applications; Antimicrobial Properties is expanding most quickly as safety requirements extend shelf-life targets in prepared meat categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German retail chains absorb premium pricing for high-barrier technical films, while Indian poultry processors prioritize cost minimization in basic overwrap applications.
Germany
Centralized meat processing and export logistics concentrate demand for 30-50 micron multilayer structures with guaranteed line uptime. The EU Packaging and Packaging Waste Regulation is forcing rapid reformulation toward mono-material alternatives. Bavarian slaughter and cutting operations anchor European high-barrier film consumption.
United States
Modified atmosphere packaging adoption in retail chains drives EVOH coextrusion demand for chilled beef and pork shelf-life extension. FDA food contact substance notification requirements extend 18-24 months for reformulated sealant layers. Midwestern beef processing corridors concentrate technical service partnerships with film suppliers.
China
GB standards for food contact plastics are expanding testing protocols for heavy metal migration into meat matrices. Domestic cold chain expansion in tier-2 cities creates virgin demand for barrier films in poultry retail modernization. Yangtze River Delta processing hubs concentrate import substitution efforts for high-barrier substrates.
India
FSSAI enforcement of mandatory cold storage for packaged meat is creating demand for high-barrier films in poultry and mutton retail modernization. BIS standards are expanding testing protocols for overall migration limits. Tier-2 city cold chain underpenetration offers expansion corridors for technical film suppliers.
France
High-clarity retail display tray specifications command price premiums in supermarket fresh cut visibility applications. REACH authorization requirements for intentional microplastics are compelling anti-fog additive reformulation. Parisian retail concentration drives standardization of biaxially oriented PP structures across automated packaging lines.
Meat Packaging Films Market Competitive Landscape
Integrated multinational suppliers and regional specialty converters split the market between technical service bundling and cost-focused commodity resin sales. Concentration is moderate, with top-tier players capturing premium positioning through equipment protocol integration while mid-scale converters compete on spot pricing. Two strategic archetypes dominate: global packaging conglomerates with embedded line optimization services, and European film specialists with backward integration into resin streams. Competitive moves center on chemical recycling infrastructure partnerships and mono-material R&D investment cycles.
Among global packaging conglomerates, Amcor plc, Sealed Air Corporation, and Mondi Group exemplify divergent strategic positioning. Amcor plc represents the technical service archetype through global network deployment. Sealed Air Corporation occupies premium positioning via system integration approaches. Mondi Group anchors European supply security through captive resin and paper substrate control. These three players illustrate how scale, regional integration, and service bundling create distinct competitive vectors in barrier film supply.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Sealed Air Corporation |
| Coveris Holdings SA |
| Winpak Ltd. |
| RKW Group |
| Mondi Group |
| Sonoco Products Company |
| Charter Next Generation |
| Others |
Supply & Pricing Matrix
Caprolactam feedstock concentration in Germany and China determines both the spread between premium barrier grades and commodity overwrap pricing and the geographic clustering of polyamide resin supply. This single-source dependency for nylon barrier layers compresses margins on multi-layer structures while elevating technical service bundling as the primary price differentiation mechanism.
Pricing Analysis
Aftermarket technical service revenue streams now drive lifetime value capture more than resin tonnage sales. Three-tier pricing structure across premium, standard, and economy levels segments buyers by equipment integration depth and formulation complexity. Cost compression in commodity polyethylene overwrap intensifies as mono-material mandates force R&D reinvestment cycles. Food service distributors exhibit highest price sensitivity, while German meat processors absorb premiums for guaranteed line uptime specifications.
Supply Chain Analysis
Extended payment terms from German retail chains and supply-chain finance facilities anchored by Bavarian processing hubs are restructuring working capital requirements for converter operations. Raw material sourcing draws from Saudi ethylene feedstock, Belgian caprolactam, and Korean EVOH resin streams. Single-source vulnerability concentrates in polyamide 6 production clusters exposed to force majeure disruptions. Distribution runs through centralized slaughter and cutting operations in export logistics corridors before radiating to retail and food service endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service revenue layers attached to packaging line optimization contracts are expanding faster than commodity film tonnage, reframing supplier economics around recurring performance guarantees rather than transactional resin sales.
For Market Incumbents: Build equipment protocol lock-in moats by embedding film specifications directly into processor maintenance schedules and spare parts logistics. Deepen backward integration into recycled resin streams to secure circular economy positioning ahead of EU Packaging and Packaging Waste Regulation enforcement. Expand technical service headcount in German centralized processing hubs where uptime guarantees outweigh unit cost in procurement criteria. For New Entrants and Emerging Players: Tier-2 Indian cities with FSSAI-mandated cold storage expansion represent the most penetrable entry point for high-barrier film suppliers lacking established retail chain relationships. Chemical recycling infrastructure partnerships with petrochemical majors offer white-space positioning for multi-layer waste stream recovery currently landfilled. Target poultry processors in underpenetrated cold chain corridors with active antimicrobial coating formulations as a differentiated go-to-market anchor. For Investors and Strategic Acquirers: The market sits at a regulatory-forced reformulation phase that favors converters with captive resin supply and established FDA/EFSA notification expertise. Long-term viability over the next decade hinges on mono-material R&D pipelines and chemical recycling feedstock access rather than legacy multi-layer capacity. Watch ECHA substance restriction timelines on intentional microplastics as the inflection signal for anti-fog additive reformulation scramble intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material R&D Investment | EU Packaging and Packaging Waste Regulation compliance demands dismantling multi-layer structures for recyclability. |
| Chemical Recycling Partnership | Pyrolysis alliances with petrochemical majors enable closed-loop recovery for currently non-recyclable film waste. |
| Active Antimicrobial Coating Launch | Nisin and chitosan formulations capture premium pricing in ready-to-cook marinated meat segments. |
| Technical Service Network Expansion | German meat processors prioritize packaging line uptime guarantees over unit cost minimization in vendor selection. |
| Backward Integration into Recycled Resin | Mondi Group's captive kraft paper and recycled resin streams anchor European supply security positioning. |
Research Methodology
Cross-validation between primary interviews with film converter plant managers, meat processor procurement leads, and retail chain category buyers anchors the qualitative findings against secondary validation from EU Packaging and Packaging Waste Regulation filings, ECHA substance restriction databases, and customs trade data for ethylene and caprolactam feedstock flows. Bottom-up triangulation across equipment protocol specifications and top-down analysis of resin demand patterns were combined to calibrate segment-level estimates.
Calibration against historical pricing spreads between barrier grades and commodity overwrap structures, combined with equipment installation rates in German processing hubs, shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include film type chemistry, thickness gauge, barrier functional performance, end-user procurement archetype, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating cold chain infrastructure buildout rates and reformulation cycle timelines.
Stress conditions across caprolactam supply disruptions, EU Green Deal carbon border friction intensity, and mono-material revalidation timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement schedules and equipment replacement cycles. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Heat Transfer Films Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Moisture Barrier Bags Market
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
Saudi Arabia Plastic Packaging Films Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Biodegradable Plastic Films Market
Packaging Barrier Films
Barrier Coated Papers Market