
 Global Micro-Perforated Films Market | 2026-2036
Global Micro-Perforated Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micro-Perforated Films Market Foresight
Fresh produce distributors is collapsing toward food service aggregators and meal-kit platforms as the dominant procurement channel for breathable packaging. Amcor plc leverages its vertical integration into resin formulation and film conversion to sustain margin control across polyethylene and polypropylene grades. Sealed Air Corporation anchors North American supply through proprietary micro-perforation equipment and food safety certification depth. Mondi Plc competes via kraft-paper hybrid structures that merge fiber-based sustainability claims with controlled gas permeability.
Micro-perforated films are polymer substrates engineered with laser- or mechanically punched apertures ranging from 50 to 200 microns, designed to balance oxygen and carbon dioxide exchange while blocking moisture loss and microbial ingress. Polyethylene dominates volume for cost-sensitive fresh produce wrapping, while polypropylene captures premium positioning in retort-ready and microwaveable applications where thermal stability determines performance. Food packaging concentrates the largest revenue pool, though medical device sterilization pouches represent the fastest-growing application as hospitals shift toward pre-sterilized, breathable barrier systems.
The U.S. FDA regulates direct food-contact films through 21 CFR compliance for migration limits, while the EU F-Gas Regulation and REACH restrict certain fluorinated barrier chemistries used in high-performance variants. Japan's METI enforces JIS standards for plastic recycling compatibility that reshape material selection for exporters targeting that market. Stakeholders must decide whether to absorb compliance costs across multiple certification regimes or consolidate production in jurisdictions with mutual recognition agreements.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing converters to redesign film structures for mechanical recyclability, collapsing legacy multi-material laminates toward mono-polymer or fiber-hybrid formats.
Growth Catalysts
- Fresh produce shelf-life extension:Retailers and food service aggregators specify micro-perforated polyethylene for breathable wrapping of berries, leafy greens, and prepared salads to reduce shrinkage.
- REACH fluorinated chemistry restrictions:The EU F-Gas Regulation and ECHA proposals on PFAS are redirecting high-barrier film demand toward perforated mono-material alternatives that avoid fluorinated coatings.
- Medical sterilization pouch migration:Hospitals in Germany and Japan are replacing reusable instrument trays with pre-sterilized, breathable barrier pouches for infection control compliance.
Market Restraints
- Resin price volatility:Polypropylene and polyethylene feedstock costs fluctuate with crude oil and natural gas benchmarks, compressing converter margins on fixed-price annual contracts.
- Laser perforation equipment concentration:Precision micro-perforation machinery suppliers cluster in Northern Italy and Southern Germany, creating lead time bottlenecks for capacity expansion.
- Competing active packaging formats:Ethylene absorber sachets and modified atmosphere packaging systems capture premium fresh produce accounts that prioritize shelf-life over breathability.
Strategic Opportunities
- India organized retail penetration:Reliance Retail and BigBasket are building cold-chain distribution for fruits and vegetables, creating first-time specification of breathable films in a market historically using open crates.
- Cellulose nanofiber hybrid structures:Convergence of kraft paper substrates with bio-based sealant layers opens compostable claims for bakery and ready-meal segments under EU Single-Use Plastics Directive scope.
- Meal-kit platform direct sourcing:HelloFresh and Blue Apron procurement teams are bypassing traditional distributors to specify custom perforation patterns for specific produce SKUs.
Industry Challenges
- Migration testing complexity:21 CFR compliance for direct food contact requires batch-specific analytical verification, extending new product qualification timelines by four to six months.
- Perforation pattern IP fragmentation:Proprietary laser control algorithms and hole-array geometries are locked behind competitor patent thickets, limiting design freedom for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micro-Perforated Films Market |
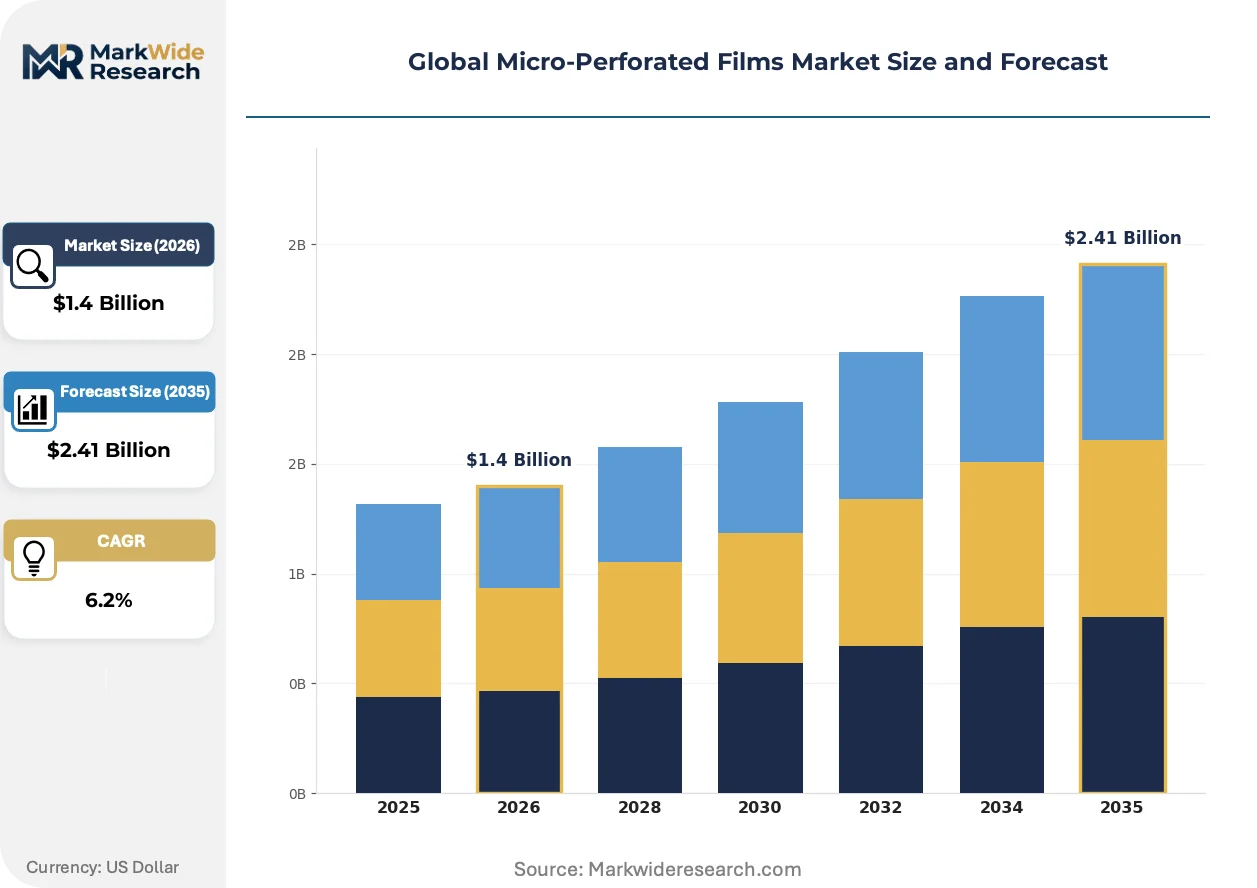
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester, Ethylene Vinyl Acetate Application: Food Packaging, Medical Devices, Agricultural Films, Disposable Hygiene, Industrial Packaging End User Industry: Consumer Goods Manufacturers, Pharmaceutical Companies, Agricultural Suppliers, Industrial Goods Producers Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Retail Chains |
| Companies Covered | Amcor plc, Sealed Air Corporation, Mondi Plc, Winpack Ltd., UPM-Kymmene Corporation, Bolloré Group, Polyplex Corporation Limited, Sonoco Products Company, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micro-Perforated Films Market Shifts & Advancements
Digital printing integration and artificial intelligence-driven quality control are compressing minimum order quantities and enabling SKU proliferation that legacy analog production could not support.
Water-based barrier coatings for polyethylene substrates are decomposing the historical trade-off between moisture resistance and recyclability. Fresh produce packagers in the Netherlands and Belgium are trialing these formulations for cucumber and pepper wrapping. The technology is decomposing demand for ethylene vinyl alcohol coextrusions that previously dominated high-humidity applications.
The EU Green Deal's packaging recyclability targets are accelerating mono-material mandates across member states. France's AGEC law and Germany's VerpackG amendments now require demonstratable mechanical recycling compatibility for household packaging. Converters serving Aldi and Lidl pan-European supply chains are consolidating specifications to polypropylene or polyethylene mono-structures to avoid country-specific SKUs.
Food service aggregators are consolidating procurement decisions previously dispersed across regional distributors. Sysco and US Foods specification teams now mandate shelf-life performance guarantees backed by modified atmosphere testing data, shifting supplier selection criteria from price-per-kilogram toward total cost of spoilage reduction. This concentration is most visible in the US Northeast and California produce distribution corridors.
Global Micro-Perforated Films Market Segmentation
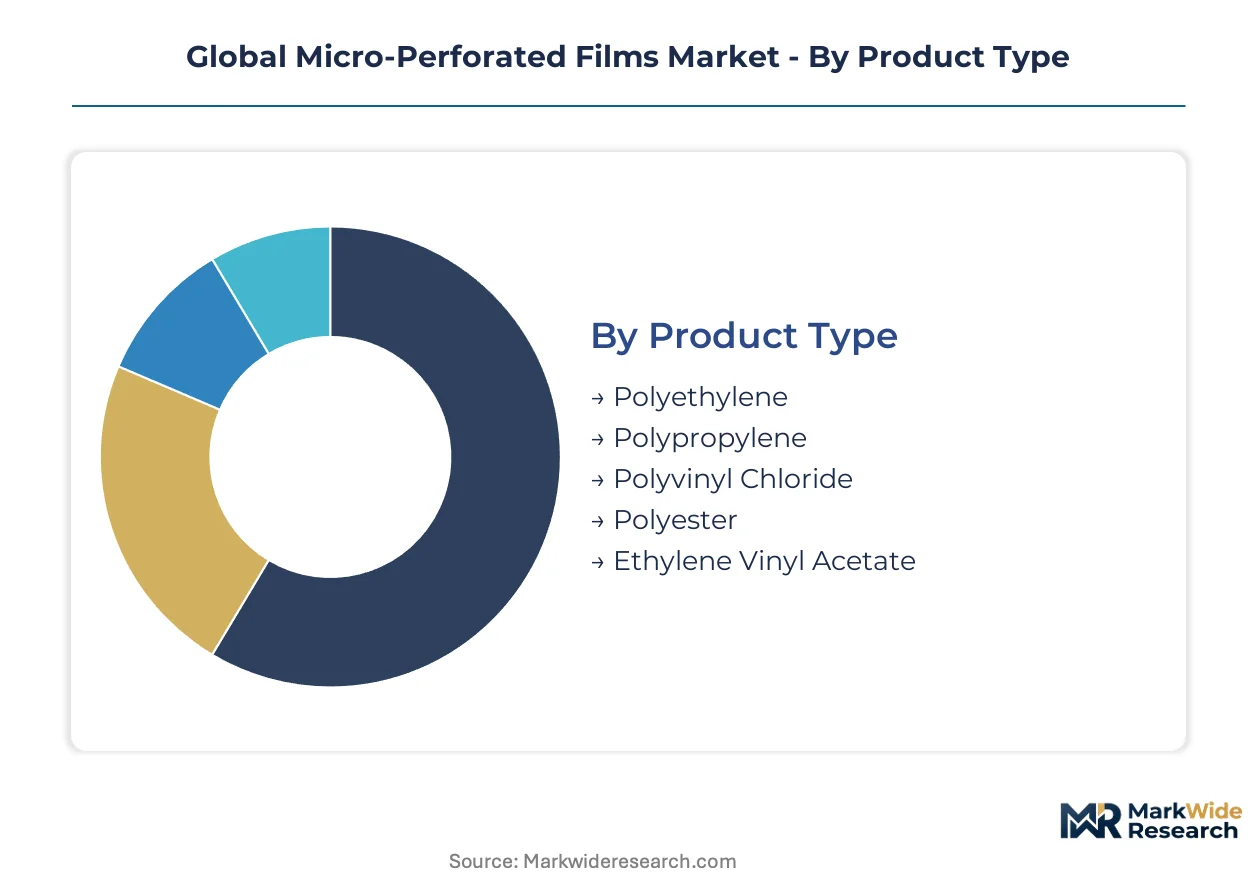
Micro-perforated film specifications diverge sharply across resin chemistry and end-use performance requirements. Channel selection determines margin capture, with direct sales yielding specification control while distributors absorb working capital burdens for smaller accounts.
Product Type:
Polyethylene and polypropylene flow predominantly through distributor networks for cost-sensitive fresh produce wrapping, while specialty grades reach medical and industrial buyers via direct technical sales teams.
- Polyethylene:Linear low-density formulations dominate breathable berry and leafy green wrapping due to puncture resistance and cost positioning. German bakery chains and Dutch produce distributors specify this grade for automated flow-wrap lines where seal integrity at high speeds determines throughput.
- Polypropylene:Biaxially oriented structures capture retort-ready and microwaveable applications requiring thermal stability above 120°C. Japanese meal-kit platforms and German ready-meal producers drive specification of cast polypropylene for modified atmosphere compatibility.
- Polyvinyl Chloride:Cling film variants persist in manual wrapping operations for meat and cheese counters where stretch recovery matters more than breathability precision.
- Polyester:High-clarity grades serve premium produce branding where shelf visibility and printability justify material cost premiums.
- Ethylene Vinyl Acetate:Coextruded sealant layers enable cold-seal adhesion for heat-sensitive confectionery and chocolate applications.
Polyethylene dominates installed base. Polypropylene is where expansion concentrates.
Application:
Volume distribution skews toward food contact approvals, while margin concentration sits with medical certification depth and technical service intensity.
- Food Packaging:Breathable lidding and flow-wrap for fresh produce, bakery, and ready-meals constitutes the revenue foundation. Aldi and Lidl pan-European procurement teams are consolidating specifications toward mono-material polyethylene to satisfy Germany's VerpackG recyclability mandates.
- Medical Devices:Sterilization pouches for pre-sterilized surgical instruments are climbing the fastest as German and Japanese hospitals replace reusable trays for infection control compliance. Tyvek-compatible sealant layers require FDA 21 CFR and EU MDR dual certification.
- Agricultural Films:Greenhouse climate-control films with precision perforation patterns regulate humidity for high-value tomato and pepper cultivation in Spain and Italy.
- Disposable Hygiene:Breathable backsheet films for adult incontinence products require soft tactile properties and moisture vapor transmission balance.
- Industrial Packaging:VCI film perforation for corrosion-sensitive metal components serves automotive tier-one suppliers in Germany and the US Midwest.
Food packaging anchors volume scale. Medical devices command price premiums through certification barriers.
End User Industry:
Procurement sophistication varies dramatically, with pharmaceutical and consumer goods buyers driving specification complexity while agricultural suppliers prioritize unit economics.
- Consumer Goods Manufacturers:Unilever and Nestlé packaging engineers specify custom perforation patterns for specific produce SKUs, bypassing traditional distributors to work directly with converters.
- Pharmaceutical Companies:Sterile barrier qualification protocols extend supplier onboarding to 18-24 months, concentrating purchasing among converters with FDA and EU MDR established master files.
- Agricultural Suppliers:Bayer Crop Science and Syngenta distributors specify greenhouse films through regional cooperatives in Italy's Emilia-Romagna and Spain's Almería clusters.
- Industrial Goods Producers:Bosch and Siemens procurement teams mandate VCI film performance guarantees backed by accelerated corrosion testing data.
Consumer goods manufacturers drive SKU proliferation. Pharmaceutical companies enforce the steepest supplier consolidation.
Distribution Channel:
Channel selection determines working capital allocation and technical service intensity, with direct relationships enabling specification lock-in.
- Direct Sales:Amcor and Mondi field technical service teams co-develop perforation patterns with HelloFresh and Blue Apron procurement groups, embedding converters in meal-kit platform supply chains.
- Distributors:Regional plastics distributors in France and Italy hold polyethylene inventory for small-to-mid produce packagers lacking volume to justify mill-direct relationships.
- E-commerce Platforms:Alibaba and IndiaMART channels serve experimental buyers in India's organized retail buildout, though cold-chain reliability remains inconsistent.
- Retail Chains:Carrefour and Tesco private-label specification teams source directly for controlled-atmosphere produce bags, consolidating volumes across multiple country operations.
Direct sales commands margin leadership. Distributors absorb volume volatility for fragmented accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters export micro-perforated polyethylene to Dutch produce distributors and French retail chains, establishing a westward trade corridor that shapes European specification standards. Asian demand pulls Japanese biaxially oriented polypropylene toward meal-kit platforms in South Korea and Taiwan. North American supply chains bridge Canadian resin production with US food service aggregator consolidation.
Germany
Bakery chains and ready-meal producers in Bavaria and North Rhine-Westphalia specify cast polypropylene for modified atmosphere compatibility. The country's VerpackG amendments enforce mechanical recycling compatibility, collapsing multi-material laminates toward mono-polymer formats. Laser perforation equipment suppliers cluster in Southern Germany, creating lead time bottlenecks for capacity expansion across the Rhine-Ruhr industrial belt.
United States
Food service aggregators in the Northeast and California produce distribution corridors mandate shelf-life performance guarantees backed by modified atmosphere testing data. FDA 21 CFR compliance governs direct food-contact migration limits for berry and leafy green wrapping. Sysco and US Foods specification teams consolidate procurement decisions previously dispersed across regional distributors.
Japan
Hospitals in Tokyo and Osaka replace reusable instrument trays with pre-sterilized, breathable barrier pouches for infection control compliance. METI enforces JIS standards for plastic recycling compatibility that reshape material selection for exporters targeting this market. Meal-kit platforms in the Kanto region drive specification of thermally stable films for microwaveable applications.
India
Reliance Retail and BigBasket build cold-chain distribution for fruits and vegetables, creating first-time specification of breathable films in markets historically using open crates. FSSAI food-contact regulations govern polyethylene formulations for produce wrapping. Maharashtra and Karnataka organized retail penetration concentrates demand in Mumbai and Bangalore metropolitan corridors.
Netherlands
Produce distributors in Rotterdam and Amsterdam trial water-based barrier coatings for cucumber and pepper wrapping, decomposing demand for ethylene vinyl alcohol coextrusions. The EU Green Deal's packaging recyclability targets accelerate mono-material mandates across Dutch supply chains. Wageningen University research clusters drive formulation innovation for breathable film substrates.
Global Micro-Perforated Films Market Competitive Landscape
Listed leaders compete with private specialists across resin formulation and film conversion capabilities. Three-tier concentration prevails: multinational converters with captive resin supply, mid-scale regional specialists with laser perforation equipment partnerships, and commodity distributors serving fragmented produce packagers. Strategic archetypes separate backward-integrated resin producers, equipment-integrated converters, and sustainability-focused fiber-hybrid innovators. Competitive moves center on mono-material portfolio diversification and direct technical service embedding with meal-kit procurement teams.
Among publicly listed packaging conglomerates, Amcor plc and Sealed Air Corporation exemplify scale-driven archetypes with established FDA and EU MDR certification depth. Mondi Plc occupies a position within the fiber-hybrid tier, representing kraft-paper convergence strategies. These three anchors demonstrate how geographic footprint breadth and regulatory master file depth create supplier consolidation pressure in pharmaceutical and premium food segments.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Mondi Plc |
| Winpack Ltd. |
| UPM-Kymmene Corporation |
| Bolloré Group |
| Polyplex Corporation Limited |
| Sonoco Products Company |
| ProAmpac |
| Others |
Supply & Pricing Matrix
Water-based barrier coatings displacing ethylene vinyl alcohol coextrusions are redrawing procurement geography toward Dutch and Belgian converters while collapsing the historical premium attached to multi-layer structures. This substitution simultaneously compresses margins on legacy laminate producers in Germany and creates first-mover pricing power for coating innovators serving Aldi and Lidl pan-European specifications.
Pricing Analysis
Mechanical perforation equipment pricing gaps separate legacy Italian machinery from next-generation German laser systems and experimental ultrasonic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FDA 21 CFR and EU MDR dual-certified films commanding substantial premiums over commodity polyethylene grades. Price differentiation hinges on volume scale and customization level, with meal-kit platform direct contracts absorbing margin compression better than distributor-served fragmented accounts. Cost compression in standard-grade polyethylene is intensifying because resin price volatility transfers directly to fixed-price annual contracts.
Supply Chain Analysis
Inventory lead times for precision laser perforation equipment extend 14-20 months due to supplier clustering in Southern Germany and Northern Italy. Geographic supply concentration centers on Germany for cast polypropylene, the Netherlands for coating innovation, and China for base polyethylene resin. Raw material dependencies draw from crude oil and natural gas feedstocks, specialty laser optics, and water-based polymer dispersions. Single-source vulnerability in perforation machinery creates expansion bottlenecks for converters serving EU Green Deal recyclability mandates. Distribution runs through direct technical sales for medical and meal-kit accounts, regional distributors for fragmented produce packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-perforated films sit in early-cycle expansion as organized retail penetration in India and medical sterilization pouch migration in Germany and Japan create first-time specification demand in historically underpenetrated channels.
For Market Incumbents: Shield margin position by deepening backward integration into resin formulation and securing exclusive laser equipment partnerships with Southern German machinery suppliers. Consolidate certification master files across FDA 21 CFR and EU MDR to raise barriers against emerging Asian converters. Prioritize embedding technical service teams with HelloFresh and Blue Apron procurement groups to lock in direct relationships before distributor alternatives mature. For New Entrants and Emerging Players: Lead with cellulose nanofiber hybrid structures targeting EU Single-Use Plastics Directive compliance gaps in bakery and ready-meal segments. India's organized retail buildout offers the most penetrable geography, with Reliance Retail and BigBasket cold-chain expansion creating first-mover opportunity absent entrenched supplier relationships. Pursue e-commerce platform visibility through Alibaba and IndiaMART to capture experimental buyers before traditional distributor networks consolidate. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European converters holding laser perforation equipment partnerships but lacking backward integration into resin supply. Long-term viability over a 5-10 year window rests on mono-material portfolio positioning ahead of EU Packaging and Packaging Waste Regulation enforcement waves. Watch for inflection in water-based barrier coating adoption rates among Dutch produce distributors as signal of technology-generation transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Portfolio Conversion | Aligns converter output with Germany's VerpackG mechanical recyclability mandates and Aldi pan-European procurement consolidation. |
| Direct Technical Service Embedding | Positions converters inside meal-kit platform supply chains, bypassing distributor margin extraction for SKU-proliferation accounts. |
| Water-Based Barrier Coating Scale-Up | Captures Dutch and Belgian produce distributor trials while displacing ethylene vinyl alcohol coextrusion demand. |
| Laser Perforation Equipment Partnership | Secures capacity expansion rights amid 14-20 month lead time bottlenecks in Southern Germany supplier clusters. |
| Dual Certification Master File Investment | Creates pharmaceutical and medical device barrier qualification depth that extends supplier onboarding timelines to 18-24 months. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with film conversion executives, laser equipment manufacturers, produce procurement managers, and regulatory compliance officers; and secondary validation through customs trade databases, SEC 10-K filings of listed packaging conglomerates, EU regulatory filings on packaging waste directives, and resin price benchmark series. Bottom-up triangulation across resin grade demand curves and top-down verification against end-use industry consumption patterns anchored volume estimates.
Across the analysis window, the forecasting framework modeled resin chemistry segments, application end-uses, geographic demand clusters, and channel structure evolution as core dimensions. CAGRs emerged from segment-level growth rate synthesis rather than single-equation extrapolation. Key inputs included EU regulatory enforcement timelines for recyclability mandates, cold-chain infrastructure buildout rates in Indian organized retail, and hospital infection control procurement shifts in Germany and Japan.
Underlying assumptions cover sustained EU Green Deal packaging policy trajectory, stable crude oil feedstock pricing bands, and continued meal-kit platform consolidation, with deviation risk concentrated in resin price volatility spikes and laser equipment supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
Barrier Foil Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
North America Barrier Films Market
Packaging Barrier Films
Sealant Web Films Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Global Silicone Release Liner Market