
 Global Metalized Barrier Films Market | 2026-2036
Global Metalized Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metalized Barrier Films Market Intelligence
A shift from single-source to multi-source procurement for specialized films is decoupling buyer relationships from exclusive, long-term contracts. Large converters like Amcor leverage their global purchasing power to secure favorable terms across multiple suppliers. Jindal Poly Films competes on production scale and cost efficiency in high-volume polyester film segments. Meanwhile, Toray Plastics differentiates through its R&D in high-performance nylon and polypropylene film formulations.
Metalized barrier films are polymer substrates, such as polyester or polypropylene, coated with a micro-thin layer of metal like aluminum via vapor deposition. This process imparts high barrier properties against oxygen and moisture, serving as a cost-effective alternative to pure aluminum foil laminates. Among product types, polyester films represent the largest volume, but nylon films command higher margins for specialized applications. Food packaging remains the primary application, with pouches and sealed bags driving significant consumption.
Compliance with food contact regulations, such as those from the US FDA and the EU's framework under EFSA, is mandatory for market access. Chemical substance rules like the EU's REACH and China's GB standards govern the composition of adhesives and coatings used in film production. The key decision for manufacturers now centers on balancing barrier performance with the development of more recyclable, mono-material film structures.
Market Dynamics
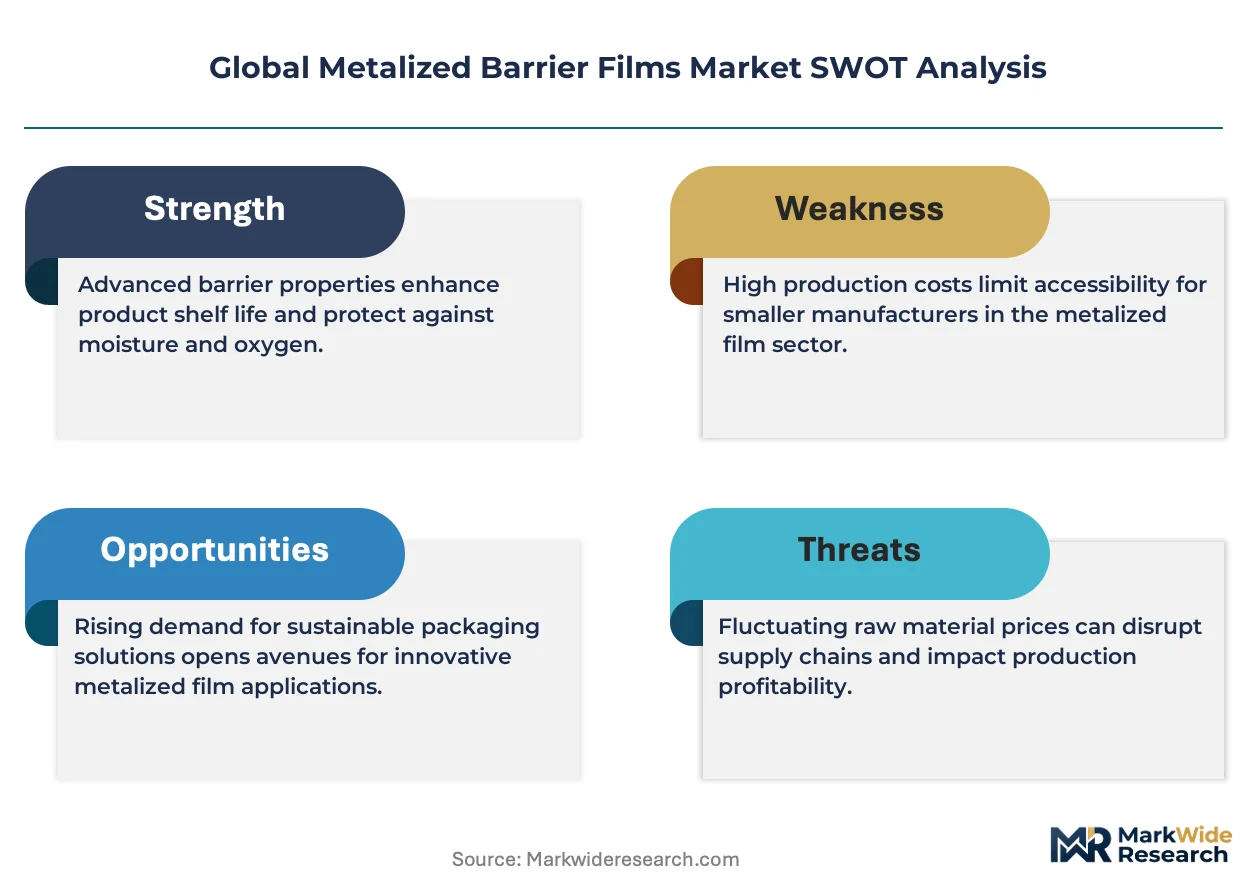
The central structural force shaping the market is the conflict between the demand for higher barrier performance and the urgent need for sustainable packaging. This tension pits traditional, high-performance metalized laminates against emerging mono-material structures designed for recyclability, a choice heavily influenced by global regulations.
Growth Catalysts
- Pharmaceutical Packaging Demand:Stringent requirements for protecting sensitive drugs from moisture, oxygen, and light are driving consumption in pharmaceutical applications, where barrier integrity is non-negotiable.
- Indian Market Expansion:India's rapidly growing food processing and fast-moving consumer goods sectors are creating significant new demand for flexible packaging solutions like pouches and bags.
- Vapor Deposition Efficiency:The cost-effectiveness of vapor deposition to create a barrier, compared to thicker and more resource-intensive aluminum foil laminates, provides a strong economic incentive for adoption.
Market Restraints
- Input Cost Volatility:Fluctuation in the price of key raw materials, including petroleum-derived polymer resins like PET and polypropylene, as well as aluminum, creates margin pressure for film producers.
- Recyclability Challenges:The multi-layer, multi-material composition of many metalized films makes them difficult to separate and recycle, creating friction with circular economy goals and plastic waste regulations.
- Substitution from High-Clarity Barriers:The development of transparent barrier technologies, such as AlOx and SiOx coatings, presents a substitution threat in applications where product visibility is a key marketing requirement.
Strategic Opportunities
- High-Performance Electronics Packaging:Untapped potential exists in packaging for sensitive electronic components, such as flexible displays or semiconductors, which require extreme protection against static discharge and environmental factors.
- Bio-based Polymer Substrates:Developing metalized barrier films using biodegradable or compostable polymers like PLA offers a path to capture demand from environmentally conscious brands and consumers.
- ASEAN Market Penetration:Expanding sales and distribution into Southeast Asian countries beyond India can capture growth from a rising middle class and increasing consumption of packaged foods and beverages.
Industry Challenges
- Regulatory Compliance Complexity:Manufacturers face the challenge of navigating and adhering to a diverse and evolving landscape of food contact material regulations, including rules from the US FDA, the EU's EFSA, and China's GB standards.
- Capital Investment Intensity:Achieving competitive scale and efficiency requires significant capital expenditure in advanced vacuum metallization chambers, plasma treatment systems, and high-speed slitting and winding equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metalized Barrier Films Market |
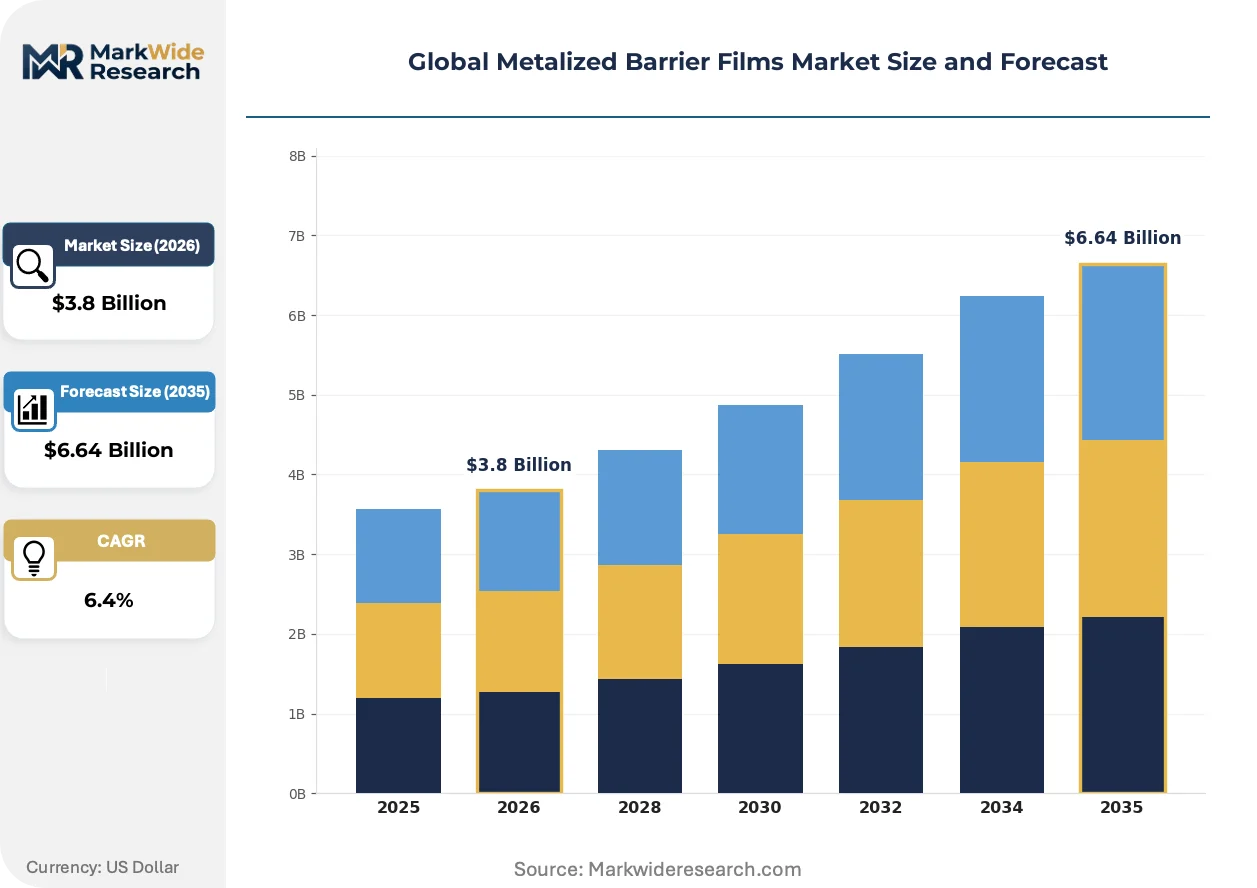
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Films, Polypropylene Films, Nylon Films, Aluminum Foil Laminates, Cellophane Films Application: Food Packaging, Pharmaceutical Packaging, Electronics Insulation, Cosmetic Wrapping, Automotive Wrapping End Use Industry: Consumer Goods, Medical Devices, Electrical & Electronics, Personal Care, Transportation Equipment Packaging Type: Pouches, Blister Packs, Vacuum Packs, Wrappers, Sealed Bags |
| Companies Covered | Amcor, Jindal Poly Films, Toray Plastics, UFlex, Berry Global, Cosmo Films, Taghleef Industries, Polyplex, Celplast Metallized Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metalized Barrier Films Market Strategic Shifts & Innovations
Material science advancements are directly confronting circular economy mandates, forcing a fundamental re-evaluation of film design. The industry is focused on innovating beyond traditional structures to meet new performance, sustainability, and regulatory benchmarks simultaneously.
Transparent barrier coatings like Aluminum Oxide (AlOx) and Silicon Oxide (SiOx) provide high protection against oxygen and moisture without the opacity of metal. These materials are seeing rapid adoption in premium food segments, such as organic snacks and coffee, where product visibility enhances consumer appeal. This technology is expanding into medical and retort pouch applications, offering a recyclable alternative to foil-based laminates.
European Union directives promoting a circular economy are compelling a shift toward mono-material packaging designs. This regulatory pressure directly impacts film converters, pushing them to abandon traditional mixed-polymer laminates in favor of more recyclable options. The flexible food packaging segment is most affected, with research and development now prioritizing all-polypropylene or all-polyethylene film structures that are compatible with existing recycling streams.
Buyer behavior among large converters and consumer packaged goods companies is evolving from single-source allegiances to dynamic multi-supplier strategies. This model prioritizes supply chain resilience and cost optimization over exclusive long-term contracts, using competitive bidding to secure favorable terms. This procurement pattern is most pronounced in the high-volume North American and European markets where global purchasing power is greatest.
Global Metalized Barrier Films Market Segmentation
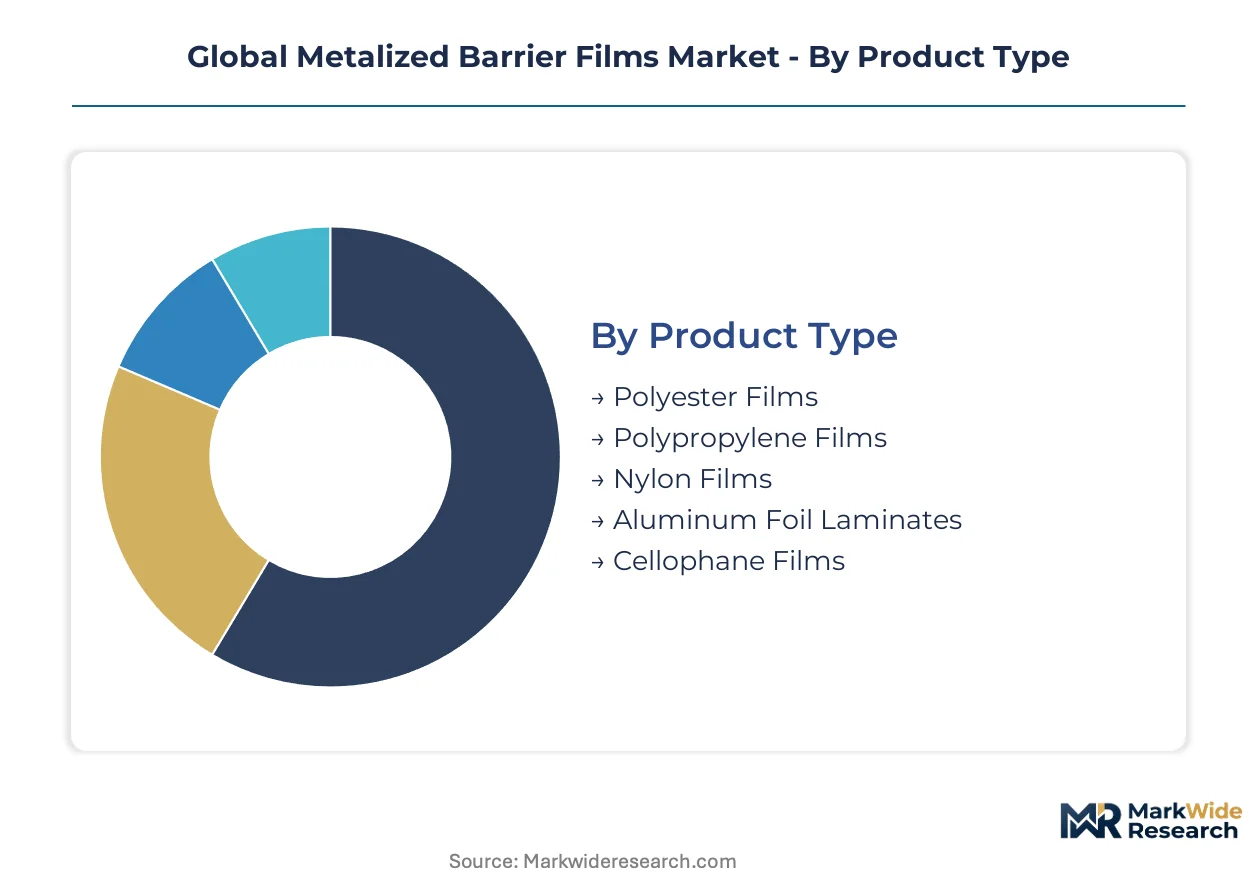
The global metalized barrier films market is segmented across several critical dimensions, reflecting the diverse material science, application requirements, and end-use industry demands. Understanding these segments helps clarify where value is concentrated and where future innovation efforts are directed, balancing performance with sustainability goals.
Product Type:
The market for metalized barrier films differentiates between standalone polymer substrates and those integrated into more complex laminate structures, each offering distinct barrier properties and cost profiles.
- Polyester Films:These films are polymer substrates, typically PET, coated with a micro-thin layer of metal, providing excellent oxygen and moisture barrier properties. Demand concentrates in high-volume food packaging applications, driven by their balance of performance, clarity, and cost-effectiveness.
- Nylon Films:Nylon films, when metalized, offer superior puncture resistance and barrier integrity, making them suitable for demanding applications. These films command higher margins in specialized pharmaceutical and medical device packaging, where barrier integrity is non-negotiable.
- Polypropylene Films:Metalized polypropylene films provide good moisture barrier and heat sealability, finding use in snack food packaging.
- Aluminum Foil Laminates:These structures offer the highest barrier performance but are thicker and less flexible than metalized films.
- Cellophane Films:Regenerated cellulose films, when metalized, offer a biodegradable option with moderate barrier properties for niche markets.
Polyester Films lead volumes today; Nylon Films are gaining share fastest.
Application:
Demand for metalized barrier films varies significantly across different applications, reflecting diverse volume requirements and critical performance standards.
- Food Packaging:This application utilizes metalized films for pouches and sealed bags to extend shelf life by protecting contents from oxygen and moisture degradation. Consumption is particularly high in India's expanding food processing sector, where flexible packaging solutions are vital.
- Pharmaceutical Packaging:Metalized films shield sensitive drugs from light, moisture, and oxygen, ensuring product stability and efficacy. Stringent regulatory compliance from bodies like the US FDA and EFSA drives demand for high-integrity barrier solutions in this sector.
- Electronics Insulation:Metalized films provide electrostatic discharge protection and barrier against environmental factors for sensitive electronic components.
- Cosmetic Wrapping:These films are used for aesthetic appeal and barrier protection in cosmetic product packaging.
- Automotive Wrapping:Niche applications exist in automotive components requiring specific barrier or reflective properties.
Food Packaging represents the largest consumption; Pharmaceutical Packaging is climbing the fastest.
End Use Industry:
The maturity of end-use industries influences the adoption rates and performance expectations for metalized barrier film solutions.
- Consumer Goods:This industry, encompassing food and beverage, relies heavily on metalized films for flexible packaging, driven by convenience and shelf-life extension. India's burgeoning consumer goods market is a significant growth catalyst for this segment.
- Medical Devices:Metalized films protect sterile medical devices from moisture, oxygen, and contaminants, ensuring product integrity until use. The stringent regulatory environment in healthcare demands high-performance barrier solutions.
- Electrical & Electronics:Metalized films provide barrier and static protection for components in this industry.
- Personal Care:Packaging for personal care products often uses metalized films for barrier properties and visual appeal.
- Transportation Equipment:Specialized applications include protective wraps for sensitive components during transit.
Consumer Goods drives the largest demand; Medical Devices exhibits the steepest expansion trajectory.
Packaging Type:
Packaging type selection often correlates with the required barrier performance and the associated margin profiles.
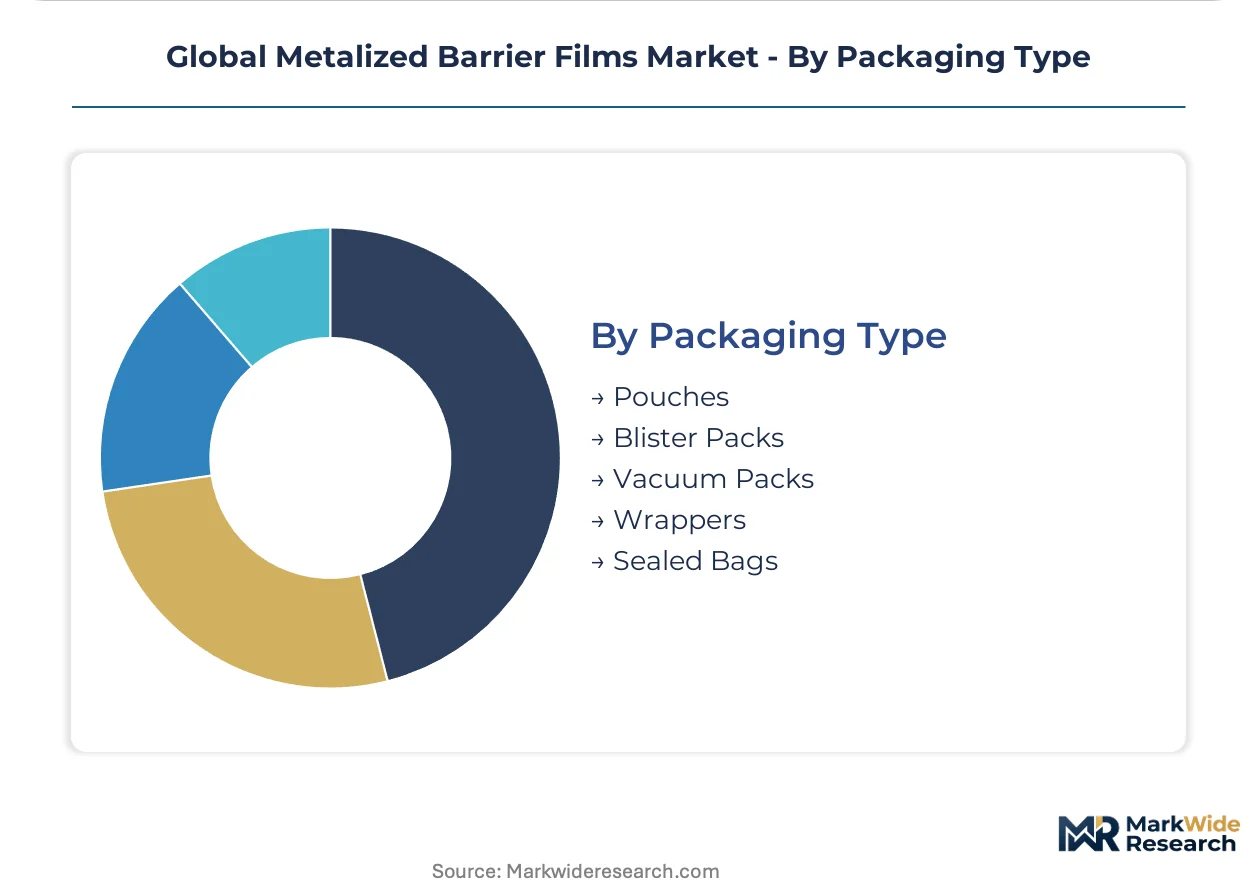
- Pouches:Flexible pouches, often stand-up or flat, are a dominant packaging type utilizing metalized barrier films for various food and pharmaceutical products. Their versatility and material efficiency drive significant consumption across global markets.
- Sealed Bags:These bags, used for items like snacks, coffee, and bulk goods, leverage metalized films for effective barrier protection against environmental factors. The cost-effectiveness of vapor deposition makes metalized films a preferred choice over pure aluminum foil.
- Blister Packs:Metalized films can be integrated into blister packs for enhanced barrier protection of individual items.
- Vacuum Packs:Packaging that requires air removal benefits from the high barrier properties of metalized films.
- Wrappers:Confectionery and other small items use metalized film wrappers for freshness and visual appeal.
Pouches dominate consumption; Sealed Bags are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's food processing sector, with its expanding consumer goods market, drives significant demand for flexible packaging solutions. This growth necessitates high-performance metalized barrier films to extend shelf life and ensure product integrity. Regulatory environments and industrial concentrations further shape regional adoption patterns.
India
India's rapidly expanding food processing and consumer goods sectors are creating substantial new demand for flexible packaging. The Food Safety and Standards Authority of India (FSSAI) mandates specific material standards for food contact applications. Major manufacturing hubs like Delhi-NCR and Mumbai are seeing increased investment in advanced packaging technologies.
United States
The United States market exhibits strong demand for metalized films in pharmaceutical and premium food packaging applications. The US FDA sets stringent requirements for barrier integrity and material safety in these critical sectors. Clusters in the Northeast, particularly around pharmaceutical research and manufacturing, drive specialized film consumption.
Germany
Germany represents a key European market, driven by its medical devices and high-end consumer goods industries. Compliance with the EU's EFSA food contact regulations and REACH chemical substance rules is mandatory for market access. North Rhine-Westphalia, a major industrial region, concentrates advanced material production and packaging innovation.
China
China's vast consumer goods market and electronics manufacturing base generate substantial demand for metalized barrier films. The country's GB standards govern material composition and safety for various applications. The Yangtze River Delta region, a major economic zone, is a hub for both film production and advanced packaging conversion.
Global Metalized Barrier Films Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized, high-performance film structures. The market structure is tiered, with some players focusing on high-volume production and others on niche applications requiring advanced material science. Strategic archetypes include large integrated converters, specialized film manufacturers, and material science innovators. Dominant competitive moves involve capacity expansion to achieve economies of scale and strategic partnerships for technology development.
At the scale-driven end, Jindal Poly Films operates on production volume and cost efficiency across polyester film segments. Amcor, a large converter, leverages its global purchasing power to secure favorable terms across multiple suppliers, influencing market dynamics. Toray Plastics differentiates through its research and development in high-performance nylon and polypropylene film formulations, targeting specialized applications.
| Leading Market Players |
|---|
| Amcor |
| Jindal Poly Films |
| Toray Plastics |
| UFlex |
| Berry Global |
| Cosmo Films |
| Taghleef Industries |
| Polyplex |
| Celplast Metallized Products |
| Others |
Cost & Logistics Intelligence
Petroleum futures prices, alongside aluminum commodity benchmarks, cascade through the metalized barrier film supply chain, directly influencing pricing tiers for converters and end-users. Volatility in these raw material markets creates margin pressure across the entire value chain, from polymer resin producers to film manufacturers.
Pricing Analysis
Input cost fluctuations directly influence the price of metalized barrier films, with producers often passing on increases to maintain profitability. Pricing stratifies across premium, standard, and economy tiers, primarily differentiated by barrier performance and volume scale. Price differentiation also stems from specialized certifications, such as those required by the US FDA for pharmaceutical applications. Pricing softness is evident in high-volume, commoditized segments due to intense competition and the push for recyclability. Pharmaceutical and medical device manufacturers exhibit lower price sensitivity compared to large consumer goods companies.
Supply Chain Analysis
Regional distribution centers facilitate the movement of finished metalized films, optimizing logistics for converters and end-users. Supply concentration for metalized films centers on manufacturing hubs in China, India, and Germany. The industry relies heavily on petroleum-derived polymer resins like PET and polypropylene, as well as aluminum for metallization. Commodity price volatility in these raw materials represents a significant structural risk for film producers. Downstream distribution typically involves direct sales to large converters and specialized distributors serving smaller, niche market players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metalized barrier films market presents a compelling margin-expansion story, driven by the shift towards high-performance, specialized film structures that command higher prices.
For Market Incumbents: Hedge against substitution threats from transparent barrier technologies by investing in advanced AlOx and SiOx coating capabilities. Consolidate market share through strategic acquisitions of smaller, specialized film manufacturers to gain access to proprietary formulations. Focus R&D on developing mono-material film structures compatible with existing recycling streams, anticipating future regulatory mandates. Strengthen relationships with large consumer packaged goods companies by offering comprehensive, sustainable packaging solutions.
For New Entrants and Emerging Players: Specialized packaging distributors represent a key entry point for new entrants targeting niche applications. Penetrate the high-margin pharmaceutical packaging segment by offering films with superior barrier integrity and robust regulatory compliance. Target the rapidly expanding food processing sector in Southeast Asian countries beyond India, leveraging cost-effective production models. A go-to-market angle focused on custom, small-batch orders for premium and organic food brands can build initial traction.
For Investors and Strategic Acquirers: Asymmetric upside sits with material science innovators developing mono-material, recyclable film structures for the long term. Evaluate companies with strong intellectual property in bio-based polymer substrates or advanced coating technologies. Acquisition targets should demonstrate proven R&D capabilities and established compliance with stringent regulations like those from the EU's EFSA. A key signal to watch is the adoption rate of recyclable film structures by major consumer goods brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Addresses the growing demand from India's food processing and consumer goods sectors. |
| Green Manufacturing Transition | Aligns production processes with global sustainability mandates and circular economy goals. |
| Product Launch: Mono-Material Films | Captures demand from brands seeking recyclable packaging solutions compatible with EU directives. |
| Strategic Partnership with Electronics OEMs | Unlocks new revenue streams in high-performance electronics packaging applications. |
| Geographic Expansion into ASEAN | Penetrates new markets with rising middle-class consumption of packaged foods and beverages. |
Research Approach
Bottom-up food packaging and pharmaceutical packaging modeling reconciled against top-down film manufacturer and raw material supplier tracking forms the analytical core of this study. Primary interviews with packaging engineers, procurement managers, R&D directors, and regulatory compliance specialists provided qualitative insights. Secondary validation drew from US FDA guidelines, EFSA reports, FSSAI mandates, and trade association publications. This approach ensured comprehensive data triangulation.
Historical trendline analysis established foundational growth patterns across the analysis window. The forecast framework modeled market dynamics across product type, application, end-use industry, packaging type, and regional regulatory frameworks. Compound annual growth rates were derived through a proprietary statistical model, incorporating historical performance and projected influences. Polymer resin prices and food processing sector growth served as key industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving recycling infrastructure, new barrier technologies, and raw material price volatility. Forecasts reflect a comprehensive set of assumptions regarding market trajectory and external factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Barrier Bags Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
Release Coatings Market