
 USA Barrier Coated Paper Market | 2026-2036
USA Barrier Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
USA Barrier Coated Paper Market Analytics
Buyer concentration among national food brands and quick-service chains is rebalancing procurement volumes toward fewer, larger contracts with integrated converters. International Paper leverages its captive pulp supply and Midwest mill network to anchor long-term supply agreements with major CPG customers. Sonoco Products Company competes through specialized rigid paperboard formats for temperature-sensitive distribution. Dow differentiates its polyethylene coating resin portfolio to serve both legacy extrusion and emerging bio-hybrid barrier platforms.
Barrier coated paper combines base stock with functional layers to block moisture, oxygen, grease, or aroma transmission, typically employing polyethylene extrusion, wax lamination, or bio-based dispersions at coat weights between 10 and 40 grams per square meter. The primary commercial purpose centers on extending shelf stability while enabling fiber recovery in standard recycling streams. Paperboard dominates value contribution due to its structural rigidity in frozen food and quick-service packaging, while bio-based coatings represent the fastest-expanding material category as converters respond to brand sustainability mandates. Flexible packaging maintains mature growth in snack and confectionery wraps where downgauging pressure limits absolute margin expansion.
FDA food-contact notification requirements govern coating migration limits, while EPA Clean Air Act standards constrain solvent-based coating operations in heavily industrialized counties. OSHA process safety management rules affect chemical handling at coating facilities across the Ohio River Valley and Southeastern paper mill corridors. Stakeholders must monitor state-level extended producer responsibility legislation in California, Oregon, and New York, as these frameworks will determine whether fiber-plus-barrier formats qualify for preferred recycling streams or face downstream fees.
Market Dynamics
Plastic-to-paper substitution mandates from quick-service chains and CPG brands are compressing qualification timelines and forcing coating converters to validate bio-based barrier performance at commercial scale faster than historical fiber-grade transitions.
Growth Catalysts
- Extended Producer Responsibility frameworks:California, Oregon, and New York legislation creates preferential recycling economics for fiber-plus-barrier formats versus plastic alternatives, pulling brand investment toward compliant packaging structures.
- Quick-service restaurant cold-chain formats:Temperature-stable paperboard for frozen distribution is displacing expanded polystyrene across major chain rollouts, anchoring volume commitments to Midwest mill networks.
- Water-based dispersion coating:EPA Clean Air Act constraints on solvent-based operations in Ohio River Valley counties accelerate converter migration to aqueous barrier systems with lower volatile organic compound profiles.
Market Restraints
- Pulp cost volatility:Northern bleached softwood kraft price swings tied to Canadian lumber harvest cycles compress converter margins on fixed-price annual contracts with food brands.
- Polyethylene resin supply concentration:Gulf Coast petrochemical corridor disruptions from hurricane season create coating raw material availability risk for extrusion-dependent barrier lines.
- Moisture barrier performance ceiling:Current bio-based dispersions fail to match polyethylene grease resistance above 70°C, limiting penetration into hot-fill and retort applications.
Strategic Opportunities
- Ohio River Valley coating hub expansion:Underutilized paper machine capacity in Kentucky and West Virginia offers brownfield sites for integrated pulp-to-barrier coating investments with rail access to Chicago distribution.
- Pharmaceutical secondary packaging:Moisture-sensitive drug blister card outer wraps represent a white-space application with higher specification tolerance and price acceptance than commodity food formats.
- USDA BioPreferred program procurement mandates:Federal purchasing preferences for certified bio-based products create a guaranteed demand floor for qualifying barrier coated paper in military and institutional foodservice channels.
Industry Challenges
- FDA food-contact notification timelines:New coating chemistry submissions face 120-day review windows that delay commercial launches and extend customer qualification cycles beyond brand sustainability target dates.
- Recyclability certification complexity:Multi-material barrier structures require simultaneous validation against Fibre Box Association standards and How2Recycle labeling criteria, fragmenting technical resources across incompatible test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Barrier Coated Paper Market |
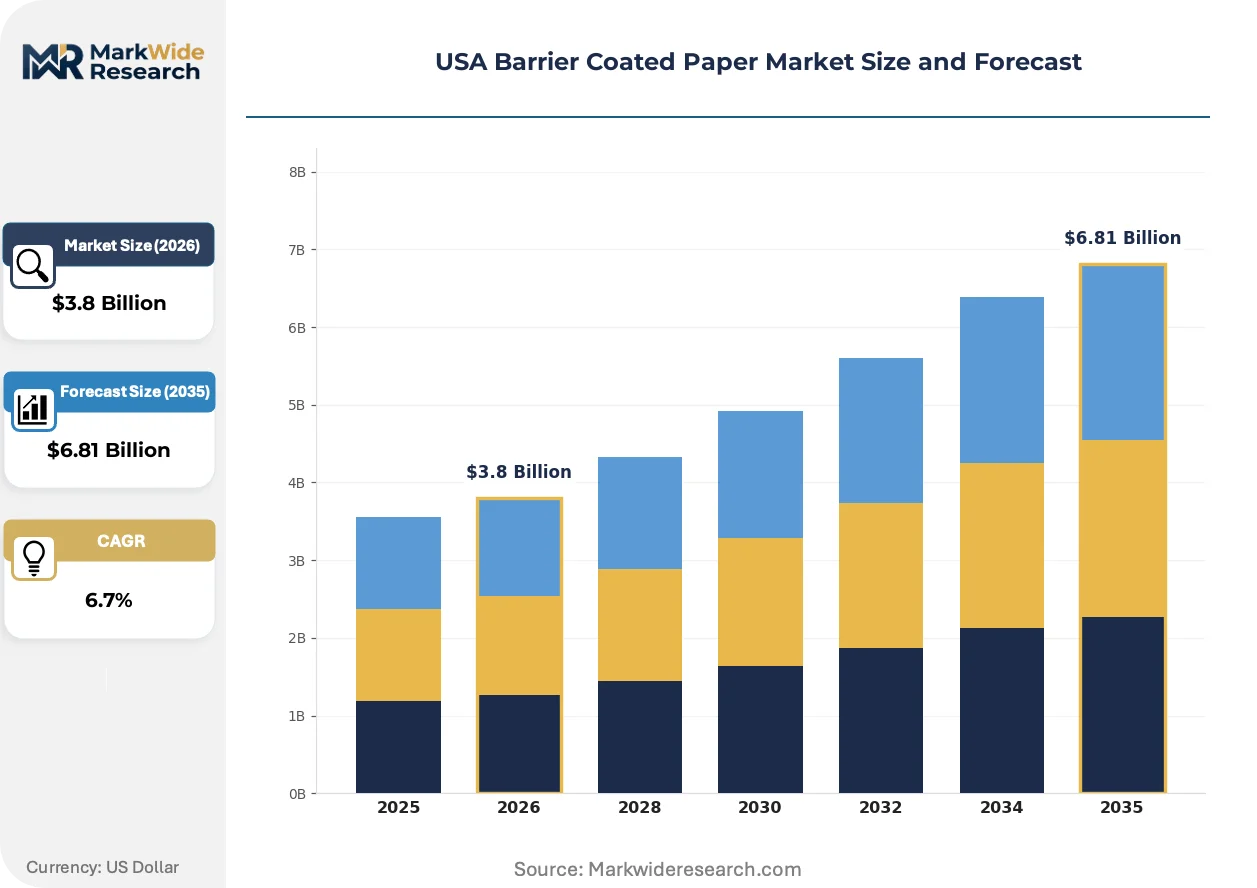
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paperboard, Tissue Paper, Flexible Packaging, Labels End Use Industry: Food & Beverage, Healthcare, Personal Care, Industrial Coating Material: Polyethylene, Wax, Bio-based Coatings, Aluminum Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Cortec Corporation, Dow, Sonoco Products Company, OMNOVA Solutions Inc., Sierra Coating Technologies LLC, Michelman, Inc., Coatings & Adhesives Corp, Cascades Inc., International Paper, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Barrier Coated Paper Market Evolving Landscape
Coating application technology and regulatory chemistry are converging to redefine barrier performance benchmarks while fiber recovery systems adapt to multi-layer structures previously excluded from standard pulping operations.
Inline spectroscopic coat-weight monitoring is automating quality control across polyethylene extrusion lines, enabling real-time thickness adjustment without manual sampling interruption. Frozen food packagers in Wisconsin and Michigan are deploying these systems to reduce barrier material overage from 12% to 4% on high-volume runs. The technology is automating yield optimization that previously required dedicated quality technicians per shift.
EPA enforcement of Maximum Achievable Control Technology standards for hazardous air pollutants is forcing solvent-based coating operations in heavily industrialized Ohio counties toward aqueous system retrofits or facility closures. Converters with legacy solvent lines face seven-figure capital decisions to install thermal oxidizers versus migrating to water-based platforms with inferior grease resistance. Food-contact flexible packaging applications requiring high aroma barrier are absorbing the steepest compliance cost increases.
Brand sustainability scorecards now weight post-consumer fiber content above unit cost in annual packaging supplier reviews, compressing procurement decision cycles from 18 months to 90 days for qualified alternatives. Quick-service chains with 2030 plastic reduction commitments are bypassing traditional RFP processes to direct-award multi-year contracts to converters with verified recycling stream acceptance. This pattern concentrates most visibly in Great Lakes manufacturing corridors where mill proximity reduces logistics emissions tracking requirements.
USA Barrier Coated Paper Market Segmentation
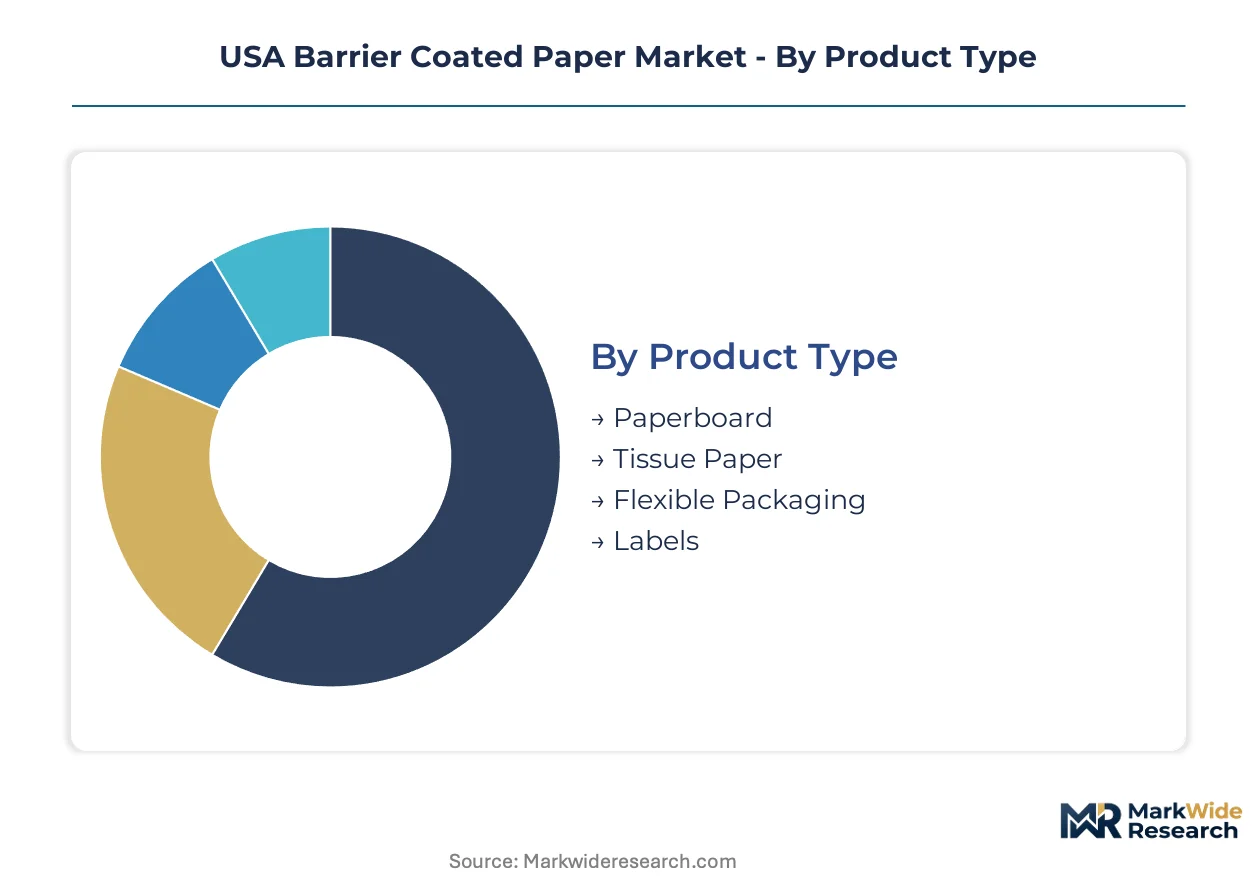
Segmentation in the USA barrier coated paper market reveals how coating technology, substrate selection, and channel strategy combine to determine margin profiles and qualification requirements. Understanding these divides helps converters align capital deployment with the highest-return application clusters.
Product Type:
Upgrade cycles in barrier coated paper track closely with frozen food distribution format changes and quick-service chain sustainability mandates, driving substrate selection toward higher-rigidity solutions.
- Paperboard:Multi-ply fiber construction with extruded polyethylene or aqueous barrier layers delivers structural integrity for frozen food trays and quick-service clamshells. Wisconsin and Michigan mill clusters anchor supply agreements with national restaurant chains converting from expanded polystyrene to fiber-based cold-chain formats under 2030 plastic reduction commitments.
- Flexible Packaging:Lightweight kraft or glassine substrates with thin-gauge barrier coatings serve snack, confectionery, and bakery wrap applications. Downgauging pressure from retail brands limits absolute margin expansion despite steady volume, with converters prioritizing coat-weight precision to minimize material overage.
- Tissue Paper:Low-basis-weight sheets with minimal barrier treatment for interleaving and protective wrapping in industrial food processing. Applications concentrate in protein packaging operations across the Great Lakes manufacturing corridor.
- Labels:Face stock with moisture and grease resistance for direct food contact labeling on chilled and frozen retail packages. Demand ties to private-label grocery expansion in Midwest distribution hubs.
Paperboard sits at the top of the volume ranking, with flexible packaging climbing the fastest as snack brands accelerate plastic-to-fiber transitions.
End Use Industry:
Customer type determines specification tolerance, with food brands accepting tighter qualification cycles than industrial buyers willing to validate novel barrier chemistries.
- Food & Beverage:Primary demand driver spanning frozen entrees, dairy, bakery, and quick-service packaging. FDA food-contact notification requirements govern coating migration limits, while EPA emissions standards push converters toward water-based systems in Ohio River Valley counties.
- Healthcare:Secondary packaging for moisture-sensitive pharmaceuticals including blister card outer wraps and medical device sterilization barriers. Higher specification tolerance and price acceptance than commodity food formats attract specialized converters seeking margin expansion.
- Personal Care:Barrier wraps for soaps, cosmetics, and hygiene products requiring aroma and moisture protection. Brand sustainability scorecards weight post-consumer fiber content heavily in supplier selection.
- Industrial:Grease-resistant interleaving for metal parts and machinery components. Price-sensitive procurement with longer contract cycles and lower barrier performance requirements.
Food and beverage commands the dominant revenue share, while healthcare offers the steepest expansion trajectory as pharmaceutical packaging specifications tighten.
Coating Material:
Margin structure varies sharply by chemistry type, with bio-based systems commanding development premiums despite performance gaps in high-temperature applications.
- Polyethylene:Extruded or laminated fossil-based resin delivering benchmark moisture and grease resistance across frozen food and flexible wrap applications. Gulf Coast petrochemical corridor concentration creates hurricane-season supply risk for Midwest converters dependent on rail-delivered resin.
- Bio-based Coatings:Aqueous dispersions of polysaccharides, proteins, or bio-polymers enabling fiber recovery in standard recycling streams. USDA BioPreferred program procurement mandates create guaranteed demand floor in military and institutional foodservice channels.
- Wax:Paraffin or microcrystalline wax lamination for moisture barrier in corrugated box liners and agricultural packaging. Declining share as recyclability certification complexity favors aqueous alternatives.
- Aluminum:Vacuum-deposited or foil-laminated metallized layers for extreme oxygen and light barrier in retort pouches and pharmaceutical formats. Highest unit cost limits penetration to premium applications.
Polyethylene retains volume leadership, with bio-based coatings gaining share fastest as California, Oregon, and New York extended producer responsibility frameworks create preferential recycling economics.
Distribution Channel:
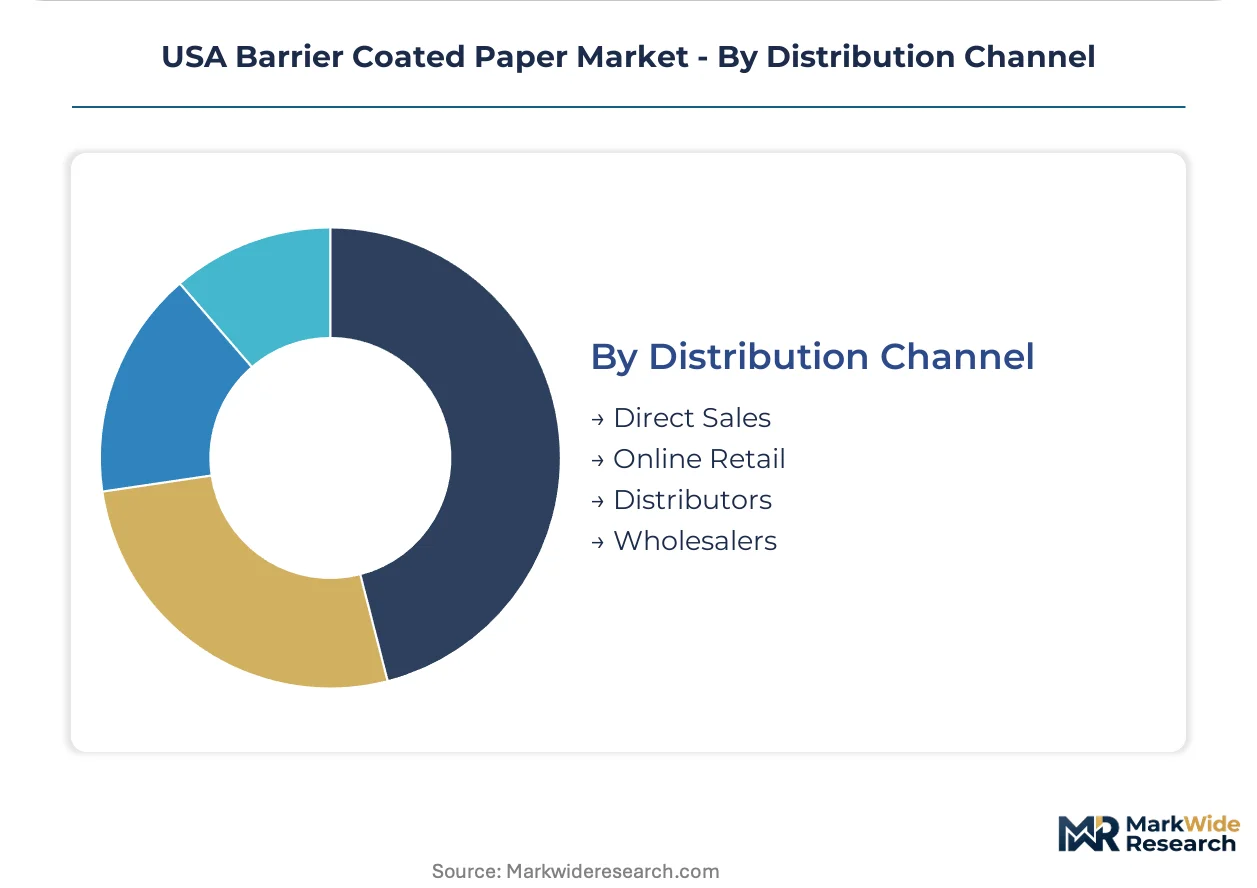
Channel selection reflects order scale and technical service intensity, with national food brands consolidating procurement through direct converter relationships.
- Direct Sales:Long-term supply agreements between integrated mills and national CPG brands or quick-service chains. Technical collaboration on coating formulation and recycling stream validation accompanies volume commitments.
- Distributors:Regional inventory stocking for mid-size converters and specialty packaging buyers requiring shorter lead times than mill-direct orders. Concentration in Chicago and Cleveland logistics hubs serving Great Lakes manufacturing corridors.
- Online Retail:E-procurement platforms for standard-grade barrier papers in lower volumes, primarily serving small food processors and craft packaging buyers.
- Wholesalers:Bulk aggregation of off-grade or discontinued barrier stock for secondary industrial applications with relaxed specifications.
Direct sales anchors the highest revenue concentration, with distributor relationships expanding most quickly as regional converters seek inventory flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Papermaking expertise clusters along the Great Lakes manufacturing corridor, where generations of workforce specialization in fiber processing and coating application anchor the industry's geographic concentration.
Great Lakes Manufacturing Corridor
Frozen food packaging demand from quick-service chains drives volume commitments across Wisconsin, Michigan, and Ohio mill networks. EPA Clean Air Act enforcement in Ohio River Valley counties accelerates converter migration from solvent-based to aqueous coating systems. Wisconsin's Fox River Valley hosts integrated pulp-to-barrier operations serving national restaurant brands converting from expanded polystyrene under plastic reduction mandates.
Southeastern Paper Mill Corridor
Tissue and industrial barrier applications concentrate in Georgia and the Carolinas where bleached kraft capacity serves protein packaging operations. OSHA process safety management rules govern chemical handling at coating facilities across this region. The Savannah-Charleston logistics corridor enables rail-export of barrier-coated board to Latin American food processors.
Ohio River Valley
Underutilized paper machine capacity in Kentucky and West Virginia offers brownfield expansion sites for integrated coating investments. State-level extended producer responsibility legislation in neighboring jurisdictions creates pull-through demand for recyclable barrier formats. Cincinnati and Louisville distribution hubs anchor supply chains reaching Chicago and Atlanta markets within single-day truck hauls.
Pacific Northwest
Bleached softwood kraft pulp production in Washington and Oregon supplies fiber to Midwest converters, though coating operations remain limited by distance from major food-brand headquarters. California's extended producer responsibility framework creates preferential recycling economics that pull brand investment toward fiber-plus-barrier structures. Seattle-area logistics clusters handle import of Asian specialty coating chemicals.
Mid-Atlantic
Pharmaceutical secondary packaging demand for moisture-sensitive drug blister card wraps concentrates in New Jersey and Pennsylvania distribution corridors. FDA food-contact notification requirements govern coating migration limits for barrier papers entering medical supply chains. Philadelphia and Baltimore ports facilitate European coating technology imports serving specialty healthcare applications.
USA Barrier Coated Paper Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Integrated paper manufacturers with captive pulp supply anchor long-term agreements with national CPG brands, while independent coating converters win share through formulation agility and faster qualification timelines. Three archetypes dominate: pulp-integrated mills controlling upstream fiber supply, specialized coating technology licensors, and regional converters serving mid-size food processors. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with brownfield coating line retrofits outpacing greenfield mill construction.
Among integrated pulp-to-paper manufacturers, International Paper exemplifies the captive supply archetype through its Midwest mill network. Dow occupies a position as a materials science anchor for polyethylene and emerging bio-hybrid barrier resin platforms. Sonoco Products Company represents the specialized rigid packaging converter tier, with its focus on temperature-sensitive distribution formats distinguishing its market position.
| Leading Market Players |
|---|
| Cortec Corporation |
| Dow |
| Sonoco Products Company |
| OMNOVA Solutions Inc. |
| Sierra Coating Technologies LLC |
| Michelman, Inc. |
| Coatings & Adhesives Corp |
| Cascades Inc. |
| International Paper |
| Others |
Value Network & Pricing Analysis
Water-based dispersion coating migration across Ohio River Valley mills simultaneously compresses capital expenditure timelines and concentrates supply relationships among converters with installed aqueous capacity. EPA Clean Air Act enforcement drives this dual transformation, rewarding early movers with pricing power over solvent-dependent competitors facing seven-figure retrofit decisions or facility closure.
Pricing Analysis
Coating formulation services bundle with substrate supply under long-term offtake agreements, while unbundled spot transactions concentrate in distributor channels serving mid-size processors. Price differentiation hinges on FDA food-contact certification tier and volume scale, with national quick-service chains accepting premiums for verified recycling stream acceptance. Cost compression in flexible packaging intensifies as downgauging pressure from snack brands squeezes converter margins. Industrial buyers exhibit highest price sensitivity, while pharmaceutical secondary packaging customers tolerate specification premiums for moisture barrier performance.
Supply Chain Analysis
Rail freight economics from Gulf Coast petrochemical corridors to Great Lakes mill networks anchor polyethylene resin distribution costs, with hurricane season disruptions creating spot availability crunches. Supply concentration rests on Wisconsin, Michigan, and Ohio for integrated pulp-to-barrier production, plus Kentucky and West Virginia brownfield expansion sites. Raw material dependencies span northern bleached softwood kraft pulp, polyethylene resin, and bio-based dispersion chemistries. Single-source vulnerability concentrates in Gulf Coast petrochemical infrastructure. Distribution runs through direct mill relationships with national CPG brands, supplemented by Chicago and Cleveland distributor hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory demand engine, with California, Oregon, and New York extended producer responsibility frameworks converting compliance obligations into volume guarantees for fiber-plus-barrier formats.
For Market Incumbents: Extend aqueous coating capacity in Ohio River Valley brownfield sites before EPA enforcement hardens asset stranding risk for solvent-dependent competitors. Deepen captive pulp integration through Midwest mill network densification to defend margin position against resin cost volatility from Canadian lumber harvest cycles. For New Entrants and Emerging Players: Pharmaceutical secondary packaging buyers represent an underserved archetype with higher specification tolerance and price acceptance than commodity food formats. Target moisture-sensitive drug blister card outer wraps through FDA food-contact notification expertise, bypassing saturated quick-service procurement channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters with aqueous coating lines and underutilized paper machine capacity in Kentucky and West Virginia. Long-term viability favors brownfield retrofit plays over greenfield mill construction. Watch USDA BioPreferred program procurement mandate expansion as inflection signal for guaranteed demand floor institutionalization.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Coating Line Retrofit | EPA Clean Air Act compliance converts seven-figure capital decisions into competitive moats for early movers. |
| Captive Pulp Supply Integration | Midwest mill network control insulates converters from northern bleached softwood kraft price swings. |
| FDA Food-Contact Notification Investment | 120-day review window expertise accelerates customer qualification cycles beyond brand sustainability deadlines. |
| Recyclability Certification Partnership | Fibre Box Association and How2Recycle dual validation unlocks preferential extended producer responsibility economics. |
| Pharmaceutical Packaging Qualification | Moisture-sensitive drug blister card wraps offer white-space margin expansion beyond commodity food formats. |
Research Methodology
Direct dialogue with coating facility plant managers, CPG packaging procurement directors, FDA regulatory affairs consultants, and Great Lakes distributor channel partners grounded qualitative findings. Secondary validation drew from EPA enforcement records, USDA BioPreferred program procurement databases, Fibre Box Association technical standards, and railroad waybill data for polyethylene resin movements. Bottom-up mill capacity surveys and top-down food-brand packaging spend estimates were triangulated against customs records for coating chemical imports.
Segment-level value and volume trajectories across the projection horizon reflect disaggregated modeling by coating material chemistry, substrate rigidity tier, end-use industry specification intensity, and regional mill cluster proximity to major distribution hubs. CAGRs were derived from trend extrapolation of coating line utilization rates, pulp cost pass-through elasticity, and regulatory compliance timeline acceleration. Forecast inputs incorporated quick-service chain plastic reduction commitment tracking and extended producer responsibility legislation adoption curves.
Underlying measurement precision varies by segment; paperboard and polyethylene coating combinations carry tighter precision than emerging bio-based dispersion categories with shorter commercial track records. Forecasts reflect assumptions about FDA notification timeline stability and state-level extended producer responsibility implementation sequencing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Bonding Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Insulation Film Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
PET Release Liner Market