
 Bag-In-Box Container Market | 2026-2036
Bag-In-Box Container Market Size, Share, and Industry Trends Forecast 2026-2036
Bag-In-Box Container Market Intelligence
Aftermarket tap and valve replacement revenue is reconfiguring margin pools away from initial box sales toward recurring component demand. Scholle IPN leverages its captive valve manufacturing to capture this service stream, while Smurfit Kappa anchors European corrugated supply through integrated paperboard production. Amcor competes on multi-layer film extrusion scale across beverage and chemical end uses.
A bag-in-box container combines a flexible multi-layer polymer bladder, typically ethylene vinyl alcohol co-extruded with polyethylene, seated within a rigid corrugated or solid fiberboard outer shell, engineered for liquid storage, controlled dispensing, and distribution efficiency. Flexible bags dominate material value given their barrier-layer complexity and replacement frequency, while paperboard boxes sustain margin through structural customization for pallet optimization. Food and Beverage end users lead volume, though Chemicals applications in industrial lubricants and agrochemicals represent the fastest-growing demand pool due to regulatory pressure on drum handling safety.
EPA hazardous material packaging standards and FDA food contact substance regulations in the United States, alongside EU REACH chemical compliance and F-Gas Regulation for refrigerant-adjacent industrial fluids, shape product certification requirements and market access thresholds. Stakeholders must monitor evolving extended producer responsibility frameworks across multiple jurisdictions, as compliance breadth will determine which suppliers retain shelf space with multinational beverage and chemical buyers.
Market Dynamics
Extended producer responsibility frameworks in the European Union and select US states are forcing material redesign cycles faster than equipment amortization schedules, compressing supplier R&D timelines while opening margin pools for recyclable film innovators.
Growth Catalysts
- REACH chemical compliance:ECHA's evolving substance restrictions are accelerating bio-based barrier film development, pulling specialty polymer capacity toward bag-in-box applications ahead of competing flexible formats.
- Wine and juice producers:French and Italian beverage houses are converting bottling lines to bag-in-box filling equipment, drawn by logistics cost reductions and shelf-space efficiency in modern retail formats.
- Agrochemical dispensing:EPA hazardous material packaging standards for industrial lubricants and crop protection chemicals are displacing steel drums with UN-certified bag-in-box systems that reduce handling injury rates.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Barrier-layer resin production clusters in Northeast Asia, exposing converters to freight cost volatility and currency mismatch risks.
- Corrugated fiberboard input costs:Kraft pulp price swings directly compress box margins, particularly for European producers lacking integrated paperboard supply.
- Glass bottle residual preference:Premium wine segments in traditionalist markets maintain format loyalty, slowing complete conversion even where total cost of ownership favors bag-in-box.
Strategic Opportunities
- Indian beverage market:FSSAI food contact regulations are stabilizing, inviting international film suppliers to establish local lamination capacity for juice and dairy applications.
- EU Green Deal packaging mandates:The bloc's 2030 recyclability targets are creating certified-circular material premiums that reward early film redesign investments.
- E-commerce alcohol channels:Direct-to-consumer wine shipping regulations are loosening across multiple US states, favoring shatterproof formats over glass for last-mile delivery.
Industry Challenges
- Multi-layer film separation:Current mechanical recycling infrastructure cannot disaggregate EVOH from polyethylene streams, forcing reliance on emerging chemical recycling partnerships with uncertain scale timelines.
- Valve engineering talent scarcity:Precision molding expertise for aseptic dispensing taps concentrates with a narrow supplier base, constraining aftermarket service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag-In-Box Container Market |
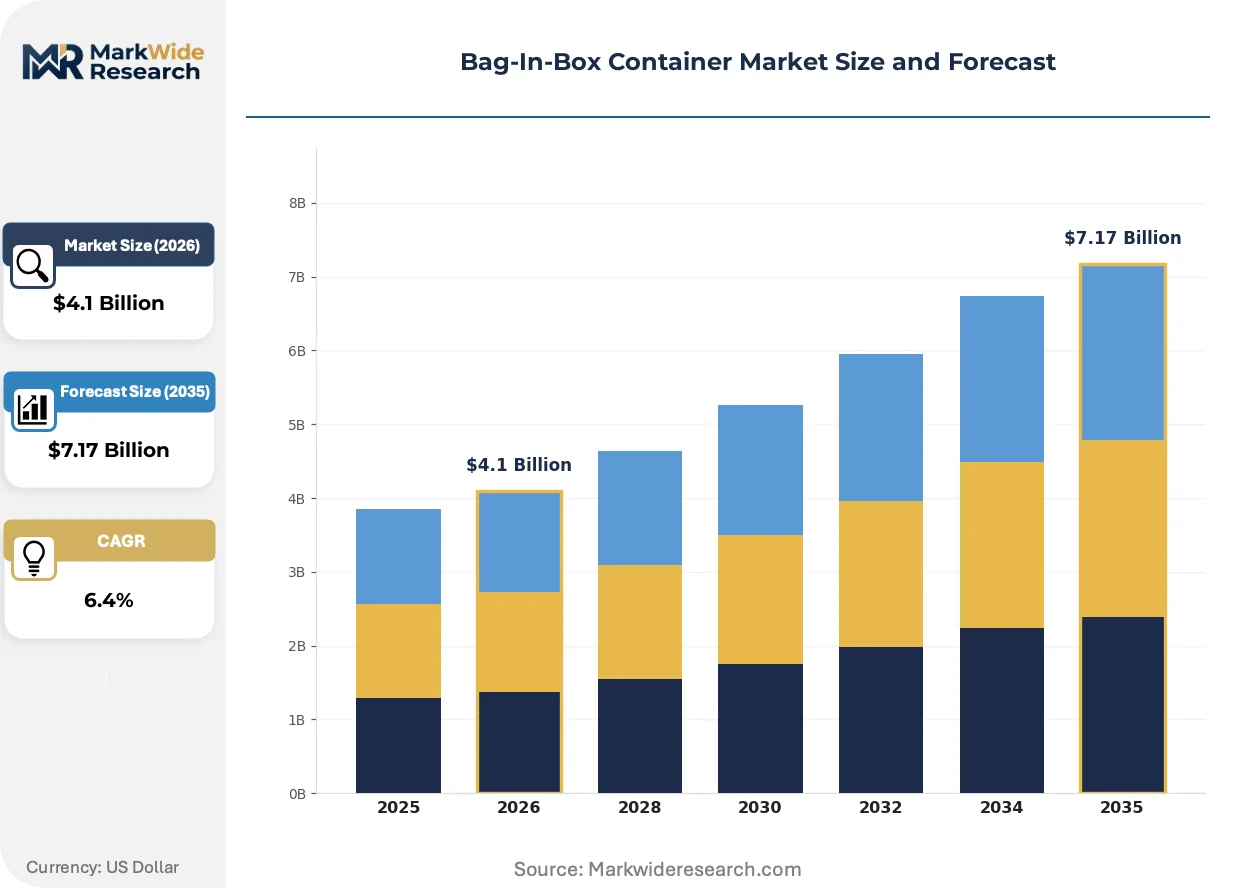
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bags, Boxes, Taps, Valves Material: Plastic, Aluminum, Composite, Paperboard End User: Food and Beverage, Chemicals, Pharmaceuticals, Cosmetics Application: Liquid Storage, Dispensing Solutions, Packaging, Distribution |
| Companies Covered | Scholle IPN, Amcor, Smurfit Kappa, Smurfit Westrock, Mondi, DS Smith, CDF Corporation, Parish Manufacturing, Liquibox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag-In-Box Container Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory compliance automation are converging to redefine competitive advantage, separating film innovators from commodity converters.
Co-extruded film structures with bio-based polyethylene feedstocks are migrating from pilot-scale validation to commercial volume, enabled by Braskem and Neste renewable naphtha supply agreements. North American juice processors are qualifying these films for aseptic filling lines at accelerated pace. The transition is compressing incumbent petroleum-based film margins while rewarding converters with captive biopolymer sourcing relationships.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are spilling over into industrial fluid packaging requirements, as EPA-aligned state programs in California and Washington adopt parallel restrictions. Chemical distributors serving HVAC and industrial cooling sectors must now specify low-permeation bag-in-box systems for alternative refrigerant chemistries. This regulatory cascade is fragmenting product portfolios and extending certification timelines for mid-tier suppliers.
Food service operators are unbundling equipment ownership from consumables procurement, shifting toward dispensing-system leases with minimum volume commitments. This model transfers capex burden to film and valve suppliers while locking in multi-year offtake agreements. The restructuring is most advanced in US institutional catering and quick-service beverage programs, where procurement functions centralize at headquarters level.
Bag-In-Box Container Market Segmentation
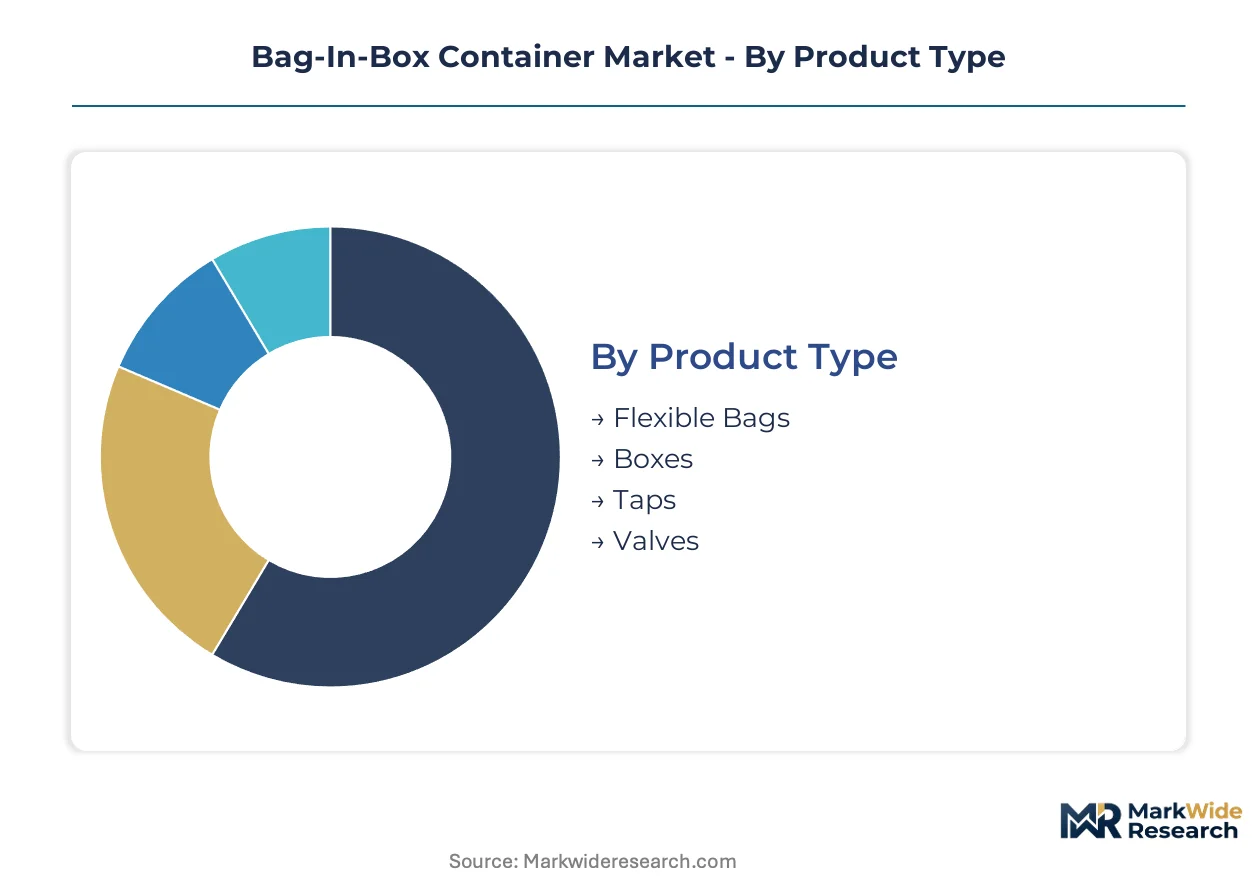
Segmentation in bag-in-box containers reveals how material complexity, regulatory scope, and end-use performance requirements fragment supplier capabilities. Each dimension demands distinct certification pathways and production assets.
Product Type:
Product architecture spans consumable components and durable hardware, with replacement economics driving divergent margin profiles across the installed base.
- Flexible Bags:Multi-layer polymer bladders co-extruded with ethylene vinyl alcohol barrier films provide oxygen and moisture protection for sensitive liquids. French and Italian wine producers are scaling aseptic filling lines for these formats, drawn by logistics cost reductions and shelf-space efficiency in modern retail formats.
- Boxes:Corrugated or solid fiberboard outer shells engineered for pallet optimization and structural protection during distribution. Kraft pulp price swings directly compress margins for European producers lacking integrated paperboard supply.
- Taps:Dispensing mechanisms integrated into bag assemblies for controlled liquid release. Quick-service beverage programs in the United States are centralizing procurement at headquarters level for these components.
- Valves:Precision-molded aseptic dispensing hardware with narrow supplier concentration. Aftermarket replacement revenue is reconfiguring margin pools away from initial box sales toward recurring component demand.
Established volume favors Flexible Bags; emerging adoption favors Valves.
Material:
Material selection tracks regulatory pressure on recyclability and bio-based content, with EU packaging mandates accelerating substitution timelines.
- Plastic:Dominant flexible film substrate spanning polyethylene and EVOH barrier layers. REACH chemical compliance is accelerating bio-based barrier film development, pulling specialty polymer capacity toward bag-in-box applications.
- Aluminum:High-barrier foil laminates for oxygen-sensitive pharmaceuticals and premium cosmetics. Current mechanical recycling infrastructure cannot disaggregate aluminum from polymer streams, forcing reliance on emerging chemical recycling partnerships.
- Composite:Hybrid structures combining polymer films with metallized or paper layers. Agrochemical distributors serving HVAC and industrial cooling sectors must now specify low-permeation composite systems for alternative refrigerant chemistries.
- Paperboard:Rigid outer shell material subject to fiber input cost volatility. Smurfit Kappa anchors European supply through integrated production, insulating against kraft pulp swings.
Plastic commands current volume leadership; Composite materials are climbing the fastest under regulatory pressure.
End User:
End-user segmentation maps to hazard classification regimes, with chemical and pharmaceutical applications imposing UN certification requirements that food and beverage formats escape.
- Food and Beverage:Wine, juice, and dairy applications where FDA food contact substance regulations and FSSAI standards govern material safety. North American juice processors are qualifying bio-based polyethylene films for aseptic filling lines at accelerated pace.
- Chemicals:Industrial lubricants, agrochemicals, and refrigerant-adjacent fluids. EPA hazardous material packaging standards are displacing steel drums with UN-certified bag-in-box systems that reduce handling injury rates.
- Pharmaceuticals:Sterile liquid formulations requiring aseptic barrier integrity. EMA and national regulators enforce extractables and leachables testing protocols that extend qualification timelines.
- Cosmetics:Premium personal care products where shelf appeal and dispensing precision matter. Glass bottle residual preference in premium segments slows complete conversion even where total cost of ownership favors bag-in-box.
Food and Beverage sustains volume concentration; Chemicals is gaining share fastest on safety regulation displacement of traditional packaging.
Application:
Application scope spans static containment through active distribution, with functional requirements determining hardware complexity and service attachment.
- Liquid Storage:Passive containment of bulk liquids in warehouse or in-transit conditions. E-commerce alcohol channels across multiple US states are loosening direct-to-consumer shipping regulations, favoring shatterproof formats over glass for last-mile delivery.
- Dispensing Solutions:Active tap-and-valve systems for controlled portion release. Food service operators are unbundling equipment ownership from consumables procurement, shifting toward dispensing-system leases with minimum volume commitments.
- Packaging:Primary and secondary containment for retail and institutional formats. EU Green Deal packaging mandates are creating certified-circular material premiums that reward early film redesign investments.
- Distribution:Optimized logistics configurations for pallet efficiency and freight density. Ethylene vinyl alcohol supply concentration in Northeast Asia exposes converters to freight cost volatility and currency mismatch risks.
Distribution anchors operational scale; Dispensing Solutions is expanding most quickly through service model restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in France and Italy demonstrate the lowest price elasticity as premium wine houses prioritize barrier performance over unit cost, while Indian juice processors and US institutional caterers exhibit acute sensitivity to per-unit packaging economics.
United States
E-commerce alcohol channels in California and New York are accelerating shatterproof format adoption for direct-to-consumer wine shipping. FDA food contact substance regulations govern multi-layer film qualifications for aseptic juice filling lines. The Pacific Northwest beverage cluster around Seattle and Portland is retrofitting bottling facilities for bag-in-box dispensing equipment.
France
Traditional wine houses in Bordeaux and Champagne are converting heritage bottling lines to bag-in-box formats for export markets. EU REACH chemical compliance through ECHA accelerates bio-based barrier film development among specialty polymer suppliers. The Île-de-France packaging engineering corridor around Paris hosts concentrated valve and tap design expertise.
Italy
Prosecco and bulk wine producers in Veneto and Piedmont are scaling aseptic filling capacity for modern retail formats. Extended producer responsibility frameworks under EU Green Deal packaging mandates force faster material redesign cycles than equipment amortization schedules permit. The Emilia-Romagna industrial belt near Bologna concentrates corrugated box manufacturing with integrated paperboard supply.
Germany
Industrial lubricant distributors in North Rhine-Westphalia are displacing steel drums with UN-certified bag-in-box systems to reduce handling injury rates. EPA-aligned state programs in California and Washington adopt parallel F-Gas Regulation restrictions for refrigerant-adjacent industrial fluids. The Baden-Württemberg automotive supplier network around Stuttgart specifies low-permeation formats for alternative refrigerant chemistries.
India
FSSAI food contact regulations stabilizing in Maharashtra and Gujarat invite international film suppliers to establish local lamination capacity for juice and dairy applications. DGFT import substitution policies favor domestic converter investments over finished packaging imports. The Karnataka beverage processing corridor near Bangalore is qualifying bio-based polyethylene films for tropical climate distribution.
Bag-In-Box Container Market Key Industry Players
Capability concentration sits with specialized valve and film engineers; scale advantage sits with integrated paperboard and multi-layer extrusion operators. The market structures around three tiers: captive converters with backward control over resin supply, independent specialists with precision molding expertise, and corrugated producers leveraging fiber integration. Strategic moves concentrate on biopolymer sourcing partnerships and chemical recycling infrastructure alliances.
Among integrated packaging conglomerates, Smurfit Kappa anchors European corrugated supply through captive paperboard production, while Amcor occupies a position across multi-layer film extrusion scale for beverage and chemical end uses. Scholle IPN exemplifies the specialized tier with captive valve manufacturing that captures aftermarket replacement revenue streams. These three represent distinct archetypes: fiber-integrated structural supply, film-scale barrier production, and precision dispensing hardware.
| Leading Market Players |
|---|
| Scholle IPN |
| Amcor |
| Smurfit Kappa |
| Smurfit Westrock |
| Mondi |
| DS Smith |
| CDF Corporation |
| Parish Manufacturing |
| Liquibox |
| Others |
Cost & Logistics Intelligence
Northeast Asian ethylene vinyl alcohol resin clusters anchor barrier-layer supply, concentrating pricing power with a handful of polymer producers who dictate converter contract terms. This geographic chokepoint amplifies cost pass-through volatility for European and North American bag-in-box manufacturers lacking backward integration into specialty resin production.
Pricing Analysis
Aftermarket valve and tap replacement revenue drives lifetime value extraction beyond initial system sales. Three-tier pricing structure across premium barrier-grade, standard multi-layer, and economy polyethylene tiers separates wine producers in France and Italy from price-sensitive Indian juice processors. Cost compression in standard-grade films is intensifying because Braskem and Neste renewable naphtha agreements are eroding petroleum-based film margins. Premium wine houses in Bordeaux demonstrate the lowest price sensitivity, prioritizing oxygen barrier performance over per-unit packaging economics.
Supply Chain Analysis
Tariff exposure between Northeast Asian resin producers and European converters dominates supply chain risk planning for barrier-layer procurement. EVOH resin production concentrates in Japan, South Korea, and China, while kraft pulp for corrugated shells feeds from Scandinavian and Brazilian fiber markets. Single-source vulnerability in precision valve molding equipment constrains aftermarket service expansion. Distribution runs through beverage co-packer networks and chemical distributor bulk terminals, with last-mile efficiency determining regional converter competitiveness.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aseptic valve engineering expertise has become the scarcest capability in this market, with fewer than a dozen precision molding operations globally qualified for FDA food contact and EPA hazardous material certifications. This talent concentration creates acquisition premiums and constrains aftermarket service scaling for mid-tier suppliers.
For Market Incumbents: Insulate margin pools by deepening captive biopolymer sourcing relationships with Braskem or Neste ahead of EU Green Deal packaging mandate deadlines. Secure exclusive distribution agreements with French and Italian wine houses converting heritage bottling lines, locking out specialty converters lacking integrated film extrusion scale. Prioritize chemical recycling infrastructure partnerships to disaggregate EVOH from polyethylene streams before mechanical recycling mandates tighten. For New Entrants and Emerging Players: Pursue white-space opportunity in Indian juice and dairy applications where FSSAI food contact regulations have stabilized but local lamination capacity remains underdeveloped. Target the Karnataka beverage processing corridor near Bangalore for bio-based polyethylene film qualification partnerships. Lead with dispensing-system lease models that transfer capex burden from food service operators to film suppliers, mirroring the restructuring already advanced in US institutional catering. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated paperboard conglomerates seeking to divest non-core flexible packaging divisions lacking valve engineering expertise. Frame long-term viability around recyclability certification breadth and biopolymer sourcing relationships rather than commodity film scale. Watch for EPA hazardous material packaging standard revisions as the inflection signal that accelerates steel drum displacement in agrochemical and industrial lubricant applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resin Supply | Braskem and Neste renewable naphtha agreements reward early converter commitments with cost advantages over petroleum-based competitors. |
| Chemical Recycling Infrastructure Partnership | Mechanical recycling cannot disaggregate EVOH barrier layers, forcing reliance on emerging pyrolysis partnerships with uncertain scale timelines. |
| Aseptic Valve Engineering Talent Acquisition | FDA food contact and EPA hazardous material certifications concentrate with narrow supplier base, constraining aftermarket service expansion. |
| EU Green Deal Packaging Mandate Compliance | Certified-circular material premiums reward early film redesign investments ahead of 2030 recyclability targets. |
| Dispensing-System Lease Model Rollout | Food service operators in US institutional catering centralize procurement at headquarters level, locking in multi-year offtake agreements. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA food contact substance filings, ECHA REACH substance restriction updates, EU F-Gas Regulation implementation guidance, and SEC 10-K disclosures from integrated packaging conglomerates. Interviews with film extrusion plant managers, wine house procurement directors, agrochemical distributor safety officers, and corrugated box technical sales engineers informed demand-side validation. Bottom-up volume estimates from converter capacity utilization triangulate against top-down addressable market calculations across beverage, chemical, and pharmaceutical end uses.
Forecast inputs span product type segmentation across flexible bags, boxes, taps, and valves; material categories including plastic, aluminum, composite, and paperboard; end-user industries governed by distinct hazard classification regimes; and application scope from passive liquid storage through active dispensing solutions. CAGRs derive from regression analysis of historical volume trends against regulatory implementation schedules and equipment conversion timelines. Bio-based polyethylene adoption curves and extended producer responsibility framework rollout pace represent key industry-specific variables.
Sensitivities concentrate around EVOH resin supply disruptions, kraft pulp price volatility, and mechanical recycling infrastructure buildout delays. Forecasts reflect assumptions about regulatory enforcement consistency and beverage producer format conversion willingness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Trash Bags Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Liquid Packaging Bag Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Portion Bags Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Bin Liners Market