
 Middle East & Africa Paper Bags Market | 2026-2036
Middle East & Africa Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & Africa Paper Bags Market Insights
A capital-intensity divergence between integrated pulp-to-bag operators and merchant converters is reorganizing competitive tiers across the Middle East and Africa. Huhtamaki Group leverages its multi-country manufacturing footprint to sustain supply security for pan-regional retail chains. Gulf East Paper and Plastic Industries LLC anchors its position through captive kraft paper production at its UAE facilities. Hotpack Packaging LLC differentiates via food-grade certification depth for quick-service restaurant supply.
Middle East and Africa paper bags are flexible packaging containers manufactured from kraft, recycled, or coated paper stock, typically featuring bottom-pasted construction with twisted paper handles or gusseted side folds for load stability; they function as primary retail carry vessels and secondary shipping protection for dry goods. Kraft paper grades dominate material selection due to burst strength and printability for branded retail applications. Gusseted bag configurations capture expanding share in e-commerce fulfillment where cubic volume efficiency reduces freight cost per unit. Stand-up pouches remain nascent in the region but attract investment for specialty food exports.
UAE municipal authorities and Saudi Arabia's Saudi Food and Drug Authority shape product compliance through food-contact material standards and import certification requirements. Egypt's Ministry of Trade and Industry enforces local content rules that protect domestic paperboard converters against Gulf competition. Stakeholders must monitor how divergent national plastic restriction timelines across Kenya, South Africa, and Gulf states redirect investment toward paper bag capacity placement.
Market Dynamics
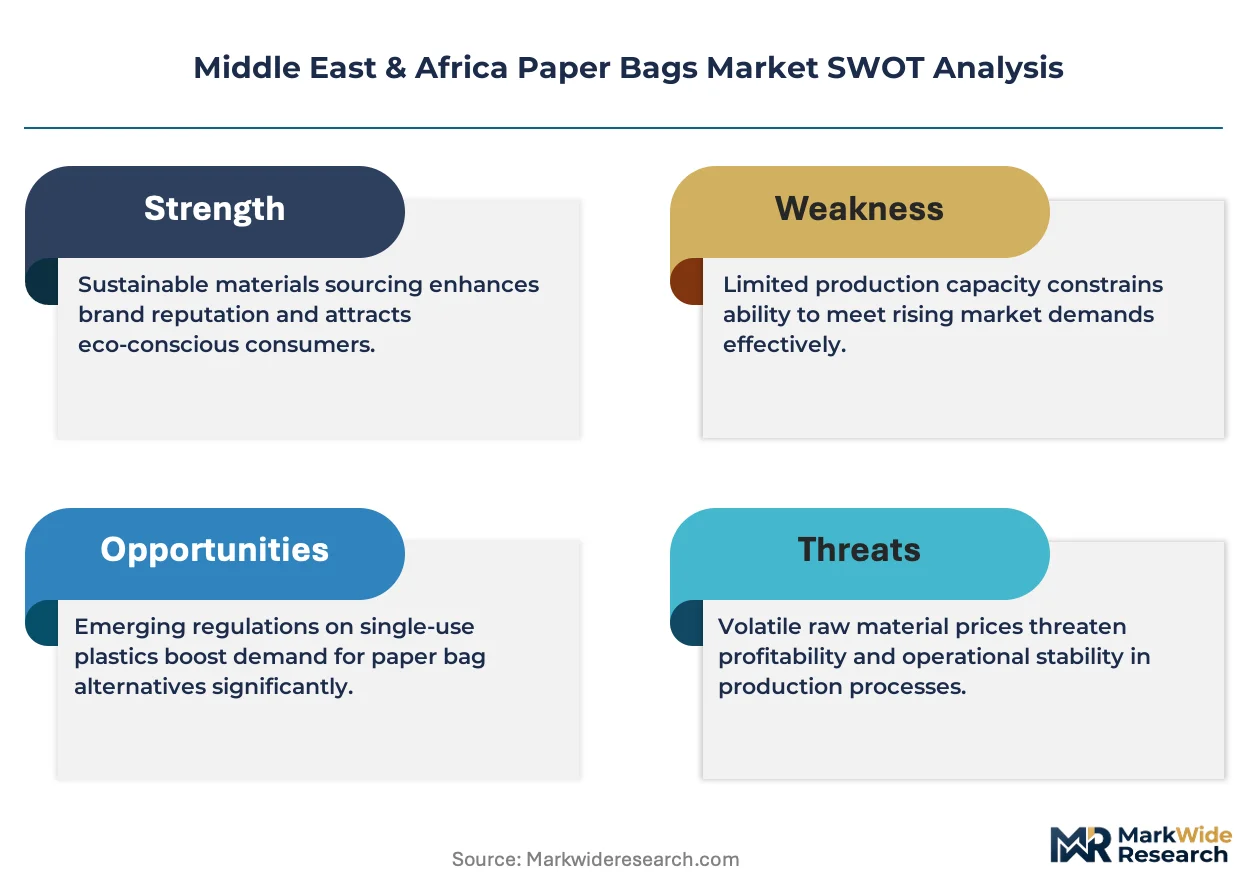
Single-use plastic prohibition timelines across Gulf Cooperation Council states are forcing food service operators to reconfigure packaging supply chains around paper-based alternatives, compressing conversion windows and concentrating demand spikes on regional kraft paper capacity.
Growth Catalysts
- SFDA Food-Contact Standards:Saudi Arabia's tightening material safety requirements for quick-service restaurant packaging are disqualifying non-compliant plastic alternatives and redirecting procurement toward certified paper bag suppliers.
- E-Commerce Fulfillment Expansion:Last-mile delivery operators across the UAE are adopting gusseted paper mailers to replace poly mailers ahead of Dubai's municipal plastic reduction deadlines.
- Bleached Pulp Substitution:Egyptian mills are installing oxygen-delignification systems to produce high-brightness kraft grades without chlorine compounds, unlocking export eligibility to European retail chains.
Market Restraints
- Softwood Pulp Import Dependency:Regional kraft paper production relies on Nordic and Latin American pulp shipments, exposing converters to freight rate volatility and currency mismatch risks.
- Water Scarcity Constraints:Kraft pulping and paper machine operations face production caps during summer months in Saudi Arabia and UAE due to municipal water rationing protocols.
- Competing Flexible Packaging:Stand-up pouches with bio-based plastic films are capturing specialty food export contracts that might otherwise transition to paper-based barrier bags.
Strategic Opportunities
- Kenya's Plastic Ban Enforcement:Nairobi's national environmental regulator is expanding prohibited item lists to include non-woven polypropylene bags, creating import substitution demand for domestically manufactured paper alternatives.
- Quick-Service Restaurant Certification Depth:Pan-regional chains are consolidating supplier panels around vendors holding BRCGS and FSSC 22000 food safety credentials, favoring converters with integrated quality systems.
- Digital Print Integration:Water-based inkjet systems are converging with inline bag converting lines to enable short-run customized retail packaging for seasonal promotional campaigns.
Industry Challenges
- Skilled Technician Shortage:Corrugator and flexo press operation expertise remains concentrated in Egyptian and Turkish training centers, constraining UAE and Saudi capacity expansion timelines.
- Multi-Jurisdiction Certification Complexity:Exporters to Gulf, East African, and North African markets must maintain parallel testing protocols for food-contact migration limits that lack mutual recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & Africa Paper Bags Market |
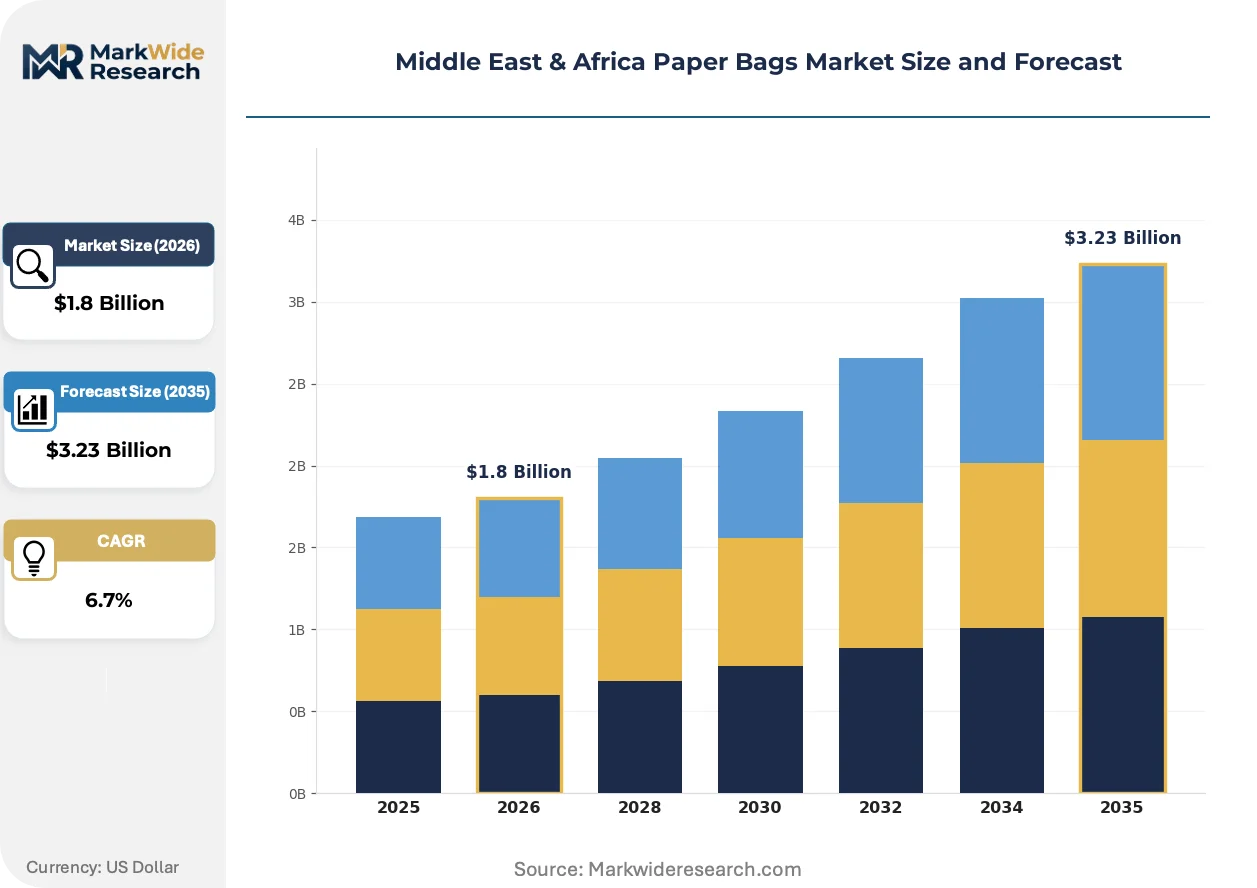
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Stand-Up Pouches, Paper Sacks End User: Retail, Food Service, E-Commerce, Healthcare Material: Recycled Paper, Kraft Paper, Coated Paper, Specialty Paper Distribution Channel: Online, Wholesalers, Supermarkets, Specialty Stores |
| Companies Covered | ENPI Group, Huhtamaki Group, Gulf East Paper and Plastic Industries LLC, Hotpack Packaging LLC, Shuaiba Industrial Company (KPSC), Green Bags UAE, Maimoon Papers Industry, Bag The Future (Pinnacle Enterprises General Trading LLC), W A K S Paper Bags Manufacturing LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & Africa Paper Bags Market Trends and Innovations
Material science advances and regulatory compliance automation are restructuring how paper bag specifications get defined, tested, and deployed across fragmented national markets with divergent implementation calendars.
Barrier coating technology is bifurcating between water-based dispersions and extruded bio-polymers for grease-resistant food service applications. Quick-service restaurant chains in Saudi Arabia and UAE are piloting both approaches simultaneously to hedge against future regulatory restrictions on per- and polyfluoroalkyl substances. This technology divergence is compressing R&D cycles as suppliers must maintain dual qualification pathways for the same end-use specification.
SFDA's 2023 update to food-contact material notification requirements now mandates migration testing documentation at the article level rather than the material level. Egyptian and UAE converters are restructuring quality assurance departments to manage batch-specific test report archives. Small merchant converters without in-house laboratory capabilities are outsourcing to third-party certifiers in Turkey and Germany, extending lead times for new product approvals.
Quick-service restaurant procurement teams are consolidating annual bag contracts around specifications that satisfy the strictest anticipated regulation across their entire operational footprint. Pan-regional chains operating in Saudi Arabia, UAE, and Egypt are standardizing on SFDA-grade compliance even where local rules remain less stringent. This anticipatory standardization is compressing price differentiation between premium-certified and standard-grade suppliers in markets with lagging regulatory timelines.
Middle East & Africa Paper Bags Market Segmentation
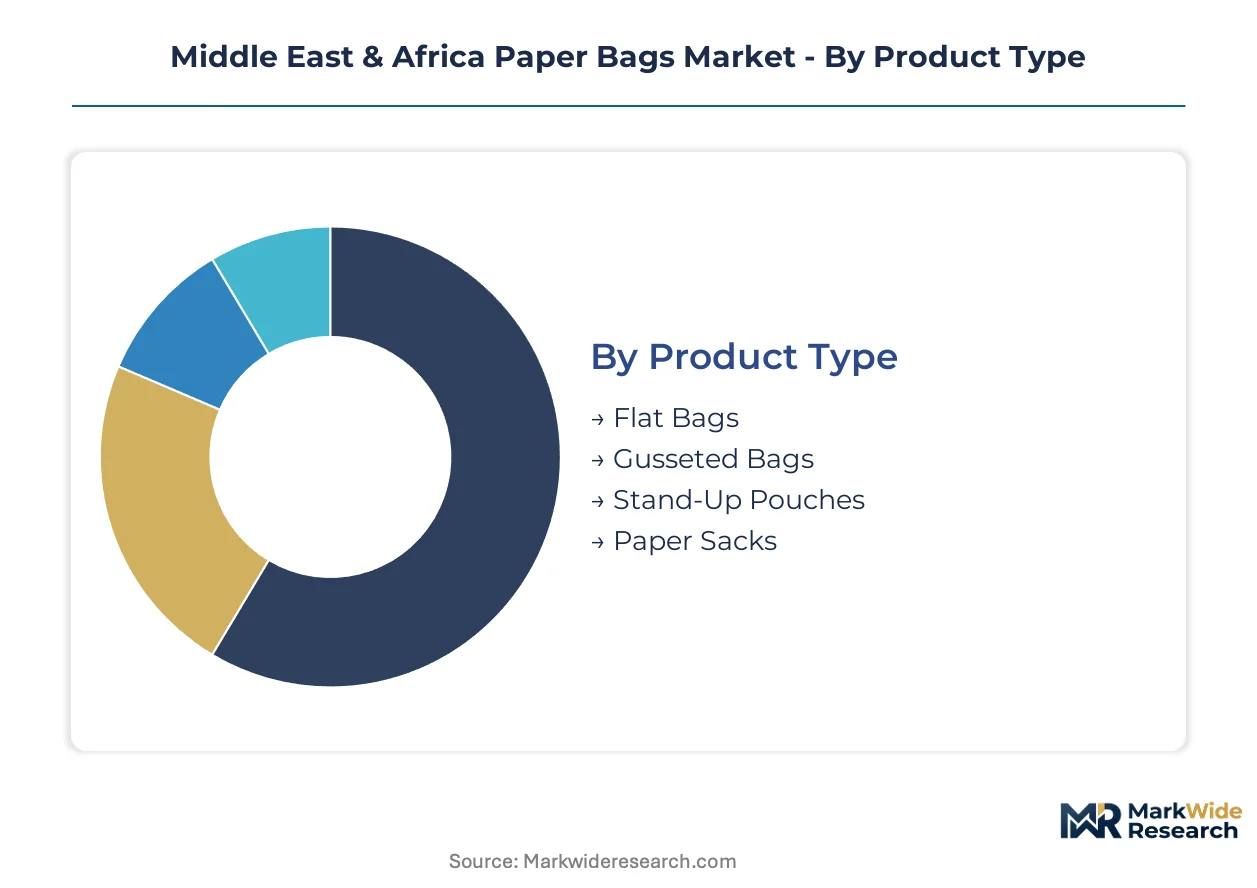
Segmentation in the Middle East and Africa paper bags market reveals how product specifications, material sourcing, and channel access fragment along national regulatory calendars and industrial capacity distribution. Understanding these splits exposes where procurement consolidation and supplier qualification investments concentrate.
Product Type:
Flat bags dominate domestic retail consumption across Egypt and Morocco, while gusseted configurations serve export-oriented e-commerce fulfillment from UAE logistics hubs.
- Flat Bags:Simple rectangular construction with twisted paper handles serves conventional retail carry applications. Egyptian supermarkets and Moroccan souk vendors absorb volume for daily commodity packaging, constrained by price sensitivity that limits premium coating adoption.
- Gusseted Bags:Side-fold expansion increases cubic capacity for irregular or bulky items. UAE last-mile delivery operators and Saudi quick-service restaurant chains specify these for fry carton and bakery box containment ahead of municipal plastic restriction deadlines.
- Stand-Up Pouches:Bottom-gusseted flexible format with resealable closures attracts specialty food exporters in Tunisia seeking European retail shelf placement.
- Paper Sacks:Multi-wall industrial construction carries cement, flour, and agricultural inputs across East African construction and milling sectors.
Flat bags hold the largest share; momentum sits with gusseted configurations climbing the fastest on e-commerce and food service conversion.
End User:
Cost tier stratification separates commodity-grade procurement in retail from certification-intensive supply to food service and healthcare.
- Retail:Supermarket chains and independent merchants drive volume for standard-grade kraft carry bags. Nigerian and Kenyan retailers prioritize unit cost over barrier performance, sourcing from domestic converters with minimal import content.
- Food Service:Quick-service restaurant operators across Saudi Arabia and UAE mandate grease-resistant coatings and SFDA-compliant migration documentation. Pan-regional chains consolidate supplier panels around vendors holding integrated quality systems.
- E-Commerce:Fulfillment center operators specify gusseted mailers with tear-strip closures for apparel and electronics dispatch. Dubai and Riyadh logistics clusters absorb premium-grade specifications.
- Healthcare:Pharmaceutical distributors require sterile-grade paper packaging for medical device and diagnostic kit containment, with demand concentrated in South African and Egyptian hospital supply chains.
Retail commands the greatest volume; food service exhibits the steepest expansion trajectory on regulatory displacement of plastic alternatives.
Material:
Supply concentration in Egyptian kraft production and Nordic pulp import dependency shape material selection trade-offs.
- Kraft Paper:Unbleached virgin pulp construction delivers burst strength and printability for branded retail applications. Egyptian mills anchor regional supply, with UAE converters importing Nordic softwood pulp for high-performance grades.
- Recycled Paper:Post-consumer fiber content satisfies corporate sustainability procurement mandates. South African and Kenyan retailers specify minimum recycled content thresholds under extended producer responsibility frameworks.
- Coated Paper:Polyethylene or bio-polymer barrier layers enable grease resistance for hot food contact. Saudi quick-service restaurant pilots evaluate water-based dispersion against extruded bio-polymer alternatives.
- Specialty Paper:High-brightness bleached grades and textured finishes serve luxury retail and gift packaging in UAE and Qatar premium retail environments.
Kraft paper dominates volume; specialty grades gain share fastest on premium retail and export packaging differentiation.
Distribution Channel:
Channel access fragments between consolidated wholesale supply to industrial accounts and fragmented retail procurement.
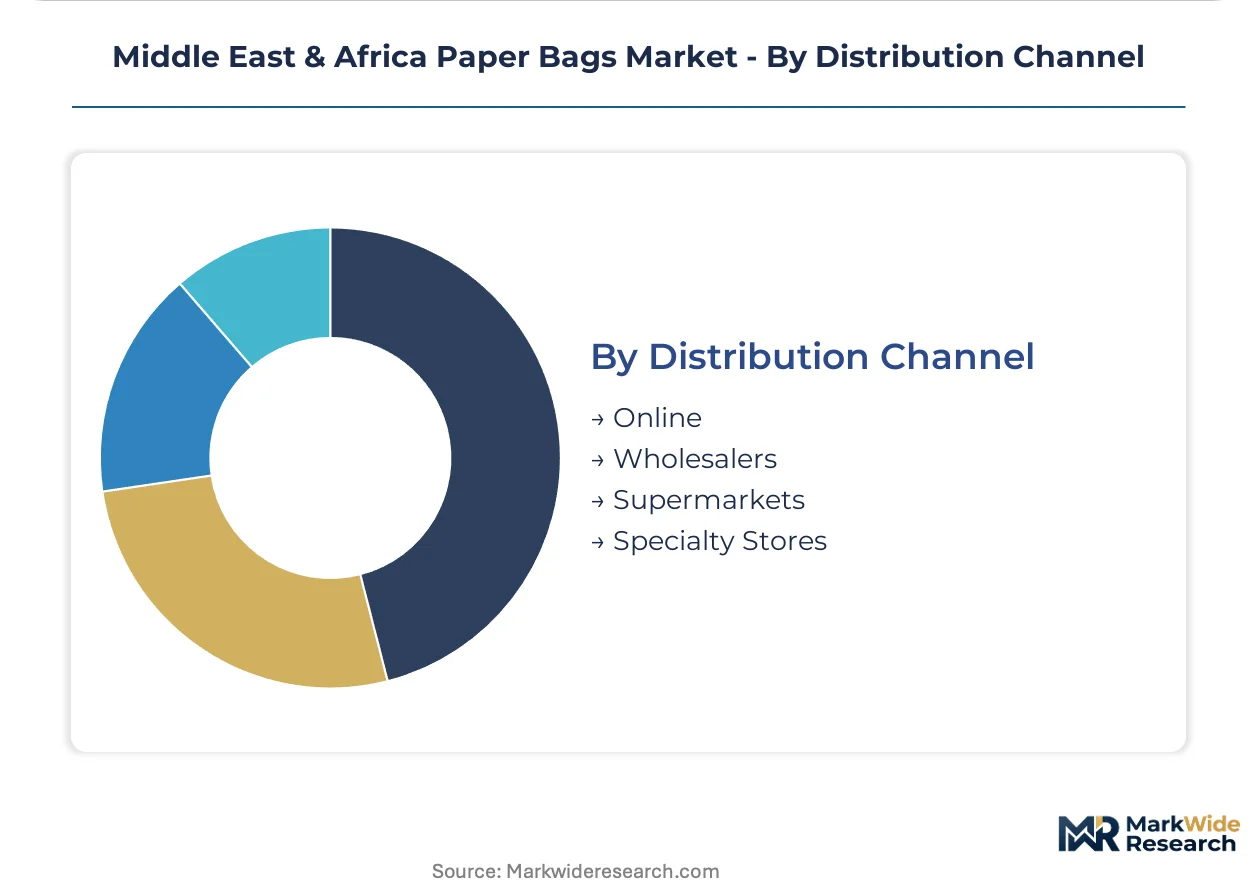
- Wholesalers:Bulk distribution to commercial and industrial end-users concentrates in Cairo, Casablanca, and Johannesburg trading hubs. Merchant converters rely on these intermediaries for market reach into secondary cities.
- Online:B2B procurement platforms serve small and mid-size retailers seeking customized short-run orders. UAE-based digital print converters leverage this channel for seasonal promotional campaigns.
- Supermarkets:Private-label bag procurement by retail chains drives specification standardization across store networks, with Carrefour and Lulu Hypermarket influencing regional grade definitions.
- Specialty Stores:Boutique packaging suppliers serve artisan food producers and luxury goods retailers requiring small-batch customized designs in Beirut and Dubai design districts.
Wholesalers retain the largest share; online channels expand most quickly on digital print integration and short-run customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in UAE and Saudi Arabia where pan-regional chains absorb premium-certified grades, while Egyptian and Moroccan markets compete on unit cost for standard retail specifications.
United Arab Emirates
Dubai's logistics operators and quick-service restaurant chains drive demand for gusseted mailers and grease-resistant food packaging ahead of municipal plastic reduction deadlines. MOHAP enforces food-contact material standards that disqualify non-compliant imports. Jebel Ali industrial zone hosts converting capacity serving GCC-wide distribution networks.
Saudi Arabia
Riyadh-based retail chains and food service operators anchor regional volume for certified paper bag procurement. SFDA's tightened migration testing requirements at the article level force converters to restructure quality assurance systems. Dammam's packaging cluster absorbs investment in barrier coating capacity for hot food contact applications.
Egypt
Domestic supermarkets and North African export markets absorb flat bag volume from Alexandria and Cairo-based converters. The Ministry of Trade and Industry enforces local content rules protecting domestic paperboard manufacturers against Gulf competition. 10th of Ramadan City mills expand oxygen-delignification capacity for high-brightness kraft grades targeting European retail chains.
South Africa
Extended producer responsibility frameworks mandate minimum recycled content thresholds for supermarket procurement in Johannesburg and Cape Town retail networks. National environmental regulators align plastic restriction timelines with East African Community harmonization efforts. Durban's industrial corridor hosts converting capacity serving pharmaceutical and healthcare packaging demand.
Kenya
Nairobi's national environmental regulator has expanded prohibited item lists to include non-woven polypropylene bags, redirecting import substitution demand toward domestic paper alternatives. Municipal enforcement of plastic bans accelerates conversion timelines for informal retail vendors. Mombasa's packaging cluster scales kraft bag capacity to serve East African Community distribution networks.
Middle East & Africa Paper Bags Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa paper bags market. Integrated pulp-to-bag operators command supply security advantages while merchant converters compete on customization velocity and short-run flexibility. The vendor base stratifies around three strategic archetypes: Gulf-based integrated manufacturers with captive kraft production, Egyptian mill-anchored converters serving price-sensitive North African retail, and UAE-based specialists holding pan-regional food-grade certifications. Dominant competitive moves include backward integration into kraft paper production and qualification investments for multi-jurisdiction food-contact compliance.
Among Gulf-based integrated operators, Gulf East Paper and Plastic Industries LLC and Shuaiba Industrial Company (KPSC) exemplify the captive production archetype, while Hotpack Packaging LLC occupies a position representing food-grade certification depth for quick-service restaurant supply chains. Egyptian and UAE-based merchant converters sit within the flexibility tier, competing on digital print integration and seasonal promotional responsiveness.
| Leading Market Players |
|---|
| ENPI Group |
| Huhtamaki Group |
| Gulf East Paper and Plastic Industries LLC |
| Hotpack Packaging LLC |
| Shuaiba Industrial Company (KPSC) |
| Green Bags UAE |
| Maimoon Papers Industry |
| Bag The Future (Pinnacle Enterprises General Trading LLC) |
| W A K S Paper Bags Manufacturing LLC |
| Others |
Pricing and Supply Chain Analysis
Ninety-day kraft pulp inventory cycles at Egyptian mills compress procurement windows for UAE converters and amplify pricing power for integrated operators with captive fiber supply. This lead-time compression intersects with SFDA certification requirements to stratify supplier tiers across the Middle East and Africa.
Pricing Analysis
The customization-premium spread between digital-print short runs and standard flexo volumes reaches three-to-one multiples in UAE food service procurement. Three-tier pricing structure across premium, standard, and economy levels separates BRCGS-certified suppliers from merchant converters and informal domestic producers. Price differentiation hinges on food-contact certification depth and volume scale commitments. Pricing pressure stems from Egyptian mill expansion flooding North African retail with standard-grade kraft. Nigerian supermarket chains exhibit highest price sensitivity; Saudi quick-service restaurant operators absorb premium tiers for compliance security.
Supply Chain Analysis
Inventory positions at Jebel Ali logistics hubs signal demand pulses six weeks ahead of Egyptian mill order books. Geographic supply concentration centers on Egypt, UAE, and Saudi Arabia for converting capacity, with Nordic and Latin American pulp shipments feeding regional kraft production. Raw material dependencies rest on softwood pulp imports, water-based barrier coatings, and food-grade ink formulations. Single-source vulnerability runs through Nordic pulp suppliers exposed to freight rate volatility. Distribution feeds from Cairo and Casablanca wholesale hubs into East African secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where migration testing documentation and batch-level certification archives generate recurring revenue streams expanding faster than base bag manufacturing.
For Market Incumbents: Compound barrier coating qualification depth across water-based and bio-polymer pathways to hedge PFAS regulatory shifts. Defend margin position by anchoring pan-regional quick-service restaurant panels through integrated BRCGS-FSSC 22000 quality systems. Backward integration into oxygen-delignification capacity at Egyptian mill assets locks fiber cost positions against Nordic pulp volatility.
For New Entrants and Emerging Players: Lead with digital print integration for seasonal promotional short runs in UAE retail clusters where established suppliers sacrifice flexibility for scale. Target Kenya's plastic ban enforcement corridor where domestic paper bag capacity lags import substitution demand. Anchor initial penetration through Mombasa-based distribution partnerships serving East African Community networks.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergent national plastic restriction timelines across Gulf and East African states concentrate procurement consolidation around multi-jurisdiction compliant suppliers. Acquisition profiles favor Egyptian mill-anchored converters with untapped Gulf certification pathways. Watch SFDA migration testing requirement expansion into additional food-contact categories as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Production | Captive fiber supply insulates Egyptian mills from Nordic softwood pulp freight volatility. |
| Multi-Jurisdiction Food-Contact Certification | SFDA-grade compliance unlocks pan-regional quick-service restaurant procurement consolidation. |
| Digital Print Platform Integration | Water-based inkjet systems enable short-run customization for UAE seasonal retail campaigns. |
| Barrier Coating Dual-Qualification | Parallel water-based and bio-polymer pathways hedge against future PFAS regulatory restrictions. |
| East African Distribution Expansion | Mombasa hub positioning captures Kenya plastic ban import substitution demand. |
Research Methodology
Cross-validation between mill production data and converter procurement records anchors the qualitative findings across the Middle East and Africa paper bags market. Primary interviews with kraft mill operations directors, quick-service restaurant procurement managers, packaging converter quality assurance leads, and logistics hub inventory planners combined with secondary validation from customs trade records, SFDA regulatory filings, Egyptian Ministry of Trade local content directives, and extended producer responsibility framework documentation. Bottom-up capacity utilization modeling and top-down demand segmentation triangulate volume estimates.
Sensitivity analysis across pulp price bands, certification compliance cost scenarios, and municipal plastic ban enforcement timelines shapes the analytical framework. Segmentation dimensions include product type, end-use vertical, material grade, and distribution channel across the projection horizon. CAGRs derive from fitted trend extrapolation against regulatory event calendars. Modeled inputs incorporate kraft paper machine operating rates, barrier coating adoption curves, and e-commerce fulfillment packaging conversion rates.
The analysis sits within stated boundaries; outcomes outside sustained Gulf Cooperation Council plastic restriction enforcement or Egyptian water scarcity escalation would require recalibration. Forecasts reflect documented assumptions around regulatory implementation cadence and pulp import cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Bag Clips Market
Bags and Containers
Liner Bags Market
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Compression Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
FIBC Market
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Flat Bottom Bags Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Foam Tube Mailer Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Aluminum Beverage Bags Market