
 Bin Liners Market | 2026-2036
Bin Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Bin Liners Market Analytics
North American blown film producers is expanding capacity for high-performance containment films to serve institutional and medical waste streams. Berry Global Inc. leverages vertical integration across resin sourcing and film extrusion to secure cost positions in healthcare-grade liners. Novolex Holdings LLC anchors its competitiveness through controlled distribution into foodservice and retail channels. Reynolds Consumer Products Inc. differentiates via brand strength in consumer-facing segments with odor-control and drawstring innovations.
Bin liners are flexible containment vessels manufactured from polyethylene resins through blown film extrusion, typically ranging from 0.5 to 3.0 mil in gauge, designed to isolate waste from containers and transport environments. The product category spans trash bags, yard waste bags, biodegradable liners, and compostable bags, each engineered to distinct decomposition timelines and load-bearing requirements. Trash bags and yard waste bags in conventional polyethylene remain the mature volume base, while biodegradable and compostable variants represent the fastest-expanding margin pool as municipal organic diversion programs multiply. Material segmentation across polyethylene, HDPE, LDPE, and recycled plastic reflects a structural split: virgin resins dominate industrial and healthcare applications demanding puncture resistance, whereas recycled plastic concentrates in residential and commercial tiers where sustainability specifications tighten procurement criteria.
The EPA regulates landfill-leachate standards that indirectly mandate liner integrity for hazardous and medical waste containment, while FDA guidelines govern material contact safety for healthcare facility applications. OSHA bloodborne pathogen standards further shape product specifications in clinical settings, requiring tear-resistant and sealed-seam constructions. State-level extended producer responsibility frameworks in California and New York are beginning to impose recycled content minimums that will reconfigure supply base qualifications. Stakeholders must monitor how rapidly evolving compostability certifications and patchwork state mandates will fragment product portfolios and test manufacturing flexibility without clear federal harmonization.
Market Dynamics
EU Single-Use Plastics Directive enforcement is fragmenting manufacturing footprints as producers retool extrusion lines for certified compostable resins ahead of 2030 mandates.
Growth Catalysts
- Healthcare containment protocols:OSHA bloodborne pathogen standards mandate tear-resistant sealed-seam constructions in US clinical settings, locking in specialized liner specifications.
- REACH chemical registration:European polymer additive disclosure requirements are accelerating substitution of conventional stabilizers with bio-based alternatives in film formulations.
- Germany municipal mandates:Waste separation ordinances in Bavaria and North Rhine-Westphalia require color-coded liner systems, multiplying SKU complexity and replacement frequency.
Market Restraints
- Resin price volatility:Ethylene feedstock costs tied to naphtha cracking margins swing liner manufacturing economics by 15-20% quarterly.
- Compostable certification backlog:TÜV Austria and BPI approval timelines extending 14-18 months delay product launches for organic waste diversion contracts.
- Mechanical recycling contamination:Multi-layer barrier films containing EVOH or nylon render post-consumer polyethylene streams non-recyclable through conventional sorting infrastructure.
Strategic Opportunities
- India urban sanitation expansion:Smart Cities Mission waste management tenders in Mumbai and Bangalore specify virgin-grade liners for medical and bulk waste containment.
- California EPR frameworks:SB 54 recycled content minimums create first-mover advantage for producers with verified post-consumer resin supply chains.
- Smart liner integration:RFID-tagged containment vessels for hospital asset tracking combine polymer extrusion with IoT sensor partnerships.
Industry Challenges
- Blown film technician scarcity:Specialized die-gap calibration and bubble stability expertise concentrates among aging workforces in Midwest US manufacturing clusters.
- Legacy extrusion retooling:Converting lines from 2.0 mil commodity gauges to sub-1.0 mil compostable films requires screw redesign and cooling tower upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bin Liners Market |
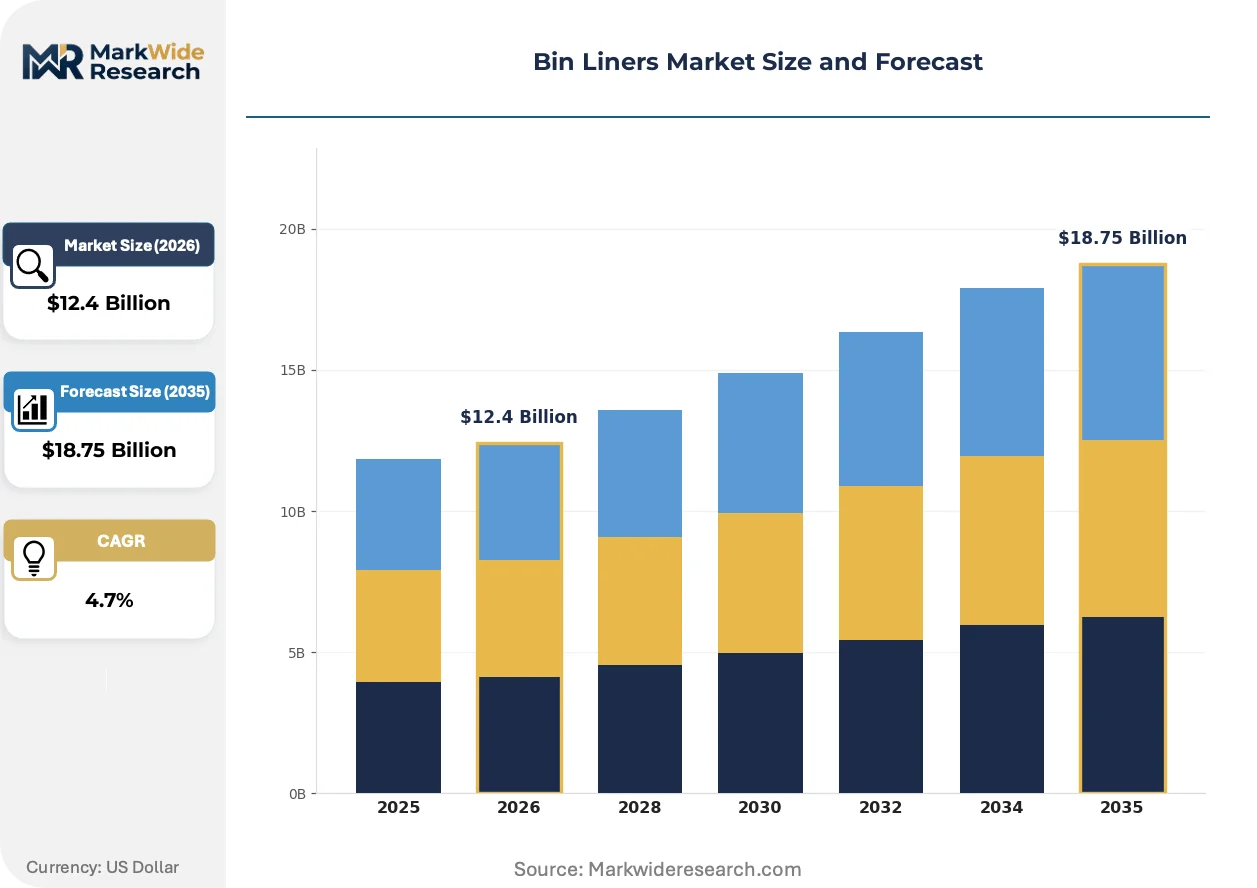
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trash Bags, Yard Waste Bags, Biodegradable Liners, Compostable Bags Material: Polyethylene, HDPE, LDPE, Recycled Plastic Capacity: 10 Gallon, 30 Gallon, 40 Gallon, 55 Gallon Usage: Residential, Commercial, Industrial, Healthcare |
| Companies Covered | Berry Global Inc., Novolex Holdings LLC, Inteplast Group, Reynolds Consumer Products Inc., The Clorox Company, Poly-America L.P., International Plastics Inc., Amcor Plc, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bin Liners Market Evolving Landscape
Material science breakthroughs and regulatory compliance automation are compressing product development cycles while expanding performance boundaries beyond conventional polyethylene capabilities.
PLA-PHA alloy films are absorbing moisture-sensitive applications previously reserved for fossil-based barriers. Hospital systems in Germany and the Netherlands are piloting these formulations for infectious waste containment at 15-20% premium pricing. The technology is absorbing regulatory risk for suppliers facing EU packaging levy escalations.
Extended producer responsibility frameworks in California and New York are forcing batch-level chain-of-custody documentation. Film converters must integrate resin provenance tracking from pellet to finished bag. Healthcare procurement departments are responding by pre-qualifying suppliers with blockchain-verified recycled content certificates.
Direct contracting between municipal waste authorities and compounders is disintermediating traditional distribution layers. France's Citeo eco-organization now specifies liner performance standards in tender documents rather than referencing brand names. This pattern is compressing margin capture for intermediate converters while rewarding resin innovators with formulation IP.
Bin Liners Market Segmentation
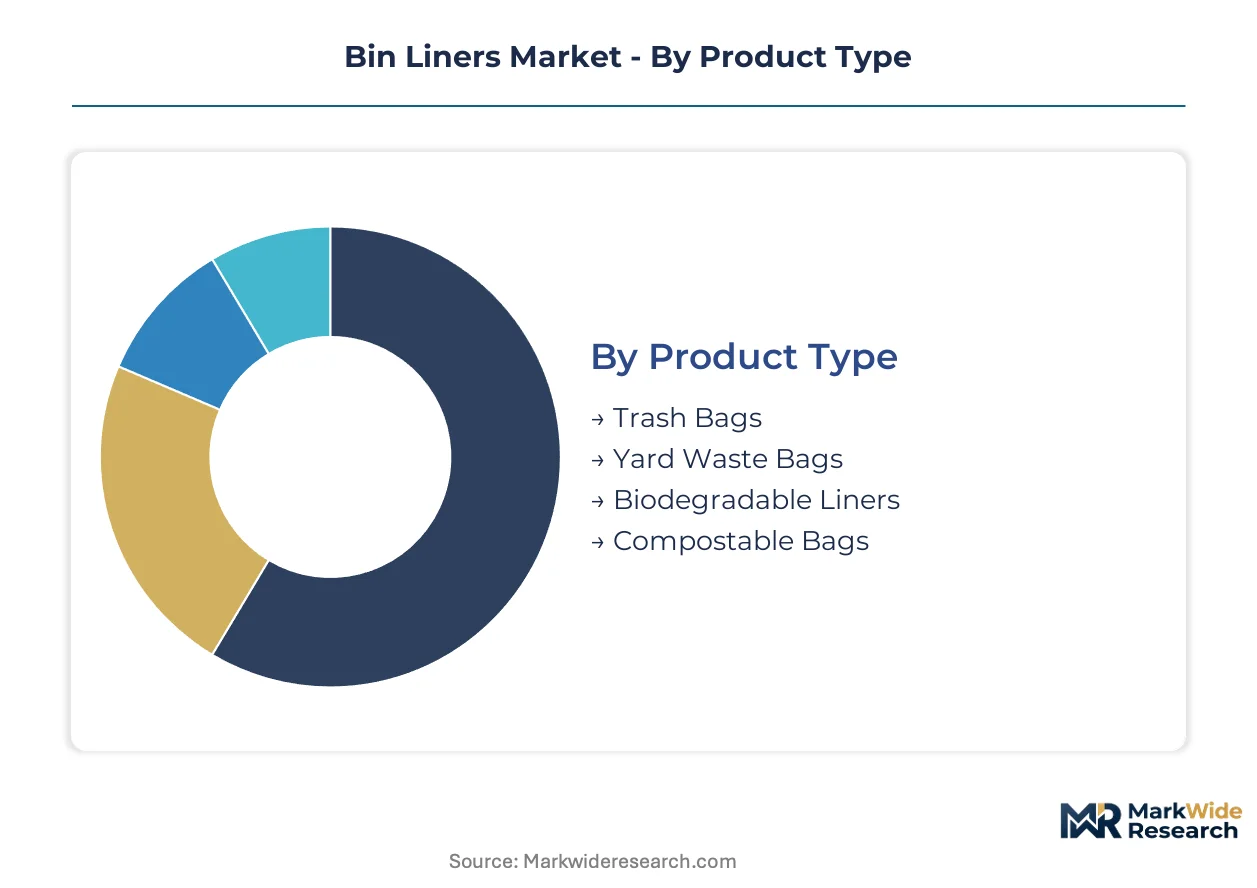
Bin liner specifications fragment across performance grades mandated by waste stream chemistry, regulatory timelines, and load-bearing requirements. Procurement patterns diverge sharply between institutional buyers demanding certified containment and residential channels prioritizing unit economics.
Product Type:
Performance specifications and decomposition timelines define competitive positioning across the four product categories.
- Trash Bags:Conventional polyethylene formulations dominate institutional procurement for general waste containment. Demand concentrates in US healthcare systems where OSHA bloodborne pathogen standards require tear-resistant sealed-seam construction for infectious material isolation.
- Compostable Bags:Certified biodegradable films engineered to municipal organic diversion timelines command premium positioning. Germany's Citeo eco-organization now embeds performance standards directly into tender specifications, disintermediating brand-based procurement.
- Yard Waste Bags:Heavy-gauge polyethylene designed for abrasive organic loads and seasonal volume spikes. Landscaper contractors in France and Belgium drive replacement frequency through spring and autumn collection peaks.
- Biodegradable Liners:Oxo-degradable and hydro-biodegradable variants targeting markets with fragmented composting infrastructure. BIS certification requirements in India are filtering substandard imports from regional supply chains.
Mature deployment sits with Trash Bags. Newer deployment is concentrated in Compostable Bags.
Material:
Resin selection maps directly to load-bearing requirements and regulatory compliance trajectories across end-use tiers.
- Polyethylene:The baseline resin family spanning linear low-density through metallocene-catalyzed grades. Blown film extruders in the US Midwest anchor capacity for healthcare-grade specifications demanding puncture resistance above 500 grams per ASTM D1709.
- Recycled Plastic:Post-consumer and post-industrial polyethylene streams reprocessed into film for residential and commercial tiers. California SB 54 mandates are accelerating batch-level chain-of-custody documentation from pellet to finished bag.
- HDPE:High-density formulations for rigid container matching and moisture barrier applications. German municipal waste separation ordinances require color-coded HDPE liners for recyclables streams in Bavaria and North Rhine-Westphalia.
- LDPE:Low-density grades offering clarity and heat-seal compatibility for retail-branded consumer segments. Drawstring and odor-control innovations differentiate LDPE offerings in US big-box retail channels.
Volume leadership remains with virgin Polyethylene. Recycled Plastic is gaining share fastest as EPR frameworks tighten procurement criteria.
Capacity:
Container matching and handling ergonomics drive gauge and dimension specifications across the four standard volumes.
- 30 Gallon:The residential kitchen standard balancing fill frequency with lifting safety. US retail channels move 30-gallon units in multi-roll packs with scent-blocking additives.
- 55 Gallon:Industrial drum liners and healthcare roll-cart containment requiring 2.0+ mil gauge for puncture resistance. OSHA regulations in US clinical settings mandate 55-gallon sealed-seam construction for regulated medical waste.
- 10 Gallon:Bathroom and office workstation formats optimized for liner change frequency. Japanese commercial building codes specify 10-gallon clear liners for transparent waste auditing.
- 40 Gallon:Municipal outdoor receptacle matching for streetscape and park maintenance. French urban sanitation contracts specify 40-gallon biodegradable liners for food waste diversion in Paris arrondissements.
Replacement velocity peaks with 10 Gallon formats. Margin expansion concentrates in 55 Gallon healthcare specifications.
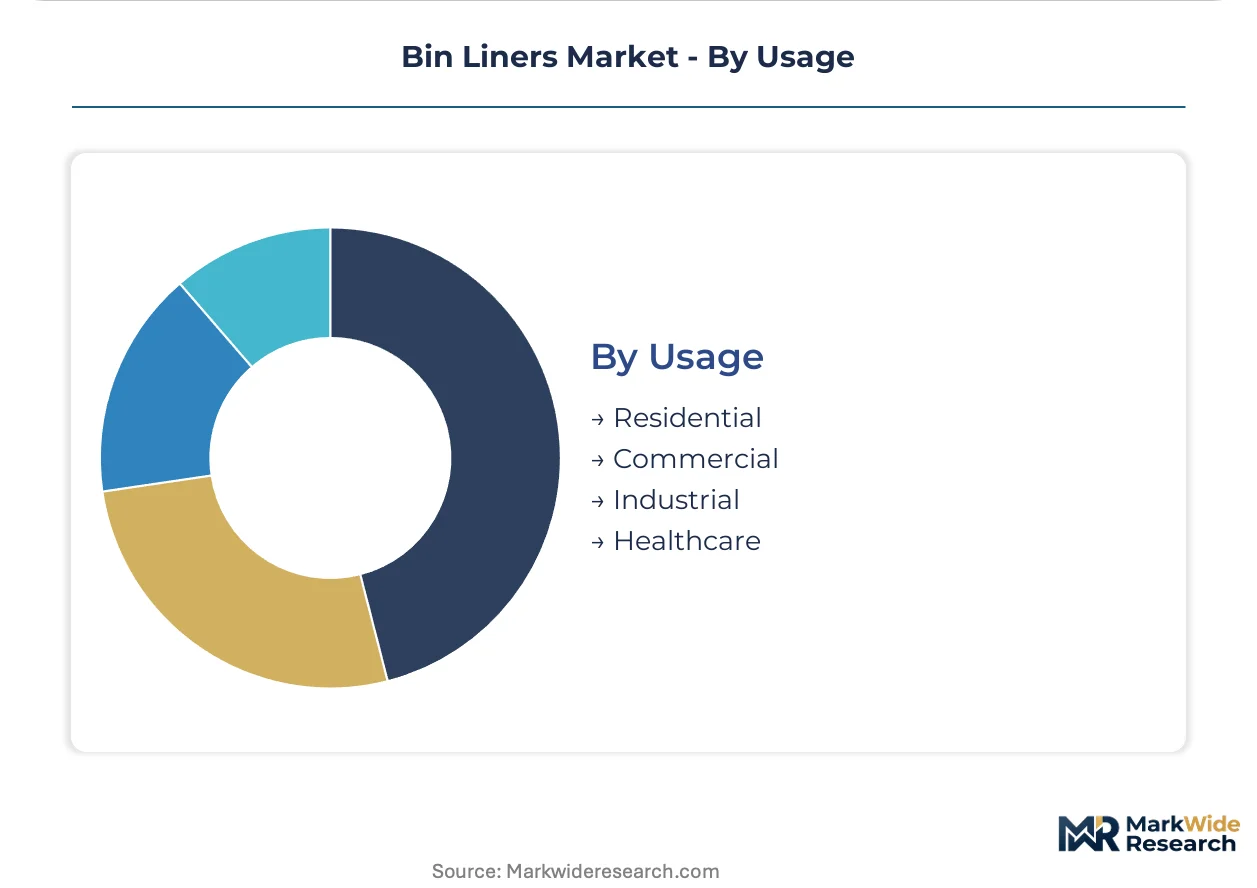
Usage:
End-use segmentation reflects divergent compliance burdens, contract structures, and performance verification requirements.
- Healthcare:Regulated medical waste containment requiring FDA-compliant material contact safety and OSHA-mandated tear resistance. US hospital systems pre-qualify suppliers with blockchain-verified batch documentation.
- Industrial:Heavy-load manufacturing and construction debris containment prioritizing gauge thickness over decomposition properties. India's Smart Cities Mission specifies virgin-grade liners for bulk waste in Mumbai and Bangalore tenders.
- Residential:Price-sensitive consumer channels dominated by private-label and brand-name polyethylene products. Drawstring and odor-control features command 15-20% shelf price premiums in US retail.
- Commercial:Office, hospitality, and foodservice applications balancing unit cost with sustainability signaling. Netherlands healthcare systems are piloting PLA-PHA alloy liners for non-infectious commercial waste at premium pricing.
Specification complexity concentrates in Healthcare. Volume scale sits with Residential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene feedstock availability from Gulf Coast petrochemical complexes anchors North American blown film capacity. European resin transitions accelerate under EU Single-Use Plastics Directive timelines. Asian demand concentrates in urban sanitation infrastructure buildouts.
United States
Healthcare procurement from HCA Healthcare and CommonSpirit Health drives specialized liner specifications for regulated medical waste. OSHA bloodborne pathogen standards mandate tear-resistant sealed-seam construction in clinical settings. Midwest manufacturing clusters in Indiana and Ohio concentrate blown film extrusion capacity for institutional-grade films.
Germany
Municipal waste separation ordinances in Bavaria and North Rhine-Westphalia require color-coded liner systems for recyclables streams. Citeo eco-organization embeds performance standards directly into tender documents rather than referencing brand names. Film converters in Baden-Württemberg retool extrusion lines for certified compostable resins ahead of 2030 mandates.
India
Smart Cities Mission waste management tenders in Mumbai and Bangalore specify virgin-grade liners for medical and bulk waste containment. BIS certification requirements filter substandard imports from regional supply chains. Maharashtra and Gujarat host expanding blown film capacity to serve urban sanitation expansion.
China
Dual carbon goals accelerate substitution of conventional stabilizers with bio-based alternatives in film formulations. GB standards for compostable packaging create compliance benchmarks for domestic producers. Yangtze River Delta manufacturing bases supply PE resin derivatives to Asia-Pacific converter networks.
France
Extended producer responsibility frameworks force batch-level chain-of-custody documentation from pellet to finished bag. Paris arrondissement sanitation contracts specify biodegradable liners for food waste diversion. Île-de-France waste authorities engage in direct contracting with compounders, disintermediating traditional distribution layers.
Bin Liners Market Competitive Landscape
Global majors compete with regional champions across resin sourcing and film extrusion capabilities. The vendor base organizes around three tiers: integrated resin-to-film producers, specialized converters, and private-label distributors. Strategic moves concentrate on backward integration into resin supply and geographic expansion through distribution partnerships. Technology licensing for compostable formulations represents a secondary competitive vector.
Among North American integrated producers, Berry Global Inc. and Novolex Holdings LLC exemplify archetypes of resin-to-film vertical control. Reynolds Consumer Products Inc. occupies a position within consumer-facing branded segments. These three entities represent distinct strategic postures: captive supply chains, channel-anchored distribution, and brand-differentiated retail positioning respectively.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Novolex Holdings LLC |
| Inteplast Group |
| Reynolds Consumer Products Inc. |
| The Clorox Company |
| Poly-America L.P. |
| International Plastics Inc. |
| Amcor Plc |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
Blown film extrusion retooling for certified compostable resins is simultaneously compressing unit economics and concentrating supply among producers with capital reserves for screw redesign and cooling tower upgrades. This technical transition locks out smaller converters while rewarding integrated resin-to-film operations with pricing power in healthcare and municipal procurement channels.
Pricing Analysis
Service bundling separates certified compostable liners with TÜV Austria or BPI chain-of-custody documentation from unbundled commodity polyethylene offerings. Three-tier pricing structure across premium certified compostable, standard virgin-grade, and economy recycled-content levels reflects certification investment and resin provenance verification. Cost compression in standard-grade polyethylene runs through ethylene feedstock volatility tied to naphtha cracking margins. Residential retail channels exhibit acute price sensitivity, while healthcare systems prioritize tear-resistance specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with ethylene feedstock concentration from Gulf Coast petrochemical complexes and naphtha import dependence in European converter networks. Blown film capacity draws from the United States, Germany, and China as anchor production geographies. Raw material dependencies center on polyethylene resins, bio-based PLA-PHA alloys, and post-consumer recycled streams. Tariff exposure on imported resin grades threatens margin stability for non-integrated converters. Distribution runs through municipal waste authority direct contracting, healthcare GPOs, and retail private-label channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized die-gap calibration expertise scarcity among aging Midwest workforces props pricing for institutional-grade liner specifications. This bottleneck limits rapid capacity expansion despite demand acceleration from healthcare containment protocols and EU material transitions.
For Market Incumbents: Lock in backward integration into bio-based resin supply chains ahead of EU Single-Use Plastics Directive enforcement timelines. Secure batch-level blockchain verification systems for post-consumer content documentation to defend against emerging compounders with formulation IP. Prioritize screw redesign capabilities for sub-1.0 mil compostable film production as a technical moat.
For New Entrants and Emerging Players: California SB 54 recycled content minimums open a window for verified post-consumer resin supply chain specialists to penetrate municipal procurement. Target India's Smart Cities Mission waste management tenders in Mumbai and Bangalore with virgin-grade liner offerings for medical waste containment. Pursue direct contracting relationships with urban sanitation authorities rather than layered distribution partnerships.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated resin producers seeking blown film extrusion capabilities. Long-term viability hinges on compostable certification throughput and healthcare-grade sealed-seam construction expertise. Watch TÜV Austria and BPI approval timeline compression as the inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Resins | Captive supply of PLA-PHA alloys secures margin against EU packaging levy escalations. |
| Compostable Certification Investment | TÜV Austria or BPI approval unlocks municipal organic diversion contract access. |
| Healthcare GPO Partnership | OSHA-compliant sealed-seam specifications anchor long-term institutional procurement. |
| Blockchain Provenance Tracking | Batch-level documentation satisfies California SB 54 chain-of-custody mandates. |
| Smart Liner IoT Integration | RFID-tagged containment vessels open hospital asset tracking revenue streams. |
Research Methodology
Document review covered blown film extrusion technical literature, EPA landfill-leachate standards, and EU Single-Use Plastics Directive implementation guidance, complemented by interviews with blown film plant managers, healthcare procurement officers at HCA Healthcare and CommonSpirit Health, municipal waste authority contract managers, and resin compounder R&D directors. Secondary validation drew from customs trade data, SEC 10-K filings of integrated producers, and Citeo eco-organization tender specifications. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Cross-referencing historical blown film capacity utilization against expert panel input on retooling timelines shaped the projection framework. Segmentation dimensions modeled include product type, material grade, capacity specification, and end-use compliance tier across the analysis window. CAGRs derived from resin price elasticity coefficients and healthcare procurement volume trajectories. Key inputs encompassed OSHA bloodborne pathogen standard enforcement intensity and Germany municipal waste separation ordinance rollout pacing.
The model assumes a particular technology adoption path for PLA-PHA alloy films; alternative pathways for fossil-based barrier substitution would alter the outlook for bio-based resin demand. Forecasts reflect assumptions on compostable certification backlog resolution and EU mandate enforcement consistency. Deviation in ethylene feedstock cost volatility or REACH chemical registration timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Global Polypropylene Woven Bags and Sacks Market
Bags and Containers
Pre-Made Bags Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Type-C Bulk Bags Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Slider Bags Market