
 Portion Bags Market | 2026-2036
Portion Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Portion Bags Market Analytics
REACH is realigning polymer formulation costs for European portion bag suppliers. Mondi Group leverages integrated pulp-to-paper operations to sustain margin stability under tightening chemical disclosure rules. Amcor Plc anchors its position through global flexible packaging scale that competes across multiple food safety jurisdictions. WinPak Ltd. differentiates via specialized barrier film technology for extended shelf-life applications.
Portion bags are precision-sealed flexible containers, typically fabricated from polyethylene, polypropylene, or biodegradable films in thicknesses ranging from 0.5 to 3 mils, designed to dispense controlled product quantities in food service, retail, and healthcare settings. Flat bags dominate transaction volumes in quick-serve condiment and single-serve snack applications where cost minimization governs procurement decisions. Stand up pouches represent the fastest-expanding product type as meal kit manufacturers prioritize shelf presence and resealability. Biodegradable films command premium positioning as food service chains face escalating waste diversion mandates across municipal jurisdictions.
The EPA regulates food-contact substance migration limits in the United States, while the EU F-Gas Regulation and REACH framework govern film extrusion chemistry and additive transparency across European supply chains. Health Canada and PMRA enforce parallel food-contact standards that shape cross-border product qualification requirements for North American suppliers. Stakeholders must monitor accelerating divergence between regional compostability certifications and recycling infrastructure capabilities when committing capital to new production lines.
Market Dynamics
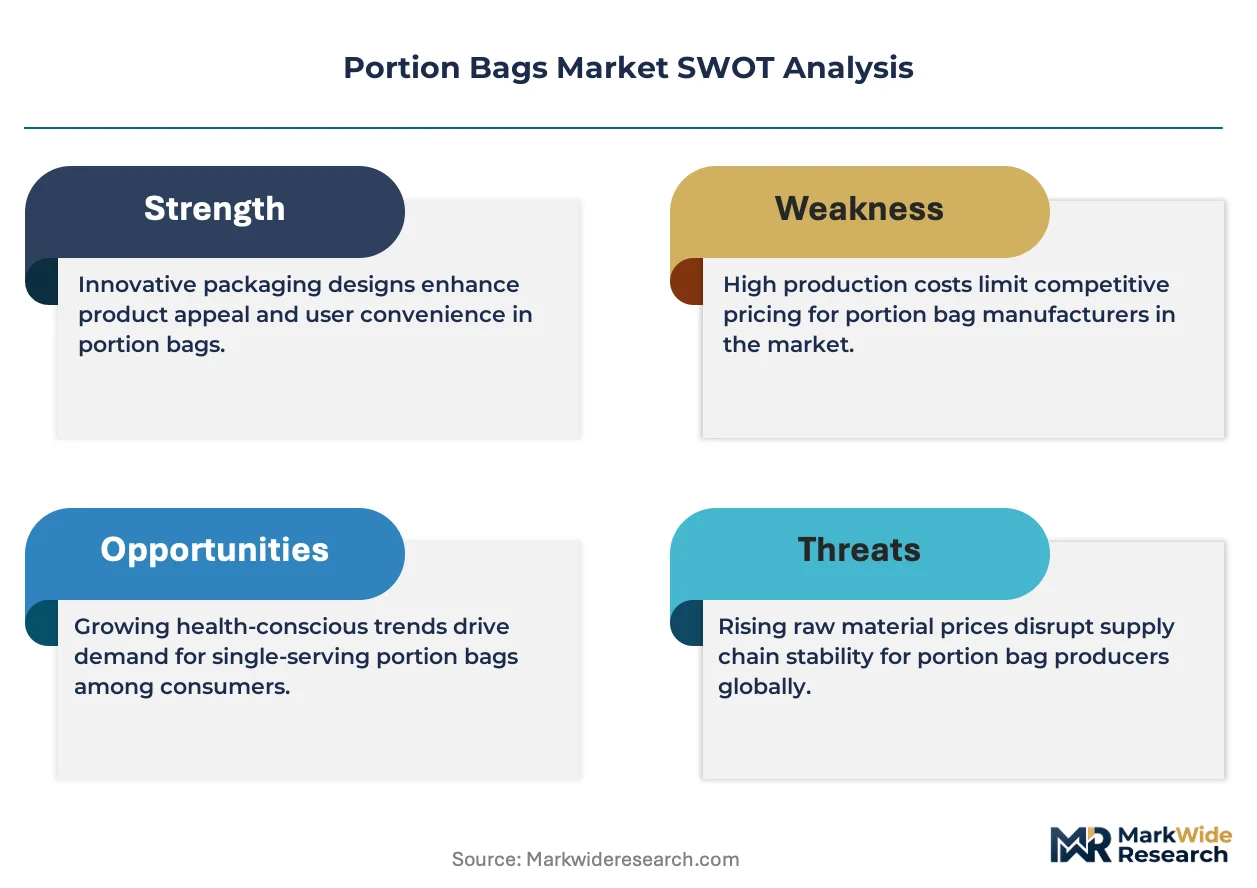
REACH disclosure mandates and EU Single-Use Plastics Directive compliance are restructuring polymer formulation costs and supplier qualification timelines across European portion bag manufacturing, forcing material pivots toward biodegradable substrates and paper alternatives.
Growth Catalysts
- EU Green Deal packaging targets:Mandatory waste diversion timelines are accelerating biodegradable film adoption across quick-service restaurant chains in Germany, France, and Italy.
- Meal kit channel expansion:Resealable stand-up pouch demand concentrates in North American and European subscription food services requiring extended shelf-life barrier properties.
- Quick-service automation:Precision-sealed condiment portion bags integrate with robotic dispensing systems across major fast-food operator networks.
Market Restraints
- Biopolymer feedstock volatility:Corn starch and PLA resin prices fluctuate with agricultural commodity cycles, compressing margins for biodegradable film converters.
- Composting infrastructure gaps:Industrial composting facility scarcity in the United States limits end-of-life value proposition for certified biodegradable packaging.
- Multi-layer recycling complexity:Barrier film laminates containing EVOH or metallized layers face technical rejection from mechanical recycling streams.
Strategic Opportunities
- Healthcare unit-dose expansion:Sterile portion bags for pharmaceutical sampling and diagnostic kit packaging penetrate underdeveloped clinical supply chains in India and Brazil.
- Extended producer responsibility schemes:French and German packaging fee structures incentivize lightweight mono-material designs that simplify post-consumer sorting.
- Digital printing convergence:Variable-data inkjet integration enables short-run customization for regional food brands and promotional versioning.
Industry Challenges
- Food-contact migration testing capacity:Laboratory bottlenecks for FDA and EFSA compliance documentation extend new product qualification timelines by 4-8 months.
- Legacy extrusion equipment retrofit costs:Converting lines from conventional PE to biodegradable film processing requires screw and die modifications averaging substantial capital outlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portion Bags Market |
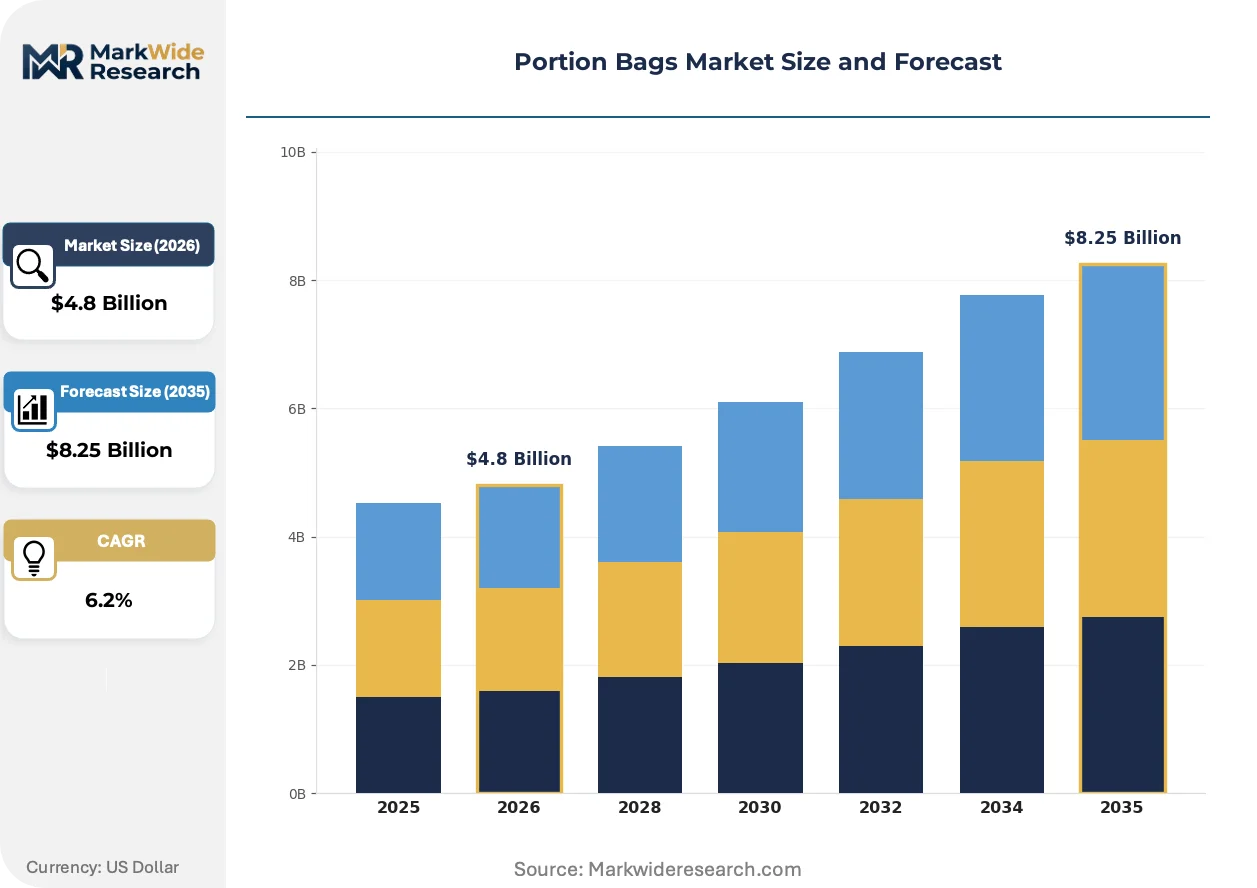
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Zip Lock Bags, Stand Up Pouches, Gusseted Bags Material: Plastic, Paper, Biodegradable Films, Polypropylene End User: Food Service, Retail, Healthcare, Hospitality Application: Snack Packaging, Meal Kits, Bulk Packaging, Condiment Portions |
| Companies Covered | ITD Food Safety, Mondi Group, WinPak Ltd., Prism Pak, Inc., RH Packaging Ltd., Biopac (UK) Ltd, Wegmans Food Markets, Wasserstrom Restaurant Supply, Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portion Bags Market Evolving Landscape
Active and intelligent packaging integration, regulatory chemistry disclosure tightening, and direct-to-consumer channel requirements are simultaneously reshaping material specification, manufacturing transparency, and format flexibility across portion bag supply chains.
Barrier coating technology is modularizing conventional multi-layer film constructions into simplified mono-material substrates with deposited silicon oxide or aluminum oxide layers. European meat and cheese processors adopt these structures to maintain oxygen transmission rates below 1 cc/m²/day while meeting recyclability targets. The shift is compressing converter qualification cycles and reducing inventory SKU complexity for food manufacturers.
REACH Article 33 disclosure thresholds for Substances of Very High Concern are forcing additive transparency across European film extrusion supply chains. Suppliers must now document phthalate, bisphenol, and heavy metal content down to 0.1% concentration levels. Small and mid-sized converters face disproportionate compliance burden relative to integrated pulp-to-paper operators with captive chemical management systems.
Direct-to-consumer meal kit operators are consolidating supplier relationships around vendors capable of simultaneous format flexibility and food safety certification. Buyers now prioritize partners with in-house graphic design, short-run digital printing, and cold-chain distribution validation over pure manufacturing scale. This behavioral pivot favors regional converters with integrated service capabilities over distant commodity producers.
Portion Bags Market Segmentation
Portion bag procurement patterns diverge sharply across format, substrate, and end-use channel, with regulatory pressure and automation requirements fragmenting supplier strategies. Material specification and sealing geometry determine compatibility with filling equipment, shelf-life targets, and waste diversion mandates.
Product Type:
Supply concentration clusters around formats compatible with high-speed automated dispensing systems in quick-service and institutional food service channels.
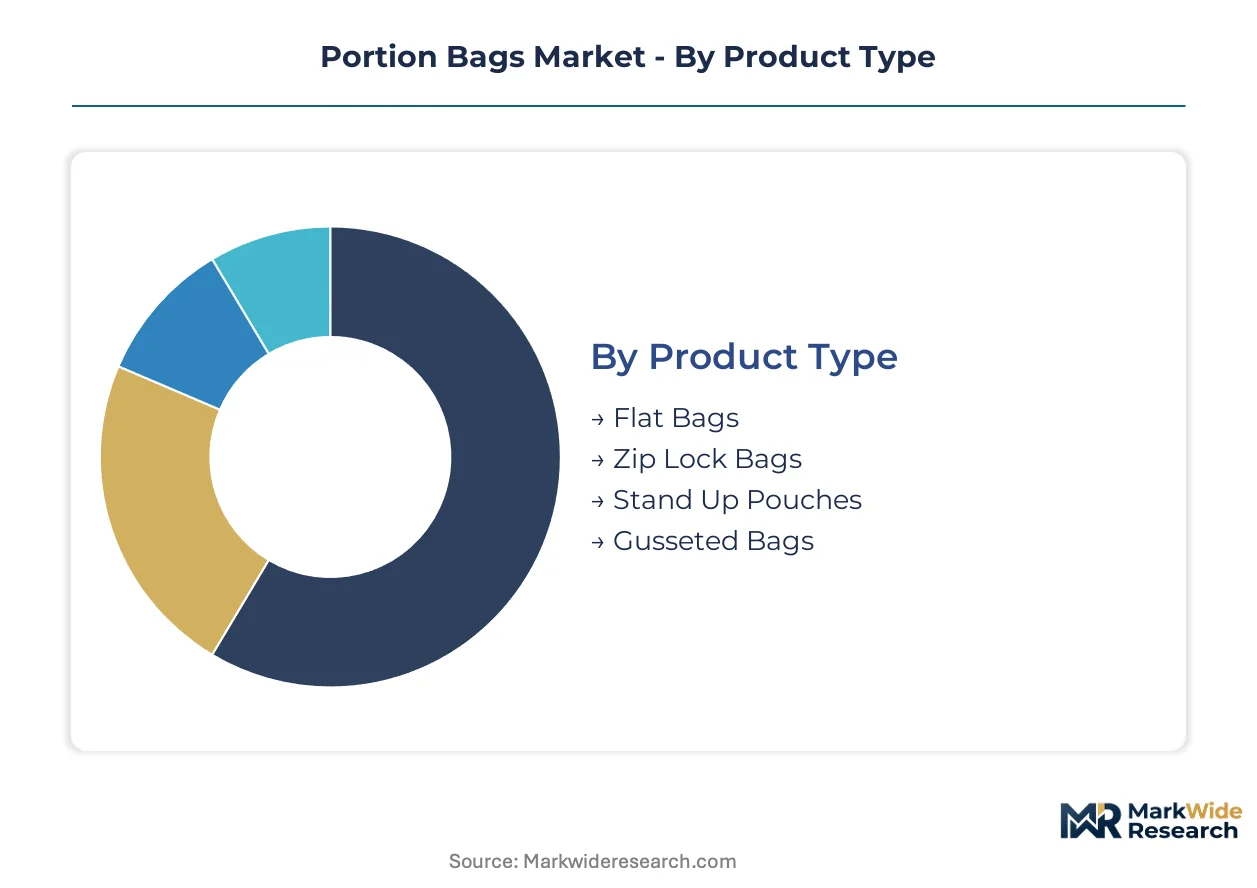
- Flat Bags:Single-web polyethylene or polypropylene constructions, typically side-sealed or bottom-sealed, dominate condiment portioning and single-serve snack applications where cost minimization governs procurement. Demand concentrates in US and German quick-service restaurant chains integrating robotic dispensing infrastructure, though thin-gauge specifications face margin compression from biopolymer feedstock volatility.
- Stand Up Pouches:Multi-layer or mono-material barrier structures with bottom gusset and resealable zipper integration, prioritized by meal kit manufacturers for shelf presence and extended shelf-life performance. North American and European subscription food services drive specification evolution toward recyclable mono-material designs with silicon oxide barrier coatings.
- Zip Lock Bags:Interlocking closure mechanisms laminated to flexible substrates, serving institutional catering and healthcare sampling applications requiring repeated access without contamination.
- Gusseted Bags:Side-pleated constructions expanding to accommodate irregular product geometries, adopted by bulk ingredient suppliers and specialty food processors.
Today's leader: Flat Bags. Tomorrow's challenger: Stand Up Pouches.
Material:
Cost tier stratification separates commodity polymer supply from certified biodegradable alternatives commanding substantial premiums.
- Plastic:Conventional polyethylene and polypropylene films, extruded in thicknesses from 0.5 to 3 mils, retain volume dominance across price-sensitive food service channels. US EPA migration limits and EU REACH disclosure mandates are elevating qualification costs for additive packages, squeezing mid-tier converters without captive resin compounding capabilities.
- Biodegradable Films:PLA, PHA, and starch-based polymers certified to industrial composting standards, positioned for quick-service chains facing municipal waste diversion mandates in France, Italy, and Germany. Corn starch and PLA resin price volatility tied to agricultural commodity cycles compresses converter margins and limits adoption beyond premium-positioned brands.
- Paper:Kraft and grease-resistant substrates with bio-based barrier coatings, advancing in EU markets under Single-Use Plastics Directive pressure.
- Polypropylene:Oriented and cast PP films selected for high-temperature tolerance and moisture barrier in retort and hot-fill applications.
Plastic maintains incumbent advantage. Biodegradable Films are climbing the fastest.
End User:
Application requirements dictate barrier specification, with food safety jurisdiction complexity favoring suppliers with multi-market certification infrastructure.
- Food Service:High-volume quick-service and institutional operators demanding precision-sealed portions compatible with automated dispensing, cold-chain distribution, and rapid inventory turnover. German and US operators are consolidating supplier relationships around vendors with simultaneous format flexibility and FDA/EFSA compliance documentation.
- Retail:Branded and private-label packaged goods requiring shelf differentiation through digital printing and structural innovation, with European extended producer responsibility schemes incentivizing lightweight mono-material designs.
- Healthcare:Sterile unit-dose packaging for pharmaceutical sampling and diagnostic kit components, penetrating underdeveloped clinical supply chains in India and Brazil.
- Hospitality:Single-serve amenity and in-room dining applications prioritizing aesthetic presentation and portion control.
Food Service commands current volume. Healthcare presents steepest expansion trajectory.
Application:
Volume distribution reflects channel automation maturity and shelf-life requirement intensity across food processing segments.
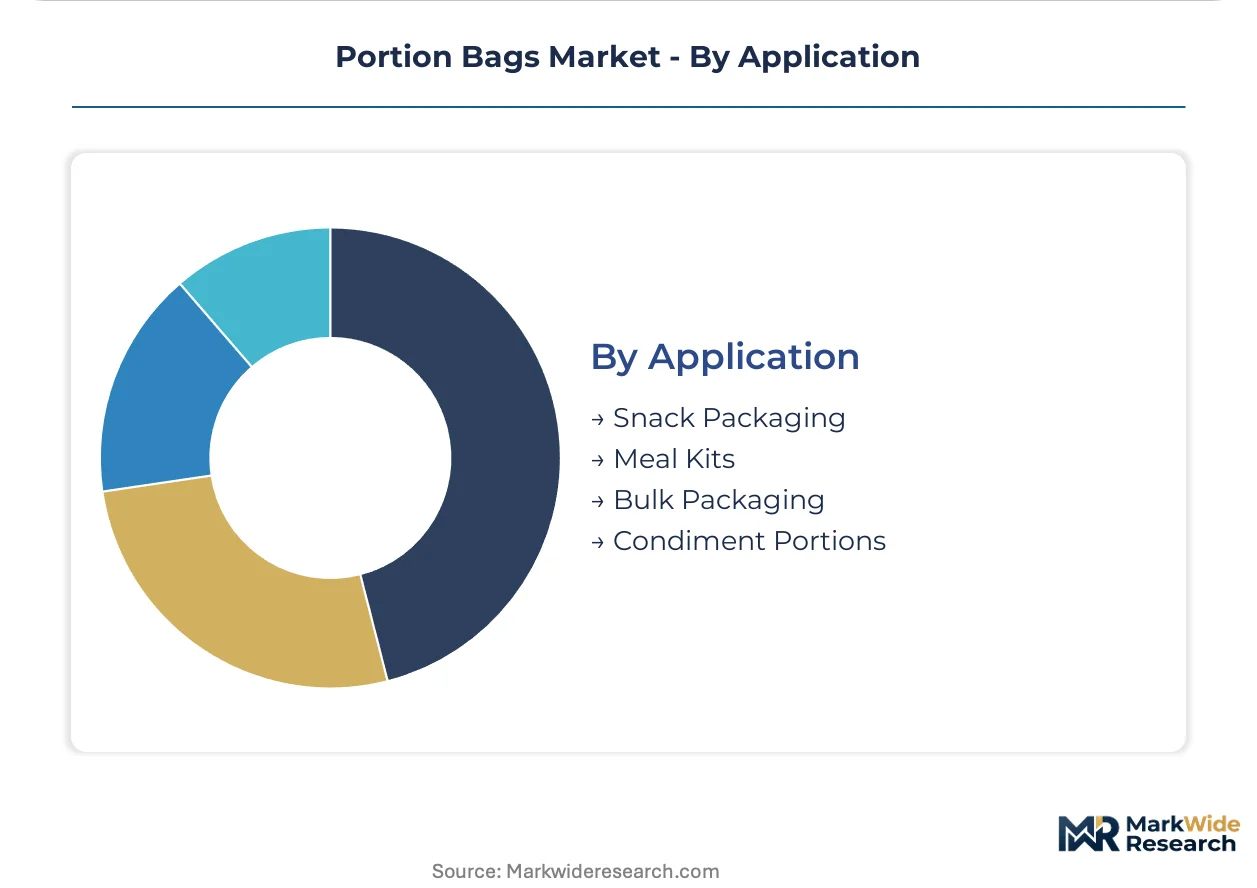
- Snack Packaging:Single-serve portions for vending, convenience retail, and airline catering, with flat bag and small format pouch specifications dominating transaction volumes.
- Meal Kits:Resealable stand-up pouches with high-barrier properties for pre-portioned ingredients requiring 7-14 day refrigerated shelf life, driving North American and European converter investment in digital printing and short-run flexibility.
- Condiment Portions:Precision-sealed flat pouches for ketchup, mustard, sauce, and dressing dispensing, integrating with robotic filling systems across major fast-food networks in the US and Germany.
- Bulk Packaging:Larger format gusseted and pillow constructions for food service ingredient supply and industrial food manufacturing.
Meal Kits anchor growth investment. Condiment Portions defend automation-driven volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer chemists and packaging engineers concentrate in Germany's Rhine-Ruhr corridor, anchoring European film extrusion expertise. German technical universities feed specialized talent directly into flexible packaging R&D centers. This workforce density shapes competitive dynamics across adjacent markets.
United States
Quick-service restaurant automation drives precision-sealed condiment bag demand across major fast-food networks. EPA food-contact substance migration limits govern polymer formulation for domestic suppliers. Chicago and Dallas-Fort Worth host converter clusters serving national distribution networks with FDA-compliant barrier film specifications.
Germany
Central European food manufacturers reconfigure supply chains for EU Single-Use Plastics Directive compliance. REACH Article 33 disclosure mandates force additive transparency down to 0.1% concentration levels. The Rhine-Ruhr industrial corridor concentrates integrated pulp-to-paper operations with captive chemical management systems.
France
Extended producer responsibility fee structures incentivize lightweight mono-material packaging designs. Municipal waste diversion mandates accelerate biodegradable film adoption in Paris and Lyon quick-service channels. The country's national packaging regulator enforces strict post-consumer sorting requirements.
China
Domestic meal kit subscription services expand resealable stand-up pouch specifications for cold-chain distribution. The Ministry of Ecology and Environment advances dual carbon goals that redirect film extrusion investments toward bio-based substrates. Yangtze River Delta converters develop silicon oxide barrier coatings for recyclable mono-material structures.
India
Healthcare unit-dose packaging penetrates underdeveloped clinical supply chains in Mumbai and Bangalore pharmaceutical clusters. FSSAI food-contact standards shape import qualification requirements for multinational flexible packaging suppliers. The country's national pharmaceutical regulator accelerates sterile packaging certification timelines for diagnostic kit manufacturers.
Portion Bags Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material technology and geographic coverage vectors. Market structure shows moderate consolidation with tiered differentiation based on integrated manufacturing depth and regulatory certification breadth. Three archetypes dominate: integrated pulp-to-paper operators with captive resin capabilities, global flexible packaging conglomerates with multi-jurisdiction compliance infrastructure, and specialized barrier film converters serving extended shelf-life applications. Dominant competitive moves include backward integration into biopolymer feedstock sourcing and strategic partnerships with meal kit operators for format co-development.
Within the integrated manufacturing tier, Mondi Group and Amcor Plc occupy positions defined by scale-driven compliance capabilities. Mondi exemplifies the pulp-to-paper archetype with Rhine-Ruhr operational density. Amcor anchors the global conglomerate vector with multi-market food safety jurisdiction coverage. WinPak Ltd. sits within the specialized barrier technology segment, representing precision film engineering for high-performance applications.
| Leading Market Players |
|---|
| ITD Food Safety |
| Mondi Group |
| WinPak Ltd. |
| Prism Pak, Inc. |
| RH Packaging Ltd. |
| Biopac (UK) Ltd |
| Wegmans Food Markets |
| Wasserstrom Restaurant Supply |
| Amcor Plc |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA/EFSA-compliant barrier films and commodity polyethylene constructions manifests in both pricing stratification and supplier qualification timelines across portion bag procurement channels. Premium-tier biodegradable films certified to industrial composting standards command substantial markups over conventional substrates, while supply chain configurations concentrate extrusion capacity in Germany and the United States to service quick-service automation demands.
Pricing Analysis
Bundled service offerings combining digital printing, short-run flexibility, and cold-chain validation separate premium converter relationships from transactional commodity supply. Three-tier pricing structure across certified biodegradable, FDA-compliant barrier, and economy polyethylene levels reflects divergent raw material input costs and compliance documentation burdens. Pricing pressure stems from corn starch and PLA resin volatility tied to agricultural commodity cycles, compressing margins for biodegradable film specialists. Quick-service restaurant chains exhibit highest price sensitivity in condiment portion procurement, while meal kit operators prioritize format flexibility over unit cost minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from major fast-food networks requiring precision-sealed condiment bags compatible with robotic dispensing systems. Raw material supply concentrates in Germany, the United States, and China, with polymer resin compounding anchored in the Rhine-Ruhr corridor and Chicago-Dallas converter clusters. Feedstock dependencies on polyethylene, polypropylene, and agricultural-derived PLA resins expose converters to petrochemical and commodity crop price cycles. Single-source vulnerability in industrial composting infrastructure limits end-of-life value capture for biodegradable film adopters in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portion bag market economics favor margin expansion through mono-material lightweighting and barrier coating substitution that reduces multi-layer complexity. Biopolymer feedstock integration and digital printing service bundling enable premium-tier positioning against commodity polyethylene competitors.
For Market Incumbents: Deepen backward integration into biopolymer feedstock sourcing to stabilize margin exposure against agricultural commodity volatility. Prioritize captive barrier coating technology development to displace EVOH and metallized layer dependencies that complicate mechanical recycling streams. Consolidate supplier relationships with meal kit operators around integrated graphic design and short-run digital printing capabilities. For New Entrants and Emerging Players: Enter via healthcare unit-dose packaging for pharmaceutical sampling and diagnostic kit components in underpenetrated Indian and Brazilian clinical supply chains. Target sterile portion bag specifications requiring FDA and CDSCO compliance documentation that incumbent commodity converters lack capacity to service. Pursue co-development partnerships with regional meal kit brands seeking format innovation without minimum order constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters face disproportionate REACH Article 33 compliance burdens relative to integrated pulp-to-paper operators with captive chemical management systems. Acquisition targets include specialized barrier film converters with silicon oxide coating expertise and multi-jurisdiction food safety certification infrastructure. Watch for inflection signals in municipal waste diversion mandate adoption across US metropolitan jurisdictions that would accelerate biodegradable film demand beyond current premium-niche positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Feedstock | Captive PLA resin supply insulates margin stability against corn starch price volatility. |
| Mono-Material Barrier Coating Adoption | Silicon oxide deposition simplifies recycling streams while maintaining oxygen transmission performance. |
| Digital Printing Service Expansion | Short-run customization capability captures meal kit channel versioning requirements. |
| Healthcare Sterile Packaging Certification | FDA and CDSCO unit-dose validation opens pharmaceutical sampling applications. |
| Extended Producer Responsibility Alignment | Lightweight mono-material designs reduce French and German packaging fee liabilities. |
Research Methodology
Bottom-up food service operator modeling reconciled against top-down film extrusion capacity tracking forms the analytical core of this study. Primary interviews with quick-service procurement directors, flexible packaging plant managers, regulatory affairs specialists at converters, and meal kit supply chain executives combined with secondary validation from FDA food-contact substance filings, ECHA REACH registration databases, EU Single-Use Plastics Directive implementation reports, and trade association statistics from flexible packaging industry bodies. Top-down customs data and bottom-up channel shipment estimates triangulate volume figures across the analysis window.
Historical trendline analysis of segment growth rates calibrated against regulatory milestone timing and automation adoption curves informs projection methodology. Segmentation dimensions modeled include product format, substrate material, end-use channel, application type, and regional regulatory cluster. CAGRs derive from regression analysis of historical volume patterns adjusted for structural shifts in polymer formulation costs and supplier qualification timelines. Forecast inputs incorporate biopolymer feedstock price elasticity and municipal composting infrastructure development trajectories.
The model holds under stable regulatory enforcement intensity and continued quick-service automation investment; deviation in EU Green Deal packaging target acceleration or US industrial composting facility buildout would shift biodegradable film adoption curves. Forecasts reflect documented assumptions regarding REACH disclosure compliance costs and barrier coating technology maturation. Periodic stress-testing of base assumptions is recommended against municipal waste diversion mandate adoption rates and agricultural commodity cycle inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Insulated Delivery Bag Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Drum Liners Market
Bags and Containers
Bin Liners Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Mesh Bags Market
Bags and Containers
Bag Clips Market