
 Self-Sealing Bags Market | 2026-2036
Self-Sealing Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Sealing Bags Market Analytics
Small-batch artisan food producers is collapsing into standardized industrial procurement as retail consolidation accelerates. Sealed Air leverages its captive film extrusion network to control resin cost volatility. Amcor sustains technology leadership through proprietary multilayer barrier platforms. Mondi competes via geographic density across Central European converting facilities.
Self-sealing bags incorporate interlocking zipper profiles, adhesive strips, or slider mechanisms laminated to flexible film substrates, typically 2-6 mil thickness, engineered for repeated access without compromising barrier integrity. Their primary commercial purpose centers on preserving shelf stability while enabling consumer convenience across ambient, chilled, and frozen distribution chains. Stand-up pouches command premium positioning in premium snack and pet food segments where shelf differentiation drives margin capture. Polyethylene dominates volume throughput in bulk industrial applications where cost minimization governs procurement decisions. Biodegradable materials represent the fastest-expanding material category as brand owners face Scope 3 emissions accountability.
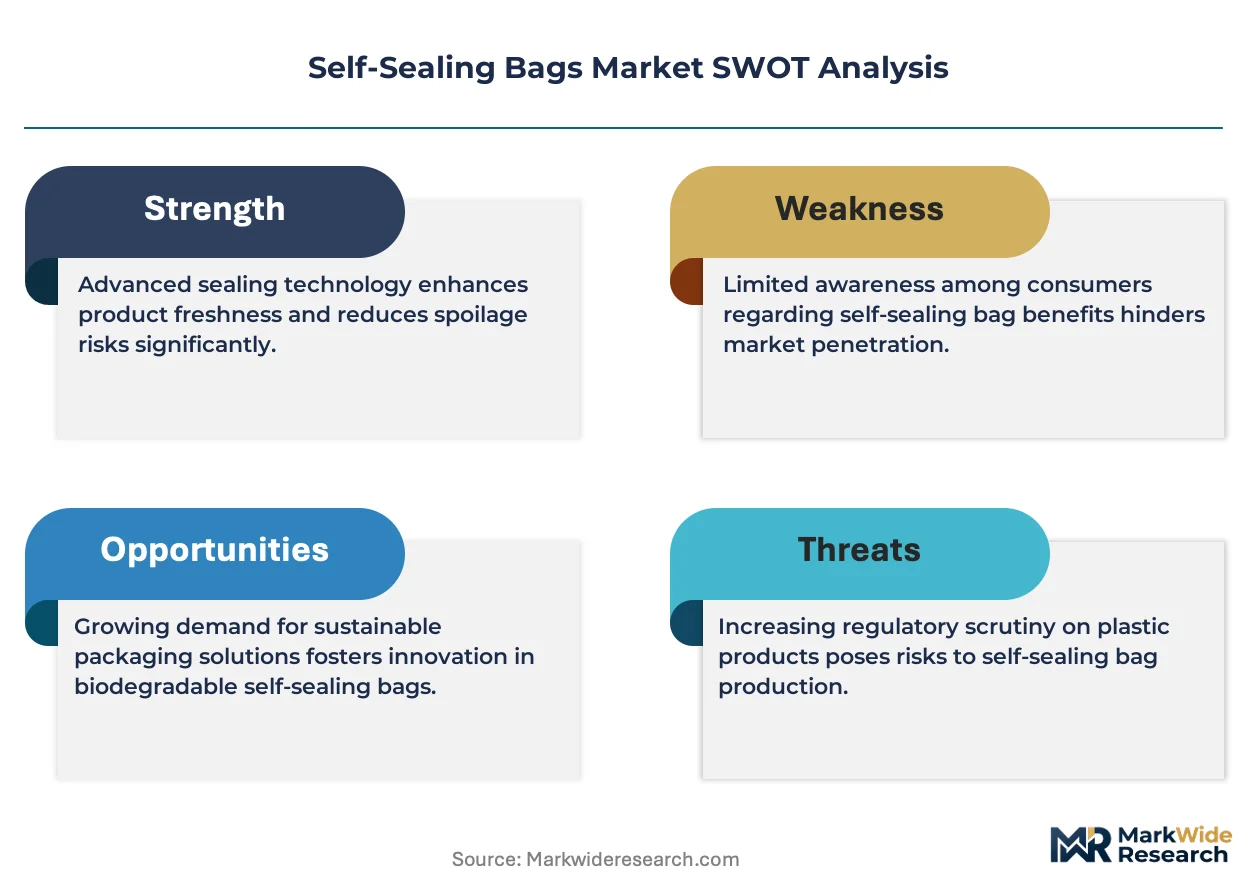
FDA food contact substance regulations govern migration limits for polyethylene and polypropylene layers in US-bound shipments. REACH restricts phthalate plasticizers and mandates SVHC disclosure across European supply chains, directly influencing adhesive formulation choices. The EU Packaging and Packaging Waste Regulation mandates recyclability-by-design standards that zipper-equipped structures must satisfy by specified deadlines. Stakeholders must monitor polymer recycling infrastructure buildout rates to validate biodegradability premium pricing before committing capital to capacity expansion.
Market Dynamics
E-commerce fulfillment centers are consolidating procurement specifications around tamper-evident closure systems, forcing converters to reengineer zipper profiles for automated handling speeds while maintaining barrier integrity across ambient-to-frozen temperature ranges.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability-by-design mandates for zipper-equipped structures are accelerating capital deployment into mono-material barrier platforms across European converting facilities.
- Scope 3 emissions accountability:Brand owners in premium snack and pet food segments are specifying biodegradable substrates to meet net-zero commitments, pulling demand from polyethylene toward compostable alternatives.
- Germany's industrial packaging corridor:Concentrated demand from automotive component suppliers and chemical distributors is sustaining high-volume throughput for 4-6 mil polyethylene bags with slider mechanisms.
Market Restraints
- Resin cost volatility:Polyethylene and polypropylene feedstock prices fluctuate with crude oil derivatives, compressing margin predictability for converters without captive extrusion capacity.
- Adhesive formulation constraints:REACH restrictions on phthalate plasticizers and SVHC disclosure requirements are eliminating legacy adhesive chemistries from European supply chains.
- Polymer recycling infrastructure gaps:Limited industrial-scale collection and reprocessing capacity for multilayer zipper structures is blocking circular economy claims and premium pricing validation.
Strategic Opportunities
- Small-batch artisan food collapse:Retail consolidation is forcing specialty producers into standardized procurement, creating volume aggregation services for regional converter networks.
- Stand-up pouch premiumization:Shelf differentiation in chilled ready-meal segments is commanding margin capture through high-clarity barrier films with resealable pour spouts.
- Biodegradable material innovation:PLA and PBAT blends with home-compostable certification are opening positioning in municipal organic waste collection systems across Nordic markets.
Industry Challenges
- Multilayer coextrusion expertise shortage:Skilled technicians capable of calibrating 5-7 layer barrier structures with zipper integration are concentrated among legacy packaging engineers nearing retirement.
- FDA food contact migration testing:Validation timelines for new adhesive-to-film lamination combinations extend qualification cycles for US-bound shipments.
- Legacy equipment retrofit costs:Existing form-fill-seal lines require mechanical modifications to handle slider-equipped pouches at automated fulfillment speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Sealing Bags Market |
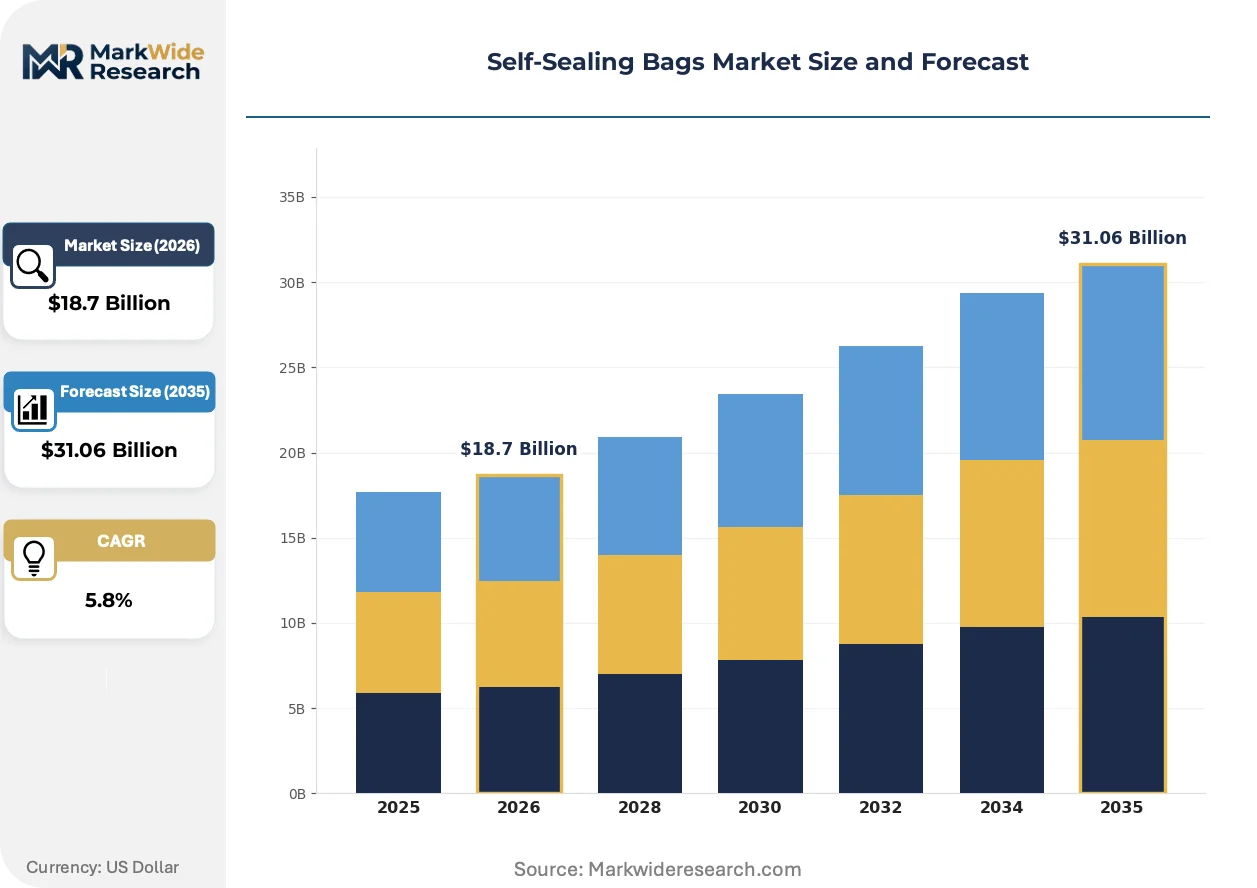
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Stand-Up Pouches, Gusseted Bags, Privacy Bags Material: Polyethylene, Polypropylene, Nylon, Biodegradable Materials End User: Retail, Food Service, Electronics, Healthcare Packaging Type: Bulk Packaging, Consumer Packaging, Custom Packaging, Others |
| Companies Covered | Sealed Air, Amcor, Berry Global, Mondi, Huhtamaki, Sonoco, Ampac Holdings, Novolex, Proficient Packaging CC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Sealing Bags Market Evolving Landscape
Active zipper profile engineering is compressing closure dimensions while maintaining hermetic seal performance, enabling thinner film gauges and reduced material intensity across temperature-sensitive distribution chains.
Mono-material polyethylene zipper systems are miniaturizing interlocking profiles to sub-2mm dimensions without sacrificing reseal cycle durability. Pharmaceutical cold-chain distributors are adopting these structures for temperature-validated shipments. The technology is miniaturizing barrier layer counts from multilayer coextrusions toward simplified recyclable constructions.
REACH SVHC disclosure mandates are forcing adhesive suppliers to reformulate pressure-sensitive strips around bio-based tackifiers. Industrial converters face reformulation validation costs and supply chain requalification. Food-contact applications in Central European markets are experiencing the most intensive compliance auditing.
Direct-to-consumer subscription snack services are compressing order batch sizes from pallet-scale to individual fulfillment units. Automated packaging lines in Dutch and Belgian e-commerce hubs are replacing bulk wicketed bags with unitized pouch formats. Pet food manufacturers in the Pacific Northwest are piloting this model for fresh-frozen product delivery.
Self-Sealing Bags Market Segmentation
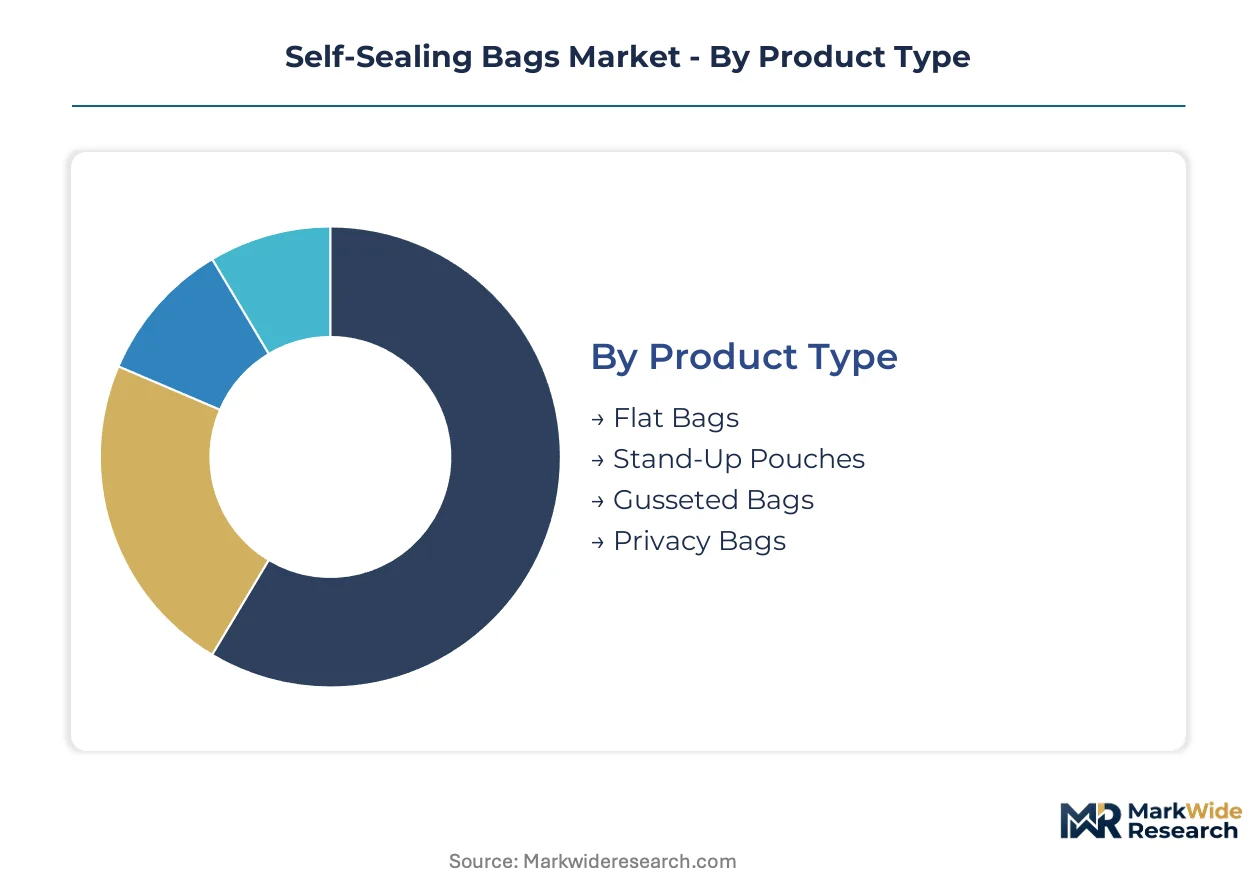
Self-sealing bag converters configure production assets around distinct specification clusters, each carrying unique barrier requirements, closure mechanisms, and regulatory compliance burdens. Procurement patterns diverge sharply between industrial bulk buyers and branded consumer goods manufacturers, forcing suppliers to maintain parallel qualification tracks.
Product Type:
REACH SVHC disclosure mandates and FDA food contact migration limits create divergent compliance pathways across structural formats, with zipper-equipped stand-up pouches facing stricter recyclability-by-design scrutiny than flat industrial bags.
- Flat Bags:Two-dimensional polyethylene or polypropylene constructions with adhesive strip or zipper profiles, typically 2-4 mil thickness. German automotive component suppliers and chemical distributors in the industrial packaging corridor specify these for part protection and inventory segregation, prioritizing cost minimization over shelf differentiation.
- Stand-Up Pouches:Three-dimensional structures with bottom gussets enabling vertical display, integrating high-clarity barrier films with resealable pour spouts or slider mechanisms. Premium snack and pet food segments in Nordic markets command margin capture through chilled ready-meal applications where shelf differentiation governs procurement decisions.
- Gusseted Bags:Side-folded constructions expanding volumetric capacity without increasing footprint, common in bulk industrial applications.
- Privacy Bags:Opaque constructions with tamper-evident closures for sensitive document or pharmaceutical transport.
Flat bags handle the majority of throughput; stand-up pouches are expanding most quickly on share as retail differentiation intensifies.
Material:
Resin cost volatility and Scope 3 emissions accountability are bifurcating procurement into polyethylene volume plays versus biodegradable premium positioning.
- Polyethylene:Dominant volume substrate across LDPE, LLDPE, and HDPE grades, offering heat-seal compatibility and moisture barrier performance at minimized unit cost. Bulk industrial applications in Germany's automotive and chemical distribution sectors sustain high-volume throughput for 4-6 mil constructions with slider mechanisms.
- Biodegradable Materials:PLA and PBAT blends with home-compostable certification, engineered for municipal organic waste collection systems. Nordic markets and premium snack brand owners facing net-zero commitments are pulling demand from conventional plastics toward compostable alternatives.
- Polypropylene:Higher clarity and temperature resistance than polyethylene, specified for retort and hot-fill applications.
- Nylon:Superior oxygen barrier for vacuum-sealed meat and cheese packaging in food service distribution.
Polyethylene retains the dominant share position; biodegradable materials are climbing the fastest as regulatory pressure on Scope 3 emissions intensifies.
End User:
Customer type determines closure complexity, with e-commerce fulfillment centers driving automated handling specifications distinct from retail shelf requirements.
- Retail:Branded consumer goods requiring high-clarity films, printed graphics, and resealable convenience features for ambient, chilled, and frozen distribution chains.
- Food Service:Institutional buyers prioritizing portion control, food safety compliance, and operational efficiency in high-throughput kitchen environments.
- Electronics:Static-dissipative and moisture-barrier specifications for component protection in semiconductor and automotive supply chains.
- Healthcare:Sterile barrier validation and tamper-evident documentation for pharmaceutical and medical device distribution.
Retail commands the largest revenue pool; food service is gaining share fastest as institutional procurement consolidates around standardized specifications.
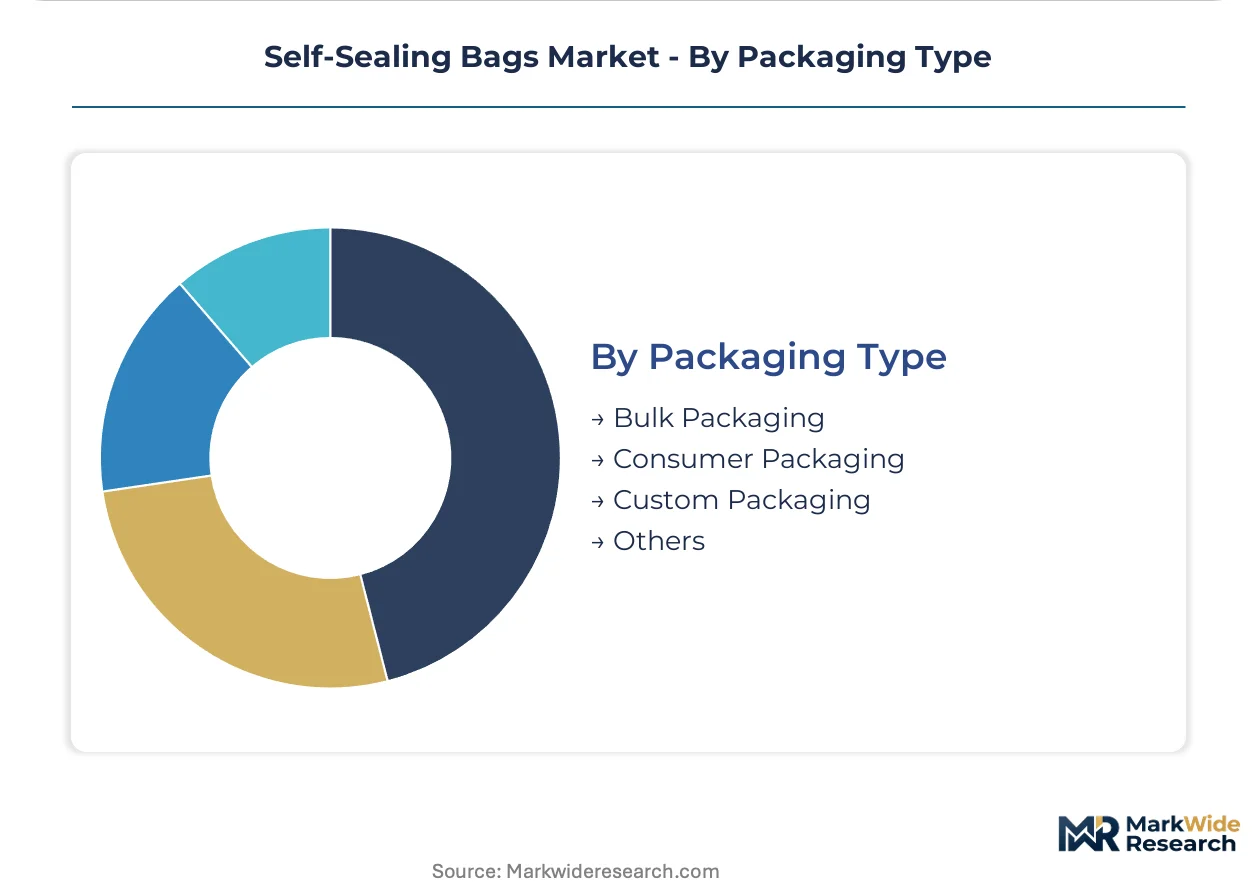
Packaging Type:
Order batch compression in direct-to-consumer channels is shifting volume from pallet-scale bulk formats toward unitized consumer and custom configurations.
- Bulk Packaging:Wicketed or roll-fed formats for automated form-fill-seal operations in industrial and food processing facilities.
- Consumer Packaging:Pre-printed, unitized pouches for retail shelf placement and e-commerce direct shipment.
- Custom Packaging:Short-run, brand-specific constructions for specialty food producers and subscription services.
- Others:Specified formats including sample sizes, promotional configurations, and seasonal variants.
Bulk packaging maintains the highest volume throughput; custom packaging is expanding fastest as small-batch artisan producers collapse into standardized procurement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Film extrusion capacity clusters along Germany's industrial corridor, with converting operations radiating toward Nordic markets and Central European distribution hubs. REACH compliance costs and recyclability mandates are redrawing procurement geography across the continent.
Germany
Automotive component suppliers and chemical distributors in the Ruhr-Rhine corridor sustain high-volume demand for 4-6 mil polyethylene bags with slider mechanisms. The EU Packaging and Packaging Waste Regulation's recyclability-by-design deadlines are accelerating converter investment in mono-material barrier platforms across Baden-Württemberg and North Rhine-Westphalia.
United States
E-commerce fulfillment centers in the Midwest and Southeast are consolidating specifications around tamper-evident closures for automated handling. FDA food contact substance regulations govern migration limits for polyethylene layers in shipments bound for retail distribution. Dallas-Fort Worth and Atlanta logistics clusters are driving unitized pouch format adoption.
China
Flexible packaging converters in the Yangtze River Delta are scaling production of zipper-equipped structures for export markets and domestic e-commerce platforms. The country's dual carbon goals are pressuring resin-intensive operations toward efficiency upgrades. Zhejiang and Jiangsu provinces host the densest concentrations of form-fill-seal equipment.
Netherlands
Direct-to-consumer subscription services in the Randstad are compressing order batches from pallet-scale to individual fulfillment units. ECHA's SVHC disclosure requirements are eliminating legacy adhesive chemistries from regional supply chains. Rotterdam's port logistics and Belgian e-commerce hubs are piloting automated packaging line conversions.
India
Food service institutional buyers in Maharashtra and Gujarat are consolidating procurement around standardized specifications for portion control applications. BIS standards and FSSAI compliance frameworks are tightening material certification requirements for flexible packaging. Mumbai-Pune industrial belt converters are expanding capacity for domestic retail and export markets.
Self-Sealing Bags Market Competitive Landscape
Concentration sits with diversified packaging conglomerates possessing captive film extrusion networks and multilayer coextrusion expertise. Three strategic archetypes dominate: integrated resin-to-pouch operators controlling feedstock cost volatility, regional specialists leveraging geographic density for logistics efficiency, and sustainability-focused innovators capturing biodegradable material premiums. Competitive moves center on backward integration into resin supply and portfolio diversification toward mono-material recyclable platforms.
Among diversified packaging conglomerates, Sealed Air, Amcor, and Mondi occupy positions representing distinct strategic vectors. Sealed Air exemplifies the integrated operator archetype with upstream control over film extrusion capacity. Amcor anchors the technology leadership tier through proprietary barrier platform development. Mondi sits within the geographic density specialist category, leveraging Central European converting facility networks for regional logistics optimization.
| Leading Market Players |
|---|
| Sealed Air |
| Amcor |
| Berry Global |
| Mondi |
| Huhtamaki |
| Sonoco |
| Ampac Holdings |
| Novolex |
| Proficient Packaging CC |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety day resin inventory cycles among European converters compress pricing negotiation windows when polyethylene feedstock volatility spikes, concentrating margin pressure on operators without captive extrusion capacity while amplifying procurement leverage for Germany's automotive component buyers in the Ruhr-Rhine corridor.
Pricing Analysis
EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across the self-sealing bags market, with recyclability-by-design compliance costs separating premium mono-material barrier platforms from standard multilayer constructions and economy-grade polyethylene bulk formats. Price differentiation hinges on certification tier—home-compostable PLA-PBAT blends command substantial premiums in Nordic markets—and volume scale, with pallet-scale industrial procurement securing double-digit discounts over unitized e-commerce fulfillment orders. Pricing pressure stems from resin cost volatility linked to crude oil derivatives, compressing converter margins during feedstock spikes. Bulk industrial buyers in Germany's chemical distribution sector exhibit highest price sensitivity, while premium snack brand owners facing Scope 3 emissions accountability demonstrate lowest sensitivity as they prioritize biodegradable substrate specifications.
Supply Chain Analysis
Rotterdam port congestion and Rhine River water level variability intermittently choke resin delivery schedules into Germany's industrial packaging corridor, forcing converters to maintain buffer stocks that tie up working capital. Film extrusion capacity concentrates in Germany, China, and the United States, with Germany's Baden-Württemberg and North Rhine-Westphalia regions hosting densest European converting clusters. Raw material dependencies center on polyethylene and polypropylene resins, bio-based tackifiers for REACH-compliant adhesives, and high-clarity barrier films for stand-up pouch applications. Supply chain risk manifests as single-source vulnerability for specialized zipper profile tooling manufactured in Zhejiang province. Distribution runs through regional converter networks supplying e-commerce fulfillment centers, with automated form-fill-seal lines in Dutch and Belgian hubs replacing bulk wicketed formats with unitized pouch structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as retail consolidation collapses small-batch artisan food producers into standardized procurement frameworks, shifting volume aggregation toward regional converter networks and eroding supplier pricing leverage.
For Market Incumbents: Consolidate backward integration into captive film extrusion networks to insulate margin structures from polyethylene resin volatility, while accelerating mono-material barrier platform R&D to preempt EU recyclability-by-design compliance deadlines. Sealed Air and Amcor have established template positions through upstream resin control and proprietary multilayer technology respectively; followers must match these capabilities or cede share in premium segments. Capacity addition in Poland and Czech Republic converting facilities offers geographic hedge against German supply chain chokepoints. For New Entrants and Emerging Players: Small-batch volume aggregation services represent the most penetrable white-space target, as collapsed artisan producers lack procurement scale to access tier-one converter pricing and require intermediary coordination. Nordic municipal organic waste collection systems offer second entry vector through home-compostable PLA-PBAT certification partnerships. Go-to-market execution should anchor in regional food hub proximity, establishing collection-and-redistribution logistics that incumbent conglomerates dismiss as sub-scale. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial packaging parents seeking portfolio simplification, particularly Central European converting assets with stranded multilayer coextrusion expertise and underutilized slider mechanism production lines. Long-term viability favors operators with demonstrated biodegradability certification pathways and e-commerce fulfillment automation compatibility. Watch industrial-scale polymer recycling infrastructure buildout rates as inflection signal—premature capacity commitments to compostable substrates risk stranded asset exposure if mechanical recycling achieves cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive resin processing insulates Sealed Air and followers from crude-linked polyethylene volatility. |
| Mono-Material Barrier Platform Development | Recyclability-by-design compliance unlocks EU market access as Packaging and Packaging Waste Regulation deadlines approach. |
| Biodegradable Substrate Certification | Home-compostable PLA-PBAT blends capture premium positioning in Nordic municipal organic waste systems. |
| E-Commerce Fulfillment Automation | Slider-equipped pouch compatibility with Dutch and Belgian automated packaging lines secures direct-to-consumer subscription volume. |
| Regional Converter Network Expansion | Poland and Czech Republic facilities reduce German logistics corridor dependency while serving Central European demand. |
Research Methodology
Cross-validation between converter production data and brand owner procurement specifications anchors the qualitative findings, with primary interviews conducted across plant managers at flexible packaging facilities, procurement leads at German automotive component suppliers, technical R&D directors in adhesive formulation, and category buyers at Nordic retail chains. Secondary validation draws from EU Packaging and Packaging Waste Regulation compliance filings, ECHA SVHC disclosure databases, customs trade data for polyethylene resin movements, and SEC 10-K segment disclosures from diversified packaging conglomerates. Bottom-up capacity assessments triangulate against top-down demand modeling from end-use sector consumption patterns.
Sensitivity analysis around resin price trajectories and recycling infrastructure deployment timelines frames the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, material substrate, closure mechanism complexity, end-use sector, and geographic regulatory cluster. CAGRs derive from installed capacity utilization rates, substitution elasticities between polyethylene and biodegradable alternatives, and e-commerce fulfillment automation penetration curves. Industry-specific forecast inputs incorporate REACH SVHC list expansion schedules and FDA food contact migration testing queue lengths.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation implementation, FDA food contact substance enforcement, and REACH SVHC disclosure mandates; material policy shifts would require re-modeling. Specific risk factors that could revise projections include accelerated mechanical recycling cost parity, abrupt resin feedstock price dislocations, and German automotive sector demand contraction. Practitioners should keep alternative scenarios live as biodegradability certification standards and polymer recycling infrastructure buildout rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Block Sack Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Textile Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Carry Bag Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Type-C Bulk Bags Market
Bags and Containers
Jumbo Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Refuse Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Drum Liners Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Cross Bottom Bags Market