
 Beverage Crates Market | 2026-2036
Beverage Crates Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Crates Market Outlook
Direct-to-retail crate pooling is tilting as major bottlers consolidate reverse-logistics contracts. Schoeller Allibert leverages its European molding footprint to dominate reusable HDPE crate supply for beer and carbonated drinks. Rehrig Pacific Company anchors North American dairy and soft drink distribution through proprietary tracking-enabled crate designs. Brambles Limited competes in pooled equipment services, extending its CHEP container network into beverage-specific formats across multiple continents.
Beverage crates are rigid, stackable containers engineered from high-density polyethylene, polypropylene, or treated wood, designed to withstand repeated washing cycles, temperature fluctuations, and mechanical stress during automated filling lines and warehouse handling. Their primary purpose is to protect bottled and canned beverages through distribution while enabling efficient return-loop logistics. Plastic crates lead volume due to durability and sanitation compliance, though composite materials are gaining traction where weight reduction matters. Stackable types occupy the core of beer and soft drink logistics, while foldable formats address space constraints in urban retail backrooms.
EPA guidelines on recycled content and FDA food-contact substance notifications shape polymer selection and washing protocol design in the United States, while REACH and EU Packaging and Packaging Waste Directive obligations drive crate standardization and recyclability targets across European supply chains. Stakeholders must monitor how deposit-return scheme expansions in multiple countries alter crate specification requirements and pooling economics.
Market Dynamics
Deposit-return legislation in Germany has triggered a fleet standardization wave that bottlers across Europe now replicate to secure reverse-logistics economics. Pooling contracts consolidate around fewer service providers as washing infrastructure and tracking systems demand capital scale.
Growth Catalysts
- REACH polymer compliance:ECHA substance restrictions on food-contact plastics force HDPE grade upgrades that extend crate lifecycles and justify premium pooling fees.
- Brewery fleet expansion:Craft and industrial brewers in Belgium and the Netherlands rebuild reusable crate inventories to replace shrink-wrapped pallets in on-premise distribution.
- RFID-embedded tracking:Automated crate counting at depot gates cuts labor costs and shrinkage losses for dairy cooperatives operating closed-loop networks.
Market Restraints
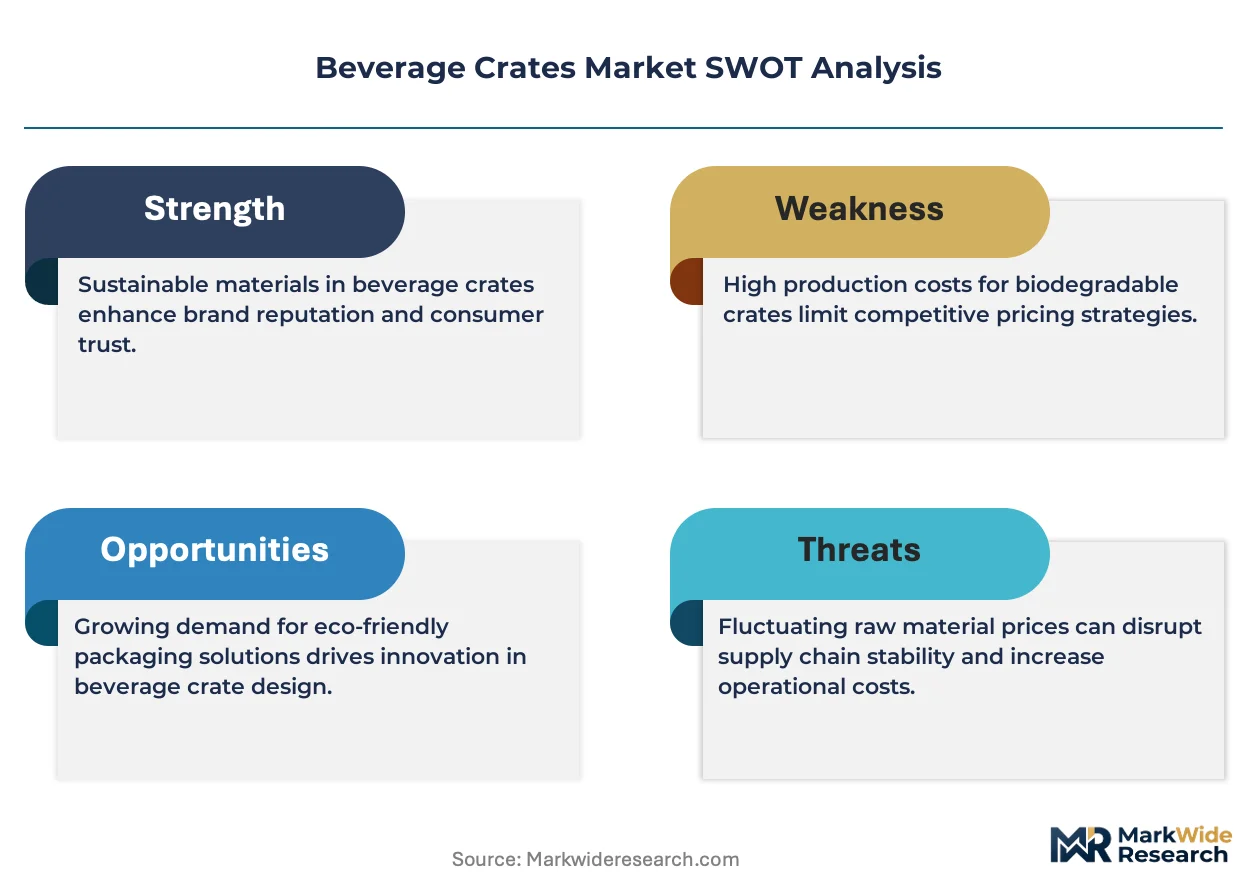
- HDPE resin volatility:Crude-linked feedstock costs swing crate production economics and compress molding margins during energy price spikes.
- Chinese molding overcapacity:Export-oriented HDPE crate producers in East Asia flood spot markets with non-pooled units that undercut European washing-service bundles.
- Deposit scheme fragmentation:Incompatible crate dimensions across Scandinavian, Germanic, and Alpine systems force bottlers to maintain parallel fleet specifications.
Strategic Opportunities
- Polish retail modernization:Discounter expansion in Warsaw and Krakow creates demand for foldable crates that collapse to one-fifth volume for back-of-store storage.
- EU Packaging and Packaging Waste Directive targets:Mandatory reuse quotas for transport packaging by 2030 position pooled crate services as compliance infrastructure.
- Composite material convergence:Glass-fiber-reinforced PP compounds blend durability with 15-20% weight reduction for manual handling in convenience store channels.
Industry Challenges
- Washing chemistry certification:NSF/ANSI and EFSA approvals for caustic detergent formulations extend validation timelines for new depot openings.
- Legacy ERP integration:Pooling operators struggle to synchronize crate tracking data with bottler inventory systems running on decade-old warehouse management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Crates Market |
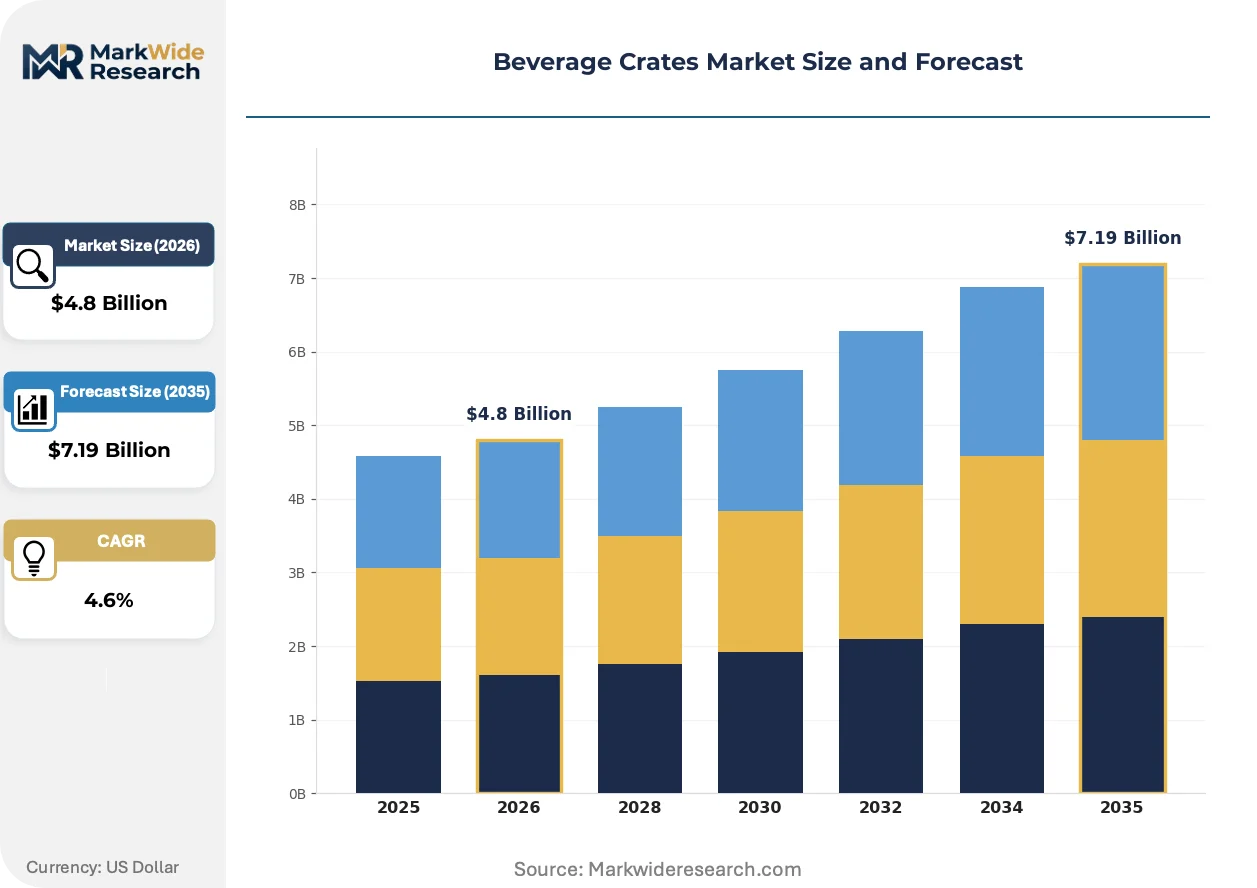
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Wood, Metal, Composite End User: Retail Stores, Wholesalers, Manufacturers, Distributors Size: Small, Medium, Large, Custom Type: Stackable, Foldable, Crate with Lid, Bulk |
| Companies Covered | Schoeller Allibert, Rehrig Pacific Company, Myers Industries, Supreme Industries Limited, DS Smith Plc, IPL Plastics Inc., Craemer Group, Brambles Limited, TranPak Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Crates Market Strategic Shifts
Material science and digital tracking are compressing the trade-off between crate durability and logistics flexibility. Regulatory reuse mandates accelerate investment in washing infrastructure and fleet telemetry.
Embedded RFID and QR-code tracking is hybridizing crate management from simple asset recovery into real-time supply chain visibility tools. Mid-sized dairy distributors in Bavaria and Baden-Württemberg deploy these systems fastest. The technology is compressing invoice reconciliation cycles and enabling dynamic deposit pricing based on actual circulation velocity rather than static rental fees.
EFSA updated its food-contact material guidelines in 2023, tightening migration limits for recycled HDPE used in beverage logistics. European crate molders now source virgin-near resin grades or invest in super-cleaning extrusion lines. German beer bottlers face the steepest compliance costs, passing specifications down through pooling contracts that exclude non-certified suppliers.
Retailers in urban France and northern Italy now specify collapsible crate formats for store-door delivery. Traditional rigid stackable designs lose share in convenience and petrol-station channels where backroom space constraints dominate procurement criteria. The shift is most visible in Paris and Milan metropolitan zones, where real estate costs pressure square-meter efficiency.
Beverage Crates Market Segmentation
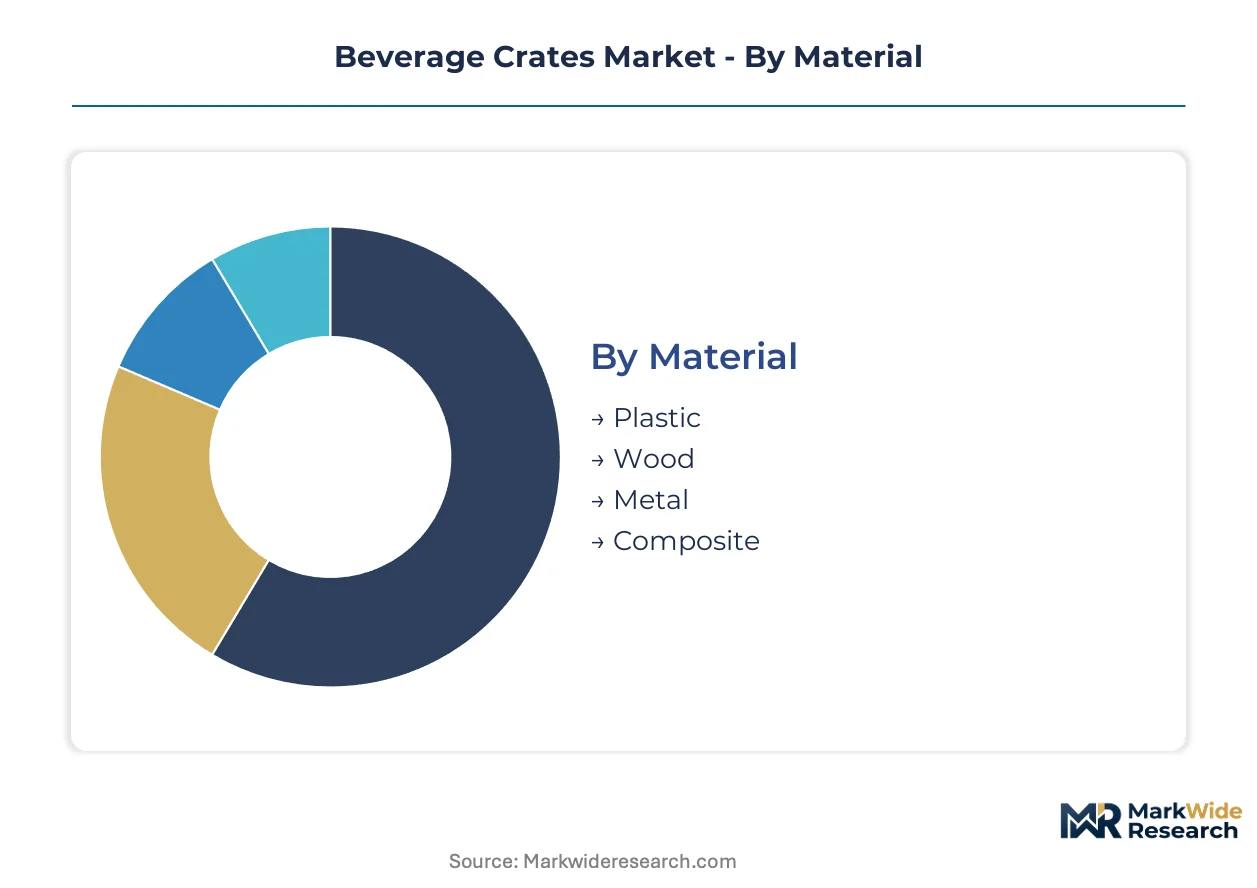
Beverage crate segmentation reveals how material durability, end-user logistics scale, and dimensional flexibility shape procurement patterns across beer, soft drink, and dairy distribution networks. Each dimension carries distinct compliance burdens and capital intensity profiles that determine supplier selection and pooling economics.
Material:
Mature resin grades dominate fleet-scale deployments while emerging composites target weight-sensitive channels.
- Plastic:High-density polyethylene and polypropylene formulations withstand caustic washing cycles and automated filling line stress. German beer bottlers under EFSA food-contact rules specify virgin-near HDPE grades that exclude recycled content from direct beverage contact surfaces.
- Wood:Treated timber crates persist in wine and spirits distribution where aesthetic presentation and thermal mass matter. French and Italian vineyard cooperatives maintain wooden fleets for estate-direct shipments despite higher sanitation validation costs.
- Metal:Aluminum and steel constructions serve high-temperature pasteurization environments where polymer deformation risks exclude plastic alternatives.
- Composite:Glass-fiber-reinforced polypropylene compounds blend structural rigidity with 15-20% weight reduction for manual handling in convenience store channels.
Plastic retains volume leadership; composite holds the steepest expansion curve.
End User:
Customer type determines whether crates circulate through open pooling networks or closed proprietary fleets.
- Retail Stores:Supermarket and hypermarket chains specify collapsible formats compatible with automated backroom sorting systems. French urban retailers drive demand for space-efficient designs that compress to one-fifth volume during off-peak storage.
- Wholesalers:Beverage distributors operating multi-brand portfolios require standardized dimensions across incompatible deposit-return schemes. Scandinavian wholesalers absorb parallel fleet specifications to serve fragmented Nordic markets.
- Manufacturers:Breweries and soft drink bottlers own or lease dedicated crate inventories sized to their filling line footprints and bottle formats.
- Distributors:Third-party logistics providers aggregate crates from multiple sources, prioritizing RFID-trackable assets that reconcile circulation velocity against rental fees.
Retail stores command the largest fleet deployment; distributors are expanding most quickly as pooling services consolidate.
Size:
Dimensional segmentation aligns crate capacity with route density and vehicle cube utilization targets.
- Small:Compact formats suit convenience stores and petrol stations with severe backroom space constraints. Italian metropolitan retailers specify these for store-door delivery in Milan and Rome.
- Medium:Standard Euro-dimension crates circulate through German deposit-return infrastructure as the reference specification for beer and carbonated drinks.
- Large:High-capacity designs serve wholesale cash-and-carry channels where pallet-level handling minimizes labor cost per case.
- Custom:Proprietary dimensions lock bottlers into single-source supply relationships and complicate secondary market liquidity.
Medium sizes anchor standardized pooling networks; custom formats gain share fastest among craft brewers seeking format differentiation.
Type:
Structural design determines stacking stability, nesting efficiency, and protection level during distribution.
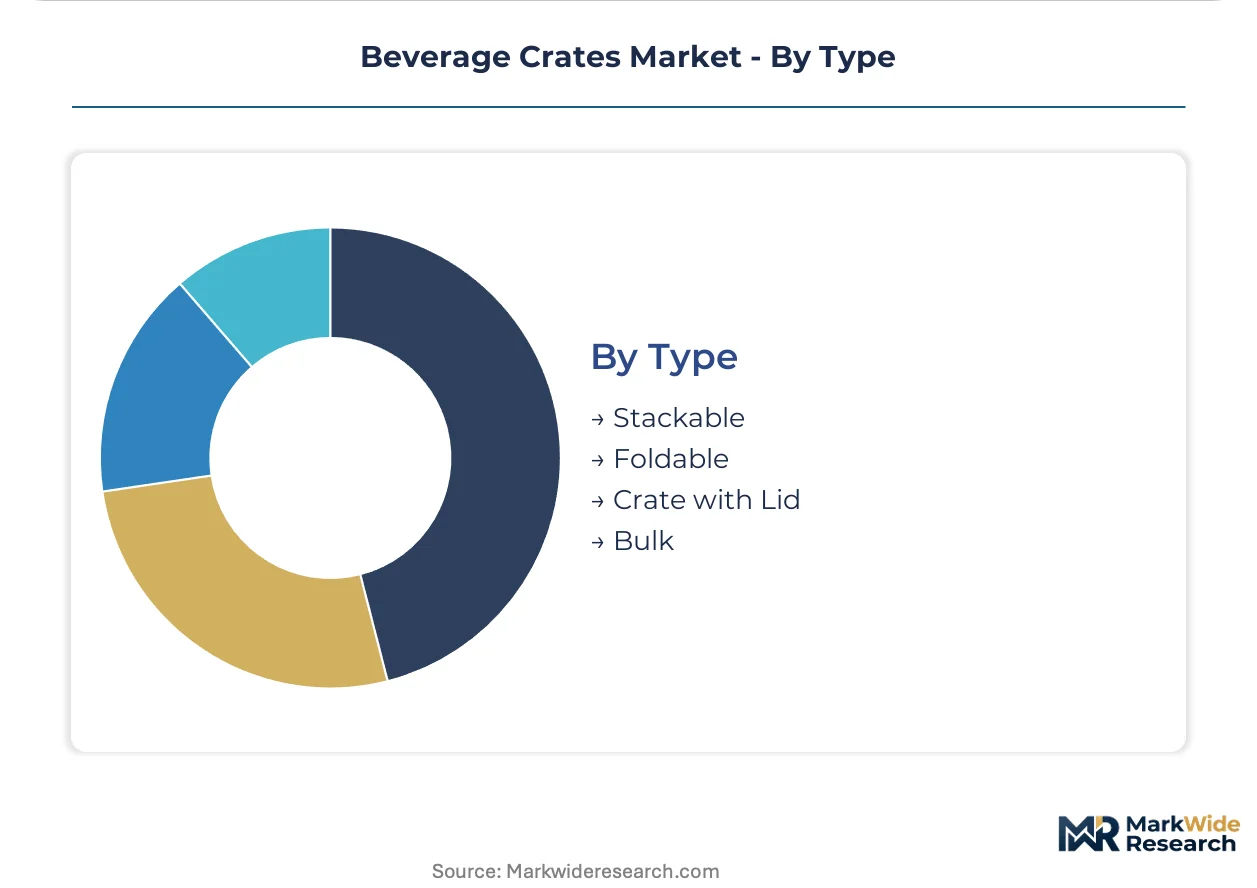
- Stackable:Rigid interlocking designs form the backbone of beer and soft drink logistics, enabling stable pallet builds and high-density warehouse storage. Belgian and Dutch brewers rebuild inventories of these formats to replace shrink-wrapped pallet distribution.
- Foldable:Collapsible structures address space constraints in urban retail backrooms where real estate costs pressure square-meter efficiency. Paris and Milan metropolitan zones show fastest uptake in convenience and petrol-station channels.
- Crate with Lid:Enclosed designs protect sensitive products from contamination and tampering in dairy and premium beverage distribution.
- Bulk:Open-top containers serve high-volume, low-velocity SKUs where protection requirements are minimal and handling speed dominates.
Stackable formats retain volume leadership; foldable types show the steepest expansion trajectory as urban retail density intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway network underwrites Central Europe's dominance in reusable beverage logistics, connecting German brewing centers to distribution nodes across twelve countries.
Germany
Deposit-return legislation mandates standardized crate circulation through the Einwegpfand system, forcing fleet homogenization across breweries. EFSA food-contact material rules tighten polymer specifications for HDPE grades used in direct beverage contact. Bavarian brewing clusters around Munich and Nuremberg operate the densest washing depot networks in Europe.
United States
FDA food-contact substance notifications and EPA recycled content guidelines shape polymer selection for dairy and soft drink distribution. Rehrig Pacific Company anchors North American supply through tracking-enabled crate designs. California's beverage distribution corridors demand RFID-embedded assets for compliance with state-level packaging waste regulations.
France
Urban retailers in Paris and Lyon specify collapsible crate formats to maximize backroom square-meter efficiency under strict commercial real estate costs. ANSM enforces food-contact compliance parallel to EU REACH obligations. The Île-de-France metropolitan zone shows fastest uptake of foldable designs in convenience and petrol-station channels.
Netherlands
Belgian and Dutch brewers rebuild reusable crate inventories to replace shrink-wrapped pallet distribution in on-premise channels. ECHA substance restrictions on food-contact plastics force HDPE grade upgrades across Rotterdam-Amsterdam logistics corridors. Craft brewing clusters in North Brabant and Limburg drive demand for custom-format crates.
Poland
Discounter expansion in Warsaw and Krakow creates demand for foldable crates that collapse to one-fifth volume for back-of-store storage. EU Packaging and Packaging Waste Directive targets position pooled crate services as compliance infrastructure for 2030 reuse quotas. Silesian manufacturing zones host emerging washing depot investments serving Central European distribution networks.
Beverage Crates Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in molding and material supply. Pooling operators consolidate around capital-intensive washing infrastructure and tracking systems that demand scale economics. Three archetypes dominate: full-service pooling platforms, proprietary fleet owners, and specialized molding houses. Competitive moves concentrate on reverse-logistics contract consolidation and RFID-embedded asset tracking deployment.
Within the European molding tier, Schoeller Allibert and Craemer Group exemplify regional fabrication specialists leveraging proximity to German brewing clusters. Rehrig Pacific Company anchors North American positioning through proprietary tracking-enabled designs. Brambles Limited occupies the pooled equipment services archetype, extending container networks into beverage-specific formats across multiple continents.
| Leading Market Players |
|---|
| Schoeller Allibert |
| Rehrig Pacific Company |
| Myers Industries |
| Supreme Industries Limited |
| DS Smith Plc |
| IPL Plastics Inc. |
| Craemer Group |
| Brambles Limited |
| TranPak Inc. |
| Others |
Value Chain & Pricing Dynamics
German resin compounders and molding clusters around Munich and Nuremberg concentrate HDPE supply for European beverage crate production, anchoring margin pools in washing depot networks and RFID-embedded fleet management services downstream. This upstream consolidation allows pooling operators to capture value through long-term reverse-logistics contracts that lock in standardized crate circulation.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with premium-mid-economy pricing differentiation separating EFSA-certified virgin-near HDPE grades from standard recycled-content tiers. Price differentiation rests on certification level and washing service bundling, with German beer bottlers absorbing premium tiers for compliance while Polish discounters drive cost compression in economy segments. Pricing pressure stems from Chinese molding overcapacity flooding spot markets, compressing margins on non-pooled units. Small convenience store chains exhibit highest price sensitivity; multinational bottlers with deposit-return mandates show lowest.
Supply Chain Analysis
Export-control regimes on advanced polymer processing equipment limit super-cleaning extrusion line deployments to European and North American molders, constraining supply expansion. Manufacturing concentrates in Germany, China, and the United States, with HDPE resin feedstock drawing from Gulf Coast petrochemical complexes and Middle Eastern crackers. Supply chain risk centers on crude-linked resin volatility disrupting production economics. Distribution runs through pooled equipment platforms and proprietary brewery fleets, with RFID-trackable assets commanding priority allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against shrink-wrapped pallet distribution and single-use corrugated alternatives that undercut reusable crate economics in cost-sensitive channels. Deposit-return fragmentation and washing infrastructure scale requirements create defensive moats for consolidated operators.
For Market Incumbents: Entrench market position through backward integration into resin compounding to secure EFSA-compliant HDPE grades, and expand washing depot density in Bavarian brewing clusters to capture craft brewery fleet rebuilds. Lock in long-term pooling contracts with RFID-embedded tracking to exclude Chinese spot-market competitors from closed-loop networks.
For New Entrants and Emerging Players: Establish a beachhead in Polish foldable crate segments serving Warsaw and Krakow discounter expansion, where EU Packaging and Packaging Waste Directive compliance infrastructure demand outstrips local washing capacity. Target composite material convergence for convenience store channels, leveraging glass-fiber-reinforced PP weight advantages to bypass established HDPE supply relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward pooled equipment service platforms with established washing infrastructure and telemetry systems, as consolidation economics favor scale operators over specialized molders. Monitor deposit-return scheme harmonization across Scandinavian, Germanic, and Alpine systems as the inflection signal for fleet standardization acceleration and premium pooling fee expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Secures EFSA-compliant HDPE supply for German beer bottlers facing migration limit tightening. |
| RFID Fleet Telemetry Deployment | Enables dynamic deposit pricing for Bavarian dairy cooperatives operating closed-loop networks. |
| Foldable Crate Format Expansion | Addresses Paris and Milan metropolitan backroom space constraints under commercial real estate pressure. |
| Washing Depot Network Densification | Captures Polish discounter compliance demand ahead of 2030 EU reuse quota enforcement. |
| Composite Material R&D Investment | Delivers 15-20% weight reduction for manual handling in Italian convenience store channels. |
Study Parameters
Initial hypotheses were tested against primary input from brewery operations directors, pooling service procurement managers, HDPE resin procurement leads, and washing depot technical supervisors, and refined through secondary validation against EFSA guidance documents, EU Packaging and Packaging Waste Directive regulatory filings, German deposit-return system operator reports, and customs trade data on HDPE crate imports. Bottom-up triangulation of fleet inventory data with top-down market sizing completed the analytical framework.
Demand-supply-balance framing anchored the forecast architecture across the analysis window, with segmentation modeling across material grade tiers, end-user channel types, dimensional formats, and structural design categories. CAGRs were derived from installed base turnover rates and deposit-return scheme expansion trajectories, incorporating polymer price elasticity assumptions and washing infrastructure capacity buildout schedules as industry-specific inputs.
Sensitivities concentrate around EFSA food-contact material guideline revisions, EU reuse quota enforcement timing, and HDPE resin price volatility. Forecasts reflect documented assumptions on fleet standardization velocity and pooling contract renewal rates. Material shifts in deposit-return scheme harmonization or super-cleaning extrusion technology cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Drink Can Market
Beverage Packaging
Stackable Beaker Market