
 Laboratory Consumables Primary Packaging Market | 2026-2036
Laboratory Consumables Primary Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Consumables Primary Packaging Market Foresight
EU MDR and the FDA's updated container closure guidance for biologics is shifting procurement specifications toward extractables-free, gamma-stable primary packaging. Thermo Fisher Scientific leverages its vertically integrated resin-to-sterile-finish capability to dominate high-complexity cell therapy applications. Sartorius AG anchors European bioproduction demand through membrane-integrated bag and tube systems. Corning Incorporated specializes in pharmaceutical-grade borosilicate vials with controlled hydrolytic resistance, competing on material science depth rather than commodity scale.
Laboratory consumables primary packaging comprises the immediate-contact vessels and containment systems—vials, tubes, syringes, and bottles—fabricated from polypropylene, glass, polyethylene, or silicone in rigid, flexible, semi-rigid, or pouch configurations, engineered to maintain sterility, chemical inertness, and dimensional stability from manufacture through end-use. Polypropylene tubes and vials lead volume due to their compatibility with autoclaving and centrifugation cycles, while silicone components command premium positioning in high-value biologics where plunger seal integrity determines shelf life. Glass retains structural importance in pharmaceutical companies requiring USP Type I hydrolytic resistance for parenteral formulations, though flexible polyethylene pouches are gaining share in research labs adopting modular, space-efficient workflow designs.
The FDA enforces container closure integrity testing under biologics license applications, while EMA's Annex 1 revision mandates single-use technology validation for sterile manufacturing, directly shaping supplier qualification burdens and material traceability requirements. ISO 15378 and USP <661> establish physicochemical benchmarks that determine market access for glass and polymer primary packaging. Stakeholders must monitor how the EU AI Act and impending FDA guidance on artificial intelligence in manufacturing quality systems will reshape validation protocols for automated visual inspection and defect detection in consumables production.
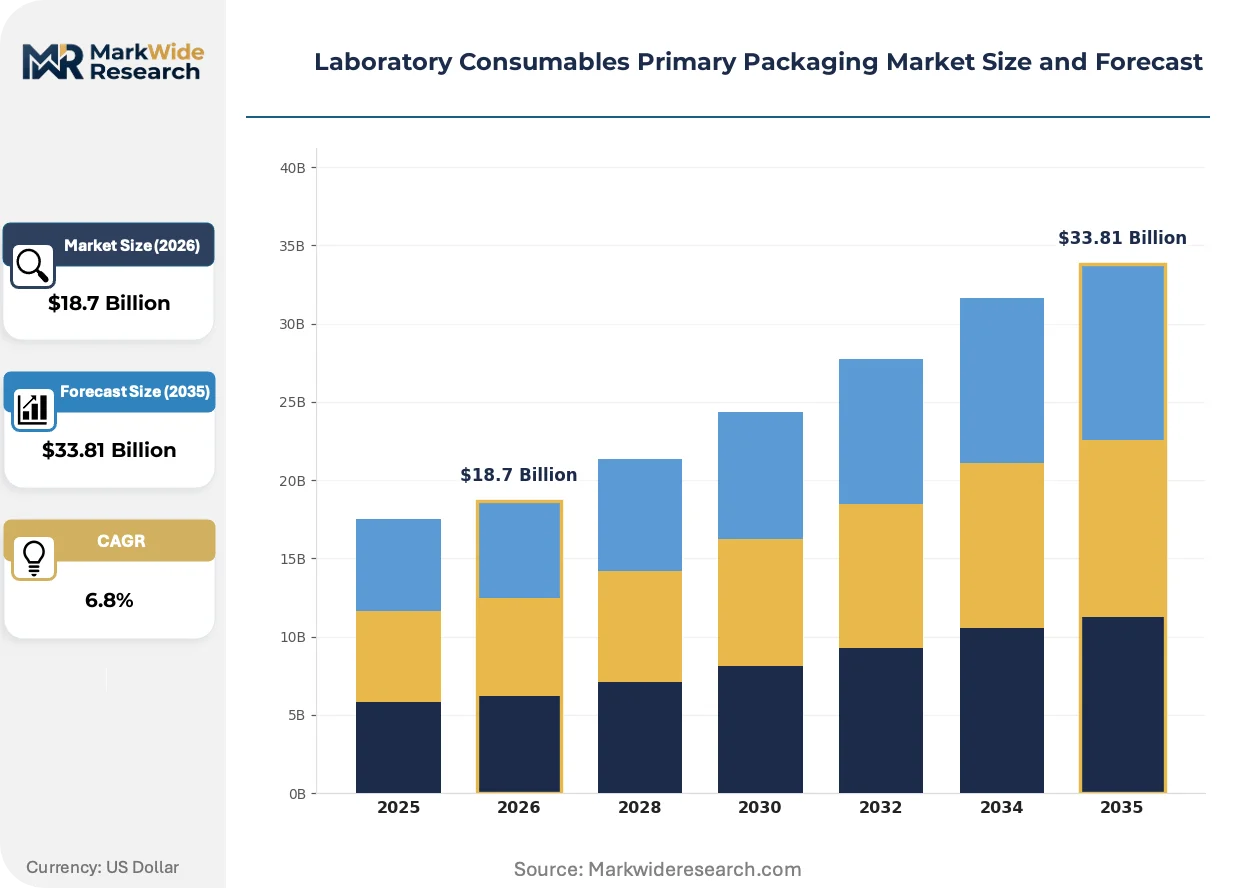
Market Dynamics
Single-use technology validation mandates under EMA's Annex 1 revision are compressing supplier qualification timelines while simultaneously expanding procurement volumes for extractables-free, gamma-stable primary packaging systems.
Growth Catalysts
- EMA Annex 1 Sterile Manufacturing Mandates:The 2022 revision requires validated single-use technology for aseptic processing, forcing biopharmaceutical contract manufacturers to expand consumable procurement.
- Cell Therapy Manufacturing Scale-Up:Autologous and allogeneic cell therapy production lines require sterile, closed-system consumables with documented extractables profiles.
- German Supplier Cluster Density:Concentrated membrane-integrated bag and tube manufacturing in Lower Saxony and Thuringia reduces lead times for European bioproduction facilities.
Market Restraints
- Medical-Grade Resin Supply Concentration:Pharmaceutical-grade polypropylene and cyclic olefin polymer feedstocks depend on a limited number of polymerization facilities in the US Gulf Coast and Northwestern Europe.
- Gamma Irradiation Capacity Bottlenecks:Sterilization service providers face scheduling constraints as biologics manufacturing expands faster than cobalt-60 and e-beam facility commissioning.
- Glass Hydrolytic Resistance Limitations:USP Type I borosilicate vials remain necessary for parenteral formulations, preventing full polymer substitution in high-value injectables.
Strategic Opportunities
- AI-Enabled Visual Inspection:The EU AI Act creates compliance pathways for automated defect detection systems that reduce manual inspection labor in consumables finishing.
- Modular Research Lab Configurations:Flexible polyethylene pouch systems are displacing rigid containers in academic and contract research settings seeking space-efficient workflow redesign.
- Closed-System Transfer Device Integration:Convergence of primary packaging with drug delivery mechanisms creates value-add positioning for suppliers with device-assembly capabilities.
Industry Challenges
- Extractables Study Standardization:Lack of harmonized protocols between USP <661>, ISO 10993, and BPOG guidelines forces redundant testing and extended qualification timelines.
- Cleanroom Manufacturing Talent Scarcity:Aseptic processing engineering and polymer science specializations face recruitment gaps as biologics capacity expands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Consumables Primary Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Tubes, Syringes, Bottles Material: Polypropylene, Glass, Polyethylene, Silicone Form: Rigid, Flexible, Semi-Rigid, Pouch End User: Research Labs, Pharmaceutical Companies, Clinical Laboratories, Educational Institutions |
| Companies Covered | Becton Dickinson and Company, Sartorius AG, Thermo Fisher Scientific Inc., Greiner Bio-One International GmbH, Eppendorf AG, Merck KGaA, Corning Incorporated, Schott AG, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Consumables Primary Packaging Market Shifts & Advancements
Automated visual inspection and closed-system integration are compressing manual handling requirements while regulatory pressure on extractables documentation intensifies material science investment.
Machine vision systems with deep-learning defect classification are automating final container inspection in consumables finishing operations. High-volume tube and vial manufacturers are retrofitting legacy lines with AI-enabled cameras that detect particulate, cosmetic, and dimensional anomalies at throughput rates exceeding human inspection capacity. This is automating quality assurance labor out of sterile packaging workflows while tightening release specifications.
EMA's Annex 1 revision and FDA container closure guidance for biologics are converging procurement specifications toward extractables-free, gamma-stable materials with full supply chain traceability. Suppliers must now document resin lot genealogy through polymerization, conversion, and sterilization. European biopharmaceutical manufacturers are responding by consolidating vendor bases to those with integrated resin-to-sterile-finish capabilities.
Contract research organizations and academic core facilities are unbundling traditional distributor relationships to procure directly from specialized consumables manufacturers. This channel disintermediation is compressing margin capture by broad-line laboratory distributors while rewarding suppliers with configurable minimum order quantities and rapid turnaround. The shift is most visible in Germany and Switzerland, where dense supplier clusters enable same-day or next-day fulfillment to research institutions.
Laboratory Consumables Primary Packaging Market Segmentation
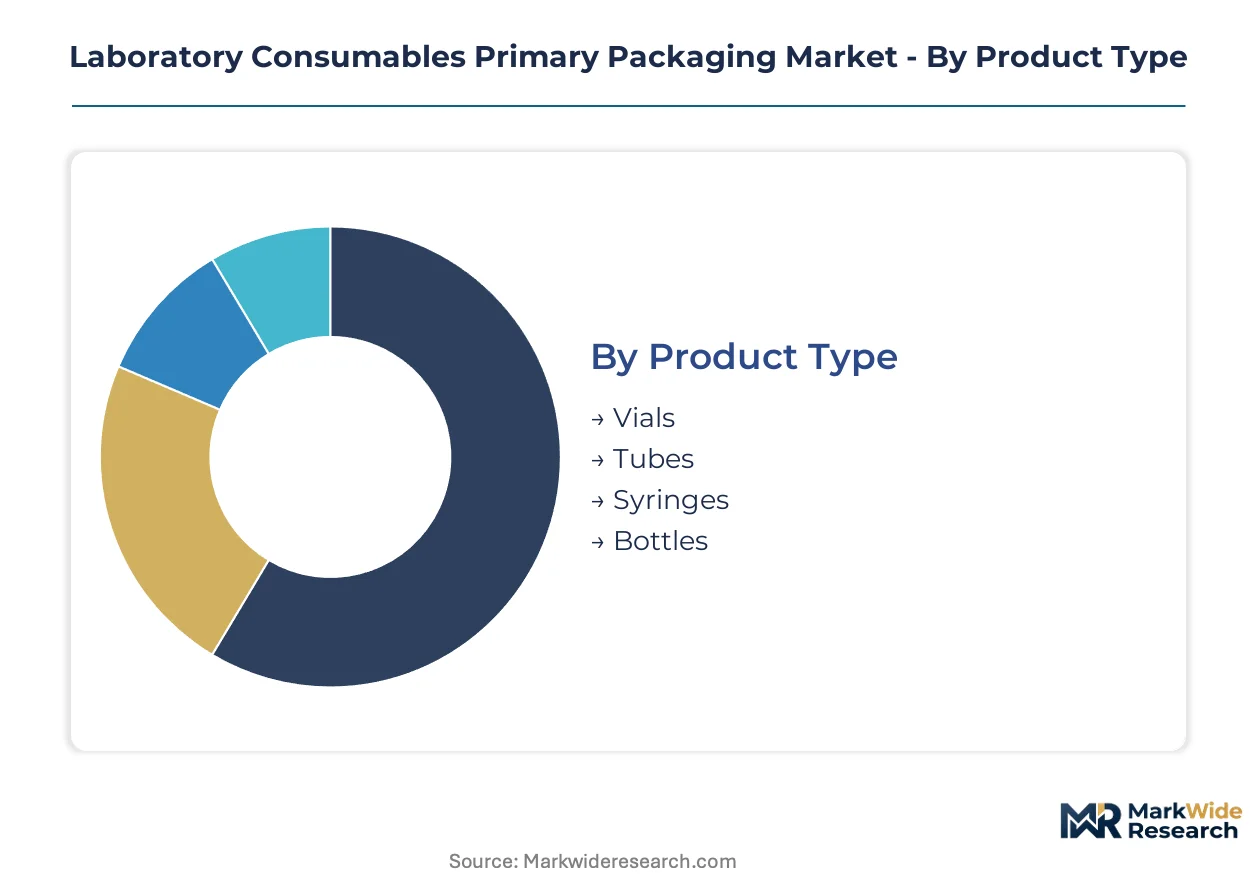
Segmentation in laboratory consumables primary packaging reflects divergent sterility requirements, material compatibility demands, and workflow configurations across research and manufacturing environments. Procurement specifications vary sharply between high-volume cell therapy production and modular academic research setups.
Product Type:
Upgrade cycles accelerate where EMA Annex 1 mandates force replacement of legacy containers with validated single-use alternatives.
- Vials:USP Type I borosilicate and cyclic olefin polymer variants dominate parenteral formulation containment, with hydrolytic resistance certification determining supplier qualification in German pharmaceutical manufacturing.
- Tubes:Polypropylene centrifuge and storage tubes command the highest procurement volumes, driven by autoclave compatibility requirements in biopharmaceutical contract manufacturing organizations scaling cell therapy capacity.
- Syringes:Prefilled glass-barrel and polymer-barrel systems integrate plunger-seal assemblies for biologic delivery, with silicone coating specifications critical to protein stability.
- Bottles:Wide-mouth and narrow-neck configurations serve media preparation and buffer storage in research labs, with HDPE and PETG alternatives displacing glass in non-parenteral applications.
Tubes sit at the top of the volume ranking, with vials climbing the fastest.
Material:
Cost tiers separate commodity resin applications from pharmaceutical-grade specifications requiring full polymerization-lot traceability.
- Polypropylene:Medical-grade homopolymer and copolymer resins form the backbone of tube, vial, and closure production, with gamma-stabilized grades commanding price premiums in biologic applications.
- Glass:USP Type I borosilicate retains structural importance for parenteral formulations requiring inert contact surfaces and visible particulate inspection, preventing full polymer substitution in high-value injectables.
- Polyethylene:LDPE and HDPE variants enable flexible pouch and semi-rigid bottle production for space-efficient research workflows, with linear low-density grades expanding in single-use bag applications.
- Silicone:Platinum-cured elastomer components seal syringe plungers and valve assemblies, with extractables documentation requirements intensifying procurement scrutiny in cell therapy manufacturing.
Polypropylene sits at the top of the volume ranking, with silicone climbing the fastest.
Form:
Customer workflow redesigns favoring modularity and space efficiency are displacing rigid container formats in research settings.
- Rigid:Injection-molded polypropylene and glass containers maintain dimensional stability through autoclaving and centrifugation cycles, serving high-throughput screening and sample archiving in clinical laboratories.
- Flexible:Multi-layer polyethylene and ethylene vinyl alcohol pouches reduce storage footprint and shipping weight, gaining share in academic core facilities reconfiguring bench space.
- Semi-Rigid:Thermoformed PETG and polycarbonate trays bridge structural integrity with reduced mass, deployed in kit assembly and intermediate processing steps.
- Pouch:Stand-up and lay-flat bag configurations with integrated tube ports enable closed-system fluid transfer, expanding in bioproduction lines adopting single-use technology.
Rigid sits at the top of the volume ranking, with pouch climbing the fastest.
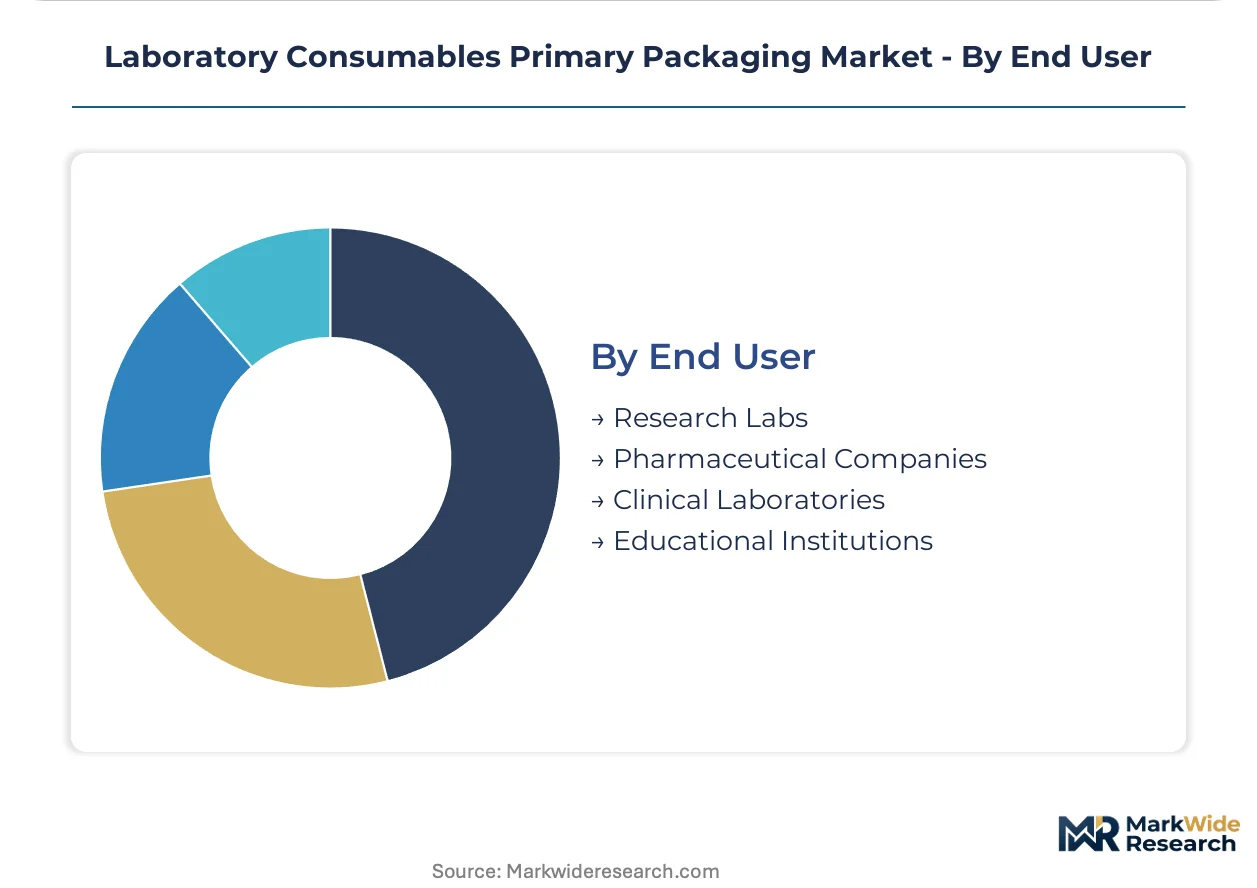
End User:
Procurement authority concentration varies sharply between centralized pharmaceutical supply chains and fragmented academic purchasing.
- Research Labs:Academic and government facilities prioritize configurable minimum order quantities and rapid turnaround, driving direct procurement from specialized manufacturers in German supplier clusters.
- Pharmaceutical Companies:Biologics manufacturers enforce extractables-free, gamma-stable specifications with full resin genealogy documentation, consolidating vendor bases to integrated resin-to-sterile-finish suppliers.
- Clinical Laboratories:Diagnostic testing facilities consume high-throughput tube and vessel formats, with automation compatibility determining format selection in centralized reference labs.
- Educational Institutions:Undergraduate teaching labs drive commodity-grade procurement at price-sensitive tiers, with distributor relationships persisting where technical support requirements are minimal.
Pharmaceutical companies sit at the top of the volume ranking, with research labs climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer scientists and aseptic processing engineers concentrate in Germany's Lower Saxony and Thuringia regions, anchoring European bioproduction supply chains. This talent density shapes procurement patterns across the continent.
Germany
EMA's Annex 1 sterile manufacturing mandates drive contract manufacturers toward validated single-use technologies. The country's national pharmaceutical regulator enforces extractables documentation requirements that compress supplier qualification timelines. Sartorius AG and Eppendorf AG anchor dense manufacturing clusters in Göttingen and Hamburg, serving biopharmaceutical production lines with membrane-integrated bag systems.
United States
FDA container closure integrity testing requirements for biologics license applications intensify demand for USP Type I hydrolytic resistance certification. The agency's updated guidance on gamma-stable materials shapes procurement specifications for cell therapy manufacturers. Thermo Fisher Scientific leverages vertically integrated resin-to-sterile-finish operations across Massachusetts and California to dominate high-complexity applications.
Switzerland
Swissmedic's stringent quality system requirements for sterile manufacturing elevate barrier-to-entry for primary packaging suppliers. The country's pharmaceutical regulator mandates full polymerization-lot traceability that favors integrated manufacturers. Basel and Zurich host specialized membrane and tubing operations serving contract research organizations with configurable minimum order quantities.
China
NMPA's evolving biologics container closure standards accelerate domestic capacity investment in pharmaceutical-grade polymer conversion. The national medical products administration's alignment with ISO 15378 creates compliance pathways for export-oriented manufacturers. Yangtze River Delta clusters in Suzhou and Shanghai concentrate blow-fill-seal and flexible pouch production for regional vaccine filling operations.
India
CDSCO's strengthening good manufacturing practice inspections for sterile products drive upgrade cycles in domestic consumables procurement. The central drugs standard control organization's emphasis on material traceability rewards suppliers with documented resin genealogy. Maharashtra and Gujarat host emerging polymer conversion operations serving contract manufacturing organizations scaling biologics capacity for export markets.
Laboratory Consumables Primary Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where integrated resin-to-sterile-finish capabilities separate premium positioning from commodity supply. Three strategic archetypes dominate: vertically integrated life science conglomerates controlling polymerization through final sterilization; specialized membrane and bag fabricators with deep process engineering expertise; and regional conversion houses serving price-sensitive research markets. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturers securing captive gamma irradiation capacity or licensing automated visual inspection systems to compress release timelines.
Among vertically integrated life science conglomerates, Thermo Fisher Scientific Inc. exemplifies the resin-to-finish archetype, while Sartorius AG occupies a position representing European membrane-integrated system specialization. Corning Incorporated anchors the materials science depth tier, competing on pharmaceutical-grade borosilicate expertise rather than commodity scale. These three entities collectively illustrate how competitive positioning stratifies between integrated supply chain control, process engineering specialization, and material science differentiation.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Sartorius AG |
| Thermo Fisher Scientific Inc. |
| Greiner Bio-One International GmbH |
| Eppendorf AG |
| Merck KGaA |
| Corning Incorporated |
| Schott AG |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Medical-grade polypropylene resin indices cascade through polymerization, conversion, and sterilization stages into three distinct pricing tiers that separate extractables-documented biopharma supply from commodity research-grade procurement. EMA's Annex 1 validation requirements compress supplier qualification timelines while expanding procurement volumes for gamma-stable, genealogy-traceable materials that command substantial premiums over standard laboratory grades.
Pricing Analysis
The bundled-versus-unbundled service split separates suppliers offering integrated resin-to-sterile-finish capabilities from component-only vendors. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth: USP Type I hydrolytic resistance and full polymerization-lot traceability define the premium tier for biologics manufacturers, while research labs drive price sensitivity at the economy tier through direct procurement from regional conversion houses. Pricing pressure stems from gamma irradiation capacity bottlenecks as cobalt-60 facility commissioning lags biologics manufacturing expansion. Pharmaceutical companies exhibit lowest price sensitivity given regulatory non-negotiability, whereas educational institutions prioritize cost minimization where technical support requirements are minimal.
Supply Chain Analysis
Dual-sourcing requirements mandated by biopharmaceutical quality systems force manufacturers to qualify redundant suppliers for critical consumables categories. Geographic supply concentrates in Germany, the United States, and Switzerland, where specialized polymer scientists and aseptic processing engineers anchor membrane-integrated bag and tube production. Raw material dependencies center on pharmaceutical-grade polypropylene resins from US Gulf Coast polymerization facilities, cyclic olefin polymers from Northwestern Europe, and platinum-cured silicone elastomers. Single-source vulnerability in medical-grade resin feedstocks exposes converters to allocation risk during capacity constraints. Distribution runs through direct procurement channels for pharmaceutical manufacturers consolidating vendor bases, while research labs increasingly bypass broad-line distributors to source from specialized manufacturers in German supplier clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory consumables primary packaging functions as a regulatory compounder where EMA's Annex 1 sterile manufacturing mandates continuously upgrade procurement specifications and expand addressable demand for validated single-use technologies.
For Market Incumbents: Hedge against polymer substitution limitations in parenteral formulations by deepening USP Type I borosilicate expertise while securing captive gamma irradiation capacity to compress release timelines. Defend margin position through backward integration into pharmaceutical-grade resin supply and membrane-integrated system specialization that commodity converters cannot replicate. Threats from automated visual inspection technology adoption favor suppliers with AI-enabled defect detection capabilities already deployed across finishing operations. For New Entrants and Emerging Players: Contract research organizations represent the most penetrable channel partner type for specialized consumables manufacturers offering configurable minimum order quantities and rapid turnaround. Target academic core facilities in German and Swiss supplier clusters where same-day fulfillment gaps persist among incumbent distributors. White-space opportunities sit in flexible polyethylene pouch systems displacing rigid containers in modular research lab reconfigurations, and in closed-system transfer device integration where primary packaging converges with drug delivery mechanisms. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane-integrated system specialists possessing validated single-use technology platforms and documented extractables profiles that biopharmaceutical contract manufacturers cannot qualify in compressed timelines. Long-term viability over the projection horizon favors suppliers with integrated resin-to-sterile-finish capabilities that pharmaceutical companies are consolidating toward. The signal to watch is FDA guidance on artificial intelligence in manufacturing quality systems, which would reshape validation protocols and competitive positioning for automated visual inspection technology providers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gamma Irradiation Capacity | Compresses sterilization bottlenecks that currently constrain release timelines for biologics manufacturers. |
| AI-Enabled Visual Inspection Deployment | Aligns with impending FDA guidance on artificial intelligence in manufacturing quality systems validation. |
| Resin-to-Sterile-Finish Integration | Meets EMA Annex 1 polymerization-lot traceability requirements that fragment commodity suppliers. |
| Closed-System Transfer Device Convergence | Captures value-add positioning where primary packaging integrates with drug delivery mechanisms. |
| Direct Procurement Channel Development | Bypasses distributor margin capture in research lab segments seeking configurable minimum order quantities. |
Research Methodology
Multiple input streams — primary interviews with biopharmaceutical quality assurance directors, contract manufacturing procurement leads, and polymer conversion plant managers; secondary validation through FDA container closure guidance documents, EMA Annex 1 revision texts, and ISO 15378 certification databases; plus customs records of medical-grade resin trade flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement specification evolution across German, Swiss, and US bioproduction facilities. Secondary sources included USP monograph updates, BPOG extractables study protocols, and SEC filings of vertically integrated life science conglomerates.
Historical volume trajectories were cross-referenced against expert panel assessments of EMA Annex 1 implementation timelines and cell therapy manufacturing capacity buildouts. The analytical framework modeled segmentation dimensions across product type, material grade, form factor, and end-user procurement authority concentration throughout the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory mandate compliance deadlines and gamma irradiation capacity expansion schedules. Industry-specific forecast inputs included biologics license application filing rates and single-use technology validation study completion patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance timing on artificial intelligence in manufacturing quality systems, cobalt-60 facility commissioning delays, and harmonization progress between USP, ISO, and BPOG extractables protocols. Deviation in EMA enforcement consistency across member state competent authorities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Polymer Vials Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market