
 Liquid Packaging Bag Market | 2026-2036
Liquid Packaging Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Packaging Bag Market Foresight
Food-grade barrier specifications is rotating toward higher oxygen and moisture resistance in liquid packaging bags. Amcor leverages its multi-layer coextrusion capabilities to supply aseptic pouch formats for extended-shelf-life dairy. Tetra Pak International dominates carton-to-pouch conversion lines in emerging dairy markets. Mondi Group anchors European demand through renewable paper-based barrier solutions.
Liquid packaging bags are flexible primary containers engineered from laminated films or fiber-composite substrates, typically incorporating ethylene vinyl alcohol or aluminum oxide barrier layers to prevent oxygen ingress and preserve organoleptic stability for fluid contents. Stand-up pouches and spouted pouches lead volume due to their shelf presence and dispensing convenience, while flat bags retain cost advantage in bulk institutional channels. Polyethylene and polypropylene formulations command material share because of seal integrity and thermal processing compatibility, though paper-laminate hybrids are gaining traction where fiber-based claims support retail differentiation.
FDA migration thresholds under 21 CFR 177 shape polymer selection for U.S. food-contact liquid bags, while EU REACH and the Packaging and Packaging Waste Regulation mandate recyclability targets that constrain multi-material laminate designs. India's BIS certification requirements for food-grade plastics create compliance checkpoints for imported pouch films. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in mono-material recyclable structures or advanced sorting-compatible barrier technologies.
Market Dynamics
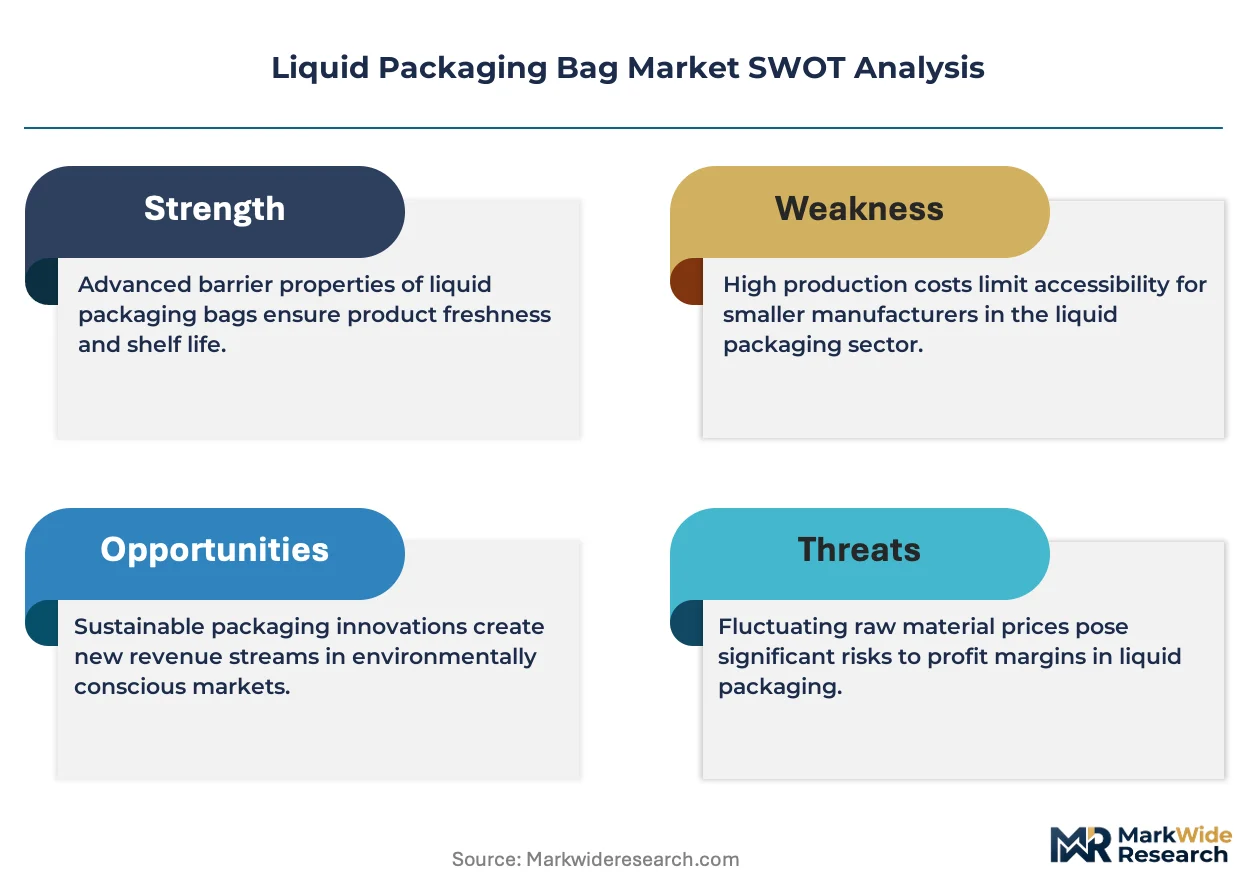
EU REACH migration limits on plastic food contact materials are forcing converters to abandon legacy laminate structures and invest in coextruded barrier films with demonstrably lower substance migration profiles.
Growth Catalysts
- ASEP-7 Dairy Processing Standards:Vietnam's national food safety authority mandates spouted pouch formats for ambient liquid dairy, accelerating converter investment in high-speed filling lines.
- Ethylene Vinyl Alcohol (EVOH) Coextrusion:Five-to-seven-layer blown film lines achieve oxygen transmission rates below 0.5 cc/m²/day, unlocking twelve-month shelf life for UHT milk without aluminum foil.
- Jakarta-Bandung Manufacturing Corridor:Indonesian packaging clusters concentrate blow molding and converting capacity within 80 kilometers, cutting logistics costs for brand owners.
Market Restraints
- Propylene Feedstock Volatility:Polypropylene resin contracts track naphtha spreads, exposing converters to margin compression when olefin crackers run at reduced rates.
- Masterbatch Supply Concentration:Three German compounders control 60% of European food-contact white masterbatch supply, creating single-source risk for dairy pouch printers.
- Aluminum Oxide Barrier Brittleness:Metallized films crack during high-speed form-fill-seal operations, limiting line speeds to 80 pouches per minute versus 140 for coextruded alternatives.
Strategic Opportunities
- India BIS IS 15495 Certification Gap:Domestic laboratories lack capacity for full migration testing, creating first-mover advantage for converters with in-house analytical capabilities.
- Cellulose Nanofiber-PET Hybrids:Japanese pulp mills and film extruders collaborate on renewable barrier substrates that satisfy METI's 2030 plastic reduction targets.
- Direct-to-Processor Digital Platforms:Vietnamese e-procurement marketplaces connect dairy cooperatives with certified converters, bypassing traditional distributor markups.
Industry Challenges
- Coextrusion Die Design Expertise:Vietnam and Indonesia lack sufficient polymer rheology engineers to optimize layer distribution for oxygen-sensitive applications.
- Extended Producer Responsibility Registration:EU Packaging and Packaging Waste Regulation requires individual producer registration in each member state, fragmenting compliance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Packaging Bag Market |
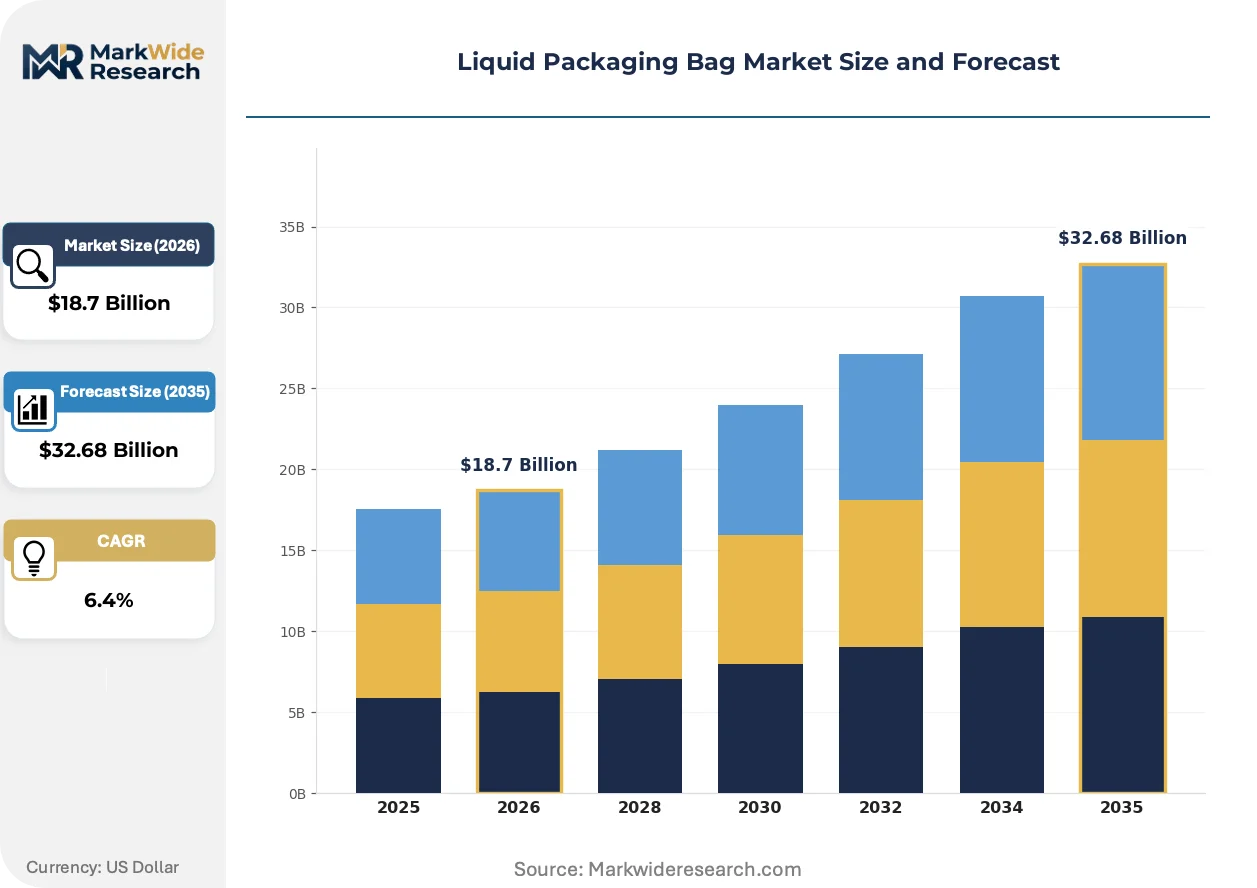
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Stand-Up Pouches, Box Pouches, Spouted Pouches Material: Polyethylene, Polypropylene, Nylon, Paper End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Closure Type: Zip Lock, Screw Cap, Heat Seal, Spout |
| Companies Covered | Amcor, Mondi Group, Tetra Pak International, Sealed Air Corporation, Berry Global Inc., Smurfit Kappa, BillerudKorsnas AB, SIG Group AG, Uflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Packaging Bag Market Shifts & Advancements
Barrier film architecture is pivoting from metallized and aluminum-foil laminates toward transparent oxide-coated and bio-based coextruded structures. This transition reflects both regulatory pressure on multi-material recyclability and brand owner demands for shelf visibility.
High-barrier transparent oxide coatings applied via plasma-enhanced chemical vapor deposition are displacing aluminum foil in premium juice and wine pouch applications. European organic beverage processors specify these structures to satisfy EFSA clean-label positioning while maintaining six-month shelf stability. The shift is compressing demand for conventional metallizing equipment and redirecting capital toward vacuum coating lines.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) in food contact materials are eliminating fluoropolymer-based grease barriers from paper-laminate pouch specifications. Converters in Germany and France accelerate testing of bio-wax and polysaccharide alternatives. Dairy and ready-meal segments face reformulation timelines of eighteen to twenty-four months to validate substitute barrier performance.
Brand owners in Southeast Asia compress supplier qualification cycles from twenty-four months to nine months as dairy market entry intensifies. Indonesian and Vietnamese processors now demand simultaneous technical audit and pilot production rather than sequential validation. This compression favors converters with established laboratory infrastructure and documented HACCP systems over greenfield entrants.
Liquid Packaging Bag Market Segmentation
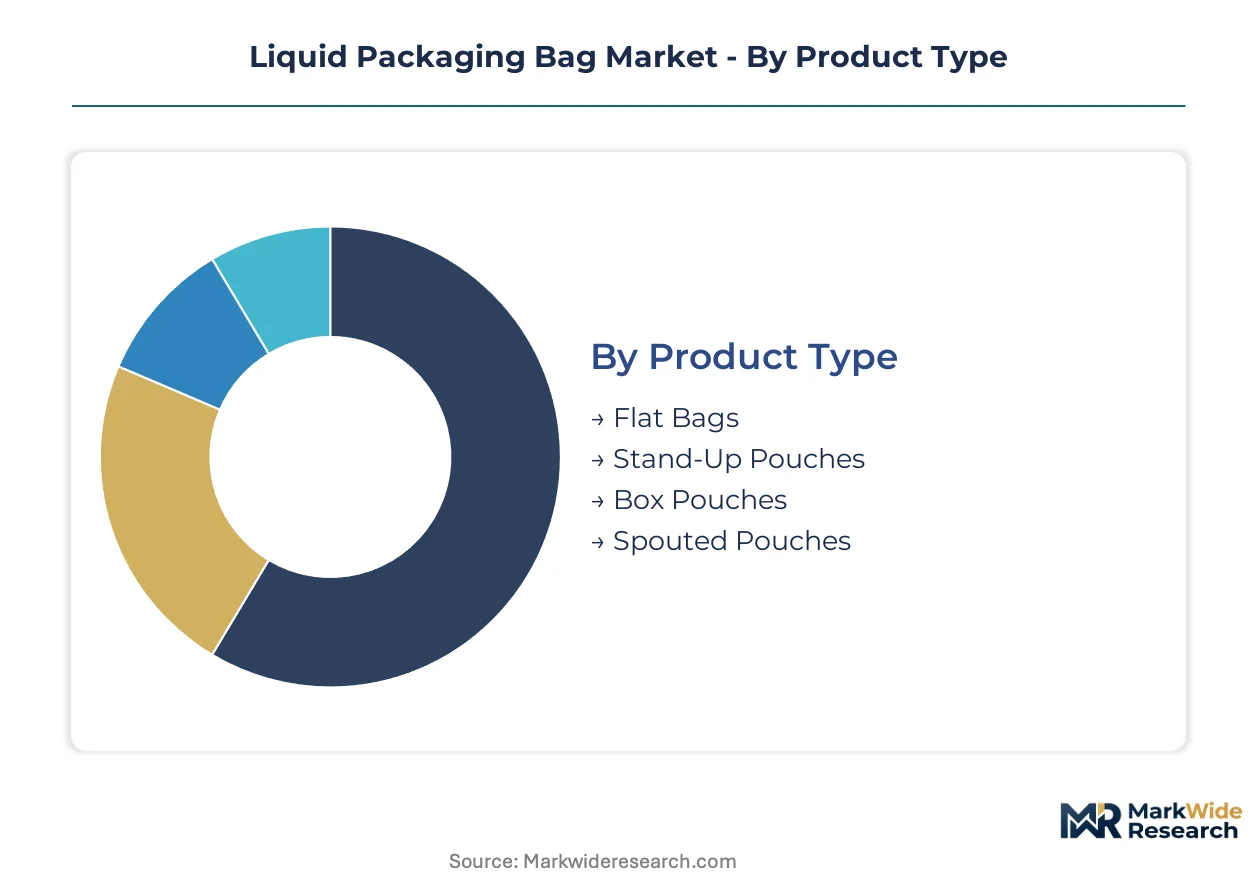
Liquid packaging bag segmentation reveals divergent technical requirements across dairy, pharmaceutical, and chemical applications. Material selection and closure mechanisms determine barrier performance, filling line compatibility, and end-user handling economics.
Product Type:
Flat bags dominate domestic bulk institutional channels in Vietnam and Indonesia, while stand-up and spouted formats drive export-led premium dairy positioning in European and Japanese markets.
- Flat Bags:Two- or three-side-sealed polyethylene or polypropylene structures optimized for high-volume UHT milk and cooking oil distribution. Demand concentrates in Indonesian institutional food service and Vietnamese dairy cooperatives where cost-per-unit trumps shelf presence, though oxygen transmission rates above 5 cc/m²/day limit shelf life to 90 days.
- Stand-Up Pouches:Gusseted bottom structures with multi-layer EVOH or aluminum oxide barriers enabling 180-day ambient stability for ready-to-drink beverages. Japanese and South Korean brand owners specify these formats for retail juice and functional drinks, driving converter investment in bottom-seal integrity testing.
- Box Pouches:Rectangular flat-bottom formats with side gussets maximizing pallet density for bulk liquid chemicals and agricultural inputs.
- Spouted Pouches:Integrated fitment structures for controlled dispensing of condiments, personal care liquids, and pharmaceutical syrups; ASEP-7 compliance mandates in Vietnam accelerate dairy adoption.
Flat bags command the established base. The steepest expansion runs through spouted pouches.
Material:
Polyolefin cost structures vary with naphtha cracker operating rates, while paper-laminate hybrids attract sustainability-driven brand owners in EU markets facing REACH recyclability mandates.
- Polyethylene:Linear low-density and metallocene grades deliver seal strength and puncture resistance for frozen and refrigerated liquid applications. Indonesian converters favor PE for coconut milk and palm oil pouches due to local resin availability and FDA 21 CFR 177 compliance documentation from Singapore traders.
- Polypropylene:Cast and oriented films provide clarity and stiffness for retortable ready-meal sauces and pharmaceutical liquids. Demand clusters in Vietnam's ASEP-7 certified dairy processors and Japanese METI-aligned converters developing cellulose nanofiber-PP hybrids.
- Nylon:Polyamide layers in coextruded structures resist puncture and provide oxygen barrier in vacuum-packed liquid foods and chemical concentrates.
- Paper:Fiber-based substrates with bio-wax or polysaccharide barrier coatings replacing fluoropolymer-treated structures under EU PFAS restrictions; German and French organic beverage processors pilot these for six-month shelf life claims.
Polyethylene anchors volume throughput. Paper-laminate structures are climbing the fastest on regulatory tailwinds.
End User:
Food and beverage processors specify barrier grades with migration testing documentation, while pharmaceutical and chemical buyers prioritize lot traceability and child-resistant closure compatibility.
- Food & Beverage:Dairy, juice, wine, edible oil, and ready-to-drink formats requiring oxygen transmission below 1 cc/m²/day and compliance with FDA, EU REACH, and India BIS IS 15495 standards. Vietnamese and Indonesian dairy cooperatives drive spouted pouch volume through direct-to-processor digital procurement platforms.
- Pharmaceuticals:Oral liquids, intravenous solutions, and diagnostic reagents demanding USP Class VI or equivalent extractables testing. Japanese PMDA and EU EMA registration requirements favor converters with ISO 15378 certified cleanrooms.
- Cosmetics:Serums, lotions, and hair care products requiring aesthetic print quality and airless dispensing compatibility; South Korean and French brand owners lead specification intensity.
- Chemicals:Agricultural inputs, industrial lubricants, and cleaning concentrates where chemical resistance and UN-certified transport integrity override barrier sophistication; Indonesian plantation sector drives bulk flat bag demand.
Food and beverage holds the volume base. Pharmaceuticals are gaining share fastest on regulatory compliance premiums.
Closure Type:
Closure selection determines resealability, tamper evidence, and filling line speed compatibility, with heat seal and spout formats diverging on capital equipment requirements.
- Zip Lock:Press-to-close interlocking profiles for multi-serve food and chemical applications requiring repeated access; limits oxygen barrier performance versus permanent seals.
- Screw Cap:Injection-molded threaded fitments enabling precise dosing and child-resistant options for pharmaceuticals and cleaning chemicals; German masterbatch supply concentration creates qualification bottlenecks.
- Heat Seal:Permanent fusion seals delivering maximum barrier integrity at lowest unit cost; dominates bulk dairy and edible oil in Southeast Asian manufacturing clusters.
- Spout:Integrated pour-and-reseal structures with welded or snapped fitment attachment; aluminum oxide barrier brittleness during high-speed form-fill-seal limits line speeds versus coextruded alternatives.
Heat seal closures dominate unit economics. Spout integration is expanding most quickly on convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in liquid packaging bags tilt toward surplus in Asian manufacturing clusters while European and North American markets absorb specialty barrier films through cross-border trade. Vietnam and Indonesia run structural export positions in polyethylene-based dairy pouches. Germany and the United States import advanced coextruded structures for extended-shelf-life applications.
Vietnam
Dairy cooperatives drive spouted pouch procurement through direct-to-processor digital platforms, bypassing traditional distributor networks. ASEP-7 standards from the national food safety authority mandate fitment-equipped formats for ambient liquid dairy, accelerating converter certification timelines. The Ho Chi Minh City-Dong Nai manufacturing corridor concentrates blow molding and high-speed filling line investment within 50 kilometers of port infrastructure.
Germany
Organic beverage processors specify transparent oxide-coated pouches to satisfy EFSA clean-label positioning while maintaining six-month shelf stability. EU REACH Annex XVII restrictions on PFAS in food contact materials eliminate fluoropolymer-based grease barriers, forcing eighteen-to-twenty-four-month reformulation cycles. The Rhine-Ruhr packaging cluster anchors demand for bio-wax and polysaccharide barrier alternatives in paper-laminate structures.
United States
FDA migration thresholds under 21 CFR 177 shape polymer selection for food-contact liquid bags, favoring converters with documented extractables testing. Brand owners in the Northeast Corridor compress supplier qualification cycles from twenty-four months to nine months as dairy market entry intensifies. The Chicago-Milwaukee industrial corridor concentrates converter capacity for frozen and refrigerated liquid applications.
Indonesia
The Jakarta-Bandung manufacturing corridor concentrates blow molding and converting capacity within 80 kilometers, cutting logistics costs for plantation sector brand owners. BIS-equivalent import certification requirements for food-grade plastics create compliance checkpoints for films sourced from regional traders. Domestic resin availability from Singapore traders supports polyethylene dominance in coconut milk and palm oil pouch formats.
Japan
METI's 2030 plastic reduction targets drive collaboration between pulp mills and film extruders on cellulose nanofiber-PET hybrid substrates. PMDA registration requirements for pharmaceutical liquids favor converters with ISO 15378 certified cleanrooms. The Kansai-Osaka industrial zone anchors development of renewable barrier technologies for premium juice and wine pouch applications.
Liquid Packaging Bag Market Competitive Landscape
Concentration sits with diversified packaging conglomerates and regional film specialists competing on barrier technology and regulatory certification speed. The vendor base splits between integrated multinationals with captive resin access and independent converters serving single-country dairy cooperatives. Two strategic archetypes dominate: scale-driven barrier film suppliers with multi-layer coextrusion capabilities, and niche specialists in spouted pouch fitment integration. Competitive moves center on backward integration into masterbatch compounding and geographic expansion through distributor acquisition in Southeast Asian manufacturing clusters.
Within the diversified multinational tier, Amcor plc and Tetra Pak International exemplify scale-driven positions, while Mondi Group occupies a specialist niche in renewable paper-based barrier solutions. These three entities anchor the competitive spectrum from petroleum-derived coextrusion to fiber-composite substrates, representing the technology bifurcation reshaping material selection decisions. Their collective positioning reflects the tension between shelf-life extension requirements and recyclability mandates under EU Packaging and Packaging Waste Regulation frameworks.
| Leading Market Players |
|---|
| Amcor |
| Mondi Group |
| Tetra Pak International |
| Sealed Air Corporation |
| Berry Global Inc. |
| Smurfit Kappa |
| BillerudKorsnas AB |
| SIG Group AG |
| Uflex |
| Others |
Supply & Pricing Matrix
Seventy-five-day resin inventory cycles in Southeast Asian converting clusters concentrate pricing power among polyolefin traders with Singapore storage capacity. This lead-time compression amplifies margin volatility for Vietnamese and Indonesian dairy pouch processors when naphtha spreads widen.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in liquid packaging bags. Price differentiation hinges on ASEP-7 certification status and EVOH barrier layer thickness. Pricing pressure stems from propylene feedstock volatility squeezing converter margins. Dairy cooperatives in Vietnam exhibit highest price sensitivity, while Japanese pharmaceutical brand owners absorb premium tiers for PMDA-compliant structures.
Supply Chain Analysis
Container availability on the Singapore-Jakarta trade lane shapes inbound logistics costs for European masterbatch inputs. Supply concentrates in Vietnam, Indonesia, and Germany for converting capacity, with polyethylene resin sourcing from Singapore and Thai petrochemical complexes. Raw material dependencies center on LLDPE resin, EVOH barrier film, and food-grade white masterbatch. Single-source vulnerability runs through German masterbatch compounders controlling European supply. Distribution runs through direct-to-processor digital platforms in Vietnam and traditional distributor networks in EU markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical audit and pilot production bundling represents a service-attach opportunity expanding faster than base film supply, as Southeast Asian dairy processors compress supplier qualification cycles.
For Market Incumbents: Shield ASEP-7 certified capacity in Vietnam through backward integration into masterbatch compounding. Consolidate distributor networks in Indonesia before direct-to-processor platforms erode channel control. Regulatory fragmentation across EU member states on extended producer responsibility registration threatens margin structures. For New Entrants and Emerging Players: India BIS IS 15495 certification fast-track offers entry wedge for converters with in-house migration testing laboratories. Target Vietnamese dairy cooperatives bypassing traditional distributor markups through e-procurement marketplaces. Lead with spouted pouch fitment integration capability against flat bag incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because barrier film architecture transitions create acquisition targets with stranded metallizing equipment. ISO 15378 certified cleanroom capacity in pharmaceutical liquids commands scarcity premiums. Watch EU REACH Annex XVII PFAS restriction timelines as inflection signal for bio-wax barrier substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Masterbatch Compounding | Reduces single-source dependency on German compounders for food-contact white masterbatch supply. |
| ASEP-7 Certification Investment | Unlocks Vietnamese dairy cooperative procurement through national food safety authority mandates. |
| Direct-to-Processor Digital Platform Launch | Bypasses distributor markups in Vietnamese manufacturing corridors concentrated near Ho Chi Minh City. |
| Cellulose Nanofiber-PET Hybrid Development | Satisfies Japan METI plastic reduction targets for renewable barrier substrates in premium applications. |
| EU Extended Producer Responsibility Registration | Complies with Packaging and Packaging Waste Regulation fragmentation across member state workflows. |
Research Methodology
Desk research of customs trade databases, FDA 21 CFR 177 migration threshold documentation, and EU REACH Annex XVII restriction filings preceded structured interviews with Vietnamese dairy cooperative procurement managers, Indonesian plantation sector packaging engineers, German organic beverage brand technical directors, and Japanese pharmaceutical converter quality leads. Bottom-up demand modeling from end-use consumption patterns triangulated against top-down capacity assessments from regional film extrusion line counts.
Variance decomposition across product type, material substrate, closure mechanism, and end-use industry dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories incorporating ASEP-7 adoption curves in Vietnam and PFAS substitution timelines in EU markets. Forecast inputs included naphtha spread volatility indices and BIS laboratory certification capacity expansion in India.
The analysis sits within stated boundaries; outcomes outside sustained EU REACH enforcement intensity or abrupt polyolefin feedstock disruption would require recalibration. Forecasts reflect assumptions on regulatory compliance timelines and barrier technology substitution rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bulk Tote Dumpers Market
Bags and Containers
Block Sack Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Inner Bulk Liners Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Trash Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Piping Bags Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Carry Bag Market
Bags and Containers
Loop Handle Bags Market